
 Metals in Electric Vehicle Charging Infrastructure Market | 2026-2036
Metals in Electric Vehicle Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Metals in Electric Vehicle Charging Infrastructure Market Intelligence
The market for high-purity copper and aluminum, critical for ultra-fast charging systems, is decoupling from the pricing of standard-grade structural steel used in station enclosures. Norsk Hydro ASA specializes in low-carbon aluminum, targeting premium segments focused on sustainability. In contrast, Glencore leverages its vast scale in copper and zinc to supply a broader range of applications across different performance tiers. Rio Tinto competes by offering certified responsible production for its aluminum, appealing to ESG-conscious buyers in public infrastructure projects.
Metals in electric vehicle charging infrastructure comprise high-conductivity and structural materials essential for power delivery and hardware integrity. This includes copper with a minimum IACS rating of 98% for efficient power transfer in cables and connectors. Within applications, copper dominates high-performance cables for ultra-fast charging systems. Aluminum, however, is a leading material for the structural housings of charging stations and power supply units due to its favorable strength-to-weight ratio and corrosion resistance.
Regulatory frameworks like the EU's RoHS directive restrict hazardous substances, influencing metal alloy choices for connectors and internal components. In the United States, standards from the Society of Automotive Engineers (SAE) define connector and cable specifications for interoperability. China's GB standards govern public charging equipment safety and performance. Suppliers must therefore navigate a complex web of national standards and sustainability reporting mandates to maintain market access.
Market Dynamics
The central dynamic shaping the market is the tension between the massive scale-up of public charging networks, particularly in China, and the simultaneous rise of stringent sustainability mandates like the EU's CSRD, which demand greater transparency in metal sourcing.
Growth Catalysts
- Public Infrastructure Mandates:Government programs in North America and Europe mandating the build-out of national EV charging corridors directly stimulate demand for copper, aluminum, and steel for stations and grid connections.
- Ultra-Fast Charging Technology:The push for charging times under 15 minutes requires systems operating at high power levels, which in turn necessitates the use of high-purity, high-conductivity copper for cables and connectors.
- Fleet Electrification:Corporate and municipal vehicle fleets are transitioning to EVs, creating concentrated demand for dedicated, high-utilization charging depots that consume significant quantities of structural and conductive metals.
Market Restraints
- Input Cost Volatility:The pricing for high-purity copper, essential for high-performance cables, is subject to significant commodity market fluctuations, creating budget uncertainty for large-scale infrastructure projects.
- Refining Concentration:Geographic concentration in the refining of battery-grade and conductivity-grade metals creates supply chain vulnerabilities, exposing the market to geopolitical risks and trade policy shifts.
- Substitution Limitations:While aluminum is used in housings, substituting it for copper in high-power flexible cables remains technically challenging without significant performance trade-offs, limiting cost-reduction options.
Strategic Opportunities
- Low-Carbon Metals:The development and certification of low-carbon aluminum and recycled copper provides a significant opportunity to capture premium pricing from ESG-focused buyers and public projects with sustainability requirements.
- Vehicle-to-Grid Systems:The emergence of V2G and bi-directional charging hardware creates a new application category for specialized alloys and connectors designed for high-cycle-life and grid-interfacing standards.
- Emerging Market Build-Out:Regions like Southeast Asia and Latin America represent nascent markets where establishing local supply chains and partnerships for charging hardware offers long-term growth potential.
Industry Challenges
- Regulatory Fragmentation:Suppliers face significant compliance costs and design complexities in navigating divergent technical standards, such as SAE in the US, GB standards in China, and CE marking requirements in Europe.
- Supply Chain Qualification:Integrating and validating new suppliers of recycled or sustainably-sourced metals is a time-consuming and expensive process, slowing adoption despite strong market demand for such materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metals in Electric Vehicle Charging Infrastructure Market |
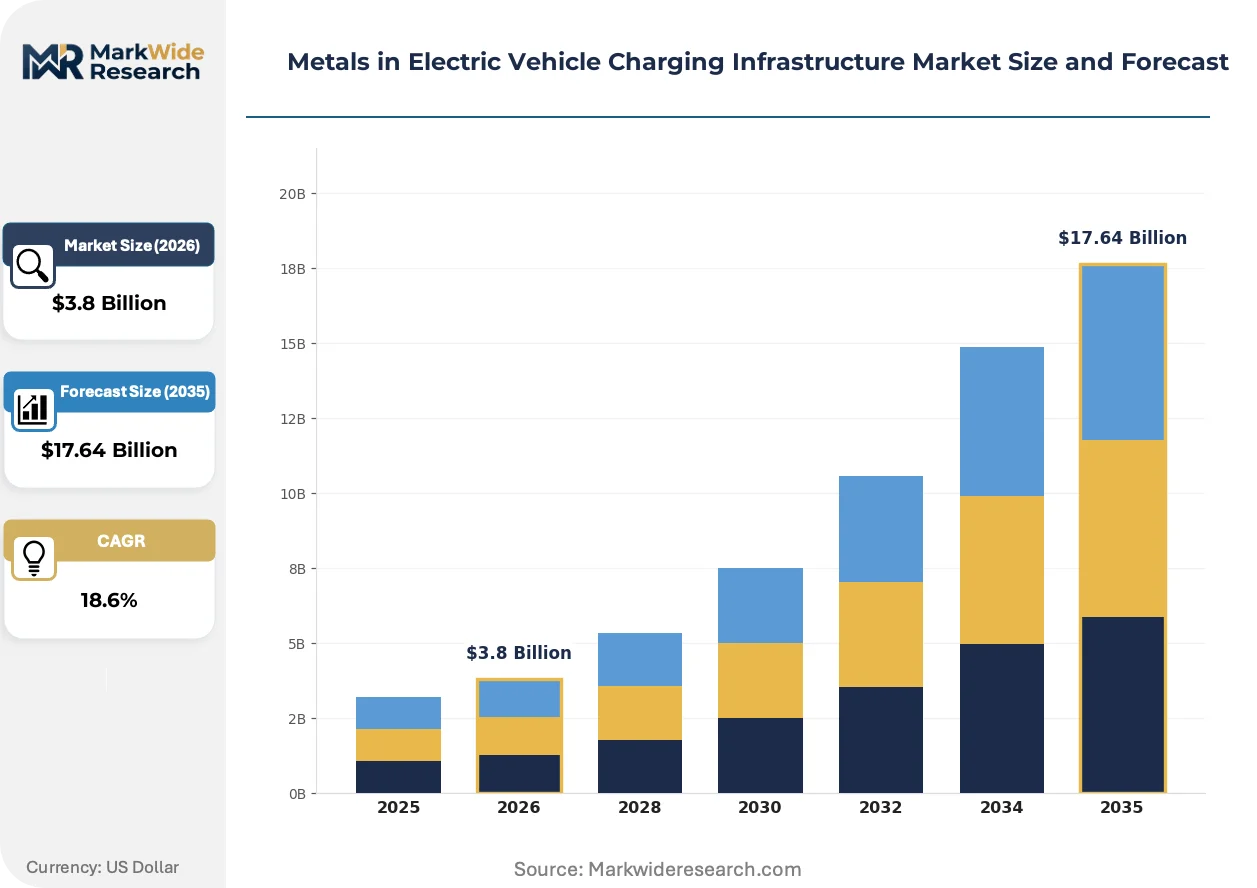
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper, Aluminum, Steel, Zinc Application: Charging Stations, Power Supply Units, Cables, Connectors Technology: Fast Charging, Ultra-Fast Charging, Wireless Charging, Level 2 Charging End User: Public Infrastructure, Commercial Fleets, Residential Users, Transportation Networks |
| Companies Covered | Alcoa Corporation, CODELCO, Emirates Aluminum (EGA), First Quantum Minerals Ltd., Glencore, JSW, KGHM, Norsk Hydro ASA, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metals in Electric Vehicle Charging Infrastructure Market Strategic Shifts & Innovations
Material science advancements are converging with circular economy principles. This is driven by the dual needs for higher electrical performance in ultra-fast charging and verifiable sustainability credentials demanded by new regulatory frameworks.
Liquid-cooled cable technology is a key product evolution. These systems use advanced copper alloys and dielectric fluids to manage extreme heat in high-power DC fast chargers. Developers of charging networks rated at 350kW and above are the primary adopters. This technology is integrating advanced thermal management directly into the power delivery path, enabling higher charging speeds without compromising material safety or longevity.
The EU's Corporate Sustainability Reporting Directive (CSRD) is a significant policy shift. It compels companies to disclose detailed environmental and social impacts across their value chains, including metal sourcing. This directive is forcing a new level of supply chain transparency for both metal producers and charging equipment manufacturers. The aluminum segment is particularly affected, as suppliers with certified low-carbon products gain a distinct competitive advantage in European public tenders.
A discernible shift is occurring in procurement behavior, with material certifications becoming a primary decision criterion. This pattern disrupts traditional commodity purchasing models that focused almost exclusively on cost and availability. It favors suppliers who can provide verifiable documentation for responsible sourcing or recycled content. This trend is most prominent within public infrastructure projects in the European Union and among corporate fleet operators in North America.
Metals in Electric Vehicle Charging Infrastructure Market Segmentation
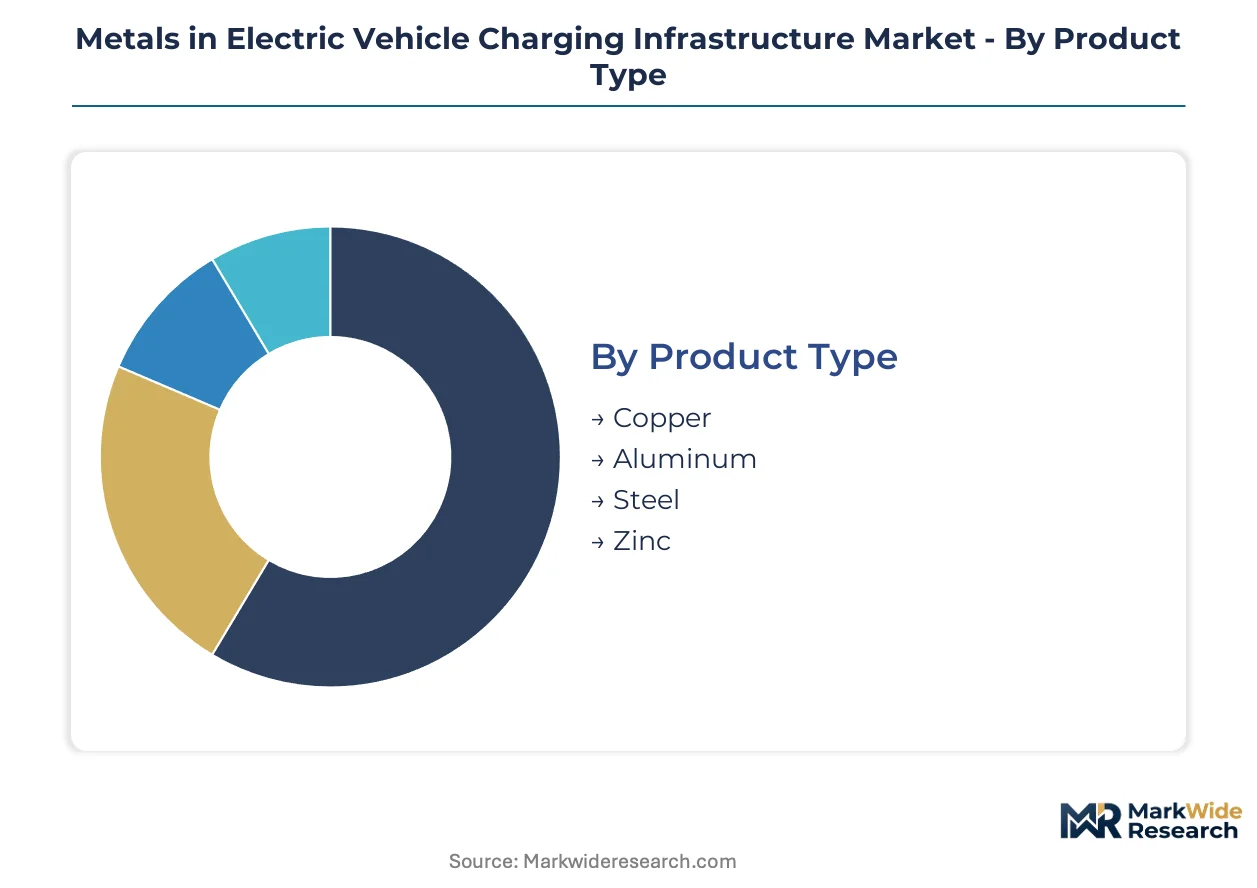
Market segmentation provides a critical framework for understanding the diverse material requirements and demand patterns within the electric vehicle charging infrastructure sector. Analyzing these distinct segments reveals where investment and innovation are concentrating for metal producers and charging equipment manufacturers.
Product Type:
Supply concentration significantly impacts the availability and pricing of specific metal products required for EV charging infrastructure.
- Copper:High-purity copper, with a minimum IACS rating of 98%, forms the core of efficient power transfer in charging cables and connectors. Demand for this high-conductivity material concentrates in ultra-fast DC charging systems, driven by the need to minimize energy loss and heat generation during high-power delivery for rapid EV battery replenishment.
- Aluminum:Low-carbon aluminum serves as a primary structural material for charging station enclosures and power supply unit housings due to its strength-to-weight ratio and corrosion resistance. European public infrastructure projects increasingly demand certified low-carbon aluminum, influencing procurement decisions for ESG-conscious buyers.
- Steel:Structural steel provides the foundational support for public charging stations and protective bollards, offering durability and impact resistance.
- Zinc:Zinc is primarily used in galvanizing steel components for corrosion protection and in some specialized alloy applications for connectors within charging hardware.
Copper absorbs the bulk of installed capacity for conductive elements; aluminum is expanding most quickly in structural components for sustainability-focused projects.
Application:
The specific application within the charging ecosystem dictates the performance characteristics and quantities of metals required for optimal functionality.
- Cables:High-performance cables for ultra-fast charging systems necessitate advanced copper alloys and sophisticated insulation materials to manage extreme power loads and thermal conditions. The drive for faster charging times directly influences the specifications for these critical power delivery components.
- Connectors:Robust and high-conductivity connectors, often combining copper alloys with specialized coatings, ensure reliable power transfer and mechanical durability under frequent use. Regulatory frameworks like SAE standards in the United States define specific requirements for connector interoperability and safety.
- Charging Stations:Charging stations encompass the entire enclosure and internal power electronics, primarily utilizing aluminum for housing and steel for structural integrity.
- Power Supply Units:Power supply units integrate various metals, including aluminum for heat sinks and copper for internal wiring, to efficiently convert and manage electrical energy.
Each application within EV charging infrastructure demands a tailored selection of metals, balancing conductivity, durability, and cost efficiency.
Technology:
Advancements in charging technology continuously redefine the material specifications and performance requirements for conductive and structural metals.
- Ultra-Fast Charging:Systems rated at 350kW and above require liquid-cooled copper cables and advanced thermal management solutions to dissipate intense heat generated during high-power transfer. The technical demands of ultra-fast charging drive innovation in high-purity metal alloys.
- Wireless Charging:Emerging wireless charging technologies utilize specialized copper coils and magnetic shielding materials, requiring precise engineering for efficient energy transfer across an air gap. Development in this segment focuses on material properties that minimize energy loss and maximize charging efficiency.
- Fast Charging:Standard fast charging (e.g., 50-150kW DC) relies on high-conductivity copper cables and robust connectors, balancing performance with infrastructure cost.
- Level 2 Charging:Level 2 AC charging, common for residential and workplace installations, uses more conventional copper wiring and standard connectors, focusing on durability and cost-effectiveness.
The evolution of charging technologies directly influences the demand for specialized metal alloys and advanced material configurations.
End User:
Distinct end-user segments exhibit varying scales of deployment and specific procurement priorities, influencing the demand characteristics for metals.
- Public Infrastructure:Government programs in Europe and North America mandate large-scale public charging corridor build-outs, driving demand for significant volumes of structural steel and high-purity copper. Sustainability mandates like the EU's CSRD influence material sourcing for these projects.
- Commercial Fleets:Corporate and municipal fleet electrification initiatives create concentrated demand for dedicated, high-utilization charging depots that require robust structural and conductive metals. These installations often prioritize durability and long-term operational efficiency.
- Residential Users:Individual residential installations primarily consume smaller quantities of copper wiring and aluminum for home charging units, prioritizing ease of installation and cost.
- Transportation Networks:Dedicated charging solutions for buses, trucks, and other heavy-duty vehicles within transportation networks demand heavy-duty, high-capacity metal components for power delivery and station construction.
Each end-user segment drives distinct metal procurement strategies, balancing volume requirements with performance specifications and sustainability goals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta region, a major manufacturing and innovation hub, drives significant demand for metals in EV charging infrastructure. This region anchors global volume for charging point deployment, influencing material specifications. Rapid expansion of charging networks across various geographies necessitates tailored material sourcing strategies.
China
Demand for metals in EV charging infrastructure is robust in China, driven by the world's largest EV market and extensive public charging point expansion. China's GB standards govern safety and performance, directly impacting metal alloy choices for equipment. The Yangtze River Delta and Pearl River Delta regions demonstrate high concentrations of charging station manufacturing and deployment.
United States
The United States sees substantial demand for copper and aluminum, fueled by federal mandates for national EV charging corridors. The Inflation Reduction Act (IRA) incentives support domestic manufacturing and infrastructure projects. California's aggressive EV adoption targets and charging network build-out make it a focal point for material procurement.
Germany
Germany's automotive sector and the EU's CSRD significantly influence metal sourcing for charging infrastructure. The EU Green Deal targets promote sustainable material choices, favoring low-carbon aluminum and recycled copper. Bavaria and North Rhine-Westphalia are key regions for EV manufacturing and charging station deployment.
India
India represents a nascent yet rapidly expanding market for EV charging infrastructure metals, driven by fleet electrification and government initiatives. The PLI scheme for automotive components encourages local production of charging hardware. Gujarat's industrial corridors are becoming centers for EV component manufacturing and charging network development.
United Kingdom
The United Kingdom's government programs actively support the expansion of its EV charging network, increasing demand for structural and conductive metals. CE marking requirements ensure product compliance for all charging equipment sold in the market. London and the Southeast region lead in urban charging infrastructure deployment and technology adoption.
Metals in Electric Vehicle Charging Infrastructure Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the metals for EV charging infrastructure market. This market structure features a tiered supply chain, from raw material extraction to specialized component manufacturing. Strategic archetypes include large-scale commodity metal suppliers, niche providers of high-purity or recycled metals, and integrated material-to-component manufacturers. Dominant competitive moves involve capacity expansion for high-purity materials and strategic partnerships for verifiable sustainable sourcing.
Specialized material suppliers such as Norsk Hydro ASA exemplify the focus on low-carbon aluminum, targeting premium segments with sustainability mandates. Rio Tinto occupies a position anchored by certified responsible production for its aluminum, appealing to ESG-conscious buyers in public infrastructure projects. Glencore represents a large-scale producer leveraging its vast copper and zinc assets to supply a broader range of applications across various performance tiers in the market.
| Leading Market Players |
|---|
| Alcoa Corporation |
| CODELCO |
| Emirates Aluminum (EGA) |
| First Quantum Minerals Ltd. |
| Glencore |
| JSW |
| KGHM |
| Norsk Hydro ASA |
| Rio Tinto |
| Others |
Cost & Logistics Intelligence
High-purity copper costs, foundational for efficient power transfer, directly influence the pricing of ultra-fast charging cables and connectors, flowing through to project developers and ultimately EV users. This cost component reflects upstream refining capacity and global commodity market fluctuations.
Pricing Analysis
Value tied to charging speed and reliability anchors pricing for advanced charging infrastructure metals. Price differentiation stems from material certification levels, such as low-carbon aluminum, and performance tiers for ultra-fast charging systems. Pricing pressure stems from commodity market volatility for copper, impacting large-scale infrastructure projects. Residential users exhibit the highest price sensitivity for basic charging units, while public infrastructure projects prioritize long-term performance and sustainability credentials over initial cost.
Supply Chain Analysis
Returns and refurbishment flows for charging station components are nascent, reflecting the infrastructure's early lifecycle, but will grow with circular economy mandates. Geographic supply concentration for critical metals centers on China for refined copper and aluminum, alongside Australia and Chile for primary copper extraction. Raw material dependencies include high-purity copper, low-carbon aluminum, and specialized alloys for connectors. Geopolitical risks associated with refining concentration in specific regions represent a structural supply chain vulnerability. Distribution for charging hardware components primarily runs through direct-to-project developers and charging network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refining capacity for high-purity copper and low-carbon aluminum represents a named capacity bottleneck propping pricing in this market, framing it as a supply-constrained story.
For Market Incumbents: Lock in long-term supply agreements for certified low-carbon aluminum and high-purity copper to mitigate input cost volatility. Invest in R&D for advanced material alloys that enhance thermal management in ultra-fast charging systems, addressing the threat of technical obsolescence. Expand refining capacity in geopolitically stable regions to reduce single-source vulnerability. Prioritize certification investments for sustainable sourcing to meet evolving regulatory demands like the EU's CSRD.
For New Entrants and Emerging Players: Capture niche opportunities in specialized components for Vehicle-to-Grid (V2G) systems, leveraging demand for high-cycle-life connectors. Target emerging markets like Southeast Asia and Latin America, which represent underpenetrated geographies for charging infrastructure build-out. Focus on developing localized supply chains and partnerships to provide cost-effective solutions tailored to regional standards. Offer products with verifiable sustainability credentials as a key go-to-market angle.
For Investors and Strategic Acquirers: Accelerated global EV adoption is the leading indicator that signals long-term viability for metals in charging infrastructure over a 5-10 year window. Acquisition targets should include specialized alloy producers with strong R&D capabilities in thermal management, and certified low-carbon metal suppliers. Watch for significant shifts in national EV charging mandates or breakthroughs in battery technology as inflection signals for future investment strategies. Material deviation in named triggers warrants pause and re-evaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Low-Carbon Aluminum | Increases availability of sustainably sourced structural materials for public infrastructure projects. |
| Long-term Copper Offtake Agreements | Secures stable supply and mitigates price volatility for high-conductivity cables. |
| Investment in Advanced Thermal Management R&D | Enables higher power density and faster charging speeds without material degradation. |
| Certification for Recycled Metal Content | Attracts ESG-conscious buyers and complies with evolving sustainability mandates. |
| Strategic Partnerships in Emerging Markets | Establishes early market presence and localized supply chains for future growth. |
Research Approach
Multi-period observation of EV charging network deployments and metal commodity prices anchored the trend analysis, supplemented by interviews with EV charging network operators, metal producers, charging equipment manufacturers, and regulatory bodies. Secondary data sources included government EV deployment reports, trade association publications, company sustainability reports, and national standards documents. This approach enabled both bottom-up and top-down triangulation of market data.
An input-output matrix framework guided the quantitative assessment across the analysis window. The model segmented demand by product type, application, technology, end-user, and regional deployment stage. Compound Annual Growth Rates (CAGRs) were derived from historical trends and future projections, incorporating key inputs like global EV sales forecasts and public charging point installation targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and raw material price volatility. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market