
 PV BESS EV Charging Systems Market | 2026-2036
PV BESS EV Charging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
PV BESS EV Charging Systems Market Insights
China is rewriting the competitive map for PV BESS EV charging systems through massive domestic manufacturing scale and export-oriented capacity expansion. Tesla leverages its Supercharger network architecture to anchor premium fast-charging deployments across North American corridors. SUNGROW sustains cost leadership in power conversion systems through captive inverter production and vertical control over key components. Huawei competes aggressively on smart grid software, integrating AI-driven load balancing into its string inverter and storage management platforms.
PV BESS EV charging systems combine photovoltaic generation, battery energy storage, and electric vehicle supply equipment into unified power architectures, typically operating at DC fast-charging rates of 150 kW to 350 kW with round-trip storage efficiency above 85%. These systems buffer intermittent solar output to deliver reliable vehicle charging while reducing grid dependency and peak demand charges. Fast chargers within the product type dimension command the highest capital intensity but also the steepest utilization curves in commercial corridors. Grid-connected integration level configurations dominate current deployments, though off-grid and hybrid variants are gaining traction in remote fleet operations and resilience-critical infrastructure where islanding capability justifies premium hardware costs.
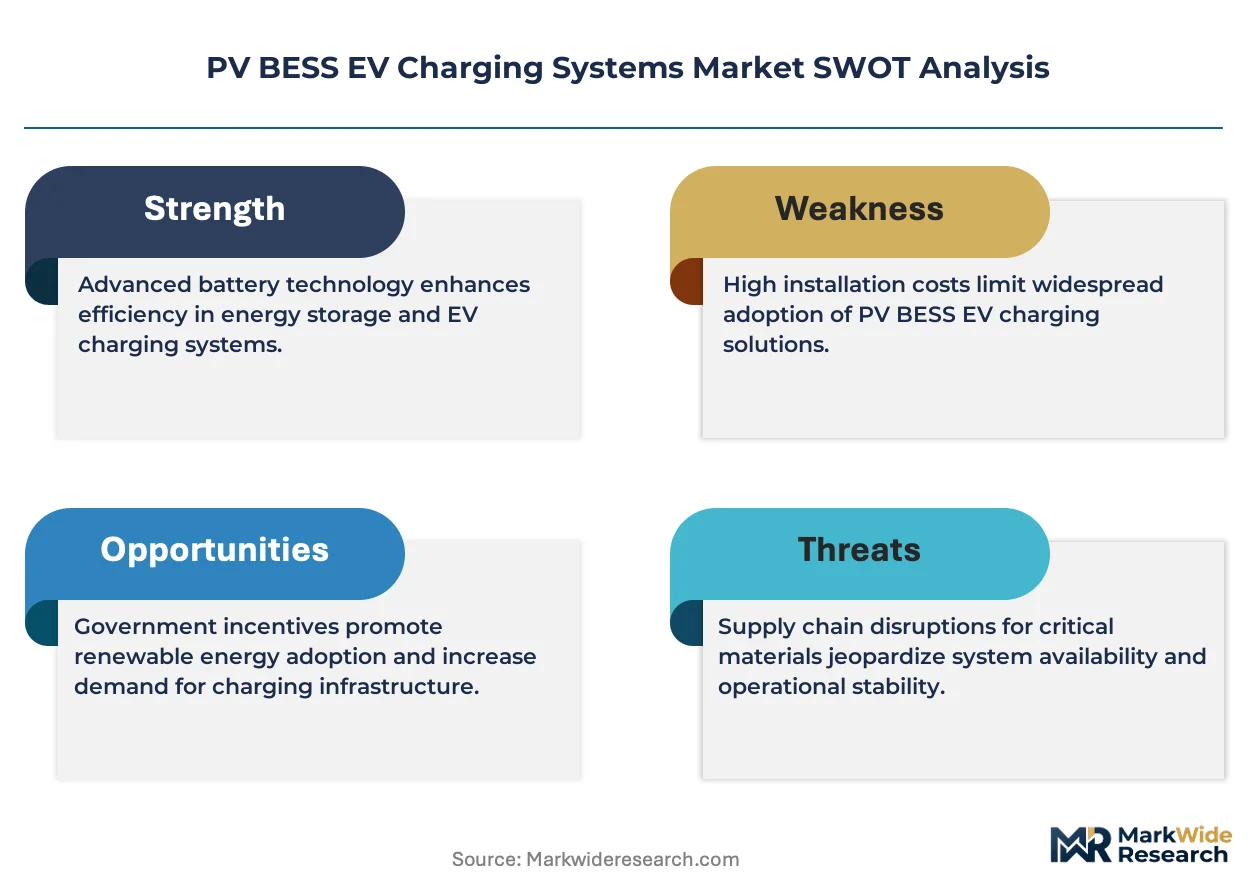
China's MIIT and NMPA shape domestic product certification and grid interconnection standards, while the EU Green Deal and F-Gas Regulation in Europe mandate refrigerant phase-downs and circularity requirements for thermal management components. These frameworks elevate compliance costs for non-compliant imports while creating preferential market access for certified local and regional suppliers. Stakeholders must weigh regulatory divergence against platform standardization as they allocate R&D budgets across multiple certification regimes.
Market Dynamics
Grid congestion at commercial charging hubs is forcing operators toward hybrid solar-storage architectures that can island during peak pricing windows. This structural pressure reconfigures procurement toward integrated power electronics and away from standalone charger hardware.
Growth Catalysts
- California ZEV Mandates:Fleet electrification deadlines in the United States are compressing deployment timelines for solar-integrated depots serving logistics operators.
- Power Purchase Agreements:Corporate offtake contracts for renewable energy are financing behind-the-meter storage at charging facilities without direct capital outlay.
- Silicon Carbide Inverters:Wide-bandgap semiconductors are cutting conversion losses and enabling higher-density DC fast-charging modules.
Market Restraints
- Lithium Price Volatility:Battery pack cost uncertainty is freezing long-term procurement commitments from fleet operators with thin margins.
- Transformer Lead Times:Utility interconnection equipment from North American suppliers now stretches 18-24 months, delaying commercial commissioning.
- EU F-Gas Phase-Down:Thermal management refrigerant restrictions are forcing redesigns of liquid-cooled charging systems and raising compliance costs for imported hardware.
Strategic Opportunities
- Remote Mining Fleets:Off-grid solar-storage charging in Australia and Canada is displacing diesel generation for heavy-duty haul trucks.
- Vehicle-to-Grid Integration:Bidirectional charging protocols are creating new revenue streams for fleet operators in frequency regulation markets.
- India PLI Scheme:Domestic manufacturing incentives for advanced chemistry cells are attracting module assembly investments for localized charging infrastructure.
Industry Challenges
- Power Electronics Talent:Shortages of engineers with combined PV, battery, and EVSE expertise are throttling deployment velocity for integrated systems.
- Multi-Standard Certification:Simultaneous UL, CE, and GB compliance for export markets is extending product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PV BESS EV Charging Systems Market |
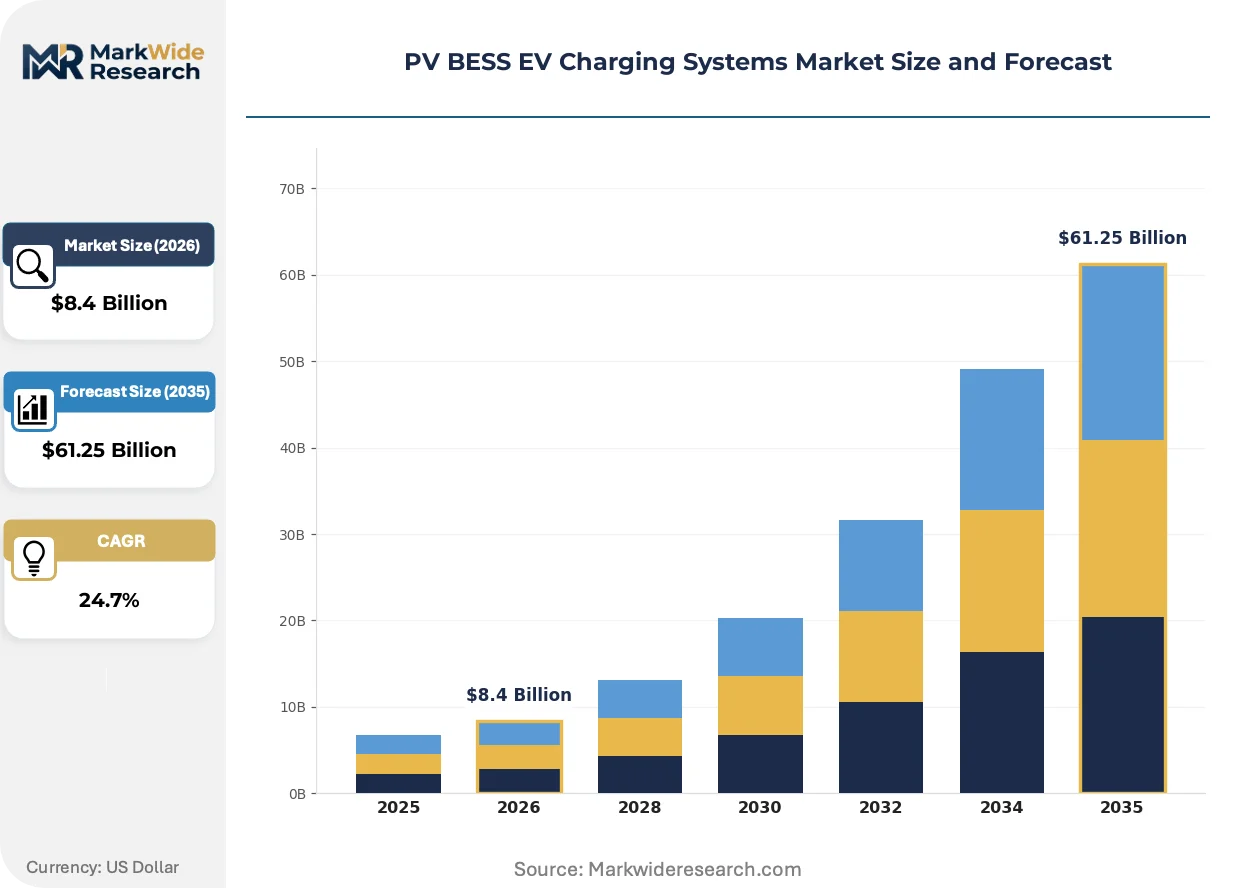
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $61.25 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Units, Commercial Stations, Fleet Solutions, Fast Chargers Integration Level: Standalone, Grid-Connected, Hybrid, Off-Grid Application: Public Infrastructure, Residential Charging, Workplace Charging, Fleet Operations Service Type: Installation, Maintenance, Consultancy, Software Solutions |
| Companies Covered | EVBox, KSTAR, Tesla, SMA, Huawei, SUNGROW, Electrify America, Envision Solar, GoodWe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PV BESS EV Charging Systems Market Trends and Innovations
Digital orchestration layers are becoming the primary battleground as hardware commoditizes across the solar-storage-charging stack. Control software now determines system economics more than component specifications.
AI-driven predictive maintenance is digitizing operations across commercial charging networks. Algorithms analyze inverter thermal patterns and battery degradation curves to preempt failures. Fleet operators in Germany and the Netherlands are deploying these platforms to minimize downtime at high-utilization corridors. The technology is digitizing service contracts from reactive repairs toward guaranteed availability metrics.
The EU F-Gas Regulation is accelerating refrigerant transitions in liquid-cooled charging hardware. Natural coolant alternatives are displacing synthetic hydrofluorocarbons in thermal management systems. Chinese manufacturers are retooling export-bound production lines to meet these specifications ahead of enforcement deadlines. European port authorities are now screening incoming equipment for compliance documentation.
Consolidated procurement platforms are aggregating demand from fragmented fleet operators. Third-party asset managers are underwriting solar-storage charging deployments and selling electrons-as-a-service to logistics customers. This model is spreading fastest in the United States where tax equity financing structures support off-balance-sheet treatment. Small and mid-sized carriers gain access to charging infrastructure without capital deployment or operational complexity.
PV BESS EV Charging Systems Market Segmentation
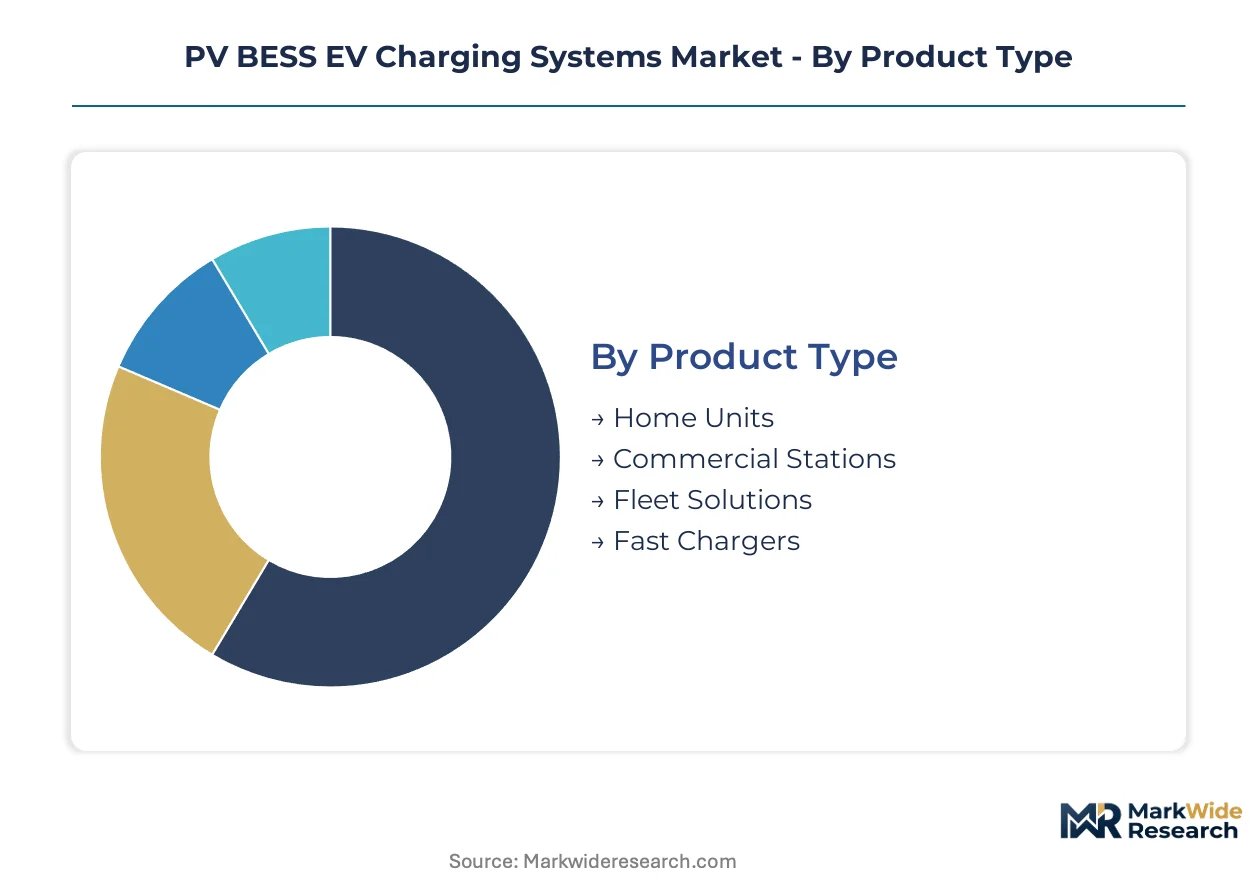
Segmentation in PV BESS EV charging systems reveals how hardware configurations, grid interconnection strategies, and service models map to distinct customer economics. Procurement patterns diverge sharply between residential adopters seeking bill optimization and fleet operators prioritizing uptime guarantees.
Product Type:
Mature DC fast-charging hardware dominates capital deployment, while integrated fleet solutions represent the fastest-emerging configuration as logistics electrification accelerates.
- Fast Chargers:DC units operating at 150-350 kW incorporate silicon carbide power electronics to minimize conversion losses. Demand clusters along California interstate corridors and Texas logistics hubs where California Air Resources Board mandates compress fleet electrification timelines.
- Fleet Solutions:Multi-station solar-storage architectures with centralized energy management serve depot-based charging for delivery and transit operators. Germany's KBA certification requirements and F-Gas refrigerant rules are reshaping thermal system specifications for European deployments.
- Commercial Stations:Retail-facing charging plazas with 4-20 dispensers target highway corridors and urban retail centers.
- Home Units:Single-point AC or DC systems below 50 kW serve residential garages with behind-the-meter solar coupling.
Fast chargers retain volume leadership; fleet solutions hold the steepest expansion curve.
Integration Level:
Cost tiering separates basic grid-tied configurations from premium hybrid architectures that command 40-60% capital premiums for islanding capability.
- Grid-Connected:Systems without storage buffer rely on net metering or time-of-use arbitrage, limiting resilience value. Procurement concentrates in US states with favorable interconnection standards and stable utility rate structures.
- Hybrid:Solar-plus-storage configurations with seamless grid/island switching command premium pricing for resilience-critical applications. Mining operators in Western Australia and remote Canadian territories are displacing diesel generation with these systems.
- Standalone:Charger-only deployments without generation or storage assets represent legacy infrastructure being retrofitted.
- Off-Grid:Fully autonomous solar-storage charging serves locations beyond utility distribution networks.
Grid-connected configurations dominate current installed base; hybrid systems are gaining share fastest among new commercial deployments.
Application:
Customer type segmentation separates fragmented residential demand from concentrated fleet procurement with multi-million-dollar contract values.
- Fleet Operations:Centralized depot charging for logistics, transit, and municipal vehicles requires 500 kW to multi-MW power capacity. India's PLI scheme for advanced chemistry cells is attracting domestic assembly investments to serve this segment locally.
- Public Infrastructure:Highway and urban charging plazas serve mixed-use demand with high utilization volatility. China's MIIT certification standards and GB/T connector mandates shape procurement for domestic and export-bound equipment.
- Workplace Charging:Employer-sited stations serve employee vehicles during business hours with lower power requirements.
- Residential Charging:Single-family and multi-unit dwelling installations represent high-volume, low-margin hardware sales.
Fleet operations command the highest revenue per site; public infrastructure represents the largest addressable unit count.
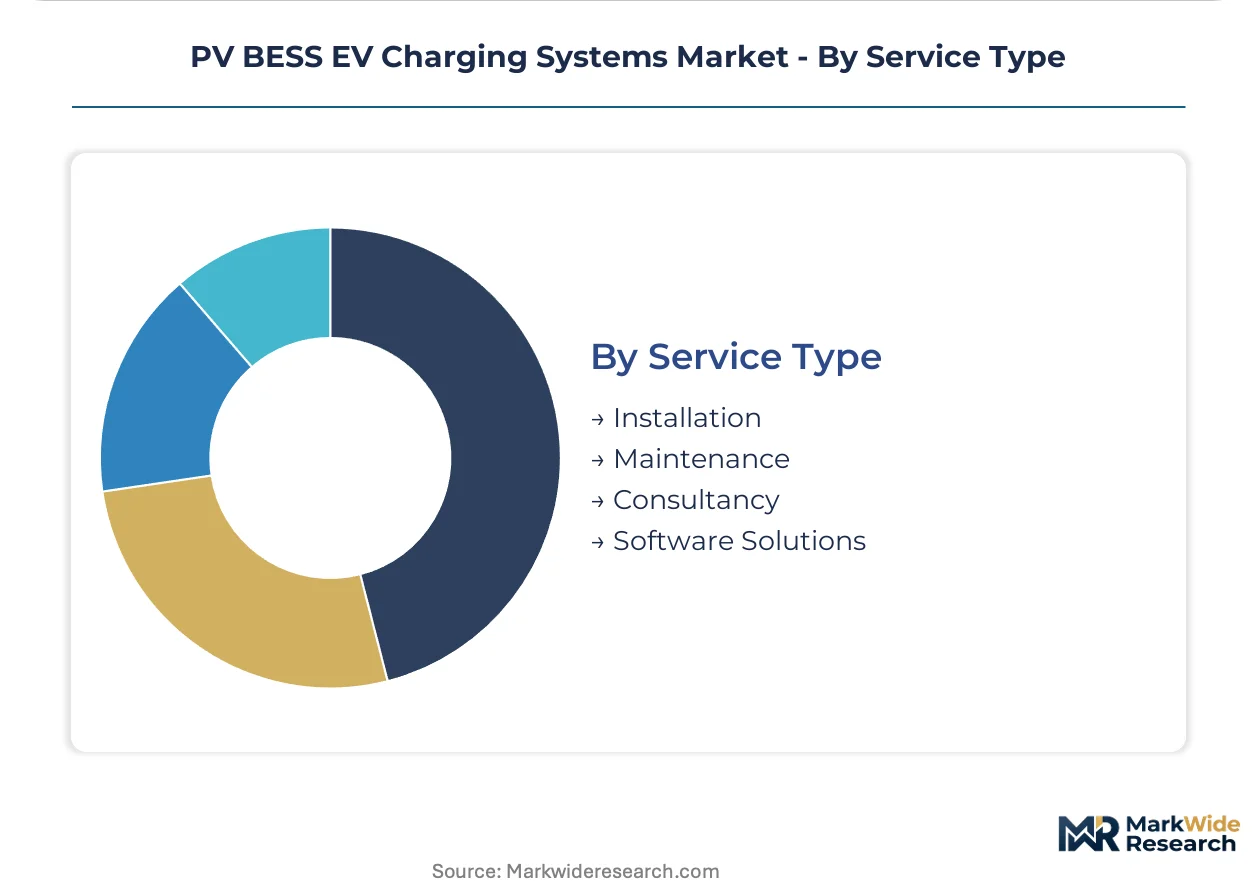
Service Type:
Margin structure inverts between commoditized installation labor and recurring software subscriptions with 70%+ gross margins.
- Software Solutions:Energy management platforms with AI-driven load balancing and predictive maintenance digitize system economics. Dutch and German fleet operators are deploying these tools to guarantee availability metrics in service contracts.
- Maintenance:Preventive and corrective service contracts for power electronics and battery systems extend asset life. China's NMPA and MIIT joint regulations on battery traceability are elevating documentation requirements for service providers.
- Installation:Electrical contracting and civil works for charger deployment face margin compression from labor shortages.
- Consultancy:Feasibility studies and interconnection navigation support early-stage project development.
Installation services handle the highest transaction volume; software solutions capture the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: fleet operators in the United States prioritize grid resilience and peak shaving, while Chinese deployments emphasize manufacturing cost optimization and export-ready standardization. European procurement centers on regulatory compliance and circularity requirements.
United States
Fleet electrification mandates in California and grid resilience investments in Texas drive commercial deployment of hybrid solar-storage charging hubs. The Inflation Reduction Act tax credits accelerate behind-the-meter storage adoption for logistics depots. Dallas-Fort Worth logistics corridors host the densest concentration of multi-MW solar-integrated charging installations serving regional distribution networks.
China
Domestic manufacturing scale and export-oriented capacity expansion reshape global supply dynamics for power conversion equipment. MIIT certification standards and NMPA battery traceability rules elevate compliance thresholds for grid interconnection. The Yangtze River Delta manufacturing cluster supplies over half of global string inverter and energy management system production for charging infrastructure.
Germany
KBA type approval requirements and F-Gas refrigerant phase-downs force thermal system redesigns in liquid-cooled charging hardware. Fleet operators deploy AI-driven predictive maintenance platforms to guarantee availability metrics under stringent service contracts. The Ruhr industrial corridor hosts Europe's densest concentration of solar-integrated heavy-duty depot charging for municipal transit electrification.
Australia
Remote mining operations displace diesel generation with off-grid solar-storage charging for heavy-duty haul truck fleets. The country's national energy regulator mandates grid stability standards that favor hybrid architectures with islanding capability. Western Australia's Pilbara region leads deployment of autonomous solar-charging stations for 24/7 mining logistics operations.
India
The PLI scheme for advanced chemistry cells attracts domestic module assembly investments to serve fleet electrification demand. Central Electricity Authority grid codes shape interconnection standards for commercial charging hubs. Maharashtra's Pune-Nashik industrial corridor concentrates manufacturing investments for localized charging infrastructure serving last-mile delivery electrification.
PV BESS EV Charging Systems Market Competitive Landscape
Capability concentration sits with integrated platform specialists; scale advantage sits with captive component manufacturers. The vendor base stratifies across three tiers: full-stack integrators controlling power electronics and software, hardware-focused fabricators with cost-optimized manufacturing, and regional system assemblers serving localized certification requirements. Dominant competitive moves include backward integration into semiconductor sourcing and strategic partnerships for multi-standard certification acceleration.
Among scale-driven power electronics specialists, SUNGROW and Huawei occupy positions anchored in manufacturing depth and smart grid software integration respectively. Tesla exemplifies the full-stack archetype through its Supercharger network architecture. These three companies represent distinct competitive vectors: cost leadership through captive inverter production, AI-driven load balancing platforms, and premium fast-charging network density.
| Leading Market Players |
|---|
| EVBox |
| KSTAR |
| Tesla |
| SMA |
| Huawei |
| SUNGROW |
| Electrify America |
| Envision Solar |
| GoodWe |
| Others |
Pricing and Supply Chain Analysis
China's Yangtze River Delta manufacturing cluster controls over half of global string inverter and energy management system production for charging infrastructure, anchoring margin pools in power electronics assembly rather than raw materials or downstream installation services. This concentration enables tier-one suppliers to capture value through captive component sourcing while forcing price competition on non-integrated hardware fabricators.
Pricing Analysis
Long-term power purchase agreements and electrons-as-a-service contracts dominate commercial fleet procurement, insulating operators from capital expenditure while locking in subscription revenue for asset managers. Price differentiation hinges on certification tier — UL-listed hardware commands premiums over CE-marked alternatives in North American corridors — and software integration depth, with AI-driven load balancing platforms capturing recurring margins. Cost compression in standalone charger hardware is intensifying because silicon carbide inverter adoption is eroding conversion-loss advantages. Small and mid-sized logistics carriers exhibit the highest price sensitivity, lacking balance-sheet capacity for direct infrastructure ownership.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for North American deployments, with inverter and battery management system imports facing potential duty escalations. Manufacturing concentration rests on China for lithium-ion cell assembly, South Korea for advanced cathode materials, and Germany for precision thermal management components. Raw material dependencies span refined copper for busbars, silicon carbide wafers for power semiconductors, and lithium carbonate for storage cells. Single-source vulnerability in transformer production from North American suppliers has extended utility interconnection timelines. Distribution runs through third-party asset managers aggregating fragmented fleet demand into consolidated procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PV BESS EV charging infrastructure fragmentation creates entry niches as fleet electrification timelines compress and procurement patterns splinter across certification regimes, customer scale tiers, and service model preferences.
For Market Incumbents: Entrench position through backward integration into silicon carbide semiconductor sourcing and captive battery cell supply, defending against emerging platform aggregators. Prioritize multi-standard certification acceleration to compress product development cycles currently extended by simultaneous UL, CE, and GB compliance requirements. Deepen software subscription attach rates to offset hardware margin erosion. For New Entrants and Emerging Players: India's Pune-Nashik industrial corridor offers the most penetrable geography, with PLI scheme incentives for advanced chemistry cell assembly creating localized manufacturing footholds. Target remote mining fleet operations in Western Australia and Canadian territories where off-grid solar-storage configurations displace diesel generation with minimal incumbent competition. Lead with predictive maintenance platforms guaranteeing uptime availability metrics rather than hardware-only sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet charging platform operators holding electrons-as-a-service contracts but lacking integrated power electronics manufacturing. Five-to-ten year viability hinges on software gross margin sustainability and regulatory certification moats. Watch for F-Gas Regulation enforcement deadlines in European ports as an inflection signal for thermal management system redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Sourcing | Captive semiconductor supply cuts conversion losses and insulates against wide-bandgap material shortages. |
| Multi-Standard Certification Acceleration | Parallel UL, CE, and GB approval compresses product launch timelines across North American, European, and Chinese corridors. |
| AI-Driven Predictive Maintenance Platform Launch | Dutch and German fleet operators deploy these tools to guarantee availability under stringent service contracts. |
| Electrons-as-a-Service Model Expansion | Third-party asset managers aggregate fragmented logistics demand while retaining off-balance-sheet treatment under IRA tax structures. |
| Natural Coolant Thermal System Redesign | EU F-Gas Regulation compliance requires refrigerant transitions in liquid-cooled charging hardware ahead of enforcement deadlines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, utility interconnection planners, power electronics procurement leads, and EPC contractors; and secondary validation against FERC interconnection filings, EIA capacity deployment data, IEA technology cost benchmarks, and MIIT certification registries. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across the analysis window.
Forecast inputs span product type segmentation by charging power tier, integration level by grid interconnection architecture, application by customer scale and use case, and service type by revenue model. CAGRs derive from modeled deployment velocity against regulatory mandate deadlines and manufacturing capacity expansion curves. Silicon carbide inverter adoption rates and battery pack cost trajectories anchor technology-specific assumptions.
Practitioners should monitor lithium price volatility, transformer lead time extensions, and EU F-Gas enforcement timing for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market