
 Global Electric Vehicle (EV) Charging Service Market | 2026-2036
Global Electric Vehicle (EV) Charging Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Vehicle (EV) Charging Service Market Intelligence
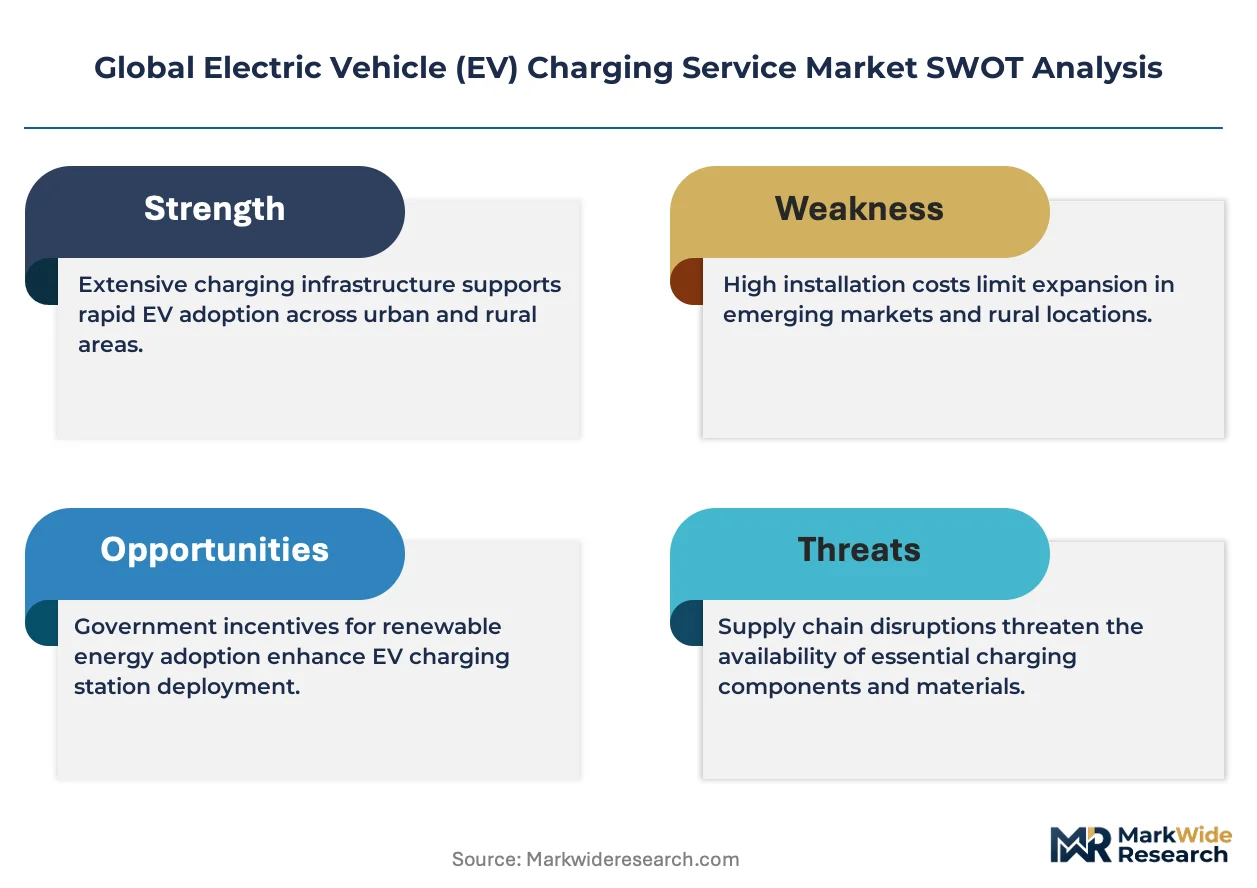
Buyer concentration is expanding as commercial fleet operators and municipal governments consolidate procurement decisions across multi-site charging contracts. Tesla leverages its Supercharger network dominance to anchor highway corridor deployment in North America. ChargePoint Holdings competes through software-integrated hardware platforms that sustain recurring revenue from commercial operators. Shell Recharge differentiates by extending retail fuel station conversions into combined charging and convenience hubs across European markets.
The electric vehicle charging service encompasses the provision of electrical energy transfer, network management, and payment processing infrastructure that enables battery electric vehicles to replenish stored energy, typically operating at power levels from 7 kW alternating current for Level 2 residential units to 350 kW direct current for fast charging stations with liquid-cooled cable systems. Its primary commercial purpose is to deliver reliable, metered energy access that supports vehicle uptime for private owners and operational continuity for fleet-dependent businesses. Fast charging commands premium pricing due to capital intensity and grid interconnection requirements, while Level 2 charging occupies the volume base through lower installation costs and broader real estate compatibility. Battery swapping remains structurally constrained by proprietary pack geometries but holds margin potential in commercial fleet applications with standardized vehicle platforms.
The EU Green Deal and F-Gas Regulation shape European product standards for cooling systems and grid interconnection protocols, while China's GB standards and MIIT directives enforce domestic interoperability and state grid integration requirements. The US EPA and NHTSA coordinate tailpipe and fuel economy rules that indirectly mandate charging availability ratios in zero-emission vehicle states. Stakeholders must monitor evolving grid capacity allocation mechanisms and dynamic tariff structures as determinants of station profitability and deployment sequencing.
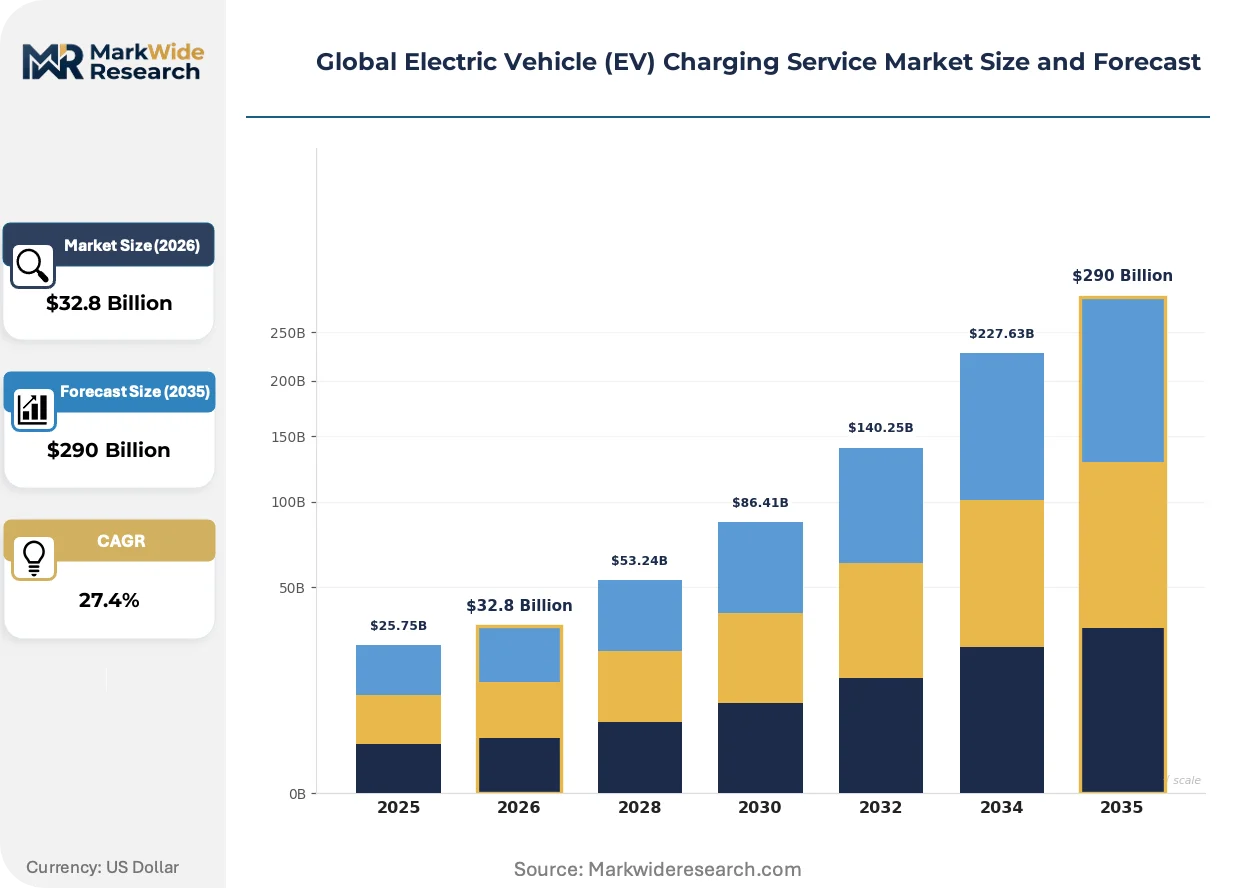
Market Dynamics
Commercial fleet operators and municipal procurement programs are consolidating multi-site charging contracts, compressing vendor margins while elevating software-integrated hardware platforms that sustain recurring revenue streams beyond hardware sales.
Growth Catalysts
- EU Green Deal mandates:Germany, France, and the Netherlands enforce tightening compliance timelines for charging infrastructure density, compelling commercial real estate developers to pre-wire parking assets.
- China's MIIT directives:State-backed grid modernization and municipal procurement programs accelerate station deployment across megacities, creating captive demand for domestic interoperability standards.
- 350 kW liquid-cooled systems:Highway corridor operators adopt high-power direct current hardware to minimize dwell time for long-haul commercial fleets, anchoring premium pricing tiers.
Market Restraints
- Grid interconnection queues:Utility approval timelines in the US extend 18-24 months for fast charging stations, freezing capital deployment and inflating project carrying costs.
- Transformer and switchgear supply:European electrical equipment manufacturers face order backlogs stretching 12-16 months, constraining station commissioning schedules.
- Proprietary battery geometries:Battery swapping remains structurally constrained by non-standardized pack designs, limiting margin capture in commercial fleet applications despite standardized vehicle platform potential.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for electric vehicle manufacturing create downstream demand for charging infrastructure in Delhi, Mumbai, and Bangalore metropolitan clusters.
- Retail fuel station conversions:Shell and integrated oil majors repurpose European forecourts into combined charging and convenience hubs, capturing dwell-time commerce revenue.
- Vehicle-to-grid integration:Bidirectional charging technology convergence with home energy management systems opens residential battery arbitrage revenue streams for utilities and aggregators.
Industry Challenges
- High-voltage electrical technician scarcity:Specialized labor for 350 kW installation and maintenance commands wage premiums of 40-60% above standard electricians, inflating operational costs.
- GB standards compliance:China's domestic interoperability and state grid integration requirements force foreign hardware vendors into costly certification cycles and joint venture structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Vehicle (EV) Charging Service Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $290 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Charging, Level 2 Charging, Wireless Charging, Destination Charging, Battery Swapping Application: Private Vehicles, Commercial Fleets, Public Transportation, Ride Sharing, Logistics Customer Type: Individual Consumers, Commercial Operators, Fleet Managers, Municipal Governments, Workplace Deployment: Urban Areas, Suburban Zones, Highway Corridors, Residential Complexes, Commercial Complexes |
| Companies Covered | ChargePoint Holdings, Tesla, Shell Recharge, EVgo, Electrify America, Blink Charging, ABB, Siemens, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Vehicle (EV) Charging Service Market Strategic Shifts & Innovations
Power electronics miniaturization and silicon carbide semiconductor adoption are compressing charger footprints while elevating conversion efficiency, enabling deployment in space-constrained urban environments previously inaccessible to high-power hardware.
Silicon carbide power modules are overtaking insulated-gate bipolar transistor architectures in 150 kW and above charging stations. European and North American highway corridor operators are adopting SiC-based hardware to reduce cooling system volume by 30-40%. This technology compression is overtaking incumbent thermal management designs, shrinking station footprints and enabling retrofit installation in existing parking structures with limited electrical room capacity.
The F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in European charging station cooling systems, compelling manufacturers to adopt CO2 transcritical or propane-based alternatives. Industrial consequence includes 15-20% higher capital costs for compliant thermal management hardware. Fast charging equipment deployed along German autobahn corridors faces the most acute compliance pressure, with operators accelerating procurement timelines to lock in pre-2026 equipment certifications.
Fleet operators are consolidating charging procurement under centralized energy management contracts rather than site-by-site hardware purchases. Commercial logistics and last-mile delivery segments are displacing fragmented owner-operator arrangements with multi-year service agreements bundling hardware, software, and energy arbitrage. This concentration is most visible in California and the Netherlands, where zero-emission vehicle mandates have compressed fleet electrification timelines and elevated operational continuity requirements.
Global Electric Vehicle (EV) Charging Service Market Segmentation
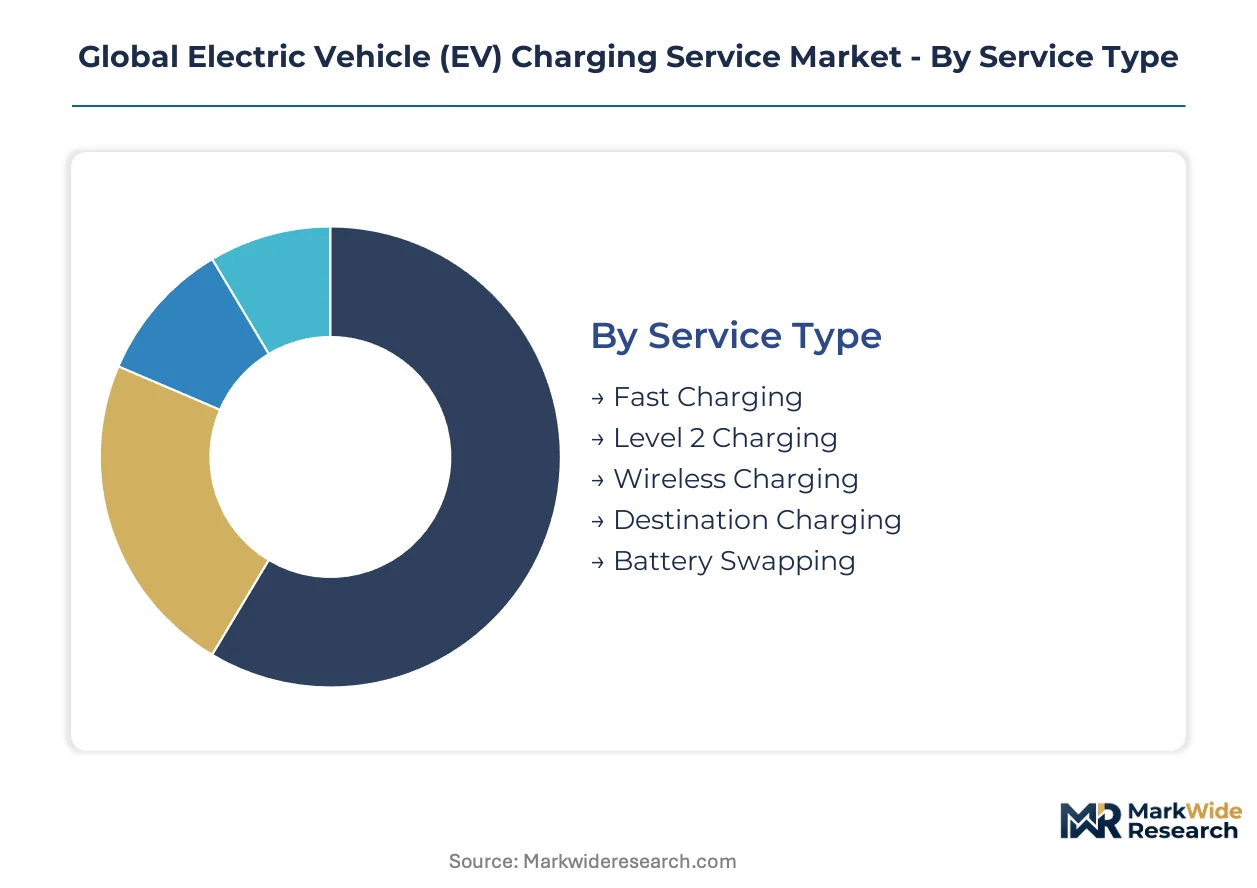
Segmentation in EV charging services reveals divergent capital intensity and margin profiles across power levels and deployment contexts. Service providers must align hardware specifications, software platforms, and energy procurement strategies to the distinct operational rhythms of each segment.
Service Type:
Upgrade cycles in charging hardware accelerate as silicon carbide semiconductors displace legacy insulated-gate bipolar transistor architectures, compressing equipment replacement timelines from seven years toward five.
- Fast Charging:Direct current systems operating at 150-350 kW with liquid-cooled cable assemblies minimize dwell time for long-haul commercial fleets. Highway corridor operators in Germany and California anchor procurement volumes as zero-emission vehicle mandates tighten fleet electrification deadlines.
- Level 2 Charging:Alternating current units at 7-19 kW dominate installation counts through lower capital requirements and broader real estate compatibility. Workplace and residential deployments across Dutch municipal programs sustain volume leadership despite thinner per-unit margins.
- Wireless Charging:Inductive pad systems enable automated fleet depot operations without connector wear. Limited commercial penetration reflects efficiency losses and infrastructure standardization gaps.
- Destination Charging:Integrated hospitality and retail installations capture extended parking durations. Shopping mall operators in Chinese megacities bundle charging with loyalty programs to extend customer dwell.
- Battery Swapping:Automated pack exchange stations circumvent charging duration constraints entirely. Proprietary pack geometries from NIO and other OEMs limit interoperability despite standardized commercial fleet potential.
Level 2 Charging sits at the top of the volume ranking, with Fast Charging climbing the fastest.
Application:
Cost tier differentiation separates capital-intensive depot installations from opportunistic public charging, with fleet operators consolidating procurement under multi-year energy management contracts.
- Private Vehicles:Residential and workplace charging dominates energy throughput per session. Individual ownership patterns in suburban US zones and European single-family housing sustain Level 2 hardware demand.
- Commercial Fleets:Centralized depot charging with 150-350 kW DC hardware supports operational continuity for logistics and last-mile delivery. California Air Resources Board mandates compress electrification timelines for medium- and heavy-duty segments.
- Public Transportation:Bus and rail electrification requires megawatt-scale depot infrastructure with grid interconnection upgrades. Municipal procurement in Shenzhen and Santiago anchors volume concentration.
- Ride Sharing:High-utilization vehicles demand rapid turnaround charging in urban cores. Driver incentives from Uber and Didi Chuxing steer deployment toward fast charging corridors.
- Logistics:Warehouse-to-last-mile routes favor overnight depot charging with daytime opportunity charging at distribution hubs. Amazon and DHL electrification commitments in Germany and the Netherlands drive contract consolidation.
Commercial Fleets command the steepest expansion trajectory as zero-emission mandates displace diesel platforms.
Customer Type:
Customer concentration patterns shift procurement power toward institutional buyers with multi-site deployment authority and centralized energy arbitrage capabilities.
- Individual Consumers:Residential installations and ad-hoc public charging sustain the broadest addressable base. Homeowner associations in California and Texas navigate electrical panel upgrade costs.
- Commercial Operators:Retail, hospitality, and workplace hosts monetize parking assets through charging access fees. Shell Recharge and integrated oil majors convert European forecourts into combined charging and convenience hubs.
- Fleet Managers:Centralized procurement of hardware, software, and energy services displaces fragmented owner-operator arrangements. LeasePlan and Arval multi-year service agreements bundle operational continuity guarantees.
- Municipal Governments:Streetlight-integrated charging and public curbside deployment address urban dwellers without dedicated parking. Amsterdam and Singapore procurement programs prioritize sidewalk footprint minimization.
- Workplace:Employer-subsidized charging extends daily electric range for commuters. Corporate sustainability commitments in tech clusters around Bangalore and Seoul accelerate installation timelines.
Fleet Managers are gaining share fastest as electrification mandates consolidate procurement authority, with Individual Consumers retaining volume leadership.
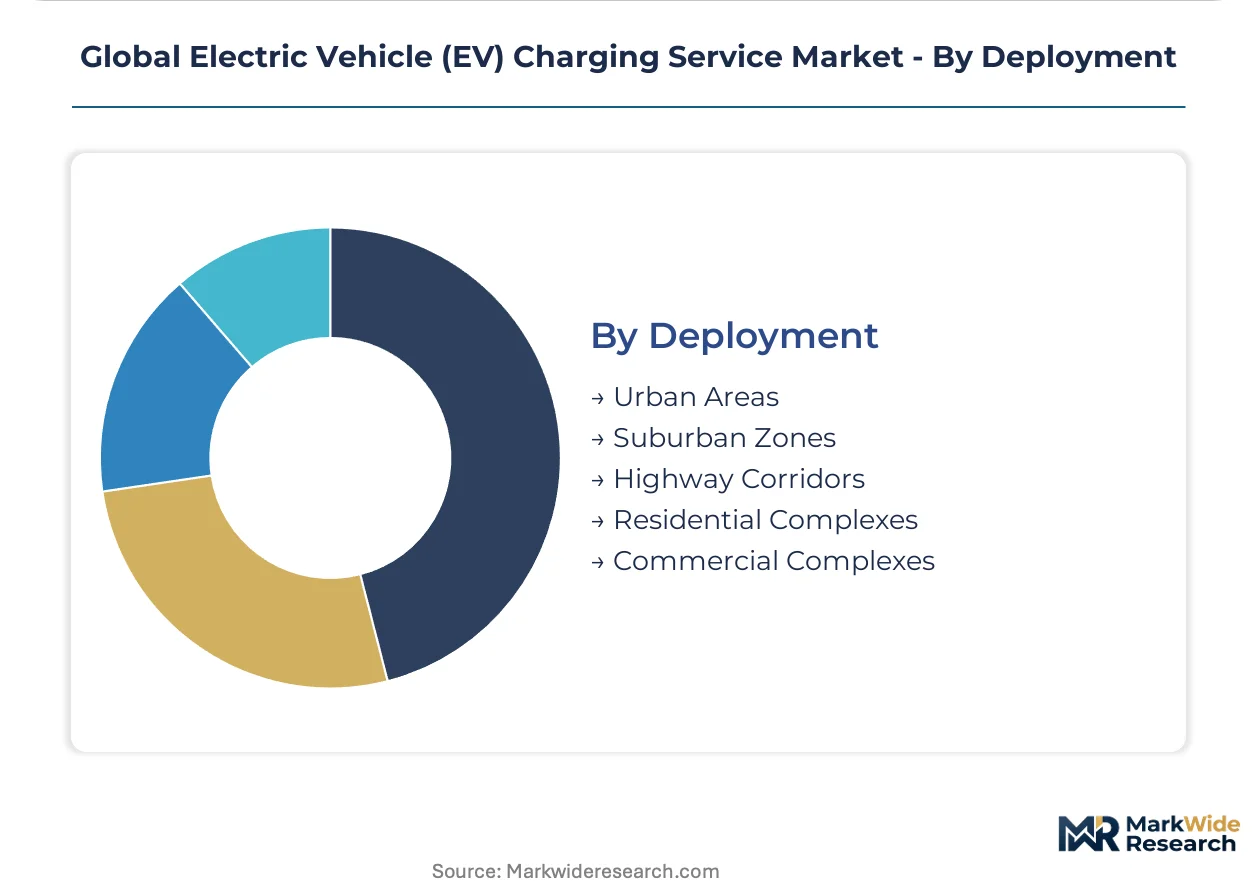
Deployment:
Geographic deployment patterns track population density, grid capacity availability, and real estate access constraints across urban, suburban, and corridor contexts.
- Urban Areas:Curbside and parking structure installations face space constraints and electrical room limitations. Paris and Tokyo deploy compact 50 kW units in heritage districts with restricted excavation permissions.
- Suburban Zones:Single-family residential and retail center installations offer lower grid interconnection complexity. US metropolitan rings around Atlanta and Phoenix sustain Level 2 volume concentration.
- Highway Corridors:350 kW liquid-cooled stations anchor long-distance travel confidence. Tesla Supercharger dominance along US Interstate corridors and German autobahn networks shapes competitive access.
- Residential Complexes:Multi-unit dwelling installations require property owner coordination and load management systems. Condominium associations in Vancouver and Sydney navigate split-incentive barriers.
- Commercial Complexes:Office park and industrial zone deployments serve workplace and fleet depot applications. Logistics parks around Rotterdam and Shanghai integrate charging into warehouse design specifications.
Urban Areas retain the largest installed base, with Highway Corridors expanding most quickly as corridor completion becomes a competitive priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed grid modernization outpaces US utility approval timelines by 12-18 months, while Germany's autobahn corridor buildout compresses vendor certification cycles under F-Gas Regulation deadlines.
China
Municipal procurement programs in Shenzhen and Shanghai accelerate station deployment across megacities. MIIT directives enforce GB standards compliance and state grid integration requirements. Yangtze River Delta manufacturing clusters supply liquid-cooled cable assemblies for 350 kW highway installations.
Germany
Commercial fleet operators consolidate multi-site charging contracts under zero-emission vehicle mandates. The EU Green Deal and F-Gas Regulation tighten infrastructure density timelines and cooling system refrigerant phase-downs. Autobahn corridor operators near Frankfurt and Munich lock in pre-2026 equipment certifications.
United States
California Air Resources Board mandates compress electrification timelines for medium- and heavy-duty segments. EPA and NHTSA coordination on tailpipe rules indirectly mandates charging availability ratios. Tesla Supercharger dominance anchors Interstate corridor completion from Los Angeles to San Francisco and Dallas to Houston.
Netherlands
Zero-emission vehicle mandates elevate operational continuity requirements for last-mile delivery fleets. National charging infrastructure density targets exceed EU Green Deal baselines. Amsterdam streetlight-integrated procurement prioritizes sidewalk footprint minimization in heritage districts.
India
Production-linked incentives for electric vehicle manufacturing create downstream infrastructure demand. Central Electricity Authority guidelines shape grid interconnection protocols for metropolitan clusters. Delhi, Mumbai, and Bangalore logistics parks integrate depot charging into warehouse design specifications.
Global Electric Vehicle (EV) Charging Service Market Key Industry Players
US producers anchor the software-integrated hardware tier; European specialists hold the retail fuel station conversion segment. The vendor base stratifies across three tiers: integrated oil majors repurposing forecourt assets, pure-play charging network operators, and industrial electrical equipment manufacturers. Dominant competitive moves include strategic partnerships bundling hardware with energy management services and geographic expansion into municipal procurement corridors.
Within the network operator tier, ChargePoint Holdings and Tesla exemplify divergent strategic archetypes. ChargePoint Holdings occupies a position emphasizing software-integrated platforms that sustain recurring revenue from commercial operators. Tesla anchors highway corridor deployment through vertically controlled infrastructure. Shell Recharge represents the integrated oil major archetype, converting European retail fuel stations into combined charging and convenience hubs.
| Leading Market Players |
|---|
| ChargePoint Holdings |
| Tesla |
| Shell Recharge |
| EVgo |
| Electrify America |
| Blink Charging |
| ABB |
| Siemens |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up charging network specialists have consolidated fragmented hardware vendors across North America and Europe, compressing procurement timelines while anchoring pricing discipline through multi-year service contracts that bundle energy management with hardware deployment.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for silicon carbide power modules and liquid-cooled cable assemblies. Three-tier pricing structure across premium, standard, and economy levels separates highway corridor operators with 350 kW requirements from workplace hosts at 7-19 kW and residential installers at basic alternating current levels. Price differentiation rests on certification grade — UL listing for North American deployments versus GB standards compliance for Chinese state grid integration — and volume scale in municipal procurement programs. Cost compression in Level 2 hardware is intensifying because European electrical equipment manufacturers face transformer order backlogs stretching 12-16 months. Fleet managers consolidating multi-site contracts exhibit lowest price sensitivity; individual consumers navigating homeowner association approvals show highest sensitivity to upfront installation costs.
Supply Chain Analysis
Freight costs for liquid-cooled cable assemblies and high-voltage switchgear from Chinese manufacturing hubs to European port terminals have elevated landed cost premiums by 15-20% above ex-factory pricing. Geographic supply concentration centers on China for silicon carbide semiconductors and power electronics, Germany for precision cooling systems and grid interconnection hardware, and South Korea for high-capacity electrical components. Raw material dependencies draw from copper cathode contracts, rare earth magnet supplies for motor drives, and aluminum extrusions for enclosure housings. Single-source vulnerability in transformer manufacturing constrains station commissioning schedules across German autobahn corridors. Distribution runs through direct OEM relationships for fleet depot installations, electrical distributors for commercial workplace deployments, and municipal procurement frameworks for curbside urban infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in EV charging services hinges on silicon carbide semiconductor adoption compressing equipment replacement cycles and elevating conversion efficiency premiums for space-constrained urban deployments.
For Market Incumbents: Cement software-integrated platform dominance by deepening backward integration into power electronics manufacturing and securing captive supply of silicon carbide modules from Yangtze River Delta foundries. Defend against emerging pure-play energy management aggregators by embedding vehicle-to-grid bidirectional capabilities into existing hardware install bases before regulatory mandates accelerate in California and the Netherlands. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass incumbent distributor relationships and compress customer acquisition costs for last-mile delivery electrification contracts. Target India's PLI scheme downstream demand in Delhi, Mumbai, and Bangalore metropolitan clusters where domestic interoperability standards remain unsettled. Penetrate through overnight depot charging optimization software rather than capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial electrical equipment manufacturers with charging hardware divisions but lacking recurring software revenue streams. Long-term viability across the analysis window favors asset-light network operators with multi-year municipal procurement contracts over hardware-dependent vendors exposed to silicon carbide transition capex. Watch for F-Gas Regulation compliance deadlines in Germany accelerating pre-2026 equipment certification lock-ins as inflection indicator for European market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Transition | 30-40% cooling system volume reduction enables retrofit installation in existing parking structures with constrained electrical room capacity. |
| Fleet Energy Management Contract Consolidation | Multi-year service agreements bundling hardware, software, and energy arbitrage displace fragmented owner-operator arrangements in California and Netherlands logistics segments. |
| Retail Fuel Station Conversion | Shell Recharge and integrated oil majors repurpose European forecourts into combined charging and convenience hubs capturing dwell-time commerce revenue. |
| Vehicle-to-Grid Integration Development | Bidirectional charging convergence with home energy management systems opens residential battery arbitrage revenue streams for utilities and aggregators. |
| GB Standards Certification Investment | China's MIIT directives force foreign hardware vendors into costly certification cycles and joint venture structures with state grid integration requirements. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with charging network operators, fleet procurement managers, municipal infrastructure planners, and electrical equipment manufacturing executives alongside secondary validation. Primary fieldwork drew from utility planning officers at German grid operators, EPC contractors specializing in highway corridor installations, and aftermarket service heads at integrated oil majors. Secondary sources included EIA charging infrastructure deployment data, IEA transport electrification outlooks, FERC interconnection queue filings, and national zero-emission vehicle mandate documentation from California Air Resources Board and EU Green Deal regulatory filings. Bottom-up station deployment counts triangulated against top-down energy demand projections from automotive electrification forecasts.
Segment-weighting approaches distributed value estimates across service type tiers — fast charging, Level 2, wireless, destination, and battery swapping — with further disaggregation by application segments spanning private vehicles, commercial fleets, public transportation, ride sharing, and logistics. Customer type stratification incorporated individual consumers, commercial operators, fleet managers, municipal governments, and workplace hosts. Deployment context dimensions captured urban areas, suburban zones, highway corridors, residential complexes, and commercial complexes. CAGRs derived from logistic diffusion modeling of electrification mandate compliance timelines and infrastructure density requirements. Forecast inputs incorporated silicon carbide adoption curves, grid interconnection approval timelines, and fleet electrification commitment schedules from logistics operators.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization or hydrogen fuel cell penetration in long-haul commercial segments would alter the outlook for high-power charging demand concentrations. Forecasts reflect assumptions regarding regulatory mandate enforcement consistency, grid capacity allocation mechanisms, and raw material supply continuity for power electronics manufacturing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market