
 Electric Vehicle Public Charging Pile Market | 2026-2036
Electric Vehicle Public Charging Pile Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Public Charging Pile Market Insights
Bi-directional charging integration with grid services is reconfiguring how public charging piles deliver value beyond simple energy transfer. Tesla leverages its proprietary connector ecosystem and Supercharger network density to dominate North American highway corridors. ChargePoint sustains broad software-hardware integration across multiple connector standards. IONITY anchors ultra-high-power deployment across European motorway systems.
Electric vehicle public charging piles are permanently installed electrical supply units that convert grid alternating current to direct current at power ratings from 50 kW to 350 kW, using liquid-cooled cable assemblies and CCS or CHAdeMO connectors to replenish battery electric vehicle capacity in 15–45 minutes for commercial transit and consumer mobility applications. Fast chargers occupy the dominant installed base for highway and fleet applications where dwell-time minimization commands capital allocation. DC charging technology leads growth in power electronics investment as silicon carbide modules displace conventional IGBT architectures. Wireless chargers remain nascent in public settings, constrained by infrastructure cost and alignment precision requirements.
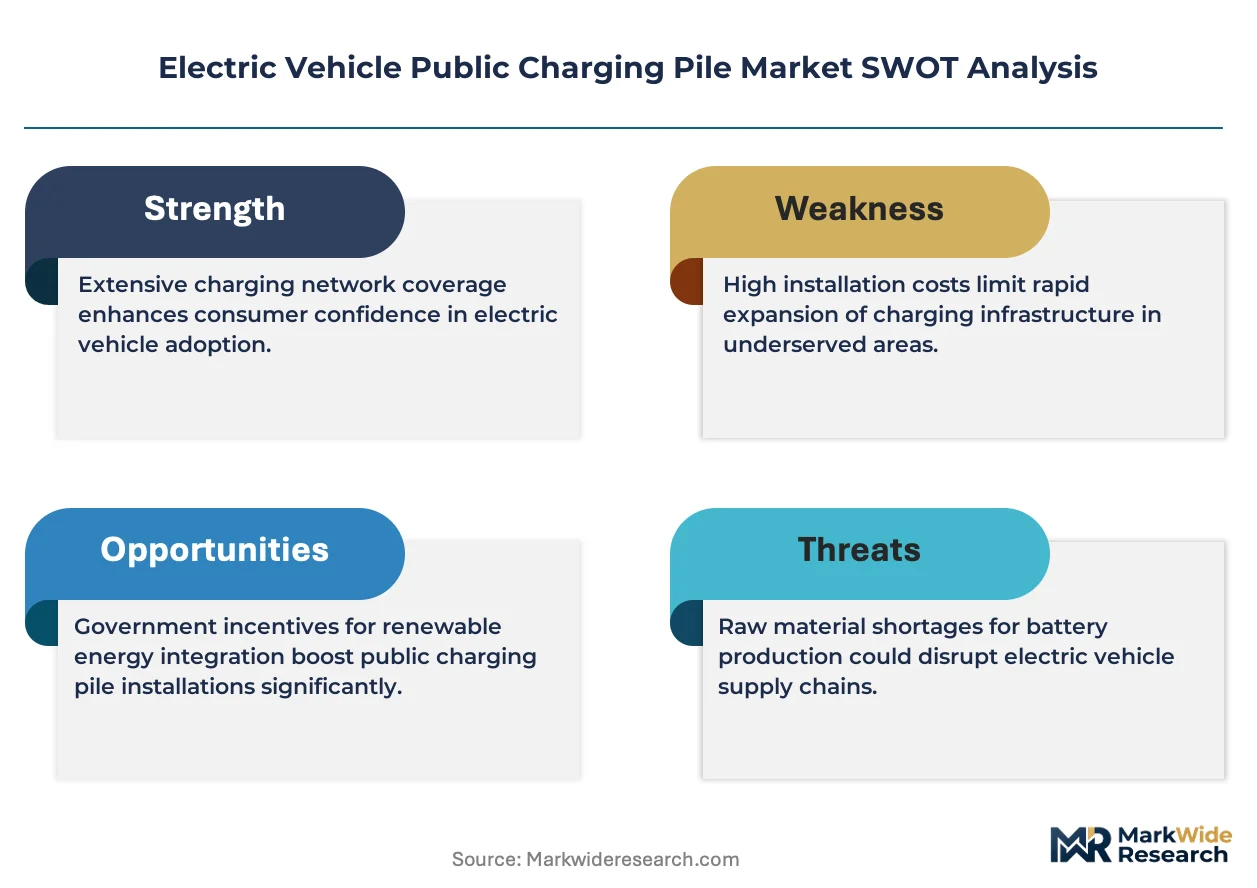
China's MIIT enforces GB/T 27930 communication protocol standards that shape interoperability mandates for all domestic public charging equipment. The EU Green Deal and F-Gas Regulation impose efficiency benchmarks and refrigerant constraints on thermal management systems within charging modules. In the United States, NHTSA and state-level public utility commissions coordinate on interstate corridor electrification funding and rate-case structures. Stakeholders must monitor how grid interconnection queues and utility tariff redesigns reshape site economics before committing capital to new locations.
Market Dynamics
Silicon carbide power modules are displacing conventional IGBT architectures across DC fast charging systems, compressing thermal management costs while enabling 350 kW+ output densities that reshape site economics and grid interconnection requirements.
Growth Catalysts
- EU Green Deal efficiency mandates:The F-Gas Regulation and complementary efficiency benchmarks accelerate equipment refresh cycles across European motorway networks, forcing legacy hardware replacement with liquid-cooled systems.
- Fleet electrification:Logistics operators deploying electric vans for last-mile delivery generate concentrated demand for 150-350 kW DC infrastructure at distribution hubs and highway access points.
- China's GB/T 27930 protocol:MIIT interoperability requirements standardize communication stacks across domestic manufacturers, reducing integration friction for network operators.
Market Restraints
- Copper and rare-earth volatility:Liquid-cooled cable assemblies and high-frequency magnetics depend on commodity inputs with concentrated supply from Chilean mining and Chinese processing clusters.
- Grid interconnection queues:Utility interconnection timelines in Germany and the United States extend 18-36 months for multi-megawatt highway corridor sites, freezing capital deployment.
- Wireless charging immobility:Alignment precision requirements and infrastructure cost multiples above conductive systems block public deployment at scale.
Strategic Opportunities
- Bi-directional V2G integration:Grid services revenue streams from frequency regulation and peak shaving transform charging piles into distributed energy assets.
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing create downstream demand for compatible fast-charging infrastructure.
- Highway corridor gaps:Secondary interstate routes in the United States and rural expressways in China remain underpenetrated relative to primary motorway density.
Industry Challenges
- Power electronics talent scarcity:Silicon carbide module design and thermal simulation expertise concentrates within automotive and aerospace supply chains, creating recruitment competition.
- Multi-standard certification complexity:CCS, CHAdeMO, and GB/T connector variants require parallel testing protocols that fragment engineering resources and delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Public Charging Pile Market |
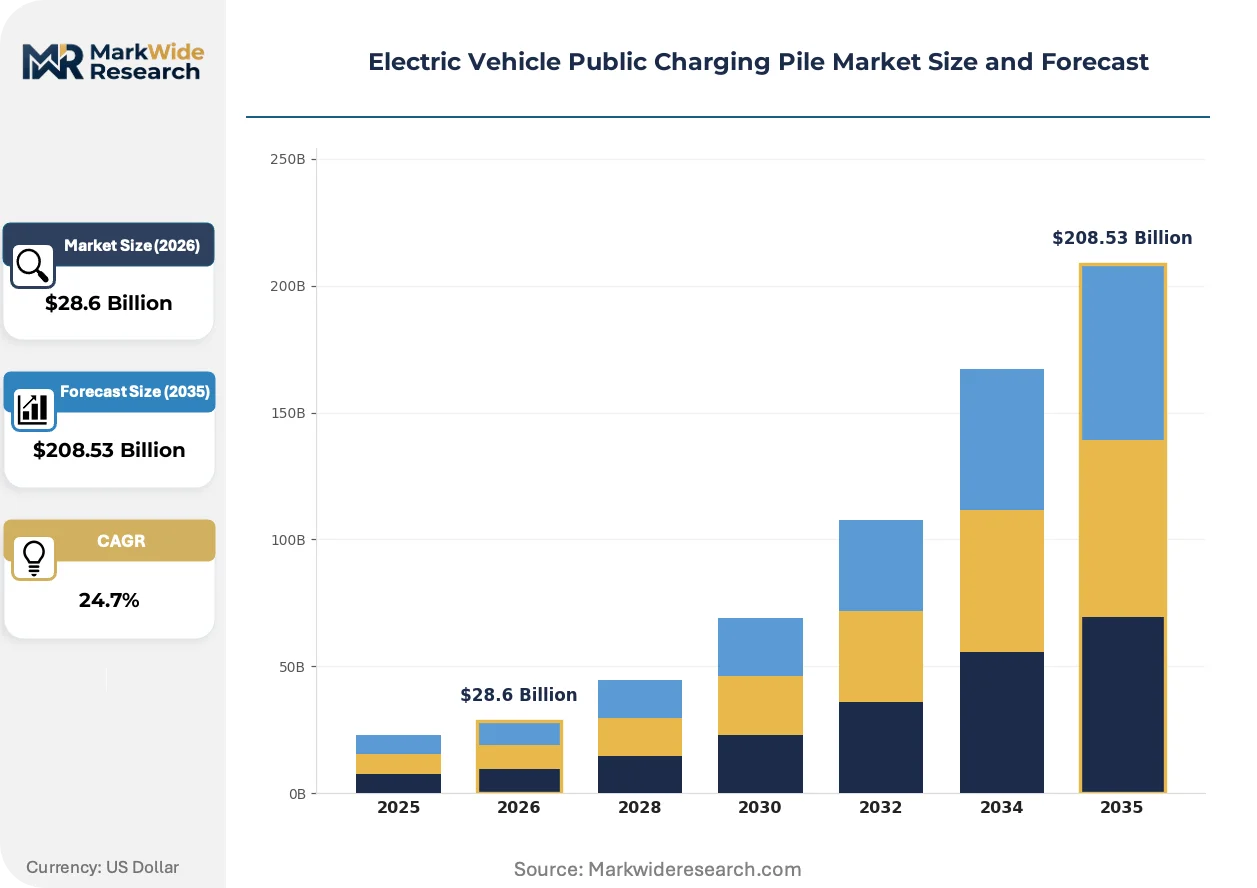
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $208.53 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
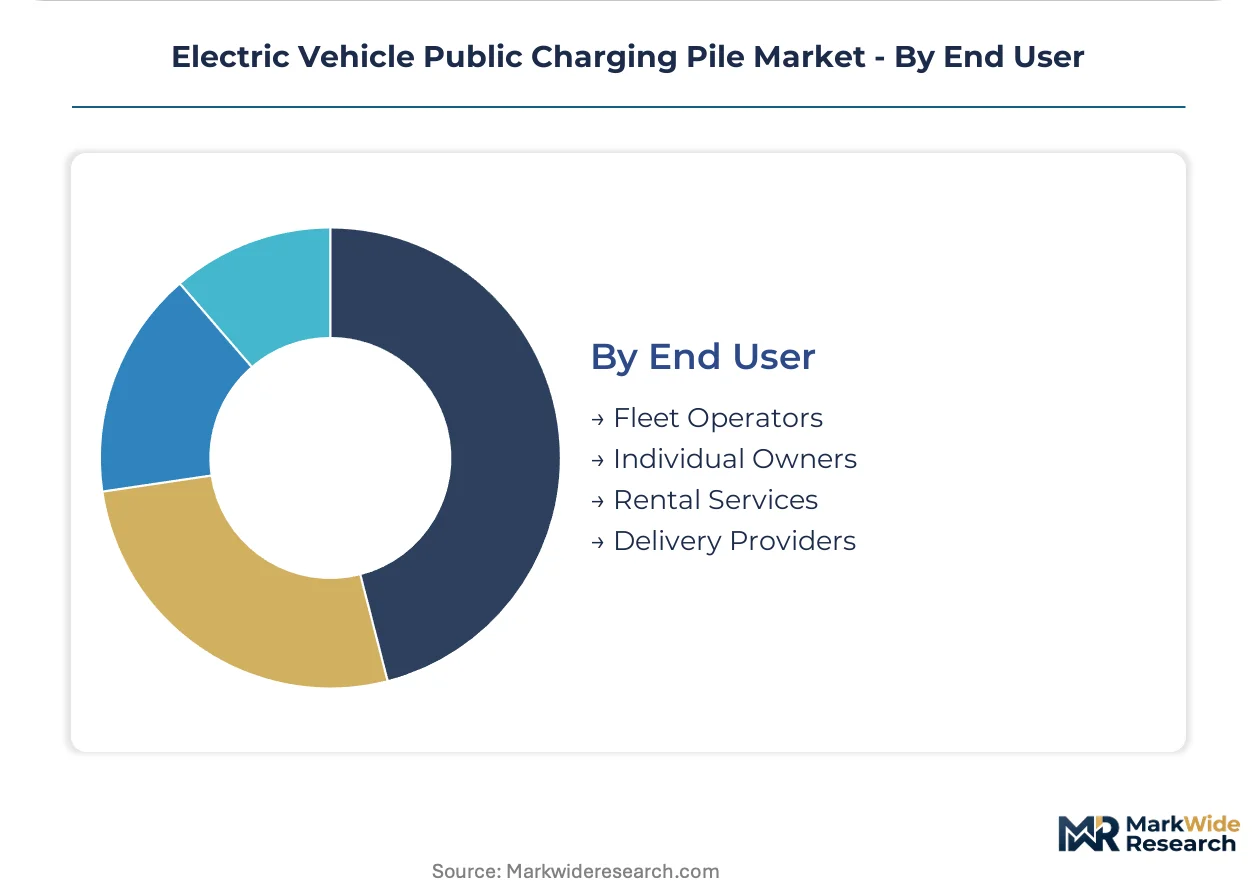
| Segmentation | Product Type: Fast Chargers, Slow Chargers, Ultra-Fast Chargers, Wireless Chargers Technology: AC Charging, DC Charging, Inductive Charging, Conductive Charging Application: Commercial Areas, Public Parking, Highway Stations, Shopping Complexes, Office Buildings End User: Fleet Operators, Individual Owners, Rental Services, Delivery Providers |
| Companies Covered | Electrify America, IONITY, Tesla, TGOOD, BP Pulse, ChargePoint, Shell Recharge, Star Charge, EVgo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Public Charging Pile Market Trends and Innovations
Power semiconductor architectures, regulatory efficiency mandates, and fleet procurement models are simultaneously evolving, creating overlapping pressure on equipment design and network deployment strategies.
Silicon carbide MOSFETs are hybridizing rectification and inversion stages within DC fast chargers, enabling 98%+ conversion efficiency at 350 kW output levels. Fleet operators and highway network developers are specifying SiC-based systems for new corridor deployments. This technology convergence is compressing thermal management footprints and reducing cooling system capex by 30-40% relative to IGBT equivalents.
The EU F-Gas Regulation imposes refrigerant phase-down schedules and leakage detection requirements on liquid-cooled charging modules. Equipment manufacturers are redesigning thermal loops to accommodate lower-GWP refrigerants and sealed-system architectures. German and French motorway operators now require F-Gas-compliant certification for new site approvals, accelerating R-410A displacement.
Fleet procurement is consolidating around energy-as-a-service contracts that unbundle hardware ownership from electricity supply and maintenance obligations. Logistics operators prefer opex-based structures that transfer utilization risk to charging network providers. This model is most visible in California and the Netherlands, where electric van deployment targets exceed 50% of new commercial vehicle registrations.
Electric Vehicle Public Charging Pile Market Segmentation
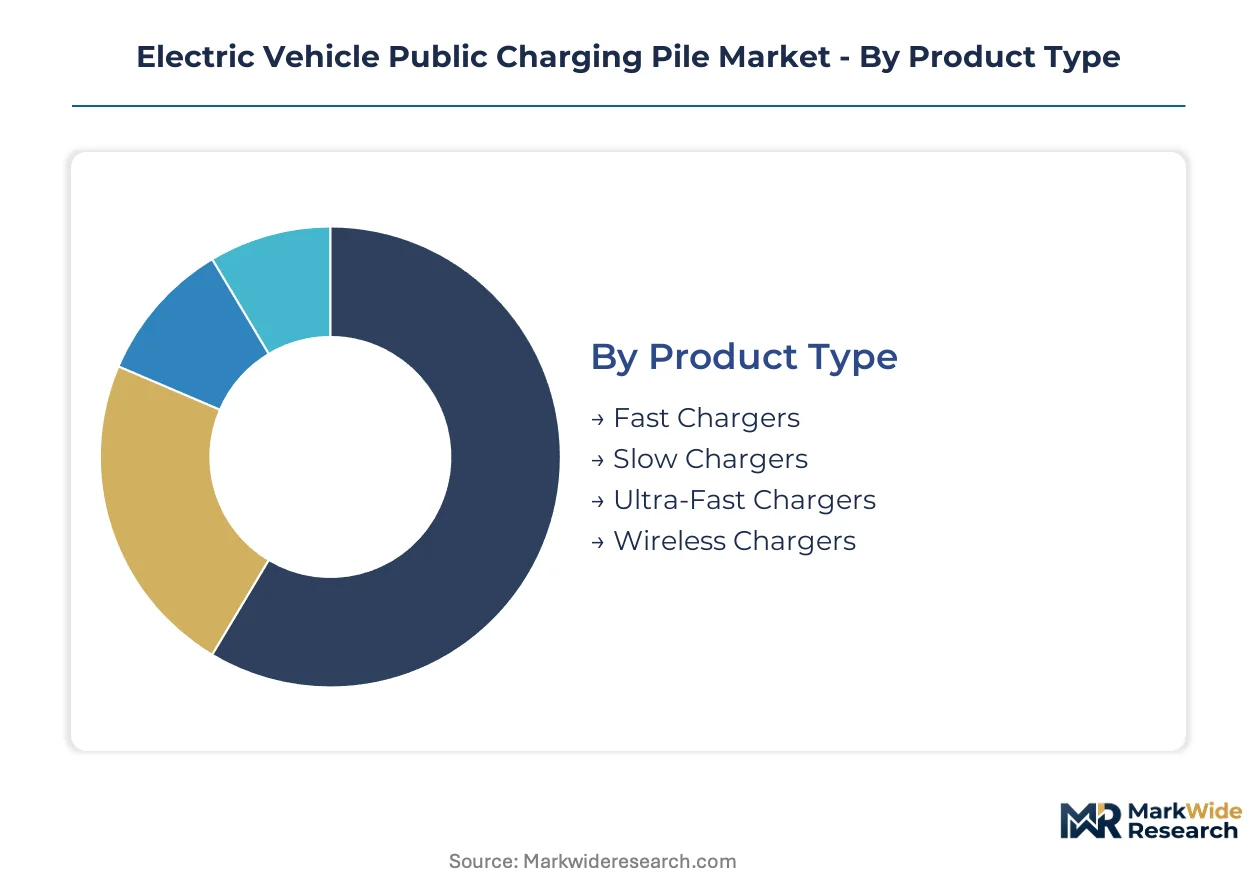
Segmentation in the Electric Vehicle Public Charging Pile Market reveals how power electronics specifications, deployment locations, and user economics fragment procurement patterns. Equipment vendors must align product roadmaps across connector standards, thermal architectures, and utilization models that vary sharply by installation context.
Product Type:
Mature DC hardware dominates highway corridors while emerging wireless architectures struggle with alignment precision and infrastructure cost multiples.
- Fast Chargers:DC systems rated 50-150 kW using liquid-cooled CCS or CHAdeMO connectors serve fleet depots and urban commercial zones where 30-45 minute dwell times align with driver breaks. German motorway operators prioritize these for corridor electrification under EU Green Deal efficiency mandates.
- Slow Chargers:AC units at 3.7-22 kW occupy workplace and residential parking installations where vehicles park for 4-8 hours. Shopping complexes in the Netherlands deploy these to capture dwell-time revenue without demanding grid upgrades.
- Ultra-Fast Chargers:350 kW+ silicon carbide-based systems enable 15-minute replenishment for long-haul commercial transit.
- Wireless Chargers:Inductive pads remain pilot-stage in public settings due to positioning tolerance requirements and capex premiums.
Fast chargers handle the majority of throughput; ultra-fast chargers are expanding most quickly on share.
Technology:
Cost tiers separate legacy AC infrastructure from premium DC architectures with advanced thermal management and power semiconductor content.
- AC Charging:Onboard rectification limits public AC units to 22 kW maximum, constraining deployment to locations with extended parking durations. Office buildings in California specify these for employee benefit programs with 6-8 hour occupancy cycles.
- DC Charging:Offboard power electronics enable 50-350 kW output using silicon carbide MOSFETs that achieve 98%+ conversion efficiency. China's GB/T 27930 protocol standardizes DC communication stacks across domestic manufacturers.
- Inductive Charging:Magnetic resonance systems eliminate connector wear but require precise vehicle alignment and buried infrastructure.
- Conductive Charging:Physical connector interfaces dominate public deployment due to reliability and cost predictability.
DC charging commands the premium tier on equipment margins; inductive systems are climbing the fastest on R&D allocation.
Application:
Volume concentration varies by utilization intensity and grid interconnection feasibility across deployment contexts.
- Commercial Areas:Retail-adjacent installations at 50-150 kW serve mixed-use demand from ride-hail vehicles and consumer EVs. Fleet operators in California negotiate priority access windows at these sites.
- Public Parking:Municipal garages and curbside stations handle sporadic demand with lower utilization rates but higher site count density. Amsterdam's street-level deployment targets 30% of parking spaces by 2030.
- Highway Stations:IONITY and Tesla anchor ultra-high-power corridors across European and North American motorway networks.
- Shopping Complexes:Destination charging at 22-50 kW extends customer dwell time and secondary revenue capture.
- Office Buildings:Workplace charging supports commuter electrification with daytime load profiles that offset peak grid demand.
Highway stations concentrate the highest per-site throughput; commercial areas are gaining share fastest on fleet electrification.
End User:
Customer type determines contract structure, with fleet procurement consolidating around energy-as-a-service models that transfer utilization risk.
- Fleet Operators:Logistics and ride-hail companies specify 150-350 kW DC infrastructure at distribution hubs and highway access points, preferring opex-based contracts that bundle hardware, electricity, and maintenance. California's electric van deployment mandates exceed 50% of new commercial registrations.
- Individual Owners:Consumer demand concentrates at retail and workplace locations where charging coincides with existing activities, accepting slower AC rates for convenience.
- Rental Services:Car-sharing fleets require rapid turnaround infrastructure at urban depots to maximize asset utilization.
- Delivery Providers:Last-mile electric van operators generate concentrated demand for 50-150 kW systems at micro-fulfillment centers.
Fleet operators dominate capital commitment; delivery providers are expanding fastest on e-commerce logistics electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement contracts and highway corridor electrification programs concentrate buyer investment across five national markets. Each geography shapes deployment through distinct regulatory frameworks and industrial clustering patterns.
China
Logistics electrification and state-mandated charging density targets drive procurement volume. MIIT enforces GB/T 27930 communication protocols that standardize domestic equipment interoperability. Shenzhen and Shanghai anchor manufacturing clusters where silicon carbide module production scales for export markets.
Germany
Commercial fleet operators and motorway network operators generate concentrated demand for ultra-high-power infrastructure. The EU F-Gas Regulation imposes refrigerant phase-down schedules on liquid-cooled charging modules. Bavaria hosts equipment testing facilities where manufacturers validate thermal management systems for corridor deployment.
United States
Interstate corridor funding and electric van deployment mandates reshape capital allocation across distribution hubs. NHTSA coordinates with state public utility commissions on electrification funding mechanisms. California's Central Valley logistics corridor concentrates 150-350 kW installations at freight transfer points.
India
Production-linked incentive schemes for advanced chemistry cells create downstream charging infrastructure demand. The Ministry of Heavy Industries channels subsidies through state nodal agencies for highway corridor development. Gujarat's automotive manufacturing belt attracts charging equipment assembly investments from domestic and foreign suppliers.
Netherlands
Urban freight electrification and curbside charging density programs drive municipal procurement. National regulators align building codes with EU Green Deal efficiency benchmarks for public installations. Amsterdam's metropolitan region hosts pilot deployments of bi-directional charging integration with distribution grid services.
Electric Vehicle Public Charging Pile Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Vertically integrated network operators anchor highway corridor deployment through captive site access and bundled energy supply contracts. Component-specialist manufacturers supply power electronics and thermal management subsystems to third-party assemblers. Strategic moves concentrate on silicon carbide sourcing partnerships and multi-standard certification acceleration to compress product launch timelines.
Within the network-operator archetype, Tesla and IONITY occupy positions defined by proprietary connector ecosystems and motorway site density. ChargePoint represents the hardware-software integration specialist tier. TGOOD sits among Chinese equipment fabricators supplying domestic and export markets with GB/T-compliant systems.
| Leading Market Players |
|---|
| Electrify America |
| IONITY |
| Tesla |
| TGOOD |
| BP Pulse |
| ChargePoint |
| Shell Recharge |
| Star Charge |
| EVgo |
| Others |
Pricing and Supply Chain Analysis
Copper and rare-earth volatility from Chilean mining and Chinese processing clusters compresses margin buffers across liquid-cooled cable assemblies and silicon carbide power modules, forcing tiered equipment pricing that separates premium SiC-based systems from legacy IGBT alternatives while concentrating procurement leverage with vertically integrated network operators.
Pricing Analysis
Cost-plus contracts with copper and silicon carbide indexation dominate fleet procurement agreements for 150-350 kW DC infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled SiC systems from air-cooled IGBT hardware and basic AC workplace units. Pricing pressure stems from commodity input volatility and extended utility interconnection timelines that freeze capital deployment. Fleet operators exhibit lowest price sensitivity due to energy-as-a-service contract preferences, while municipal curbside programs face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on wide-bandgap semiconductor manufacturing equipment limit silicon carbide substrate and MOSFET flows from United States and Japanese suppliers to Chinese equipment fabricators. Power electronics sourcing concentrates in China, Germany, and Japan for GB/T, CCS, and CHAdeMO connector variants. Liquid-cooled cable assemblies draw from Chilean copper and Chinese rare-earth processing for high-frequency magnetics. Single-source vulnerability in SiC wafer supply creates chokepoint exposure. Distribution runs through captive network-operator procurement channels and third-party equipment assemblers serving regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where site density and proprietary connector ecosystems create switching costs that entrench early movers against late-arriving competitors.
For Market Incumbents: Entrench position by accelerating silicon carbide sourcing partnerships with Japanese and German substrate suppliers before export-control tightening restricts equipment flows. Deepen backward integration into power module assembly to capture margin compression from commodity volatility. Defend against emerging Chinese equipment fabricators by securing exclusive corridor site access through bundled energy supply contracts with German and California motorway operators.
For New Entrants and Emerging Players: Secondary interstate routes in the United States and rural expressways in China's western provinces represent the most penetrable entry points given underinvestment relative to primary motorway density. India's PLI-linked advanced chemistry cell manufacturing belt offers white-space demand for compatible fast-charging infrastructure as domestic automotive electrification accelerates. Pursue joint-venture structures with state nodal agencies to secure subsidized site development capital.
For Investors and Strategic Acquirers: The market sits at an infrastructure-deployment phase that favors vertically integrated network operators with captive site portfolios and software-hardware integration capabilities. Long-term viability hinges on bi-directional V2G revenue stream maturation and grid services market development. Monitor utility tariff redesigns and interconnection queue clearance rates as inflection indicators for capital deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Sourcing Partnership | Secures substrate supply from Japanese and German suppliers ahead of tightening export controls. |
| Bi-Directional Charging Certification | Unlocks grid services revenue from frequency regulation under EU Green Deal mandates. |
| Highway Corridor Site Acquisition | Captures exclusive motorway access points along German autobahn and US interstate networks. |
| Multi-Standard Connector Integration | Reduces certification fragmentation across CCS, CHAdeMO, and GB/T variants for faster launches. |
| Energy-as-a-Service Platform Launch | Transfers utilization risk from California fleet operators to network provider balance sheets. |
Research Methodology
Operator-level perspectives from charging network procurement directors, fleet electrification managers, utility interconnection planners, and power electronics engineers anchored the qualitative base. These primary insights combined with secondary validation from NHTSA corridor funding disclosures, MIIT GB/T protocol documentation, EU F-Gas Regulation filings, and state public utility commission rate-case records. Bottom-up equipment shipment tallies and top-down infrastructure investment flows were triangulated to establish market sizing.
Scenario-bracketing around commodity price bands and interconnection timeline distributions shaped the analytical framework across the analysis window. Segmentation dimensions modeled include power rating tiers, connector standard variants, thermal management architectures, deployment location types, and end-user contract structures. CAGRs were derived from installed base growth trajectories and per-site throughput assumptions. Forecast inputs incorporated silicon carbide adoption curves and fleet electrification mandates from California and the Netherlands.
Practitioners should monitor copper and rare-earth price volatility, utility interconnection queue clearance rates, and export-control regime adjustments for early signals of forecast deviation. Forecasts reflect assumptions about sustained fleet electrification commitments and corridor funding continuity. Material shifts in F-Gas Regulation enforcement stringency or GB/T protocol revision timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
North America Electric Vehicle Charging Station Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Electric Vehicle Home Charger Market