
 Hybrid Composites Market | 2026-2036
Hybrid Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Composites Market Intelligence
REACH is pivoting the European hybrid composites sector toward bio-based resin systems and closed-loop fiber recovery. Hexcel Corporation leverages its Salt Lake City autoclave network to dominate aerospace prepreg supply. Toray Industries anchors Japanese carbon fiber capacity while competing in thermoplastic unidirectional tape for automotive structural components.
Hybrid composites combine two or more discontinuous or continuous reinforcement fibers within a unified polymer matrix, typically achieving specific strength above 300 MPa and tailored damping coefficients through controlled fiber orientation. These engineered materials primarily serve industries requiring simultaneous weight reduction and load-bearing performance. Thermoplastic hybrid composites are displacing thermoset equivalents in automotive crash structures due to faster cycle times and recyclability, while resin matrix formulations concentrate margin pools among specialty chemical suppliers. Fiber reinforcement architectures lead aerospace application value, with carbon-glass hybrids capturing structural component demand across Boeing and Airbus tier-one supply chains.
FAA airworthiness directives and EASA certification standards govern material qualification timelines for aerospace-grade hybrid laminates, extending development cycles but creating durable supplier lock-in. EPA industrial emissions guidelines and OSHA workplace exposure limits for styrene in open-mold processes are compressing hand layup capacity in North American manufacturing. Stakeholders must monitor regulatory convergence between automotive crash safety mandates and circular economy packaging requirements, as these frameworks increasingly dictate resin chemistry selection and end-of-life fiber recovery economics.
Market Dynamics
REACH compliance deadlines are forcing European manufacturers to abandon conventional epoxy systems and adopt bio-based resin formulations, compressing formulation development cycles while fragmenting supplier tiers between specialty chemical incumbents and biopolymer challengers.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Construction material specifications across Germany, France, and the Netherlands now mandate lifecycle carbon accounting. This accelerates hybrid composite substitution for steel and aluminum in structural applications.
- Thermoplastic unidirectional tape technology:Automotive OEMs in Germany's Stuttgart corridor deploy in-situ consolidation processes. Cycle times drop below 90 seconds versus 20-minute thermoset cures.
- Carbon-glass hybrid laminates:Aerospace tier-one suppliers qualify these materials for fuselage panels and wing skins. Boeing and Airbus specification releases drive qualification investments across the supply base.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock markets. Margin compression hits mid-tier prepreg manufacturers without backward integration into precursor production.
- Japanese carbon fiber concentration:Toray Industries, Mitsubishi Chemical, and Teijin control 70% of global PAN-based carbon fiber capacity. Supply disruptions from any single facility cascade through aerospace qualification chains.
- Styrene emissions compliance:OSHA workplace exposure limits and EPA industrial emissions guidelines force North American open-mold operations into costly ventilation upgrades or process abandonment.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic manufacturing incentives target aerospace and automotive component production. Local hybrid composite fabrication capacity remains underdeveloped relative to projected demand.
- Closed-loop fiber recovery systems:Pyrolysis and solvolysis technologies mature for carbon fiber reclamation. EU circular economy packaging requirements create mandated offtake agreements for recovered reinforcement.
- Wind turbine blade recycling mandates:Germany's KBA and Denmark's environmental agency advance end-of-life regulations. Hybrid composite blade designs with separable fiber architectures gain regulatory preference.
Industry Challenges
- FAA-EASA certification timeline compression:Aerospace material qualification cycles extend 18-36 months. Concurrent certification demands strain engineering resources at tier-two prepreg suppliers.
- Autoclave capacity scarcity:Large-diameter pressure vessel availability concentrates in Salt Lake City and Toulouse industrial corridors. New aerospace program ramp rates exceed installed thermal processing capacity.
- Multi-material joining expertise gaps:Adhesive selection and surface preparation for hybrid composite-to-metal interfaces require specialized process engineering. Workforce development lags behind production scale-up requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Composites Market |
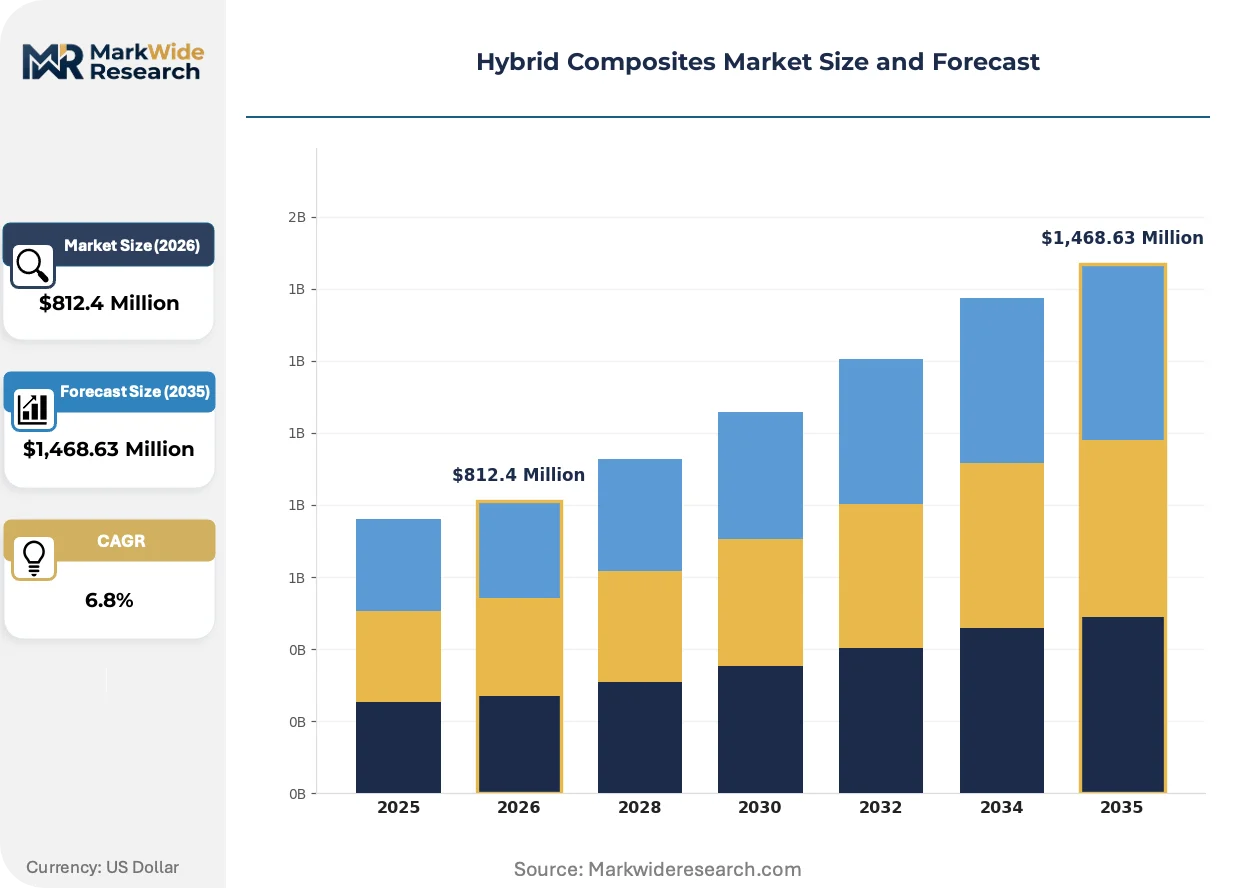
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,468.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoset, Thermoplastic, Resin Matrix, Fiber Reinforcement End User: Aerospace, Automotive, Marine, Construction Application: Structural Components, Engine Parts, Interior Features, Safety Equipment Manufacturing Process: Injection Molding, Compression Molding, Filament Winding, Hand Layup |
| Companies Covered | Hexcel Corporation, Toray Industries, Teijin Limited, SGL Carbon, LANXESS, DSM, Solvay, Gurit, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Composites Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry mandates are converging to reshape manufacturing processes across aerospace, automotive, and construction end-uses. Three distinct vectors dominate competitive positioning.
Electro-thermoplastic composite welding systems are electrifying assembly line economics for automotive structural components. BMW and Volkswagen production engineers deploy resistive implant welding for A-pillar and B-pillar reinforcements. This eliminates mechanical fastening and adhesive curing stations, compressing floor space requirements by 40% while enabling in-line recycling of production scrap.
REACH Annex XIV authorization lists now restrict bisphenol A diglycidyl ether in consumer-facing applications. German automotive suppliers accelerate substitution with bio-epoxy formulations derived from lignin and plant-based polyols. Formulation houses in Ludwigshafen and Leverkusen reallocate R&D capacity toward USDA BioPreferred certification pathways.
Consolidated procurement specifications from Airbus and Boeing tier-one suppliers now mandate digital thread traceability from fiber spool to finished component. Suppliers without AS9100D-compliant ERP integration face exclusion from qualified vendor lists. This behavioral shift concentrates contract awards among mid-cap specialists with captive MES deployments in Toulouse and Hamburg industrial zones.
Hybrid Composites Market Segmentation
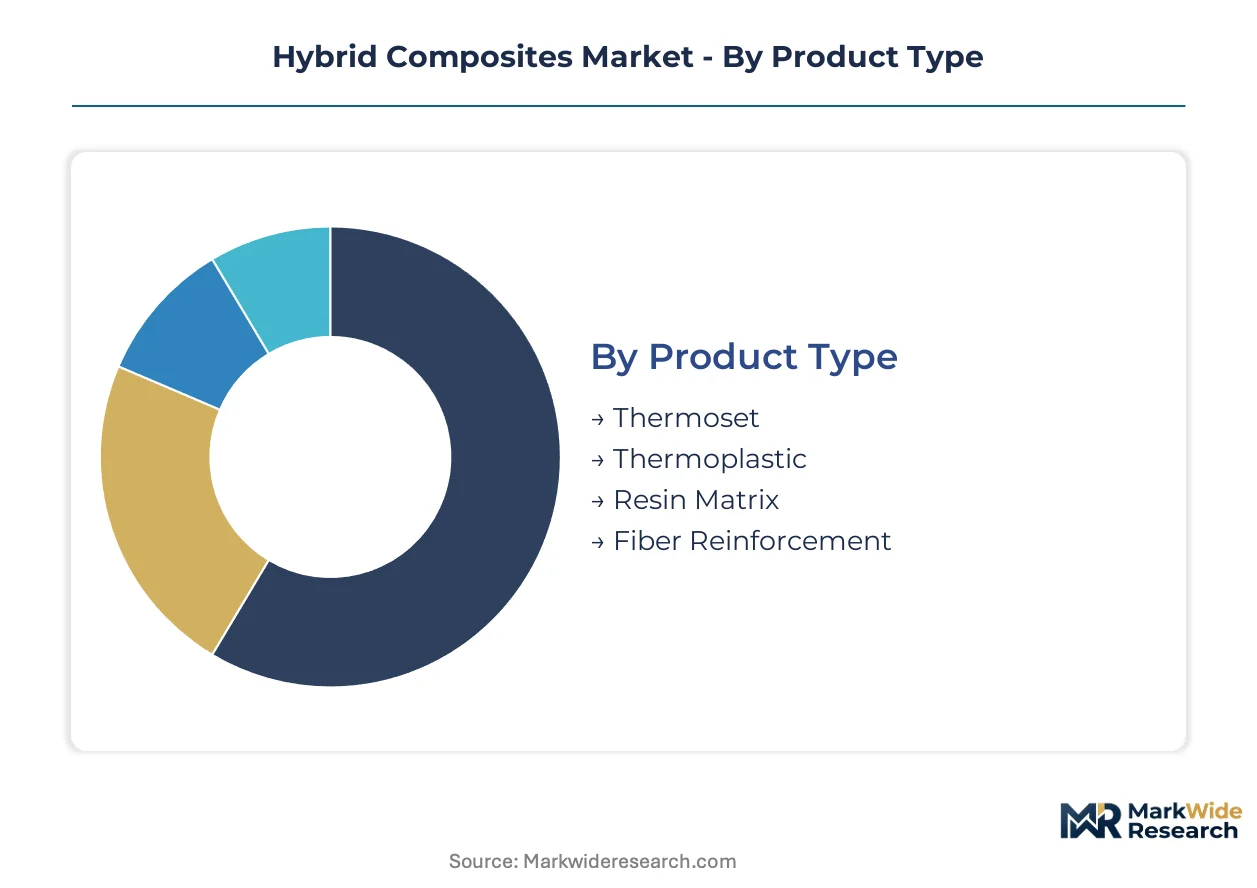
Hybrid composites serve radically different performance requirements across end-uses. Material selection hinges on thermal stability demands, production volume economics, and regulatory compliance pathways rather than cost alone.
Product Type:
Thermoset formulations dominate standalone structural applications, while thermoplastic systems embed into high-throughput automotive platforms requiring crash recyclability.
- Thermoset:Epoxy and vinyl ester matrices achieve glass transition temperatures above 180°C. Airbus A350 wing spars and Boeing 787 pressure bulkheads specify thermoset carbon-glass hybrids for fatigue resistance under cyclic loading. REACH Annex XIV restrictions on conventional epoxy precursors are accelerating bio-based formulation development among German specialty chemical suppliers.
- Thermoplastic:Polyamide and PEEK matrices enable sub-90-second molding cycles. BMW's Leipzig and Spartanburg plants deploy in-situ consolidated unidirectional tape for A-pillar reinforcements, eliminating autoclave bottlenecks. End-of-life recyclability aligns with EU circular economy packaging mandates for automotive components.
- Resin Matrix:Bio-epoxy systems derived from lignin and plant-based polyols gain USDA BioPreferred certification traction among Stuttgart corridor suppliers.
- Fiber Reinforcement:Carbon-glass hybrid architectures balance cost and specific strength for aerospace qualification pathways.
Thermoset leads volumes today; thermoplastic is gaining share fastest.
End User:
Customer procurement specifications diverge sharply on certification burden, volume scale, and material traceability requirements.
- Aerospace:FAA-EASA concurrent qualification demands 18-36 month material approval cycles. Boeing and Airbus tier-one suppliers mandate AS9100D-compliant digital thread traceability from fiber spool to finished fuselage panel. Carbon-glass hybrid laminates capture primary structural applications where specific strength exceeds 300 MPa.
- Automotive:Crash safety mandates from Germany's KBA and NHTSA drive thermoplastic adoption for energy-absorbing structures. Volkswagen's Wolfsburg and Chattanooga plants specify hybrid composite B-pillars achieving 40% weight reduction versus high-strength steel.
- Marine:OSHA styrene exposure limits compress open-mold hand layup capacity in US Gulf Coast shipyards.
- Construction:EU Green Deal embodied carbon thresholds accelerate hybrid composite substitution for steel reinforcement in German and Dutch infrastructure projects.
Automotive leads volumes today; construction is gaining share fastest.
Application:
Functional performance requirements determine fiber architecture selection and manufacturing process pairing.
- Structural Components:Primary load-bearing applications specify continuous fiber unidirectional or woven architectures. Wing skins and fuselage panels require 0°/90°/±45° quasi-isotropic layups certified to FAA airworthiness directives.
- Engine Parts:Thermal management demands drive ceramic matrix hybrid development for turbine shrouds and exhaust nozzles.
- Interior Features:Germany's BfArM and FAA flammability standards govern cabin panel resin selection. Phenolic and thermoplastic matrices displace thermoset equivalents for smoke toxicity compliance.
- Safety Equipment:Crash-optimized hybrid composites absorb impact energy through controlled fiber delamination and matrix plasticization.
Structural components lead volumes today; safety equipment is gaining share fastest.
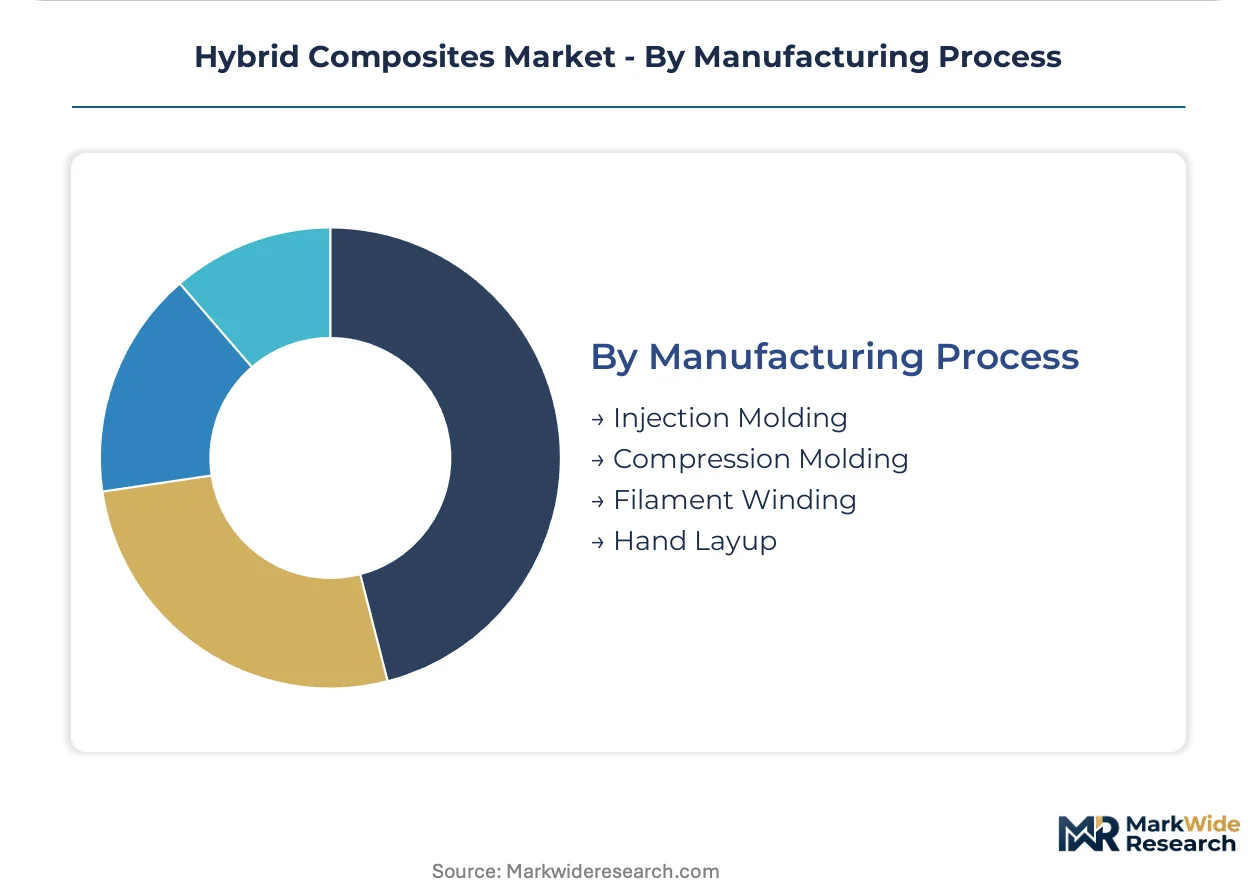
Manufacturing Process:
Capital intensity and cycle time economics stratify process selection across volume tiers and part complexity.
- Injection Molding:Discontinuous fiber-reinforced thermoplastic compounds achieve automotive interior component cycle times below 60 seconds. BMW's Landshut plant deploys multi-material injection molding for hybrid composite-metal hybrid instrument carriers.
- Compression Molding:Sheet molding compound and bulk molding compound processes serve medium-volume structural applications. Volkswagen's Braunschweig facility processes glass-carbon hybrid prepregs for underbody shields requiring stone impact resistance.
- Filament Winding:Automated fiber placement dominates pressure vessel and pipe applications requiring hoop strength.
- Hand Layup:OSHA workplace exposure limits and EPA industrial emissions guidelines force North American open-mold operations into costly ventilation upgrades or process abandonment.
Injection molding leads volumes today; compression molding is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized autoclave technicians and composite process engineers cluster in aerospace manufacturing corridors across Germany, the United States, Japan, China, and India. These talent concentrations anchor regional supply bases for hybrid composite fabrication.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive thermoplastic hybrid composite demand for structural reinforcements. EU Green Deal embodied carbon thresholds mandate lifecycle accounting for construction materials. The Munich aerospace cluster supplies carbon-glass hybrid laminates to Airbus tier-one suppliers under EASA certification protocols.
United States
Boeing specification releases accelerate qualification investments for fuselage panel applications. FAA airworthiness directives govern 18-36 month material approval timelines for aerospace-grade hybrids. Hexcel Corporation's Salt Lake City autoclave network dominates aerospace prepreg supply to Pacific Northwest manufacturing.
Japan
Toray Industries, Mitsubishi Chemical, and Teijin control PAN-based carbon fiber precursor capacity serving global qualification chains. METI industrial policy supports advanced materials R&D consortiums. The Nagoya aerospace corridor concentrates fiber placement expertise for wing skin fabrication.
China
Domestic wind turbine OEMs source hybrid composite blade architectures for separable fiber end-of-life designs. MIIT dual carbon goals accelerate substitution of steel reinforcement in infrastructure applications. The Yangtze River Delta hosts emerging prepreg manufacturing serving COMAC qualification pathways.
India
PLI scheme incentives target aerospace and automotive component production with underdeveloped local fabrication capacity relative to projected demand. DGFT import substitution policies favor domestic resin formulation development. The Bangalore-Hyderabad corridor attracts tier-two prepreg suppliers establishing technical service operations.
Hybrid Composites Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across resin matrix, fiber reinforcement, and composite fabrication value chain positions. The market structure concentrates upstream carbon fiber capacity among Japanese chemical conglomerates while fragmenting midstream prepreg supply among regional specialists. Three archetypes dominate: backward-integrated fiber producers, formulation-focused resin suppliers, and process-technology fabricators. Competitive moves center on captive fiber supply agreements and thermoplastic welding technology licensing.
Among Japanese fiber producers, Toray Industries and Teijin Limited exemplify upstream concentration archetypes with captive PAN precursor operations. Hexcel Corporation represents the aerospace prepreg specialist model with autoclave network control. European chemical conglomerates including Solvay and LANXESS occupy resin matrix formulation positions serving multiple end-use qualification pathways.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Industries |
| Teijin Limited |
| SGL Carbon |
| LANXESS |
| DSM |
| Solvay |
| Gurit |
| Avient Corporation |
| Others |
Cost & Logistics Intelligence
Aerospace-grade certification tiers bifurcate the hybrid composites market into premium qualified supply and commodity-grade alternatives, with this divergence manifesting in both pricing power concentration among autoclave-network operators and supply chain fragmentation between resin formulators and fiber producers.
Pricing Analysis
Bundle-unbundle splits separate material supply from technical service and qualification support. Three-tier pricing structure across aerospace-qualified, automotive-performance, and industrial-commodity levels tracks certification burden and fiber architecture complexity. Price differentiation centers on EASA-FAA qualification status and captive fiber supply agreements. Pricing pressure stems from acrylonitrile feedstock volatility hitting mid-tier prepreg manufacturers without backward integration into PAN precursor production. Automotive OEMs exhibit highest price sensitivity due to thermoplastic substitution options, while aerospace tier-one suppliers accept premiums for qualified vendor list security.
Supply Chain Analysis
Carbon fiber precursor supply rests on Japanese chemical conglomerates in Nagoya and Oita prefectures, with Toray Industries, Mitsubishi Chemical, and Teijin anchoring global PAN-based capacity. Raw material dependencies include acrylonitrile monomer, lignin-derived bio-epoxy feedstocks, and high-modulus glass fiber rovings. Single-source vulnerability concentrates in aerospace-grade carbon fiber qualification chains, where EASA certification locks create switching costs exceeding 18-month timeline investments. Distribution runs through qualified prepreg converters in Salt Lake City, Toulouse, and Hamburg industrial corridors serving Boeing and Airbus tier-one networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal embodied carbon thresholds and REACH Annex XIV chemistry mandates accelerate demand for compliant material systems.
For Market Incumbents: Deploy autoclave network control as the defensive anchor. Hexcel Corporation's Salt Lake City thermal processing concentration exemplifies capacity moat construction against emerging thermoplastic challengers. Secure backward integration into PAN precursor supply or captive fiber offtake agreements with Japanese producers to defend margin position against acrylonitrile volatility. Accelerate AS9100D-compliant digital thread traceability investments to maintain qualified vendor list status as Airbus and Boeing consolidate procurement specifications. For New Entrants and Emerging Players: India's domestic automotive component fabricators represent an underserved buyer archetype with PLI scheme incentives but limited local hybrid composite technical service infrastructure. Establish technical service operations in the Bangalore-Hyderabad corridor targeting tier-two aerospace suppliers and wind turbine OEMs seeking separable fiber blade architectures. License electro-thermoplastic welding technology from European automotive equipment specialists to bypass autoclave capital barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier prepreg suppliers lack captive fiber supply and struggle with concurrent FAA-EASA qualification timeline compression. Frame long-term viability around regulatory chemistry mandates tightening through the analysis window, favoring bio-based resin formulators and closed-loop fiber recovery technology providers. Target acquisition candidates among German specialty chemical houses with USDA BioPreferred certification progress and Ludwigshafen-Leverkusen R&D infrastructure. Watch EASA airworthiness directive releases for Boeing and Airbus new program specifications as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Mitigates acrylonitrile price volatility exposure for aerospace prepreg manufacturers. |
| Electro-Thermoplastic Welding Technology Licensing | Enables sub-90-second automotive structural component assembly without autoclave bottlenecks. |
| Closed-Loop Fiber Recovery System Deployment | Positions suppliers for EU circular economy packaging mandate compliance and mandated offtake agreements. |
| AS9100D Digital Thread Traceability Investment | Secures qualified vendor list status under Airbus-Boeing consolidated procurement specifications. |
| Bio-Epoxy Formulation Certification | Aligns resin matrix supply with REACH Annex XIV restrictions and USDA BioPreferred pathways. |
Research Approach
Bottom-up aerospace-automotive-construction end-use modeling reconciled against top-down carbon fiber-prepreg-resin supply tracking forms the analytical core of this study. Primary interviews with tier-one aerospace procurement directors, automotive platform engineers at Stuttgart and Wolfsburg OEMs, construction materials specification consultants, and specialty chemical R&D directors in Ludwigshafen and Leverkusen were cross-validated against secondary sources including EASA certification databases, FAA airworthiness directive filings, EU Green Deal implementation guidance, and customs trade data for carbon fiber and precursor flows.
Input-output matrices mapped fiber reinforcement architecture selection to manufacturing process economics across thermoset and thermoplastic matrix categories, with segmentation dimensions covering product type, end-user industry, application function, and manufacturing process capital intensity. CAGRs were derived from production volume build-ups by end-use, adjusted for qualification timeline constraints and regulatory chemistry transition assumptions. Forecast inputs incorporated EU embodied carbon threshold implementation schedules and India's PLI scheme incentive disbursement patterns.
Inputs from EASA-FAA certification timelines and REACH Annex XIV authorization lists were available through the study window; gaps in proprietary prepreg pricing data and long-term carbon fiber supply contract terms introduce uncertainty bands around aerospace segment projections. Forecasts reflect assumptions regarding thermoplastic substitution rates in automotive crash structures and bio-based resin formulation maturation timelines. Regulatory chemistry mandate acceleration, Japanese carbon fiber facility disruptions, and concurrent qualification demand surges for new aerospace programs warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Transportation Composites Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Composite Rollers Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Global Geocomposites Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Composite Cans Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Plastic Composites Market
Composite Materials
Composite Market
Composite Materials
Phenolic Panel Market
Composite Materials
Composite Coatings Market
Composite Materials
Aramid Fiber Reinforced Polymer Market