

High Frequency High Speed Copper Clad Laminate CCL Market Size, Share, and Industry Trends Forecast 2026-2036
High Frequency High Speed Copper Clad Laminate CCL Market Insights
Telecom equipment makers is unwinding legacy procurement patterns from consumer electronics assemblers toward dedicated high-frequency laminate suppliers. Panasonic Holdings leverages vertical integration into resin synthesis and copper foil treatment to secure formulation control. Shengyi Technology anchors volume production across multi-layer FR4 and modified epoxy platforms for base station antenna boards. Isola Group differentiates through hydrocarbon and thermoset formulations targeting millimeter-wave thresholds.
High frequency high speed copper clad laminate CCL denotes a composite substrate bonding copper foil to dielectric layers engineered for signal integrity above 10 GHz, with dissipation factors below 0.003 and dielectric constants ranging 2.2 to 4.5 depending on resin system. These laminates enable printed circuit boards that carry microwave and RF signals without excessive attenuation or skew distortion. PTFE and ceramic-filled laminates command premium positioning where aerospace electronics and satellite systems require thermal stability across orbital temperature swings. Low-loss technology segments attract fastest capacity expansion as 5G infrastructure deployments scale Massive MIMO antenna arrays. Module manufacturers represent a concentrated margin pool, since their qualification cycles lock in multi-year supply agreements with certified laminate sources.
FCC spectrum allocations in the United States and MIIT equipment certification rules in China jointly shape laminate performance benchmarks by mandating specific loss tolerances at licensed frequency bands. REACH chemical restrictions in Europe and halogen-free directives from ECHA constrain brominated flame retardant formulations, pushing resin suppliers toward phosphorus-based or inorganic filler alternatives. Stakeholders must monitor evolving base station power density requirements and satellite constellation launch schedules to align capacity investments with qualified material platforms.
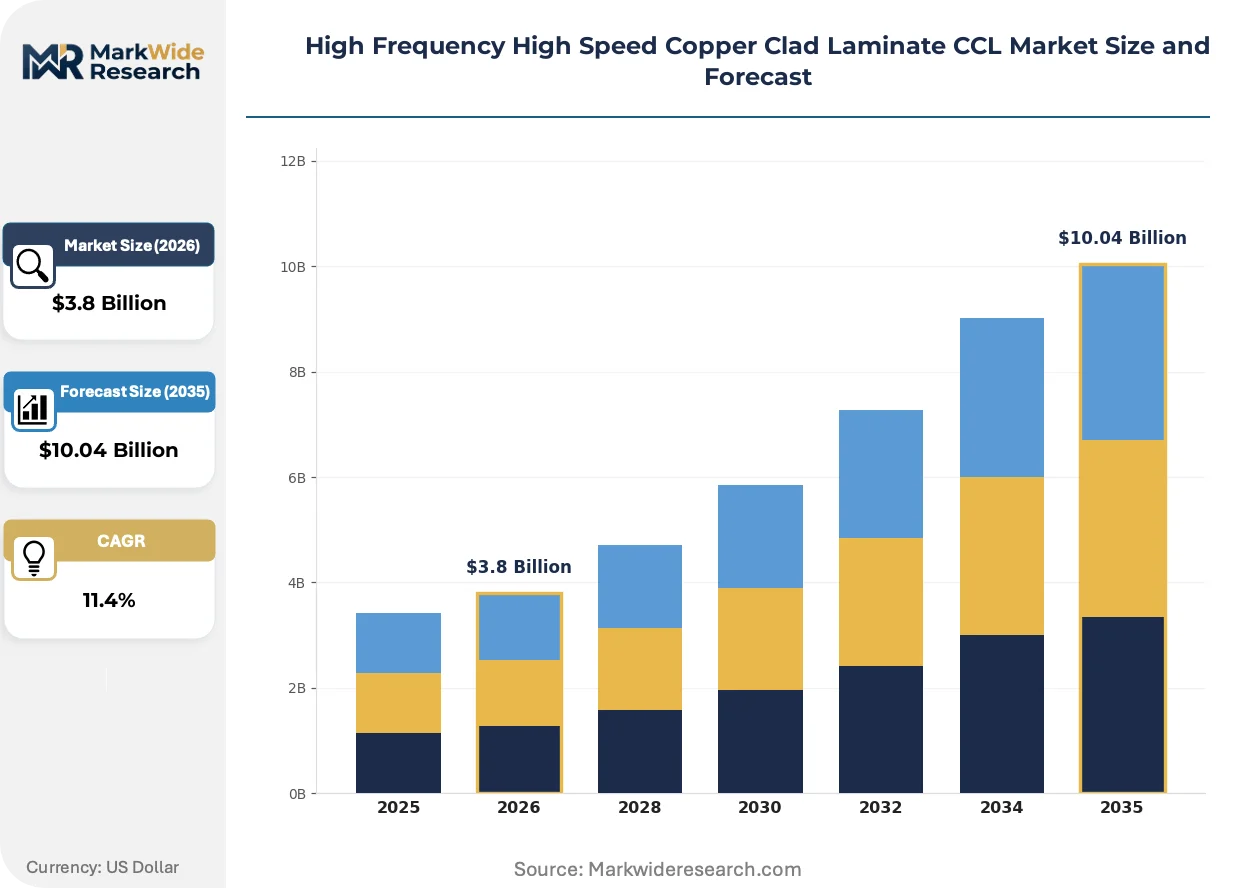
Market Dynamics
The 5G Massive MIMO rollout is compressing laminate qualification cycles from 24 months to 12 months, forcing resin suppliers to accelerate formulation validation while telecom OEMs lock in multi-source agreements before base station deployment peaks.
Growth Catalysts
- MIIT equipment certification rules:China's mandatory loss tolerance benchmarks at licensed millimeter-wave bands are pulling domestic laminate consumption away from import-dependent supply chains toward qualified local sources.
- Low-loss hydrocarbon formulations:These resin systems enable printed circuit boards operating above 28 GHz with dissipation factors below 0.002, satisfying FCC spectrum allocations for dense urban 5G coverage.
- East Asian manufacturing clusters:Concentrated PCB fabrication capacity across Japan, Taiwan, and South Korea creates localized demand pull that reduces logistics friction for high-frequency material shipments.
Market Restraints
- Copper foil supply concentration:Japanese and Taiwanese foil treatment specialists control 70% of ultra-low-profile surface finishes, exposing laminate makers to input bottlenecks during capacity expansions.
- PTFE resin cost volatility:Fluoropolymer feedstock prices fluctuate with refrigerant market cycles, compressing margins on ceramic-filled laminates for satellite thermal management applications.
- REACH chemical restrictions:ECHA halogen-free directives are constraining brominated flame retardant formulations, forcing costly reformulation cycles before European base station deployments.
Strategic Opportunities
- India telecom infrastructure:TRAI spectrum auction schedules and domestic equipment mandates are opening qualified-supplier positions for laminate makers with BIS certification pathways.
- LEO satellite constellation thermal management:Orbital temperature swing requirements are creating specification pull for ceramic-PTFE hybrids that stabilize dielectric constants across -150°C to +120°C operational envelopes.
- Phosphorus-based flame retardant convergence:Cross-industry alignment between PCB laminates and electric vehicle battery enclosures is enabling shared R&D cost pools for non-halogen resin chemistry.
Industry Challenges
- RF simulation talent scarcity:Electromagnetic modeling expertise for stack-up optimization above 10 GHz concentrates within aerospace defense contractors, limiting laminate makers' in-house design-support capabilities.
- Multi-year qualification timelines:Telecom OEM certification protocols require 18-36 months of thermal cycling and humidity bias testing before volume procurement authorization, freezing out unproven formulations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Frequency High Speed Copper Clad Laminate CCL Market Trends and Innovations
Material science advances are collapsing the performance gap between premium fluoropolymer laminates and modified epoxy systems, redistributing value capture across the supply chain as mid-tier suppliers qualify for historically guarded application segments.
Ceramic-filled thermoset composites are supplanting pure PTFE laminates in sub-6 GHz 5G infrastructure. These materials deliver dielectric constants of 3.0-3.5 with mechanical properties compatible with standard FR4 processing equipment. Base station antenna board manufacturers in Taiwan and South Korea are adopting them at scale to avoid specialized drilling and plating workflows. This substitution is compressing equipment investment requirements for laminate converters and expanding the qualified supplier base beyond fluoropolymer specialists.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon feedstocks used in traditional PTFE synthesis. Resin suppliers are responding with modified polymerization processes that reduce fluorinated content while preserving dielectric performance. European laminate distributors report 8-12 month lead time extensions as formulation transitions ripple through qualified material lists, pushing procurement teams toward alternative chemistries with established supply chains.
Antenna module manufacturers are consolidating vendor panels from 12-15 qualified laminate sources to 4-6 strategic partners with captive resin synthesis and foil treatment capabilities. This concentration reflects risk management priorities after pandemic-era supply disruptions exposed fragility in multi-tier sourcing models. China's MIIT domestic substitution mandates accelerate this pattern, as state-backed equipment tenders require primary material provenance documentation that favors vertically integrated suppliers with in-house polymer production.
High Frequency High Speed Copper Clad Laminate CCL Market Segmentation
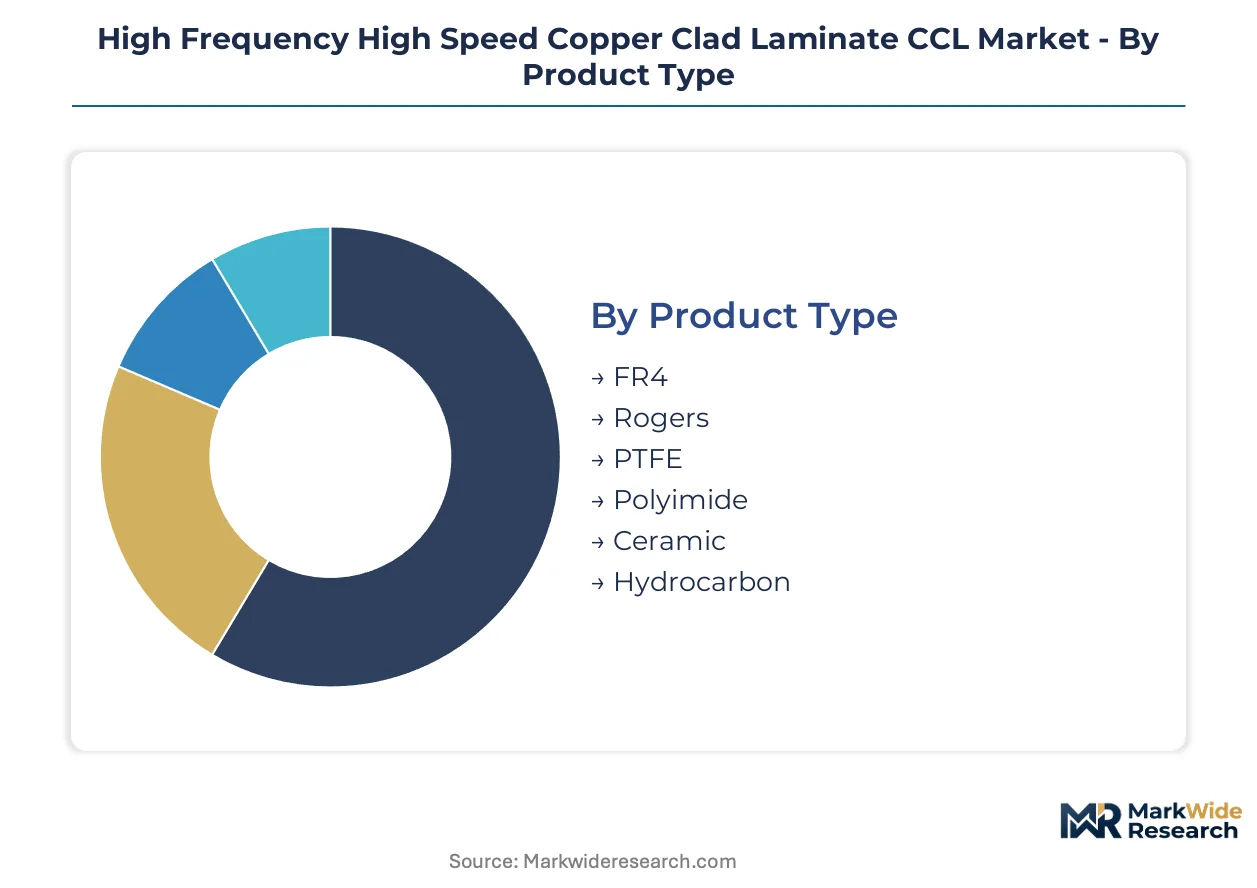
Segmentation in high-frequency CCL markets traces how material specifications cascade through qualification hierarchies. Each dimension—product chemistry, signal integrity technology, application performance tier, and end-user procurement authority—creates distinct margin bands and certification barriers.
Product Type:
Channel flows split between standardized epoxy platforms serving high-volume antenna board producers and fluoropolymer specialists feeding aerospace qualification programs.
- PTFE:Fluoropolymer resin systems deliver dissipation factors below 0.002 and thermal stability from -150°C to +120°C. Demand concentrates in satellite thermal management applications where orbital temperature swings mandate dielectric consistency. ECHA F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon feedstocks, extending European lead times.
- Hydrocarbon:These thermoset formulations enable millimeter-wave operation above 28 GHz with mechanical properties compatible with standard FR4 processing equipment. Base station antenna board manufacturers in Taiwan and South Korea are adopting them at scale to avoid specialized drilling workflows.
- FR4:Modified epoxy platforms anchor volume production for sub-6 GHz infrastructure where loss tolerances permit higher dissipation factors.
- Rogers:Branded ceramic-filled laminates occupy mid-tier positioning between commodity epoxy and premium fluoropolymer systems.
- Polyimide:High-temperature stability suits flexible circuit applications in aerospace electronics with severe thermal cycling requirements.
- Ceramic:Filler-enhanced composites stabilize dielectric constants across temperature ranges for RF filter applications.
By volume, FR4 leads. By growth pace, hydrocarbon formulations are expanding most quickly.
Technology:
Cost tiers separate qualification-grade laminates commanding multi-year supply agreements from commodity materials subject to spot-market volatility.
- Low Loss:Dissipation factors below 0.003 enable signal integrity above 10 GHz for Massive MIMO antenna arrays. Procurement concentrates among telecom equipment makers in East Asian manufacturing clusters.
- Low Dielectric Constant:Values ranging 2.2 to 3.5 minimize signal propagation delay for high-speed digital backplanes. FCC spectrum allocations at licensed millimeter-wave bands mandate specific performance thresholds.
- High Tg:Glass transition temperatures above 170°C support lead-free soldering processes in automotive radar modules.
- Halogen-Free:Phosphorus-based flame retardant chemistry satisfies REACH chemical restrictions and ECHA directives constraining brominated formulations.
- Thermoset:Cross-linked polymer structures provide dimensional stability for multi-layer board fabrication.
- Thermoplastic:Melt-processable systems enable reworkability for prototype development and low-volume aerospace applications.
By commercial concentration, low loss dominates procurement volumes. By specification intensity, low dielectric constant commands premium positioning.
Application:
Customer type determines channel structure, with defense contractors routing through qualified supplier programs while wireless device assemblers access distribution channels.
- 5G Infrastructure:Massive MIMO deployment is compressing laminate qualification cycles from 24 months to 12 months. MIIT equipment certification rules in China are pulling consumption toward domestic qualified sources.
- Satellite Systems:LEO constellation thermal management requirements create specification pull for ceramic-PTFE hybrids. Orbital temperature swing tolerances mandate dielectric stability across extreme operational envelopes.
- Aerospace Electronics:Military and commercial aviation applications require traceable material provenance and extended thermal cycling documentation.
- RF Modules:Concentrated margin pools exist here since qualification cycles lock in multi-year supply agreements with certified laminate sources.
- Military Communications:Secure supply chain requirements favor vertically integrated suppliers with captive resin synthesis capabilities.
- Wireless Devices:Consumer electronics applications prioritize cost optimization over extreme performance specifications.
By deployment scale, 5G infrastructure leads. By technical barrier height, satellite systems are climbing the fastest.
End User:
Supply concentration varies by procurement authority, with module manufacturers consolidating vendor panels while electronic assemblers maintain broader sourcing flexibility.
- Module Manufacturers:These stakeholders represent concentrated margin pools. Their 18-36 month qualification protocols require thermal cycling and humidity bias testing before volume procurement authorization.
- Telecom Equipment Makers:Unwinding legacy procurement patterns from consumer electronics assemblers toward dedicated high-frequency laminate suppliers. Multi-source agreements are locking in before base station deployment peaks.
- OEMs:Original equipment manufacturers specify laminate grades but often delegate procurement to contract manufacturers.
- Defense Contractors:Electromagnetic modeling expertise for stack-up optimization above 10 GHz concentrates within these entities, limiting laminate makers' in-house design-support capabilities.
- Electronic Assemblers:High-volume PCB fabrication shops in Taiwan, Japan, and South Korea create localized demand pull reducing logistics friction.
By contract value concentration, module manufacturers lead. By procurement pattern disruption, telecom equipment makers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and Taiwanese laminate makers ship the majority of high-frequency CCL output to base station antenna fabricators in South Korea and mainland China. This trade corridor channels premium hydrocarbon and PTFE formulations toward 5G Massive MIMO deployment clusters. Logistics friction drops when material sources sit within 48-hour freight radius of PCB shops.
China
MIIT equipment certification rules mandate specific loss tolerances at licensed millimeter-wave bands. Domestic substitution policies redirect procurement from import-dependent supply chains toward qualified local laminate sources. The Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate base station antenna board production.
Japan
Ultra-low-profile copper foil treatment specialists anchor upstream supply for premium laminate grades. METI industrial policy supports high-frequency material R&D through targeted funding mechanisms. The Kanto region around Tokyo hosts concentrated resin synthesis and copper foil processing capacity.
South Korea
Telecom OEMs compress qualification cycles from 24 months to 12 months to match 5G deployment timelines. MFDS chemical safety frameworks align with REACH restrictions on halogenated formulations. The Seoul Capital Area and Busan-Ulsan corridor concentrate antenna module manufacturing.
Taiwan
Multi-layer PCB fabricators drive demand pull for mid-tier hydrocarbon laminates compatible with standard FR4 equipment. Trade documentation requirements under MIIT rules favor suppliers with traceable material provenance. The Hsinchu-Taichung technology corridor clusters advanced substrate production.
United States
FCC spectrum allocations at 28 GHz and 39 GHz bands shape laminate performance benchmarks for dense urban 5G coverage. Defense contractors concentrate electromagnetic modeling expertise for stack-up optimization above 10 GHz. The Pacific Northwest and Greater Boston corridors host satellite electronics and aerospace RF module development.
High Frequency High Speed Copper Clad Laminate CCL Market Competitive Landscape
Player mix skews toward vertically integrated resin specialists and regional volume producers. The vendor base splits between captive polymer synthesis operations and laminate converters dependent on third-party feedstocks. Two strategic archetypes dominate: fluoropolymer specialists serving aerospace qualification programs and modified epoxy scale producers feeding telecom infrastructure. Competitive moves concentrate on backward integration into resin chemistry and multi-source procurement agreements with telecom OEMs.
Among Japan-based material conglomerates, Panasonic Holdings exemplifies the integrated archetype with in-house control over resin formulation and copper foil treatment. Taiwan Union Technology Corporation and Elite Material Co., Ltd. occupy positions within the mid-tier volume segment, representing fabricators who balance qualification depth with production scale. These three anchors illustrate how geographic concentration of PCB manufacturing capacity pulls laminate supply chain configuration toward East Asian production clusters.
| Leading Market Players |
|---|
| Panasonic Holdings |
| Shengyi Technology |
| Isola Group |
| ITEQ Corporation |
| Rogers Corporation |
| Kingboard Laminates Holdings |
| Elite Material Co., Ltd. |
| Taiwan Union Technology Corporation |
| AGC |
| Others |
Pricing and Supply Chain Analysis
Ceramic-filled thermoset composites displacing pure PTFE laminates in sub-6 GHz infrastructure simultaneously redraws procurement geography toward East Asian fabricators and compresses price premiums for fluoropolymer specialists. This substitution dynamic funnels volume toward hydrocarbon formulations that process on standard FR4 equipment, eroding the equipment-investment barrier that once protected tier-one pricing.
Pricing Analysis
Current-generation hydrocarbon laminates trade at 40-60% premiums over legacy modified-epoxy platforms, while next-generation ceramic-PTFE hybrids for satellite thermal management command substantial markups over both. Three-tier pricing structure across premium, standard, and economy levels separates aerospace qualification-grade materials from telecom infrastructure volumes and consumer wireless commodity grades. Price differentiation rests on certification depth and resin formulation control, with MIIT-qualified domestic sources in China capturing margin compression from import substitution mandates. Telecom equipment makers exhibit highest price sensitivity as they unwind legacy procurement patterns, while satellite constellation operators accept premium positioning for orbital reliability guarantees.
Supply Chain Analysis
Inventory buffers at European laminate distributors have thinned to 8-12 month lead time extensions as ECHA F-Gas Regulation phase-down schedules restrict hydrofluorocarbon feedstocks. Geographic supply concentration centers on Japan, Taiwan, and South Korea, where ultra-low-profile copper foil treatment specialists and resin synthesis operations cluster within 48-hour freight radius of PCB fabrication hubs. Raw material dependencies draw from fluoropolymer feedstocks, ceramic fillers, and phosphorus-based flame retardant chemistry. Single-source vulnerability concentrates in Japanese and Taiwanese foil treatment specialists controlling surface finish supply. Distribution runs through qualified supplier programs for defense contractors and multi-source agreements for telecom OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across this market as 5G Massive MIMO deployment compresses qualification cycles and creates niche openings for mid-tier suppliers with accelerated formulation validation. The demand-side shift toward domestic substitution in China splinters consolidated procurement patterns into geography-specific vendor panels.
For Market Incumbents: Consolidate backward integration into resin synthesis and copper foil treatment to defend formulation control against emerging hydrocarbon specialists. Lock in multi-year supply agreements with telecom OEMs before base station deployment peaks, while accelerating phosphorus-based flame retardant R&D to outpace REACH chemical restriction timelines. Priority lever: captive polymer production capacity in East Asian manufacturing clusters. For New Entrants and Emerging Players: RF simulation and stack-up optimization services represent a service-layer gap where incumbents under-serve mid-tier antenna board manufacturers lacking in-house electromagnetic modeling expertise. Target India's telecom infrastructure expansion through TRAI spectrum auction alignment and BIS certification pathway investment. Go-to-market angle: design-support partnerships that compress customer qualification cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier laminate converters in Taiwan and South Korea possessing qualified supplier status but lacking captive resin synthesis. Long-term viability over the analysis window favors vertically integrated platforms with polymer production and MIIT certification documentation. Acquisition target archetype: hydrocarbon specialists with established telecom OEM relationships and expandable foil treatment capacity. Signal to watch: satellite constellation launch schedules accelerating ceramic-PTFE hybrid specification pull.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive polymer production secures formulation control against ECHA feedstock restrictions. |
| MIIT Certification Pathway Investment | Domestic qualification unlocks Chinese state-backed equipment tender participation. |
| Phosphorus-Based Flame Retardant Scale-Up | Non-halogen chemistry alignment with REACH directives opens European base station deployments. |
| RF Simulation Service Layer Launch | Design-support capabilities differentiate mid-tier suppliers for antenna board manufacturers. |
| Multi-Source Procurement Agreement Lock-In | Pre-peak 5G deployment volume commitments freeze out unqualified competitors. |
Research Methodology
A spread of perspectives from resin synthesis directors, PCB fabrication procurement leads, telecom OEM material engineers, and satellite electronics program managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through MIIT equipment certification databases, FCC spectrum allocation filings, ECHA REACH restriction updates, and customs trade flow records. Bottom-up volume estimates from laminate converter capacity and top-down demand triangulation from base station deployment schedules were cross-referenced for convergence.
Segmentation dimensions modeled span product chemistry, signal integrity technology tier, application performance requirements, and end-user procurement authority across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Industry-specific forecast inputs include Massive MIMO antenna array deployment trajectories and LEO satellite constellation thermal management specification evolution.
Forecasts assume regulatory continuity in FCC spectrum allocation, MIIT equipment certification, and ECHA chemical restriction regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.