
 Biocomposites Market | 2026-2036
Biocomposites Market Size, Share, and Industry Trends Forecast 2026-2036
Biocomposites Market Analysis
The EU Green Deal is expanding material substitution mandates across European manufacturing, compelling automotive and construction buyers to source lower-carbon reinforced materials. BASF SE leverages its polymer science infrastructure to supply bio-based polyamide grades for under-hood applications. Trex Company, Inc. anchors North American decking demand through proprietary wood-plastic co-extrusion systems. UPM-Kymmene Corporation differentiates via integrated pulp-to-composite sourcing from Finnish forestry assets.
Biocomposites combine natural fibers such as flax, hemp, or wood flour with thermoplastic or thermoset resin matrices, typically processed through extrusion, injection molding, or compression molding to achieve densities between 1.0 and 1.4 g/cm³ and flexural moduli comparable to glass-filled polymers. These materials serve industries seeking weight reduction, carbon footprint improvement, and end-of-life biodegradability. Wood plastic composites dominate volume due to mature extrusion infrastructure and established outdoor construction specifications, while natural fiber composites capture faster growth in automotive interiors where OEMs specify renewable content thresholds. Bio-based composites command premium positioning in packaging applications requiring compostability certification.
REACH registration requirements in Europe govern chemical safety disclosure for resin systems and fiber treatments, while FDA food-contact regulations in the United States restrict certain natural fiber binders from packaging segments. BIS certification in India and GB standards in China impose mechanical testing protocols that foreign suppliers must satisfy for market access. Stakeholders must track evolving bio-content verification methodologies and regional lifecycle assessment standards to secure procurement contracts and avoid exclusion from approved vendor lists.
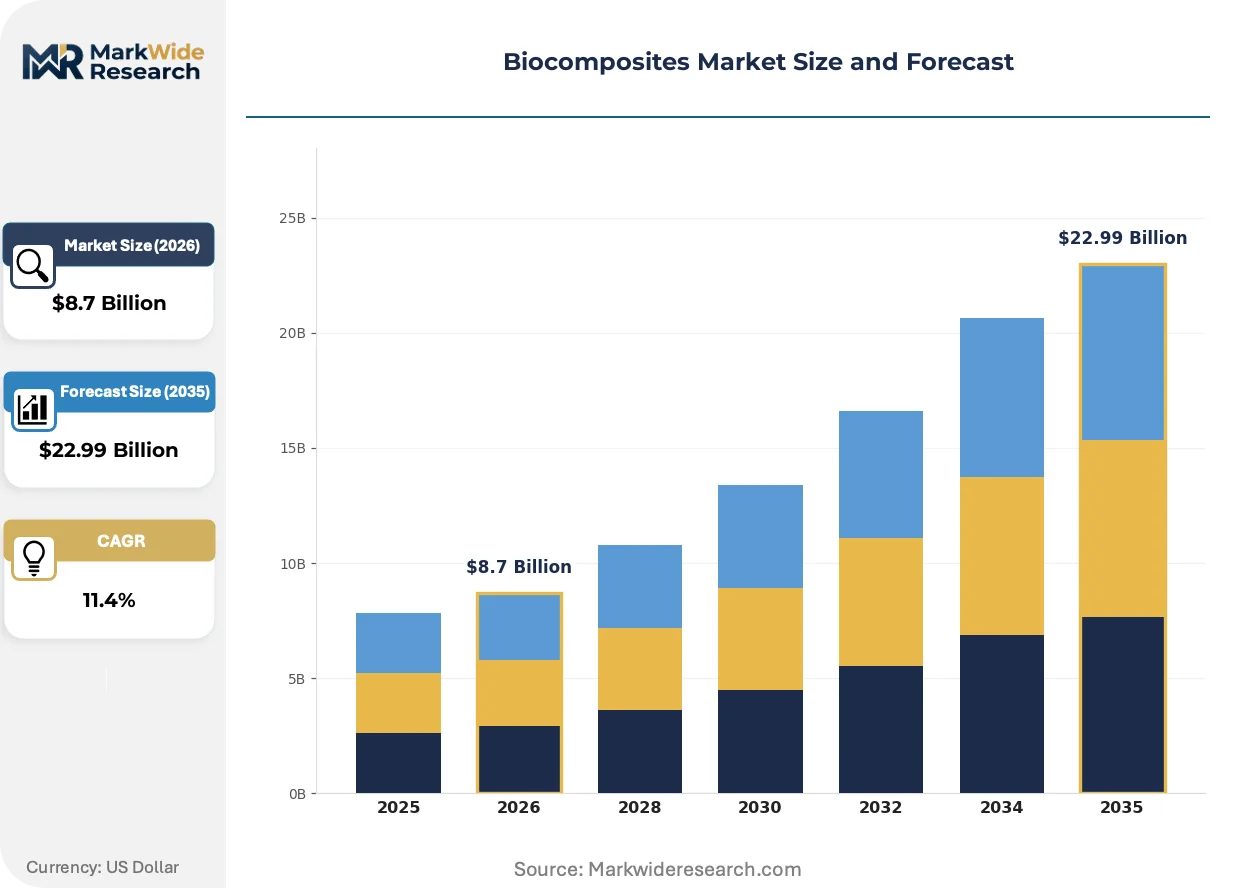
Market Dynamics
EU Green Deal mandates are compressing automotive OEM sourcing timelines for lower-carbon interior materials, forcing Tier 1 suppliers to requalify natural fiber-reinforced compounds ahead of 2030 fleet emission targets.
Growth Catalysts
- REACH bio-content verification:ECHA's evolving substance registration protocols favor fiber treatments with disclosed lifecycle data, accelerating substitution of glass-filled polymers in German automotive under-hood applications.
- Wood-plastic extrusion maturity:Decades of decking infrastructure deployment in the United States enables rapid specification transfer to secondary construction segments including fencing and cladding.
- China dual carbon goals:Provincial construction bureaus in Jiangsu and Zhejiang provinces are embedding renewable content thresholds into public infrastructure tender requirements.
Market Restraints
- Natural fiber supply concentration:European flax cultivation clusters in Normandy and Flanders create geographic single-point vulnerability for automotive-grade fiber supply security.
- Resin price volatility:Bio-based polyamide feedstock costs track castor oil commodity swings, compressing compounder margins during agricultural harvest disruptions.
- Technical limitation:Moisture absorption rates in hemp-reinforced thermoplastics restrict exterior automotive panel applications despite interior qualification success.
Strategic Opportunities
- Underpenetrated geography:India's BIS mechanical testing framework for fiber-reinforced construction materials remains sparsely enforced, creating first-mover specification advantages for compliant foreign suppliers.
- Technology convergence:Continuous fiber alignment systems borrowed from aerospace prepreg manufacturing are integrating with biocomposite extrusion lines to achieve glass-comparable tensile performance.
- Regulatory tailwind:EU Corporate Sustainability Reporting Directive disclosure requirements are compelling packaging buyers to source compostable-certified bio-based composites for food-contact applications.
Industry Challenges
- Certification timeline compression:ASTM and ISO harmonization delays for bio-content measurement methodologies force suppliers to run parallel testing protocols, extending product qualification cycles.
- Compounding skill scarcity:Fiber dispersion optimization for injection molding requires polymer rheology expertise that conventional mineral-filled compounders lack, constraining qualified toll manufacturing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocomposites Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Plastic Composites, Natural Fiber Composites, Bio-based Composites, Recycled Composites End Use Industry: Construction, Automotive, Furniture, Consumer Goods Form: Plates, Sheets, Films, Granules Application: Decking, Flooring, Automotive Interiors, Packaging |
| Companies Covered | BASF SE, UPM-Kymmene Corporation, Trex Company, Inc., Stora Enso Oyj, Dow Inc., Arkema S.A., DuPont de Nemours, Inc., Fiberon LLC, Universal Forest Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocomposites Market Emerging Trajectories
Active fiber surface modification chemistry is bridging the performance gap between natural and synthetic reinforcements, enabling specification expansion beyond established outdoor construction into structural load-bearing applications.
Hybrid natural-synthetic fiber architectures are integrating lignocellulosic reinforcements with recycled carbon fiber fragments to achieve density-weighted stiffness metrics matching virgin glass-filled compounds. Tier 1 automotive suppliers in Germany and Sweden are qualifying these hybrid grades for seat pan and door module applications. The technology is integrating formerly separate natural fiber and recycled composite supply chains into unified compounder networks.
EU F-Gas Regulation phase-down schedules are accelerating thermoplastic biocomposite adoption in HVAC housing applications previously served by foamed petrochemical derivatives. Equipment manufacturers face refrigerant containment material constraints that bio-based polyamide grades address through lower permeability coefficients. French and Italian HVAC OEMs are leading specification shifts ahead of 2027 quota reductions.
Buyer consolidation among North American home improvement retailers is compressing decking supplier negotiation cycles and unbundling traditional distributor relationships. Large-format retailers now demand direct mill relationships with volume-commitment pricing and private-label co-development rights. The channel shift concentrates procurement leverage with three national buyers while fragmenting remaining independent lumberyard distribution.
Biocomposites Market Segmentation
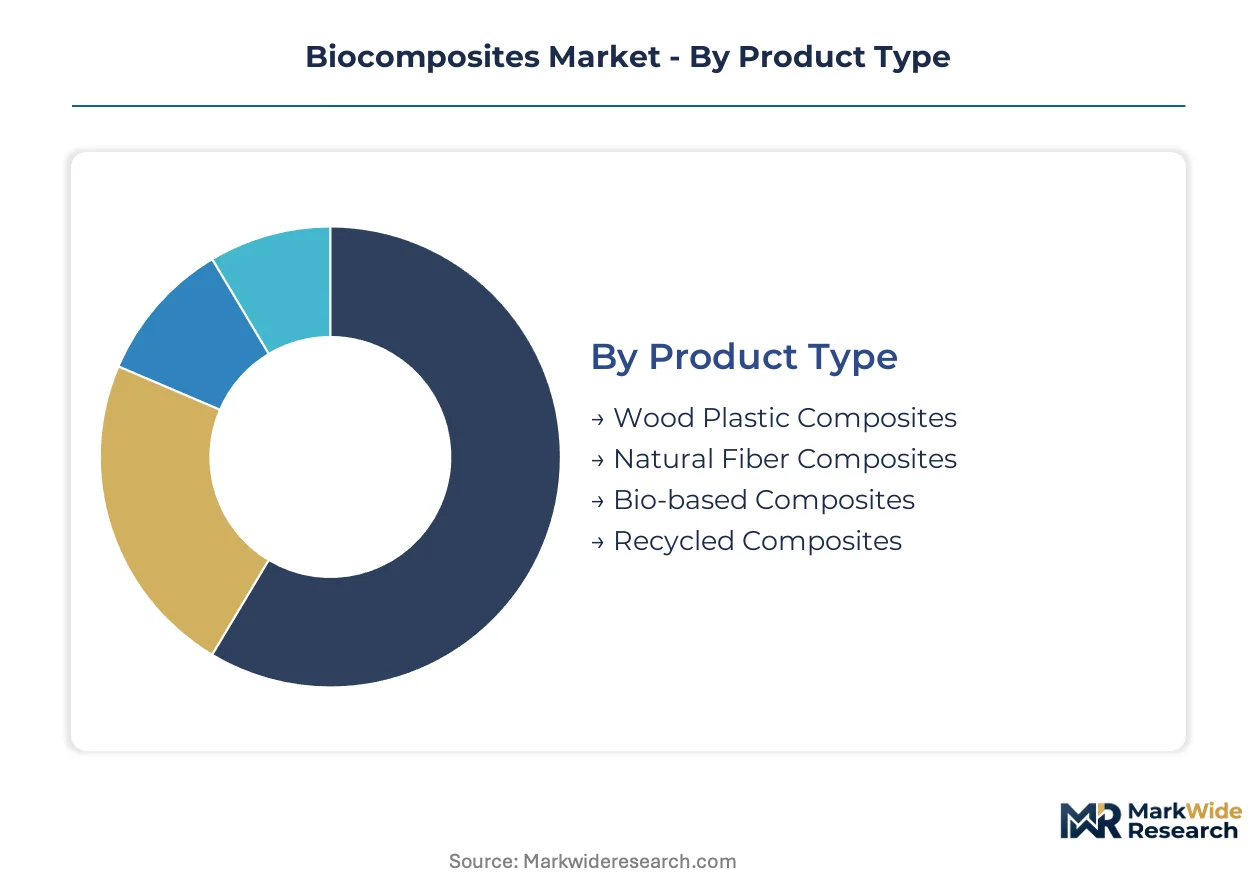
Biocomposite procurement decisions hinge on balancing mechanical performance against carbon accounting requirements, with each segment category reflecting distinct trade-offs between manufacturing maturity, regulatory compliance, and end-use specification tolerance.
Product Type:
Buyers prioritize supply security and processing compatibility when selecting among competing biocomposite chemistries, weighing established extrusion infrastructure against emerging bio-content thresholds.
- Wood Plastic Composites:These materials combine wood flour or cellulose fibers with polyethylene, polypropylene, or PVC matrices through twin-screw extrusion, achieving densities between 1.1 and 1.3 g/cm³. Demand concentrates in United States residential decking and fencing applications, where decades of outdoor performance data satisfy building code compliance and homeowner warranty expectations.
- Natural Fiber Composites:Flax, hemp, or jute reinforcements embedded in thermoplastic matrices deliver specific stiffness metrics approaching glass-filled alternatives at 40% lower density. German and Swedish automotive OEMs specify these grades for interior door panels and seat structures under EU Green Deal renewable content mandates.
- Bio-based Composites:Fully bio-sourced resin systems derived from castor oil or polylactic acid paired with natural fibers command certification premiums in European food-contact packaging segments requiring compostability verification.
- Recycled Composites:Post-industrial wood fiber and recycled polymer blends target cost-sensitive construction applications in China and India where mechanical performance specifications permit higher batch-to-batch variability.
Wood Plastic Composites leads on scale; Natural Fiber Composites leads on momentum.
End Use Industry:
Volume allocation across end-use sectors tracks divergent regulatory pressure intensities and specification maturity curves.
- Construction:Exterior decking, cladding, and fencing applications in the United States and China absorb the majority of wood-plastic composite tonnage, with building code acceptance and contractor familiarity sustaining specification inertia despite higher material costs versus pressure-treated lumber.
- Automotive:Interior paneling, seat pans, and door modules represent the primary specification vector, with German Tier 1 suppliers accelerating natural fiber compound qualification ahead of fleet emission compliance deadlines.
- Furniture:Flat-pack and outdoor furniture manufacturers in Scandinavia specify bio-based composites for sustainability-marketed product lines where consumer willingness-to-pay absorbs material premiums.
- Consumer Goods:Electronics housings and personal care packaging applications remain nascent, constrained by surface finish requirements and supply chain qualification timelines.
Construction dominates procurement volume; Automotive exhibits the steepest expansion trajectory.
Form:
Processing method compatibility and downstream manufacturing integration determine form selection across buyer segments.
- Plates:Compression-molded flat stock serves thermoforming operations for automotive interior components, with thickness tolerances critical for downstream robotic handling.
- Sheets:Extruded continuous profiles target construction cladding and furniture surfacing applications where dimensional stability across humidity cycles determines field performance.
- Films:Thin-gauge bio-based formulations address flexible packaging specifications requiring heat-sealability and print surface compatibility.
- Granules:Compounded pellet feedstock enables injection molders to integrate biocomposite content without capital investment in fiber handling and dispersion equipment.
Granules command the broadest addressable equipment base; Sheets capture the most rapid specification growth in exterior construction.
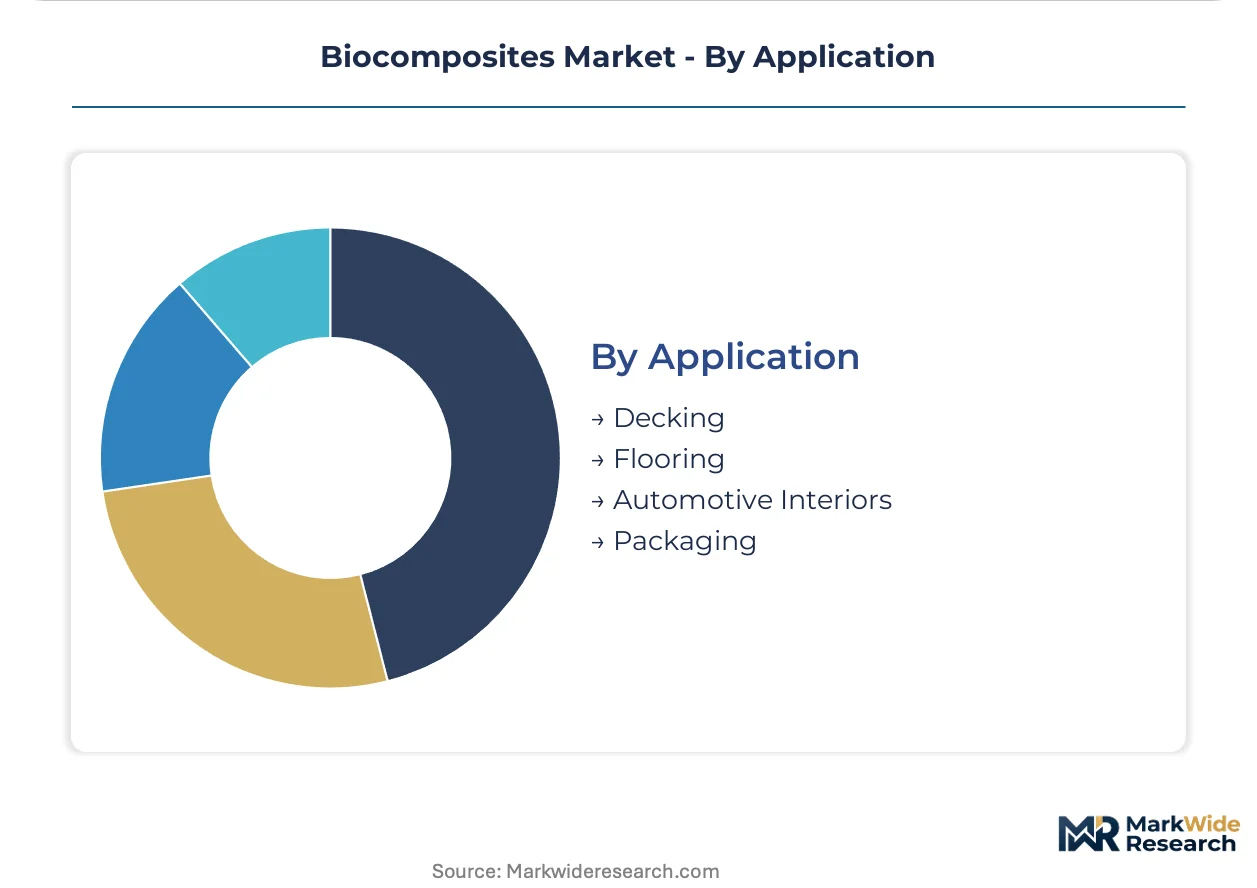
Application:
Application-level segmentation reveals how performance requirements and exposure conditions filter material selection across end-use contexts.
- Decking:Wood-plastic composite boards with co-extruded protective cap layers dominate United States residential replacement and new construction segments, with 25-year fade and stain warranties standard among national brands.
- Flooring:Luxury vinyl tile and laminate alternatives incorporating bio-based core layers target commercial interiors in Europe where building certification schemes reward renewable content.
- Automotive Interiors:Door panels, instrument clusters, and seat structures specify natural fiber-reinforced polypropylene for weight reduction and end-of-life recyclability compliance with EU ELV directives.
- Packaging:Food-contact trays and rigid containers utilize bio-based composites with compostability certification for quick-service restaurant and fresh produce segments in France and Italy.
Decking anchors current volume; Automotive Interiors is gaining share fastest on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding expertise clusters in Germany's Rhine-Ruhr corridor anchor European biocomposite formulation capacity. Wood-plastic extrusion specialists concentrate in the United States Midwest and China's Yangtze River Delta.
United States
Residential decking replacement cycles and contractor specification inertia sustain wood-plastic composite demand across the Midwest and Southeast. EPA-treated wood disposal regulations accelerate substitution toward extruded bio-based alternatives. Wisconsin and Minnesota host concentrated extrusion infrastructure serving national home improvement retail channels.
Germany
Automotive interior engineering teams in Stuttgart and Munich drive natural fiber compound qualification for fleet emission compliance. EU Green Deal renewable content mandates compress Tier 1 supplier sourcing timelines through 2030. BASF SE's Ludwigshafen polymer science infrastructure supplies bio-based polyamide grades for under-hood thermal management applications.
China
Provincial construction bureaus in Jiangsu and Zhejiang embed renewable content thresholds into public infrastructure tender requirements. MIIT industrial material standards govern mechanical testing protocols for fiber-reinforced construction products. The Yangtze River Delta hosts integrated wood-plastic extrusion clusters serving domestic decking and cladding specification growth.
India
BIS mechanical testing frameworks for fiber-reinforced construction materials remain sparsely enforced, creating specification advantages for compliant foreign suppliers. DGFT import tariff structures on polymer resins influence compounder margin structures. Gujarat and Maharashtra industrial corridors attract toll compounding investments targeting cost-sensitive secondary construction segments.
Finland
Integrated pulp-to-composite sourcing from domestic forestry assets differentiates Nordic suppliers in automotive and packaging segments. ECHA REACH registration requirements govern chemical safety disclosure for resin systems and fiber treatments. UPM-Kymmene Corporation's Rauma and Tampere operations leverage captive lignocellulosic feedstock for specialty composite grades.
Biocomposites Market Vendor Landscape
Capital-heavy integrated forest product companies compete with asset-light compounders and extrusion specialists for specification control. The vendor base spans three tiers: multinational chemical conglomerates with polymer science infrastructure, integrated forestry-to-materials operators with captive fiber supply, and regional extrusion specialists with established building product distribution. Strategic differentiation concentrates on backward integration into fiber sourcing, formulation IP for high-temperature automotive applications, and direct retail channel relationships displacing traditional lumberyard distribution.
Among integrated forestry-based operators, UPM-Kymmene Corporation and Stora Enso Oyj exemplify the captive lignocellulosic feedstock archetype. Trex Company, Inc. occupies a position within the specialized extrusion tier. BASF SE represents the diversified chemical conglomerate vector with polymer science infrastructure spanning multiple high-performance resin systems.
| Leading Market Players |
|---|
| BASF SE |
| UPM-Kymmene Corporation |
| Trex Company, Inc. |
| Stora Enso Oyj |
| Dow Inc. |
| Arkema S.A. |
| DuPont de Nemours, Inc. |
| Fiberon LLC |
| Universal Forest Products, Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal renewable content mandates gate both qualified biocomposite supply and premium-tier pricing access, compressing sourcing timelines for automotive OEMs while elevating certified compound valuations above commodity resin grades. Buyers lacking verified lifecycle data face exclusion from approved vendor lists, forcing parallel qualification investments that widen price spreads between compliant and non-compliant supply tiers.
Pricing Analysis
Bundled toll-compounding services with integrated fiber sourcing command premiums over unbundled resin-and-fiber transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments, with REACH-registered bio-polyamide grades carrying the widest spreads. Price differentiation stems from ECHA disclosure requirements and after-sales technical support bundling. Cost compression in standard-tier wood-plastic compounds is intensifying because of polyethylene spot market volatility. Construction buyers in the United States exhibit highest price sensitivity, while German automotive OEMs absorb premiums for emission compliance.
Supply Chain Analysis
Certification and qualification gating concentrates supply among compounders with in-house REACH registration capabilities and verified fiber traceability systems. Raw material dependencies center on Normandy and Flanders flax cultivation clusters, Yangtze River Delta wood flour processing, and castor oil derivatives from Indian agricultural zones. Supply chain risk runs through single-source vulnerability for automotive-grade natural fiber supply. Distribution runs through direct mill relationships with national home improvement retailers, displacing traditional lumberyard networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biocomposites market functions as a regulatory compounder where EU fleet emission targets and Green Deal mandates create structural demand acceleration for lower-carbon reinforced materials.
For Market Incumbents: Deepen backward integration into captive fiber sourcing to defend margin position against resin price volatility and emerging Asian compounders. Lock in long-term offtake agreements with Normandy flax cooperatives before 2030 supply crunches materialize. Prioritize continuous fiber alignment R&D to bridge performance gaps with glass-filled alternatives in structural automotive applications. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in France and Italy open a window for bio-based polyamide grades in HVAC housing applications previously served by foamed petrochemical derivatives. Target India's BIS-compliant construction segment where enforcement sparsity rewards first-mover specification advantages. Lead with toll-compounding partnerships to bypass capital-intensive extrusion infrastructure requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional extrusion specialists with established retail channel relationships but limited formulation IP. Long-term viability hinges on regulatory compounding durability across multiple automotive platform cycles. Watch for EU Corporate Sustainability Reporting Directive disclosure acceleration as the inflection signal for packaging segment demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Sourcing | UPM-Kymmene's captive Finnish forestry assets secure supply continuity for automotive-grade lignocellulosic feedstock. |
| REACH Registration Investment | ECHA compliance unlocks German automotive Tier 1 supplier qualification pipelines for bio-based polyamide compounds. |
| Continuous Fiber Alignment Deployment | Aerospace-derived prepreg manufacturing integration achieves glass-comparable tensile performance in biocomposite extrusion lines. |
| Direct Retail Channel Development | Trex Company's national home improvement retail relationships concentrate procurement leverage against fragmented lumberyard distribution. |
| Hybrid Natural-Synthetic Formulation | Recycled carbon fiber fragment integration bridges density-weighted stiffness gaps for Swedish OEM seat pan applications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer compounding plant managers, automotive Tier 1 procurement leads, construction distribution channel partners, and technical R&D directors at resin suppliers. Secondary validation drew from ECHA REACH registration databases, EU automotive production statistics, customs trade data for natural fiber imports, and SEC filings from listed building products manufacturers. Bottom-up segment sizing and top-down macro constraint checks provided triangulation discipline across the analysis window.
Segment-weighting approaches distributed volume and value across product type, end-use industry, processing form, and geographic production hub dimensions. CAGRs were derived from regression-based trend extrapolation moderated by regulatory milestone phasing and capacity buildout schedules. Forecast inputs incorporated EU fleet emission compliance deadlines, provincial renewable content tender requirements in Jiangsu and Zhejiang, and wood-plastic extrusion infrastructure deployment rates in the United States Midwest.
Revisions become necessary when ECHA substance registration protocols shift, castor oil commodity disruptions exceed historical volatility bands, or ASTM-ISO bio-content measurement harmonization accelerates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and automotive platform qualification timelines. A model refresh is warranted upon material change in EU Green Deal mandate implementation schedules or BIS mechanical testing framework enforcement in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Balsa Core Materials Market
Composite Materials
Composite Drums Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Composite Cans Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Lightweight Materials Market
Composite Materials
Europe Composites Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
Green Composites Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market