
 Russia Household Electric Grill Market | 2026-2036
Russia Household Electric Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Household Electric Grill Market Analytics
Smart temperature control and ceramic coating technology is rewriting how Russian manufacturers engineer electric grills for compact urban kitchens. Tefal leverages its proprietary OptiGrill sensor system to anchor premium positioning in Moscow retail channels. Scarlett competes through aggressive cost engineering that sustains volume share in mid-tier home appliance stores across the Volga Federal District. Bosch differentiates via precision German engineering credentials that command shelf space at specialty kitchen retailers.
A household electric grill is an electrically heated countertop cooking appliance utilizing resistive heating elements typically rated between 1500 and 2500 watts, designed to simulate open-flame grilling through direct contact or convection-based heat transfer for indoor food preparation. Contact grills with removable plates capture the largest installed base due to simplified cleaning routines, while portable grills represent the fastest-growing structural category as single-person households multiply in Russia's major cities. Indoor grills with adjustable temperature controls concentrate margin pools among cooking enthusiasts willing to pay for precise heat management.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) administers GOST-R certification and EAC marking requirements that dictate electrical safety and electromagnetic compatibility standards for all household grill imports and domestic production. The Eurasian Economic Commission's technical regulations further harmonize cross-border compliance obligations for manufacturers supplying Russia, Belarus, and Kazakhstan from unified production facilities. Stakeholders must monitor pending amendments to energy efficiency labeling rules that could reshape procurement criteria for retail distributors and alter competitive rankings among established suppliers.
Market Dynamics
Rosstandart's tightening GOST-R electrical safety protocols are forcing Russian manufacturers to redesign heating element architectures, compressing product development cycles while elevating compliance costs for importers from Eurasian Economic Union member states.
Growth Catalysts
- Urban household densification:Moscow and Saint Petersburg apartment complexes restrict open-flame cooking, channeling demand toward countertop electric alternatives with smoke extraction features.
- EAC marking harmonization:The Eurasian Economic Commission's unified technical regulations eliminate redundant certification barriers for Belarus and Kazakhstan-sourced components, accelerating cross-border supply chain integration.
- Ceramic coating advances:Non-stick surface technologies rated above 400°C operational thresholds extend product lifecycles and justify premium positioning among cooking enthusiasts.
Market Restraints
- Aluminum price volatility:Cast aluminum plate production consumes 35-40% of bill-of-materials costs, exposing margin structures to London Metal Exchange fluctuations.
- Import dependency for precision thermostats:Bimetallic temperature control modules concentrate production in German and Chinese manufacturing clusters, creating single-source vulnerability.
- Induction cooktop substitution:Built-in induction surfaces with grill accessories capture overlapping use cases in new-build kitchen renovations.
Strategic Opportunities
- Siberian and Far Eastern Federal Districts:Perm, Novosibirsk, and Vladivostok retail penetration remains 40-50% below Central Russia saturation levels.
- Smart home integration:WiFi-enabled temperature logging and recipe-guided cooking cycles converge with Yandex Alice and Sber Salute voice ecosystems.
- Specialty kitchen retail expansion:Cookhouse and Posuda Center chains are adding dedicated small appliance zones in Tyumen and Kazan flagship locations.
Industry Challenges
- Thermal engineering talent scarcity:Russian universities produce fewer than 200 specialized heating appliance engineers annually, constraining domestic R&D capacity.
- GOST-R certification timeline compression:Rosstandart's 2024 protocol amendments extended electromagnetic compatibility testing durations from 8 to 14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Household Electric Grill Market |
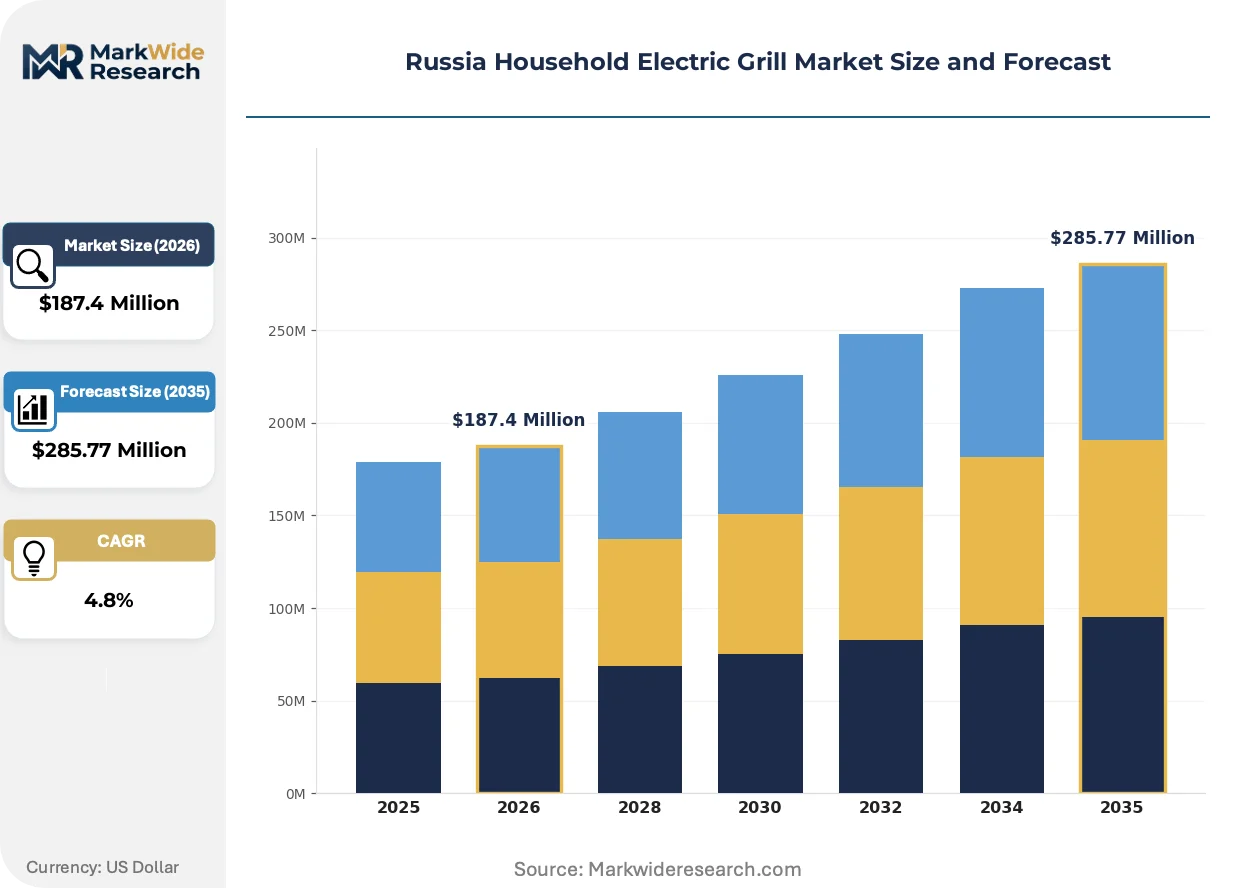
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Grill, Contact Grill, Indoor Grill, Portable Grill Feature: Non-Stick Coating, Adjustable Temperature, Removable Plates, Timer Function End User: Families, Singles, Cooking Enthusiasts, Professionals Distribution Channel: Online Retailers, Home Appliance Stores, Supermarkets, Specialty Stores |
| Companies Covered | Tefal, Philips, Bosch, Scarlett, VITEK, Polaris, Redmond, De'Longhi, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Household Electric Grill Market Evolving Landscape
Smart temperature sensing and connected cooking protocols are restructuring how Russian manufacturers differentiate premium electric grill portfolios, compressing the feature gap between imported and domestically engineered products.
Infrared quartz heating elements are collapsing the thermal response gap between electric contact grills and open-flame cooking. Moscow-based cooking enthusiasts now demand sub-90-second preheat capabilities previously exclusive to gas appliances. This performance convergence is collapsing price premiums commanded by European-imported premium lines.
Rosstandart's pending amendments to energy efficiency labeling rules mandate standby power consumption disclosures below 1 watt for all household electrical appliances. Retail distributors in the Volga Federal District are already adjusting procurement scorecards to prioritize A++ rated models. Domestic manufacturers with in-house testing laboratories are accelerating certification submissions ahead of enforcement deadlines.
Single-person households in Russia's million-plus cities are gravitating toward compact grill formats with dishwasher-safe components. Traditional family-sized contact grills face demand compression as 18-35 year old buyers prioritize storage efficiency over cooking surface area. Yekaterinburg and Nizhny Novgorod electronics retailers report portable grill SKUs turning inventory 2.3x faster than standard formats.
Russia Household Electric Grill Market Segmentation
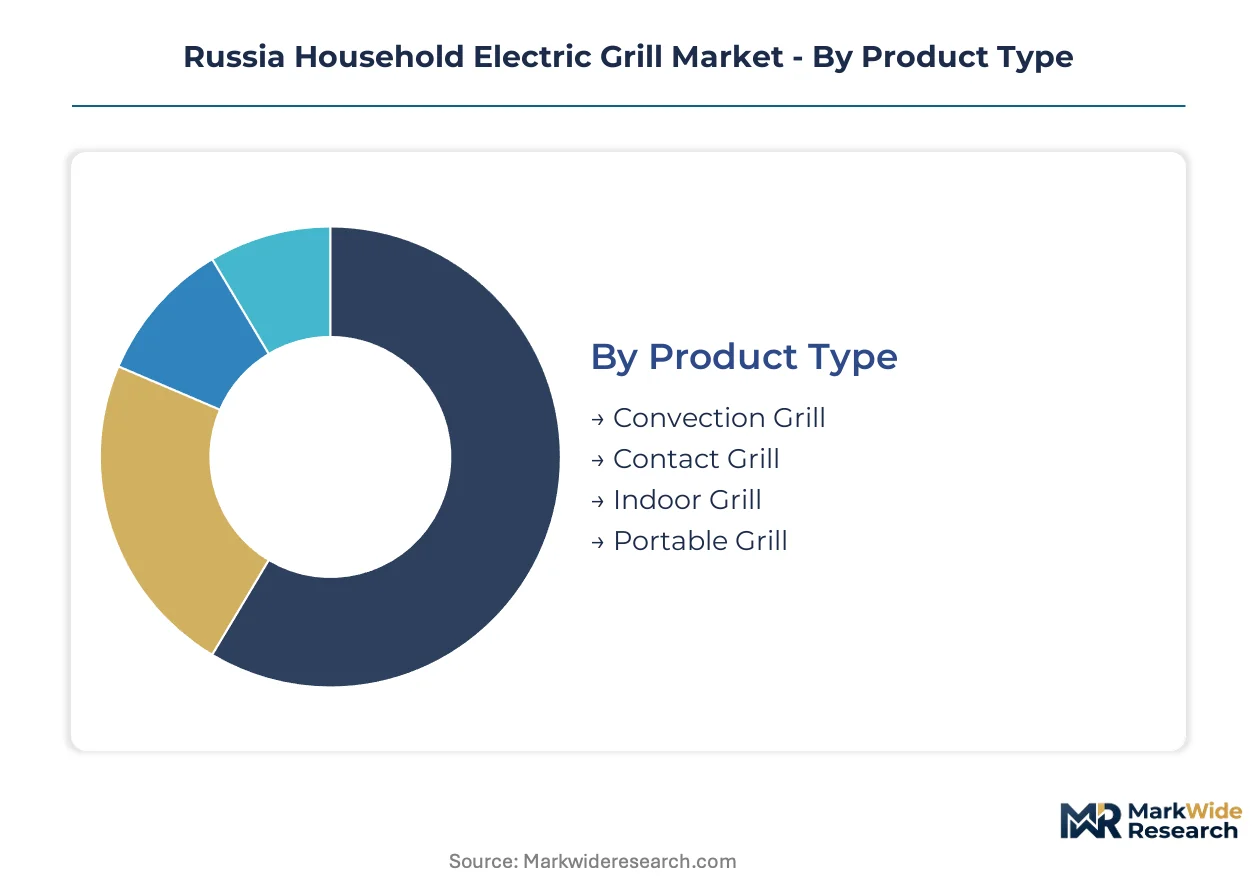
Russia's household electric grill market fragments across four critical dimensions that determine procurement priorities for Moscow retailers and Volga Federal distributors. Product architecture and feature bundles command the steepest price premiums, while distribution channel selection shapes brand accessibility for Siberian versus Central Russian buyers.
Product Type:
Inventory velocity varies dramatically across grill architectures, with portable formats turning 2.3x faster than family-sized units in Yekaterinburg and Nizhny Novgorod electronics retail.
- Contact Grill:Resistive heating elements transfer thermal energy through direct plate-to-food contact, typically rated at 1500-2500 watts. Moscow apartment dwellers prioritize these units for smokeless operation in buildings with open-flame restrictions, driving replacement cycles every 4-5 years as non-stick coatings degrade.
- Portable Grill:Compact footprints under 25 cm width accommodate single-person households in Saint Petersburg's dense urban core. These units gain fastest traction among 18-35 year old buyers who prioritize storage efficiency over cooking surface area, with dishwasher-safe components becoming non-negotiable.
- Indoor Grill:Convection-based heat circulation with adjustable temperature controls serves cooking enthusiasts seeking precise heat management for year-round protein preparation.
- Convection Grill:Forced-air thermal distribution mimics open-flame roasting through circulating hot air, appealing to buyers wanting multi-function countertop appliances.
Contact grills anchor the volume base while portable grills gain share at the steepest rate.
Feature:
Cost-tier differentiation separates premium positioning from mass-market penetration, with ceramic coating technologies commanding 40-60% price premiums over standard non-stick formulations.
- Non-Stick Coating:Ceramic and diamond-infused surface technologies rated above 400°C operational thresholds extend product lifecycles. Tefal's proprietary formulations dominate Moscow premium retail channels, while Scarlett competes through cost-engineered fluoropolymer alternatives.
- Removable Plates:Dishwasher-safe detachable cooking surfaces capture the largest installed base due to simplified cleaning routines. Families with children prioritize this feature for hygiene compliance, particularly in Tyumen and Kazan where water hardness accelerates residue buildup.
- Adjustable Temperature:Bimetallic thermostat modules enable precise heat control across protein types, concentrating margin pools among cooking enthusiasts willing to pay for performance.
- Timer Function:Audible alerts and automatic shutoff protocols address safety concerns in multi-tasking household environments.
Non-stick coating configurations generate the highest margin contribution while removable plates capture the broadest household penetration.
End User:
Customer-type segmentation reveals divergent purchasing rhythms, with cooking enthusiasts replacing units every 2-3 years versus 6-8 year cycles for casual family users.
- Families:Multi-portion cooking surface requirements above 600 cm² dominate procurement criteria, with safety certifications and cool-touch exteriors prioritized for households with young children.
- Cooking Enthusiasts:WiFi-enabled temperature logging and recipe-guided cooking cycles converge with Yandex Alice voice integration, justifying premium positioning for connected kitchen ecosystems.
- Singles:Compact storage footprints and rapid preheat capabilities under 90 seconds align with constrained urban kitchen configurations in million-plus cities.
- Professionals:Commercial-grade durability specifications and extended warranty terms support intensive daily usage patterns in home-based food preparation businesses.
Families constitute the volume foundation while cooking enthusiasts expand most quickly as premium kitchen retail chains proliferate.
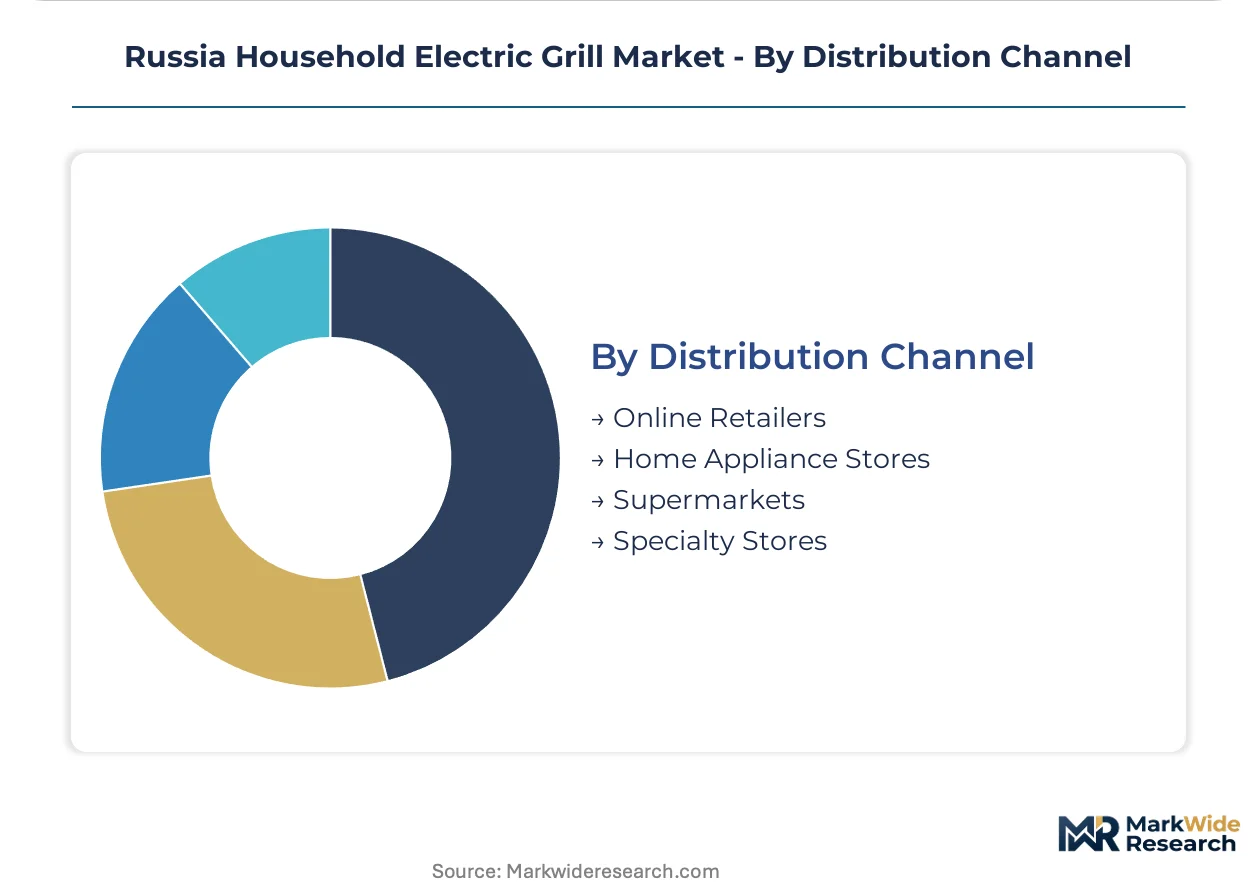
Distribution Channel:
Geographic penetration gaps separate saturated Central Russia markets from underdeveloped Siberian and Far Eastern Federal Districts, where retail infrastructure remains 40-50% below Moscow saturation levels.
- Home Appliance Stores:Physical showrooms across the Volga Federal District sustain Scarlett's mid-tier volume through tactile product demonstration and immediate fulfillment.
- Specialty Stores:Cookhouse and Posuda Center flagship locations in Tyumen and Kazan dedicate expanding small appliance zones to premium electric grill portfolios, capturing cooking enthusiast traffic.
- Online Retailers:E-commerce penetration accelerates in Novosibirsk and Vladivostok where physical specialty retail remains sparse, with delivery logistics constraining bulky appliance purchases.
- Supermarkets:Mass-market grocery channels move entry-level SKUs through impulse placement and promotional bundling with seasonal cooking campaigns.
Home appliance stores defend the volume core while specialty stores climb the fastest as experiential retail investments concentrate in secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's household electric grill market exhibits pronounced regional asymmetry between saturated Central Federal District consumption and underdeveloped Siberian penetration. Import flows concentrate through Moscow and Saint Petersburg distribution hubs before radiating eastward.
Central Federal District
Moscow apartment complexes enforce strict open-flame prohibitions, channeling demand toward smokeless electric alternatives. Rosstandart's GOST-R certification requirements apply most stringently here, with electromagnetic compatibility testing timelines extending to 14 weeks. The Moscow retail corridor anchors premium positioning for contact grills with ceramic coatings.
Northwestern Federal District
Saint Petersburg's dense urban core drives portable grill adoption among single-person households prioritizing storage efficiency. The Eurasian Economic Commission's EAC marking harmonization facilitates component sourcing from Belarusian manufacturing clusters. Cookhouse specialty retailers in the city center dedicate expanding floor space to compact indoor grill formats.
Volga Federal District
Tyumen and Kazan home appliance stores sustain mid-tier volume through tactile product demonstration. Water hardness in the region accelerates demand for removable plate configurations that simplify cleaning routines. Posuda Center flagship locations are adding dedicated small appliance zones to capture cooking enthusiast traffic.
Siberian Federal District
Novosibirsk retail penetration remains 40-50% below Central Russia saturation levels, creating expansion headroom for distributors. E-commerce channels compensate for sparse physical specialty retail infrastructure, though delivery logistics constrain bulky appliance purchases. Regional electronics retailers report portable grill SKUs turning inventory 2.3x faster than standard family-sized formats.
Far Eastern Federal District
Vladivostok's geographic isolation from European Russia amplifies supply chain complexity for imported components. The district's lower household appliance density reflects infrastructure gaps rather than suppressed demand. Cross-border trade dynamics with neighboring Asian economies introduce alternative sourcing pathways for temperature control modules.
Russia Household Electric Grill Market Competitive Landscape
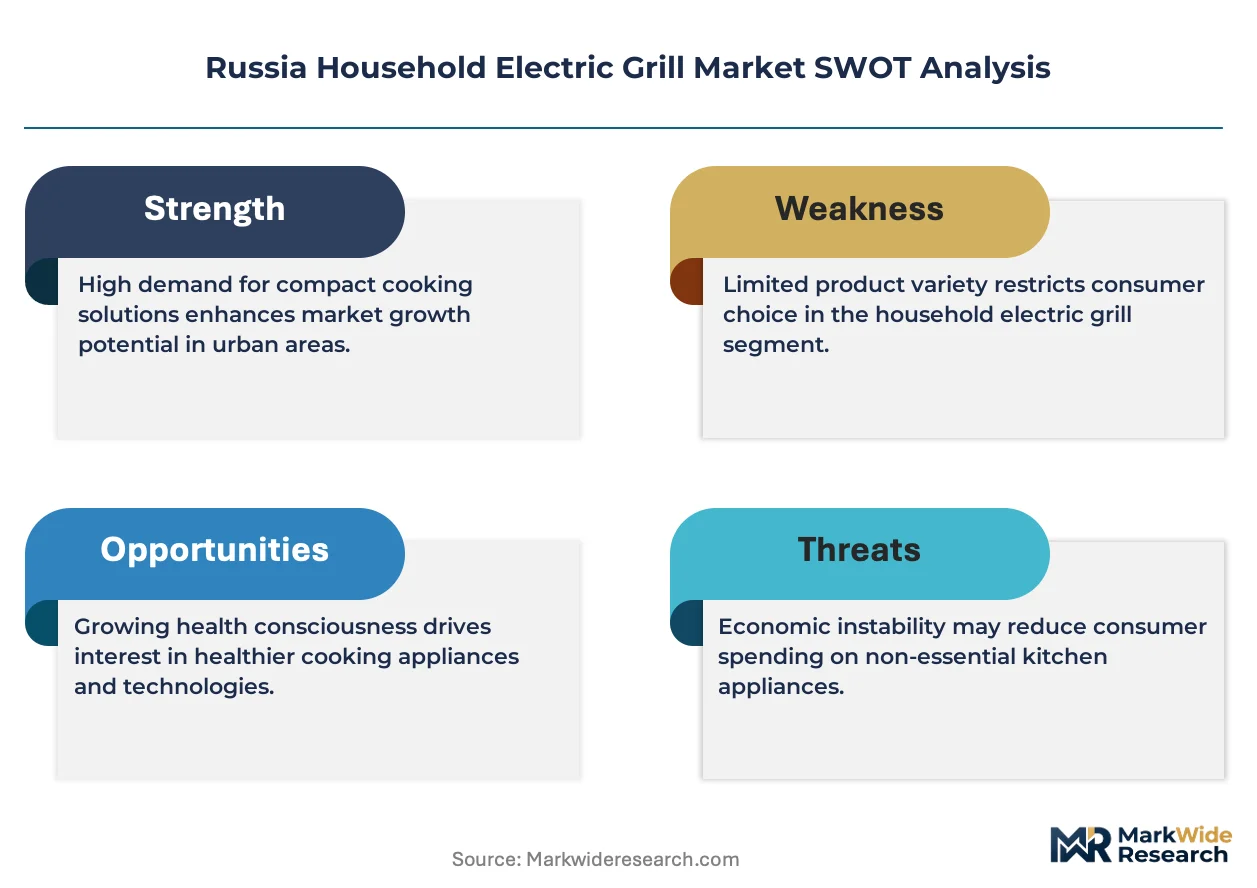
On the supply side, the industry is tiered across premium engineering credentials, aggressive cost engineering, and domestic volume manufacturing. European-origin multinationals anchor premium positioning through proprietary sensor systems and ceramic coating technologies. Russian domestic manufacturers compete through localized cost structures and distribution depth in secondary cities. The dominant competitive moves are portfolio diversification into smart home integration and geographic expansion into underpenetrated Siberian and Far Eastern Federal Districts.
Among European-origin engineering specialists, Tefal and Bosch exemplify premium-tier positioning through precision manufacturing credentials and proprietary heating technologies. Scarlett occupies a position within the domestic cost-engineering tier, leveraging volume manufacturing and distribution density across mid-tier home appliance stores. Philips represents the diversified electronics conglomerate archetype, anchoring brand recognition through broad consumer appliance portfolios. These three archetypes collectively structure competitive dynamics across Moscow premium retail, Volga Federal mid-market channels, and emerging e-commerce penetration in Siberia.
| Leading Market Players |
|---|
| Tefal |
| Philips |
| Bosch |
| Scarlett |
| VITEK |
| Polaris |
| Redmond |
| De'Longhi |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
German and Chinese manufacturing clusters for bimetallic thermostat modules concentrate upstream supply, anchoring margin pools in temperature control engineering while compressing pricing flexibility for mid-tier Russian assemblers.
Pricing Analysis
Cooking enthusiasts anchor premium pricing for ceramic-coated contact grills in Moscow specialty retail, while casual family buyers in the Volga Federal District drive volume through cost-engineered fluoropolymer alternatives. Three-tier pricing structure across premium, standard, and economy levels separates Tefal's sensor-integrated lines from Scarlett's mid-market positioning and entry-level supermarket SKUs. Cost compression in the standard tier intensifies because aluminum plate volatility exposes bill-of-materials structures to commodity swings. Casual family users exhibit highest price sensitivity, whereas connected kitchen enthusiasts tolerate 40-60% premiums for WiFi-enabled temperature logging.
Supply Chain Analysis
Cast aluminum feedstock draws from Chinese smelters and Russian domestic foundries, with precision thermostat modules sourced from German and Chinese manufacturing clusters. Ceramic coating formulations hinge on proprietary supply relationships with European chemical specialists. Single-source vulnerability concentrates in temperature control componentry, where bimetallic module production lacks qualified secondary sources. Distribution runs through Moscow and Saint Petersburg hub-and-spoke networks before radiating eastward through Novosibirsk consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against induction cooktop substitution as built-in surfaces with grill accessories capture overlapping use cases in Russian kitchen renovations.
For Market Incumbents: Pre-empt induction substitution by accelerating smart home integration with Yandex Alice and Sber Salute voice ecosystems. Deepen backward integration into ceramic coating formulation to offset aluminum price volatility exposure. Lock in exclusive thermostat module supply agreements with German manufacturers before Rosstandart's extended electromagnetic compatibility testing timelines constrain component sourcing flexibility. For New Entrants and Emerging Players: Pursue underpenetrated Siberian and Far Eastern Federal Districts where retail infrastructure remains 40-50% below Moscow saturation levels. Target single-person households in Novosibirsk and Vladivostok with portable grill formats that turn inventory 2.3x faster than family-sized units. Lead through e-commerce channels where delivery logistics gaps create first-mover advantage over established distributors. For Investors and Strategic Acquirers: Capital is best deployed toward domestic manufacturers with in-house GOST-R testing laboratories and established relationships with Rosstandart certification bodies. Long-term viability hinges on regulatory compliance agility as energy efficiency labeling amendments reshape procurement scorecards. Monitor pending standby power consumption disclosure rules as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Integration | WiFi-enabled grills converge with Yandex Alice voice ecosystems to defend premium positioning. |
| Ceramic Coating Backward Integration | In-house formulation control insulates margin structures from European chemical specialist pricing. |
| Siberian Distribution Expansion | Novosibirsk and Vladivostok retail penetration gaps create 40-50% headroom above current saturation. |
| GOST-R Certification Investment | Rosstandart's 14-week electromagnetic compatibility timelines favor laboratories with established testing protocols. |
| Portable Grill Portfolio Extension | Compact formats address single-person household growth in million-plus Russian cities. |
Research Methodology
Cross-validation between distributor interviews and customs trade data anchors the qualitative findings on import flow concentration. Primary fieldwork engaged category buyers at Cookhouse and Posuda Center chains, procurement leads at Volga Federal home appliance stores, and product managers at Moscow-based manufacturers. Secondary validation drew from Rosstandart certification databases, Eurasian Economic Commission technical regulation filings, and retail audit data from electronics channels. Bottom-up SKU-level demand modeling and top-down macroeconomic calibration ensure triangulation integrity.
Calibration against historical replacement cycle patterns and urban household formation rates refines the analytical framework across the projection horizon. Segmentation dimensions encompass product architecture, coating technology tier, end-user cooking intensity, and distribution channel type. CAGRs derive from installed base growth and premium mix expansion assumptions. Forecast inputs include Moscow apartment construction permitting data and Rosstandart regulatory amendment timelines.
Sensitivities concentrate around aluminum price volatility and GOST-R certification timeline extensions. Forecasts reflect assumptions on single-person household growth rates and induction cooktop penetration in new-build kitchens. Cross-checking against Eurasian Economic Union cross-border trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Household Coffee Machine Market