
 Cook-In-Bags Market | 2026-2036
Cook-In-Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Cook-In-Bags Market Analytics
Polyethylene terephthalate is broadening its role as a cost-effective alternative to polyamide in mid-tier roasting bags, reducing raw material costs without sacrificing thermal stability up to 200°C. Sealed Air Corporation leverages its integrated film extrusion capabilities to control resin conversion costs across North American plants. Reynolds Consumer Products anchors its position through dominant retail shelf presence in supermarkets and mass merchandisers. ProAmpac specializes in compostable film structures that target foodservice accounts seeking single-use alternatives.
Cook-in-bags are heat-resistant flexible pouches engineered from multi-layer polymer laminates or aluminum composites, designed to contain moisture and distribute thermal energy during oven, steam, or water-bath cooking cycles. These structures typically withstand temperatures from 100°C to 230°C depending on end-use application, with seal integrity and migration compliance representing critical performance parameters. Steam bags occupy the largest volume share among product types due to entrenched household familiarity and compatibility with fresh frozen vegetable processing lines. Compostable films represent the fastest-expanding material category, though margin pools remain concentrated in polyamide laminates where barrier premiums persist. Food processing end-use commands the highest per-unit value, driven by specification-grade consistency requirements and HACCP-aligned documentation.
FDA food-contact substance notifications govern polymer selection and additive packages for U.S.-distributed cook-in-bags, while EU REACH restrictions on perfluorinated compounds constrain certain grease-resistant coating formulations in European supply chains. The EU Packaging and Packaging Waste Regulation is reshaping material recovery obligations, pushing converters toward mono-material or certified compostable constructions. Stakeholders must monitor evolving state-level extended producer responsibility laws and assess whether compostable infrastructure investments align with regional collection system maturity.
Market Dynamics
Migration compliance mandates from FDA food-contact substance notifications are compressing polymer selection flexibility, forcing converters to consolidate additive packages and validate alternative resin systems ahead of specification renewals.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Certified compostable film demand is accelerating as extended producer responsibility obligations expand across member states.
- Steam bag technology:Frozen vegetable processors are embedding these pouches directly into IQF lines, capturing household familiarity with moisture-retention cooking.
- United States foodservice consolidation:Multi-unit restaurant operators are standardizing cook-in-bag protocols to reduce kitchen labor variability and plate-time inconsistency.
Market Restraints
- Polyamide price volatility:Caprolactam feedstock fluctuations from Asian petrochemical complexes transmit directly to barrier laminate costs.
- Perfluorinated compound restrictions:EU REACH Annex XVII limits on grease-resistant coatings eliminate certain high-performance formulations from European supply chains.
- Aluminum composite substitution ceiling:Metal detection incompatibility blocks adoption in processed meat facilities with inline x-ray inspection protocols.
Strategic Opportunities
- India food processing expansion:FSSAI modernization of food-contact material standards creates first-mover positioning for migration-tested film suppliers.
- Mono-material polyethylene constructions:Mechanical recycling compatibility is absorbing R&D investment from converters seeking EU Green Deal alignment.
- Cloud kitchen infrastructure:Delivery-optimized ghost kitchens in urban United States clusters are adopting pre-portioned cook-in-bag proteins to eliminate on-site protein fabrication.
Industry Challenges
- Migration testing backlog:FDA notification queue delays for novel polymer additives extend product launch timelines by 8-14 months.
- Compostable infrastructure mismatch:Industrial composting facility scarcity in mid-tier United States municipalities undermines certified film value propositions.
- Heat-seal technician scarcity:Converters face recruitment gaps for operators skilled in ultrasonic and impulse sealing of multi-layer laminates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cook-In-Bags Market |
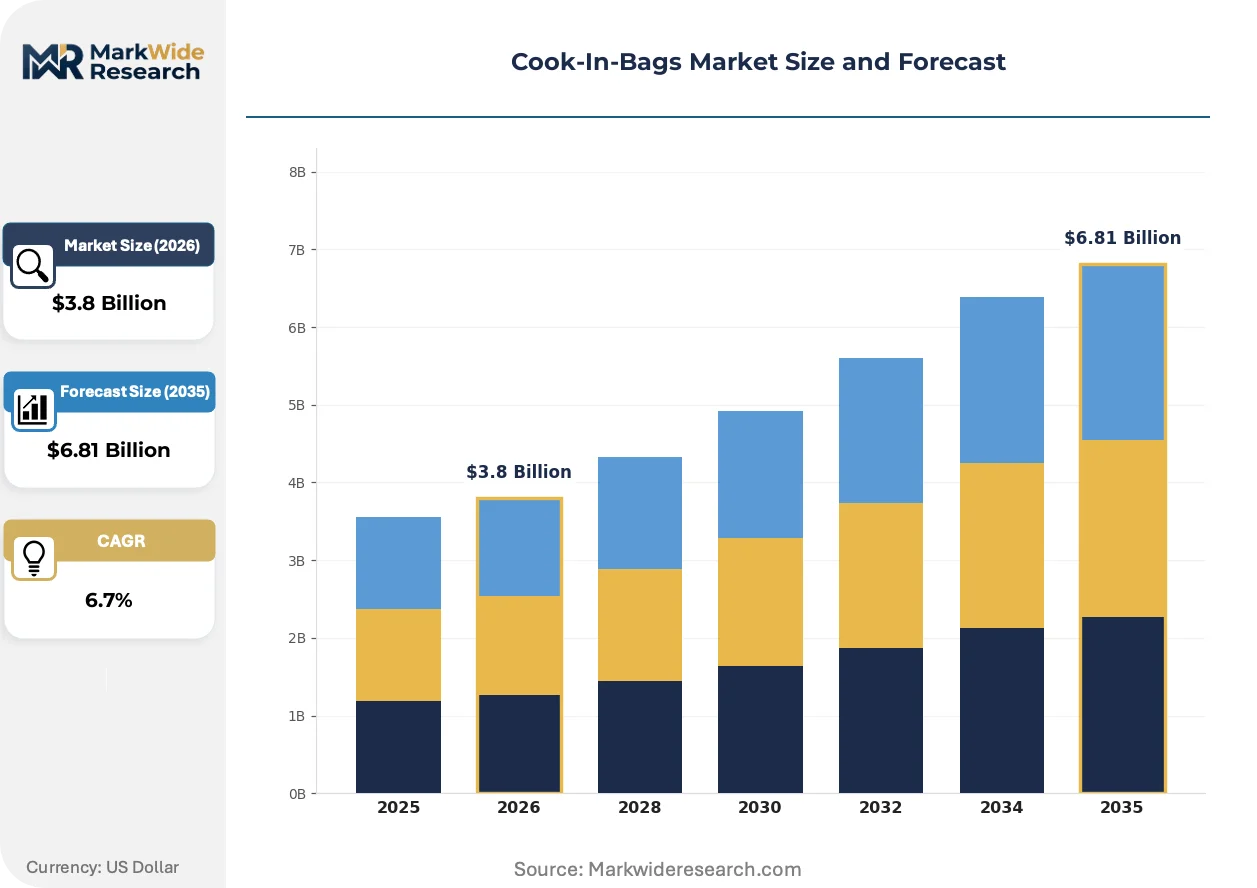
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Bags, Roasting Bags, Sous Vide Bags, Microwave Bags Material: Polyethylene, Polyamide, Aluminum, Compostable Films End Use: Household, Restaurants, Catering Services, Food Processing Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Sealed Air Corporation, Reynolds Consumer Products, S.C. Johnson & Son, Packit Gourmet, M&Q Packaging, GRANITOL, Sirane Limited, UltraSource, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cook-In-Bags Market Evolving Landscape
Material science convergence with regulatory compliance frameworks is redefining competitive advantage, as thermal performance thresholds and end-of-life recovery requirements become simultaneous design constraints rather than sequential priorities.
Polyethylene terephthalate glycol-modified formulations are absorbing mid-tier roasting bag volume from polyamide laminates, delivering 200°C thermal stability at reduced resin cost. United States retail private-label programs are adopting these films for seasonal poultry promotions. The technology is absorbing margin pressure that previously forced standard-tier products below viable conversion economics.
EU REACH restrictions on perfluorinated alkyl substances are eliminating legacy grease-resistant coatings from European cook-in-bag specifications. Converters are reformulating with silicone-based alternatives or abandoning grease resistance claims entirely. Ready-meal processors in Germany and France are absorbing specification changes through accelerated supplier qualification cycles.
Central procurement consolidation among United States healthcare foodservice operators is compressing vendor rosters from regional distributors to national film converters with direct specification support. Group purchasing organizations are absorbing compliance documentation burdens previously borne by individual facility buyers. This concentration is most visible in hospital systems across Texas, Florida, and Ohio metropolitan clusters.
Cook-In-Bags Market Segmentation
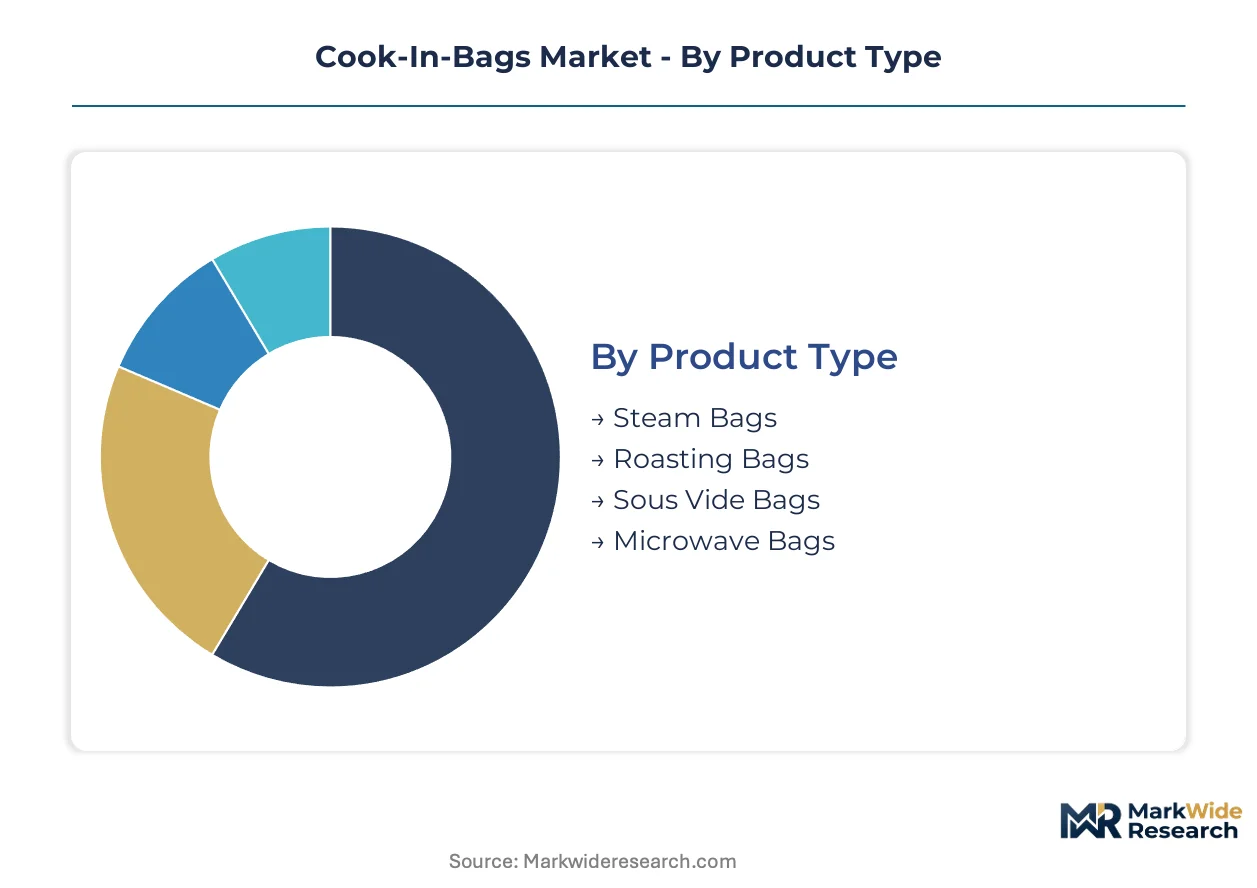
Segmentation in cook-in-bags reveals divergent capital requirements across material platforms and end-use specifications. Product type selection dictates extrusion equipment scale, while end-use determines migration testing investment intensity.
Product Type:
Steam bag production demands the heaviest capital commitment due to precision perforation systems and inline quality verification stations for seal integrity.
- Steam Bags:Multi-layer polymer laminates with laser-perforated venting zones enable controlled pressure release during microwave or oven cycles. Frozen vegetable processors in the United States embed these directly into IQF production lines, leveraging household familiarity with moisture-retention cooking to secure retail placement.
- Roasting Bags:High-temperature polyamide or PET constructions withstand oven cycles up to 230°C for poultry and meat applications. Seasonal demand surges in North American retail channels during holiday periods, requiring converters to maintain flexible capacity allocation.
- Sous Vide Bags:Vacuum-compatible multi-layer structures with extended seal bar durability for prolonged water-bath exposure.
- Microwave Bags:Single-use oriented films with rapid thermal response and vented closures for convenience meal preparation.
Steam bags absorb the bulk of installed capacity; compostable film variants within roasting bags are expanding most quickly.
Material:
Polyamide barrier laminates command premium resin sourcing networks and specialized coextrusion lines, elevating fixed asset thresholds versus commodity polyethylene.
- Polyamide:Nylon-based multi-layer structures deliver oxygen barrier performance critical for extended shelf-life protein applications. EU REACH compliance mandates on caprolactam derivatives constrain additive flexibility, forcing converters toward validated European resin suppliers.
- Compostable Films:Certified biodegradable polymers including PLA and PBAT blends target foodservice accounts seeking single-use alternatives aligned with EU Packaging and Packaging Waste Regulation obligations. Industrial composting infrastructure gaps in mid-tier United States municipalities limit value realization.
- Polyethylene:Cost-effective mono-material constructions gaining traction for mechanical recycling compatibility under EU Green Deal targets.
- Aluminum:Metal-polymer composites for ultra-high barrier applications in processed meat and ready-meal segments.
Polyamide retains the highest margin pool; compostable films are gaining share fastest among sustainability-mandated procurement programs.
End Use:
Food processing specifications require the most intensive documentation investment, with HACCP-aligned batch records and migration certificates for every production lot.
- Food Processing:Specification-grade consistency requirements drive per-unit value premiums, with inline metal detection protocols excluding aluminum composites from certain meat facilities. Central procurement consolidation among United States healthcare foodservice operators compresses vendor rosters to national converters with direct technical support.
- Restaurants:Multi-unit operators standardize cook-in-bag protocols to reduce kitchen labor variability and plate-time inconsistency across Texas, Florida, and Ohio metropolitan clusters.
- Household:Retail shelf presence through supermarkets and mass merchandisers dominates volume, with seasonal promotional cycles.
- Catering Services:Bulk-format bags for institutional feeding with simplified opening features and portion consistency.
Food processing commands the steepest specification barriers; restaurants are climbing the fastest as labor cost pressures accelerate kitchen simplification.
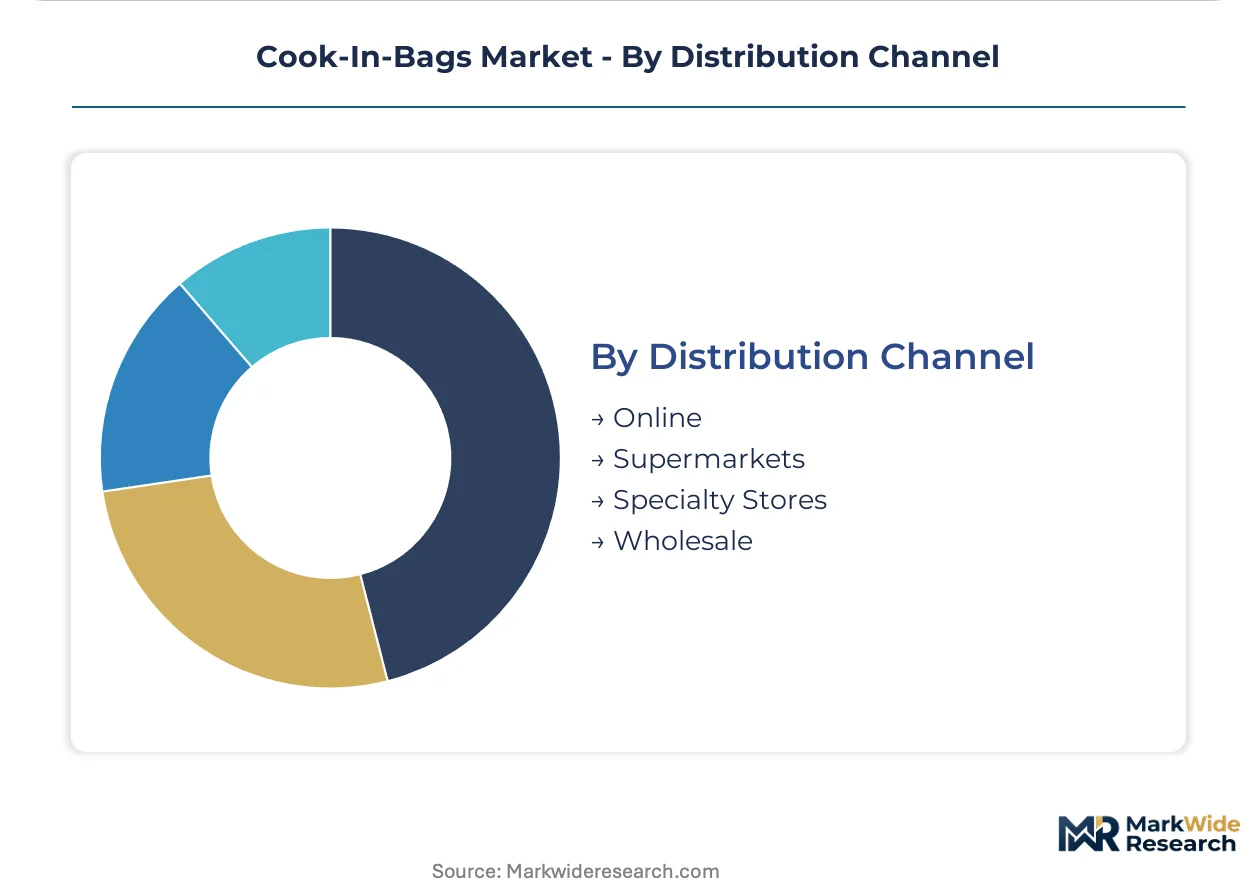
Distribution Channel:
Wholesale relationships with foodservice distributors lock up working capital through extended payment terms and private-label inventory commitments.
- Wholesale:Direct supply to institutional foodservice and industrial processors with specification negotiation and volume contracting.
- Supermarkets:Dominant retail channel for household-oriented steam and roasting bags with seasonal display allocation battles.
- Online:E-commerce penetration for specialty sous vide and compostable formats targeting enthusiast consumers.
- Specialty Stores:Premium positioning for gourmet cooking applications and professional-grade culinary supplies.
Supermarkets anchor volume throughput; online channels are expanding most quickly for niche technical formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States foodservice operators concentrate procurement power through multi-unit restaurant chains and healthcare group purchasing organizations. FDA migration testing mandates shape supplier qualification timelines. Regional clusters in Texas, Florida, and Ohio metropolitan areas standardize cook-in-bag protocols for kitchen labor reduction.
United States
Multi-unit restaurant operators in Texas, Florida, and Ohio drive standardization of cook-in-bag proteins to eliminate on-site fabrication. FDA food-contact substance notifications compress polymer selection flexibility for converters. Cloud kitchen clusters in urban United States markets absorb pre-portioned bag formats for delivery-optimized ghost kitchen operations.
Germany
Ready-meal processors in Germany absorb specification changes from EU REACH perfluorinated compound restrictions through accelerated supplier qualification. The EU Packaging and Packaging Waste Regulation pushes converters toward mono-material or certified compostable constructions. Industrial food processing corridors in Bavaria and North Rhine-Westphalia concentrate migration-tested film demand from specification-grade protein applications.
India
FSSAI modernization of food-contact material standards creates positioning opportunities for migration-tested film suppliers entering food processing expansion. Centralized kitchen infrastructure for institutional feeding drives bulk-format bag absorption. Maharashtra and Gujarat industrial corridors concentrate first-mover investments from international converters seeking compliance-aligned market entry.
Japan
Convenience store chains and ready-meal distributors sustain premium barrier film demand for sous vide and steam applications. METI circular economy guidelines influence material recovery design constraints for domestic converters. Kanto and Kansai metropolitan manufacturing belts anchor high-temperature laminate production for precision thermal performance requirements.
United Kingdom
Retail private-label programs adopt PETG-modified roasting bag films for seasonal poultry promotions to absorb margin pressure. UK REACH alignment with EU chemical restrictions constrains additive package selection for domestic converters. Food processing concentration in the Midlands and Greater Manchester absorbs specification-grade consistency requirements with HACCP-aligned documentation.
Cook-In-Bags Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail shelf presence commanding distinct capabilities from foodservice specification support. The vendor base organizes around three archetypes: integrated film extruders controlling resin conversion costs, compostable film specialists targeting sustainability-mandated procurement, and dominant retail brands leveraging mass merchandiser relationships. Competitive moves concentrate on capacity allocation flexibility for seasonal demand surges and qualification documentation depth for centralized healthcare procurement.
Among North American integrated packaging groups, Sealed Air Corporation and Reynolds Consumer Products exemplify divergent positioning archetypes. Sealed Air Corporation occupies a position anchored in film extrusion capabilities and foodservice technical support. Reynolds Consumer Products sits within the retail-dominated tier where shelf presence and seasonal promotional cycles determine volume allocation. ProAmpac represents the sustainability-specialist archetype with compostable film structures targeting foodservice accounts seeking single-use alternatives.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Reynolds Consumer Products |
| S.C. Johnson & Son |
| Packit Gourmet |
| M&Q Packaging |
| GRANITOL |
| Sirane Limited |
| UltraSource |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
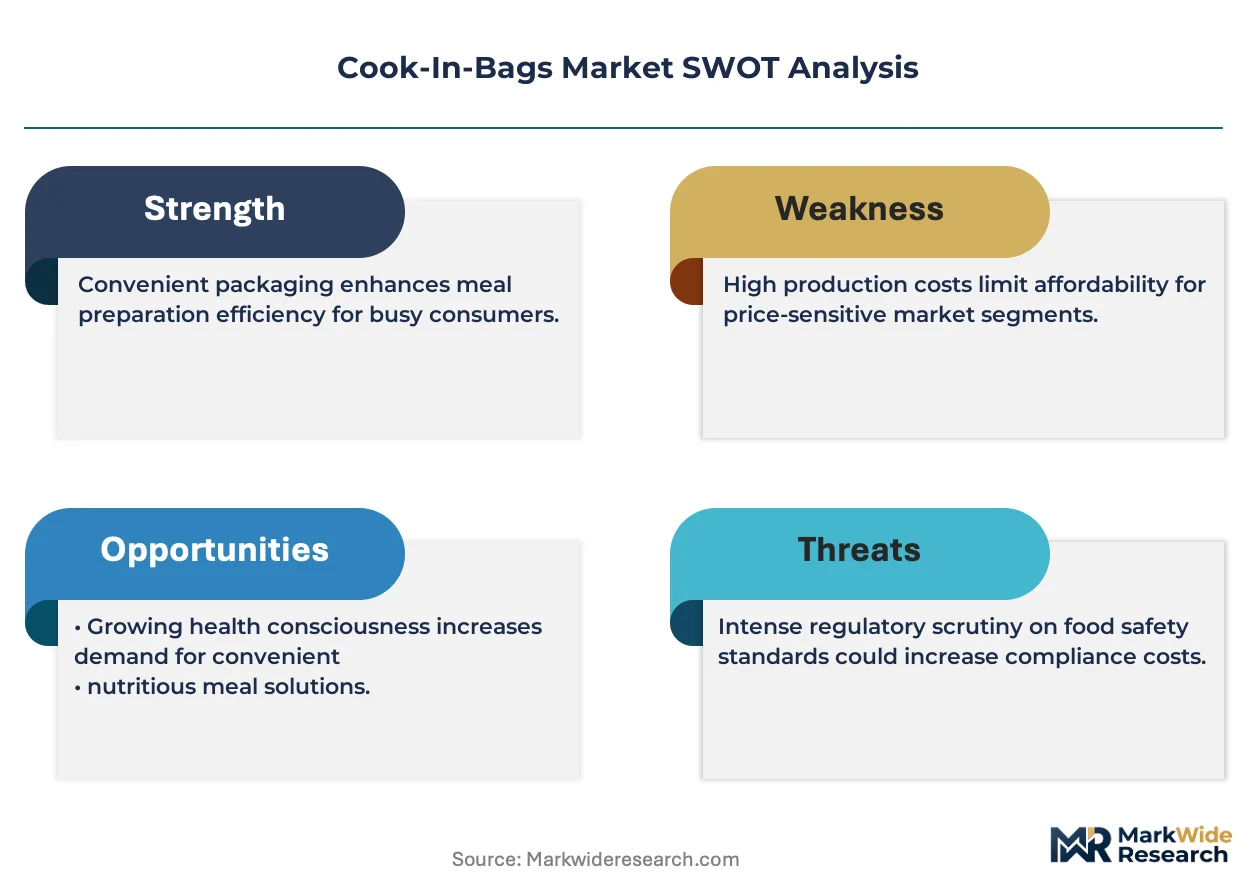
Caprolactam feedstock volatility from Asian petrochemical complexes transmits directly through polyamide laminate costs, compressing margin pools in barrier-tier cook-in-bags while PET glycol-modified alternatives absorb mid-tier volume at reduced resin conversion economics.
Pricing Analysis
Volume concentrates in commodity polyethylene steam bags where per-unit margins compress below viable conversion thresholds for smaller extruders. Three-tier pricing structure across premium, standard, and economy levels separates HACCP-documented food processing specifications from retail private-label programs and institutional bulk formats. Pricing pressure stems from centralized healthcare procurement consolidation demanding specification-grade documentation at contract-tier rates. Food processing buyers exhibit lowest price sensitivity due to HACCP compliance requirements, while household retail channels absorb promotional discounting cycles.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke patterns for migration-tested film inventory. Resin supply draws from caprolactam producers in Germany and China, PET feedstock from United States Gulf Coast complexes, and compostable polymer from certified European converters. Single-source vulnerability concentrates in FDA-validated additive packages where notification queue delays extend qualification timelines. Distribution runs through foodservice distributors with extended payment terms and private-label inventory commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cook-in-bag converters face a vertical-integration race as backward control over resin conversion and additive validation becomes the decisive cost lever against margin compression.
For Market Incumbents: Acquire FDA-validated additive package suppliers to compress migration testing timelines and defend specification-grade positioning against PET glycol-modified substitutes. Expand extrusion capacity in Texas and Ohio metropolitan clusters to capture healthcare foodservice procurement consolidation. Secure captive supply of caprolactam-grade resins to buffer Asian feedstock volatility transmission. For New Entrants and Emerging Players: Cloud kitchen infrastructure operators represent the most penetrable channel partner type for pre-portioned protein bag formats in urban United States delivery clusters. Target compostable film demand from EU-mandated procurement programs where industrial composting infrastructure gaps create first-mover qualification advantages. Pursue direct technical support contracts with multi-unit restaurant chains standardizing cook-in-bag protocols. For Investors and Strategic Acquirers: FDA notification queue clearance for novel polymer additives is the leading indicator that migration-tested film suppliers will capture accelerated specification renewals. Long-term viability centers on converters with integrated extrusion capabilities and direct healthcare procurement relationships. Monitor EU Packaging and Packaging Waste Regulation enforcement depth as the signal for compostable infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Conversion | Sealed Air Corporation's captive extrusion capabilities control polyamide and PET feedstock costs across North American plants. |
| Compostable Film Certification Investment | ProAmpac's certified biodegradable structures align with EU Packaging and Packaging Waste Regulation extended producer responsibility mandates. |
| Healthcare Procurement Consolidation Capture | National converters with HACCP-aligned documentation absorb vendor roster compression among Texas, Florida, and Ohio hospital systems. |
| Migration Testing Capacity Expansion | FDA notification queue management accelerates product launch timelines for novel polymer additive formulations. |
| Cloud Kitchen Channel Partnership | Pre-portioned protein bag formats eliminate on-site fabrication in United States urban ghost kitchen clusters. |
Research Methodology
Trade publications, customs records, and SEC filings from packaging converters formed the secondary backbone, cross-referenced with primary interviews involving film extrusion plant managers, foodservice procurement leads at multi-unit restaurant chains, FDA regulatory affairs specialists, and healthcare group purchasing organization contract managers. Bottom-up volume estimates from extrusion line capacity and top-down demand validation from end-use consumption patterns were triangulated to produce market sizing.
Historical trendline analysis of resin cost transmission, seasonal demand patterns, and specification-grade pricing premiums informed the projection framework across the analysis window. Segmentation modeling incorporated product type, material platform, end-use application, and geographic regulatory cluster dimensions. CAGRs were derived from installed capacity expansion announcements, migration testing pipeline visibility, and procurement standardization trends among United States foodservice operators.
Caveats apply where FDA notification queue delays, EU REACH restriction scope expansion, or industrial composting infrastructure deployment rates could materially shift the outlook. Forecasts reflect documented assumptions regarding resin cost transmission elasticity and healthcare procurement consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Spreads Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Dehydrated and Dried Beans Market
Packaged Foods
Packaged Currants Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
North America Pasta Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market