
 Packaged Currants Market | 2026-2036
Packaged Currants Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Currants Market Outlook
EU F-Gas Regulation is pivoting dehydration economics for European currant processors, raising capital requirements for controlled-atmosphere drying infrastructure. Sun-Maid Growers of California leverages its integrated Central Valley supply chain to sustain cost advantages in North American retail channels. AGRANA Beteiligungs-AG anchors its position through backward integration into Austrian and Polish fruit cooperatives, while Döhler Group competes via formulation partnerships with industrial bakery customers.
Packaged currants are dried, processed berries of the Ribes genus, typically preserved at 14-16% moisture content through hot-air or solar dehydration to inhibit microbial activity and extend shelf life. They function primarily as inclusion ingredients in baked goods, confectionery, and ready-to-eat cereals where water activity control determines texture stability. Dried currants dominate volume flows due to established industrial procurement contracts, while organic currants command margin premiums as clean-label bakery formulations expand. The baking application segment leads value capture, though snack-oriented resealable packaging formats are accelerating fastest in retail channels.
EU F-Gas Regulation and REACH compliance shape equipment investment timelines for European processors, while FDA enforcement of FSMA preventive controls governs U.S. import acceptance criteria for dried fruit lots. USDA organic certification and EU organic regulation create dual-track compliance burdens for suppliers serving both Atlantic markets. Stakeholders must monitor evolving pesticide maximum residue limits across EU, U.S., and emerging market jurisdictions to anticipate supply disruption risks and reposition sourcing networks accordingly.
Market Dynamics
EU F-Gas Regulation is forcing European currant processors to replace conventional refrigerant-based drying systems with heat-pump or solar-thermal alternatives, raising capital thresholds and reshaping competitive positioning between integrated and non-integrated suppliers.
Growth Catalysts
- Clean-label bakery reformulation:Industrial bakers in Germany and Austria are substituting currants for higher-cost dried cranberries and cherries in standard loaves and seasonal stollen, expanding volume commitments.
- REACH-compliant processing infrastructure:ECHA enforcement timelines are accelerating equipment replacement cycles, favoring processors with capital reserves to install controlled-atmosphere dehydration lines ahead of compliance deadlines.
- Snack-channel packaging innovation:Resealable stand-up pouches with moisture-barrier films are displacing traditional carton formats in UK and Netherlands retail, extending shelf visibility and household penetration.
Market Restraints
- Input cost volatility in natural gas:Thermal dehydration remains energy-intensive; spot price swings in European gas markets directly compress processor margins during contract-renewal windows.
- Supply concentration in Polish cooperatives:Backward integration by major processors has locked up significant black currant acreage, limiting spot-market availability for smaller compounders.
- Substitution threat from sultanas:Turkish seedless raisins trade at persistent discounts to currants, pressuring inclusion ratios in cost-sensitive industrial bakery formulations.
Strategic Opportunities
- Underpenetrated US specialty retail:American consumers show low recognition of currants versus raisins; targeted placement in natural-food channels could build category awareness.
- EU organic regulation premiums:Dual-certified organic currants command significant price spreads in German and Swiss markets, rewarding processors with cooperative conversion programs.
- Convergence of solar-thermal and IoT monitoring:Integrated sensor networks enabling real-time moisture tracking during sun-drying are reducing spoilage rates in Mediterranean processing zones.
Industry Challenges
- FSMA preventive controls compliance:FDA enforcement of foreign supplier verification programs creates documentation burdens for European exporters targeting US food manufacturers.
- Heat-pump technician scarcity:Installation and maintenance of F-Gas-compliant drying equipment requires specialized HVAC expertise that remains concentrated in German and Austrian service markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Currants Market |
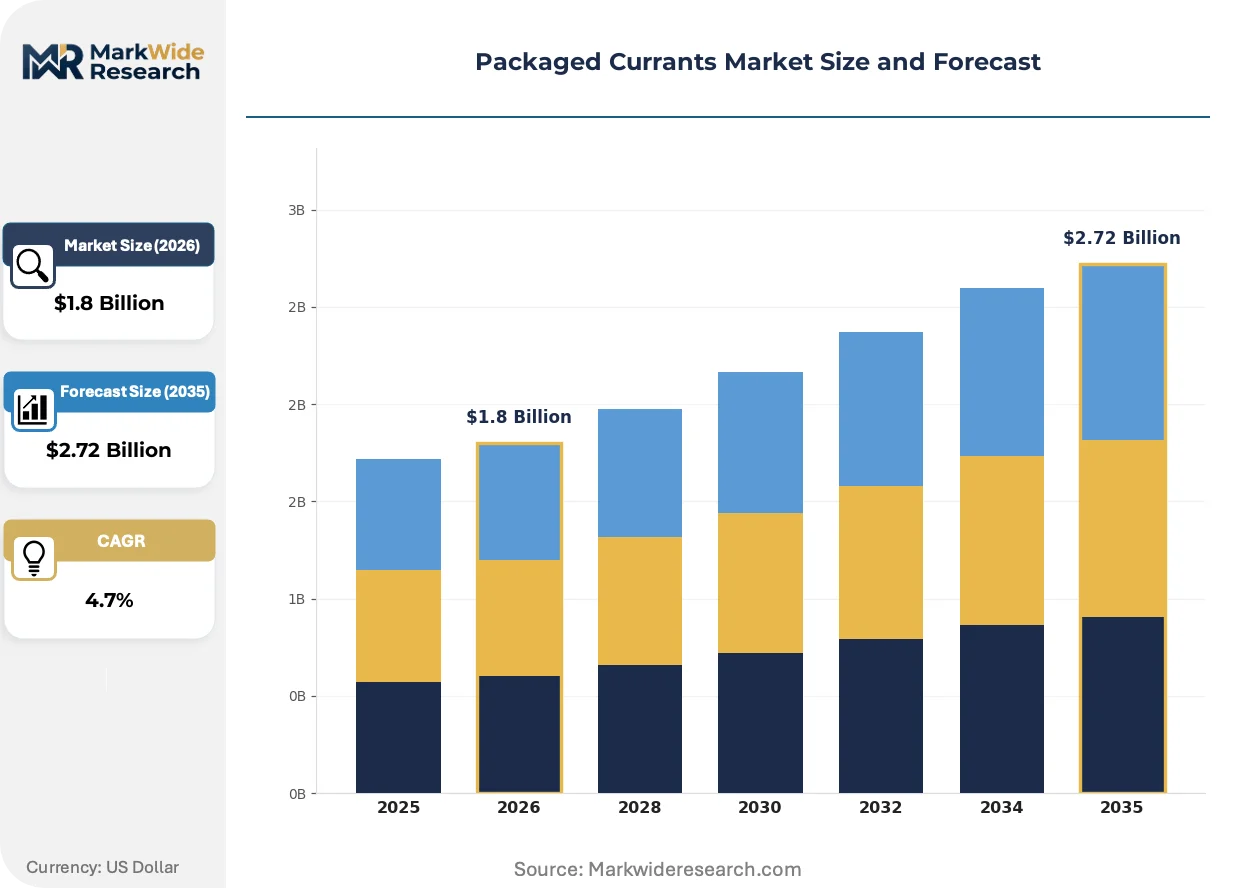
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Currants, Dried Currants, Sweetened Currants, Unsweetened Currants Application: Baking, Snacks, Breakfast Foods, Desserts Packaging Type: Resealable Bags, Boxes, Bulk Packaging, Glass Jars End Use Industry: Food & Beverage, Confectionery, Bakery, Retail |
| Companies Covered | Sun-Maid Growers of California, Ocean Spray, AGRANA Beteiligungs-AG, Döhler Group, Welch's, Kabako Gruppe, Karelia Berries, Special Fruit NV, Lion Raisins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Currants Market Strategic Shifts
Dehydration technology and procurement patterns are shifting in parallel, with regulatory pressure on emissions and clean-label pressure on formulations driving concurrent investment in process control and supply-chain transparency.
Controlled-atmosphere heat-pump drying is consolidating as the dominant technology platform for premium currant production. Austrian and German processors with existing engineering capabilities are retrofitting legacy hot-air tunnels. This consolidation is compressing the cost gap between conventional and organic-dedicated processing lines.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition timelines across Central European fruit-processing zones. Processors face stranded-asset risk in conventional compression-based cold stores. Smaller Polish cooperatives are responding through collective procurement consortia to share capital burdens.
Bakery procurement departments are tightening supplier qualification criteria beyond basic food safety to include carbon-footprint disclosure and water-stress mapping. Industrial compounders in Northern Europe now require third-party verified lifecycle data. This behavioral shift is most visible in German industrial bakery chains with published sustainability commitments.
Packaged Currants Market Segmentation
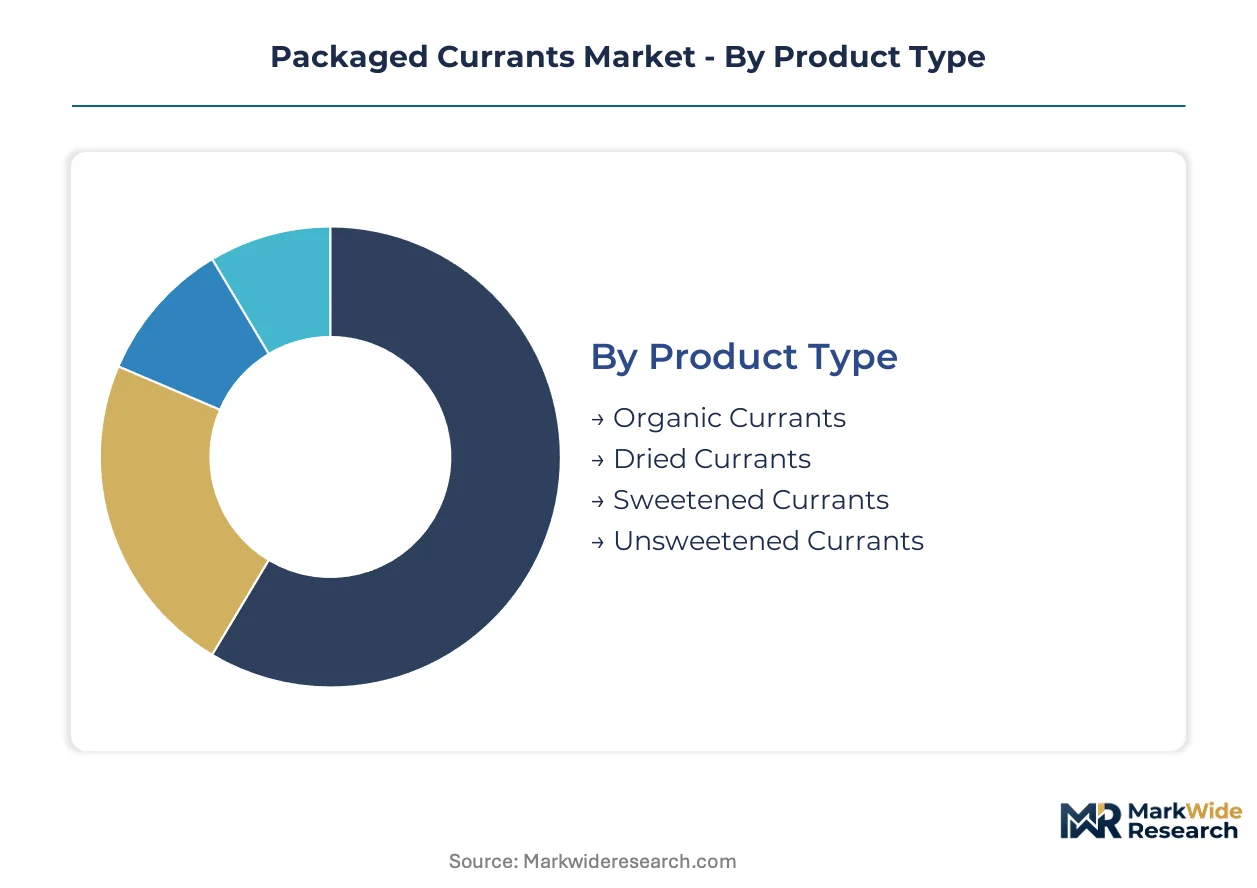
Segmentation in the packaged currants market reveals how procurement patterns diverge between commodity-driven industrial baking and premium-positioned retail channels. Understanding these splits enables processors to align drying infrastructure investments with margin profiles and compliance requirements.
Product Type:
Integration depth varies sharply: dried and unsweetened variants serve as embedded ingredients in industrial formulations, while organic and sweetened grades function as standalone retail propositions with distinct shelf-positioning strategies.
- Dried Currants:Hot-air dehydrated to 14-16% moisture content with sulfur dioxide retention below regulatory thresholds. Industrial bakers in Germany and Austria specify these for stollen and fruit loaves where water activity control determines shelf stability.
- Organic Currants:Cultivated without synthetic pesticides and processed on certified-only equipment. Swiss and German retail chains command substantial price premiums for dual EU-USDA certified lots, rewarding processors with cooperative conversion programs.
- Sweetened Currants:Infused with sucrose or grape juice concentrate post-dehydration to soften texture and extend palatability in direct-consumption formats.
- Unsweetened Currants:Retain natural tartness profile; preferred by clean-label formulators seeking minimal ingredient declarations.
Dried currants lead volumes today; organic currants are gaining share fastest.
Application:
Cost-tier stratification separates high-volume contract supply to industrial bakeries from emerging snack-channel formats with resealable packaging premiums.
- Baking:Dominant value capture through long-term procurement contracts with industrial compounders. German artisan and industrial bakers substitute currants for higher-cost dried cranberries in standard formulations, expanding volume commitments.
- Snacks:Resealable stand-up pouches with moisture-barrier films are displacing carton formats in UK and Netherlands retail, extending shelf visibility and household penetration rates.
- Breakfast Foods:Inclusion in muesli and granola formulations where texture contrast with oats drives specification.
- Desserts:Premium positioning in fruit compotes and pastry fillings with shorter production runs and higher margin capture.
Baking commands the largest revenue pool; snack applications show the steepest expansion trajectory.
Packaging Type:
Volume concentration favors bulk and box formats for industrial procurement, while margin accrues to resealable and glass formats targeting household pantry replenishment cycles.
- Resealable Bags:Stand-up pouches with oxygen-scavenging films enable extended shelf life in ambient retail conditions. UK supermarket chains are accelerating format conversion for dried fruit aisles.
- Bulk Packaging:10-25kg food-grade liners for industrial compounders and bakery manufacturing facilities with automated handling systems.
- Boxes:Traditional carton formats with inner moisture barriers; declining share in retail but retained for seasonal gift positioning.
- Glass Jars:Premium positioning in specialty food channels with visual product clarity and reuse appeal.
Bulk packaging leads volumes today; resealable bags are climbing the fastest.
End Use Industry:
Customer-type differentiation separates procurement through centralized industrial contracts from fragmented retail distribution with distinct qualification requirements.
- Food & Beverage:Broadest category spanning cereal manufacturers, dairy processors, and beverage infusion applications with varying moisture and particle-size specifications.
- Bakery:Dedicated procurement teams in German industrial chains now require carbon-footprint disclosure and water-stress mapping beyond baseline food safety certification.
- Confectionery:Chocolate enrobing and fruit-nut bar applications with stringent microbiological thresholds and foreign-matter detection protocols.
- Retail:Direct-to-consumer channels with SKU proliferation pressures and shorter order cycles demanding flexible packaging runs.
Bakery leads volumes today; retail channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled dehydration engineers and food-processing technicians concentrate in Central European fruit-processing clusters, particularly around Vienna, Warsaw, and Stuttgart, where multi-generational expertise in controlled-atmosphere drying anchors regional supply capacity.
Germany
Industrial bakery procurement teams in Munich and Hamburg drive premium currant demand for stollen and fruit-loaf production. ECHA enforcement of REACH compliance accelerates equipment replacement timelines across Bavarian processing facilities. The Lake Constance fruit-growing corridor hosts specialized cooperatives supplying organic-certified raw material to domestic dehydrators.
Poland
Black currant cultivation concentrates in Podlaskie and Warmian-Masurian provinces, supplying raw material to integrated processors. EU F-Gas Regulation phase-down schedules force cooperative consortia to pool capital for heat-pump drying infrastructure. The Białystok agro-industrial cluster anchors backward integration programs linking field operations to packaged-fruit export terminals.
United States
Natural-food retail channels in California and the Northeast show underpenetrated currant recognition relative to raisins, creating category-building opportunities. FDA enforcement of FSMA preventive controls governs import acceptance criteria for European dried-fruit lots. California's Central Valley hosts vertically integrated raisin-currant processors leveraging shared solar-thermal drying infrastructure.
Austria
Dual EU-USDA organic certification programs in Lower Austria command substantial price premiums in Swiss and German retail channels. The country's national food safety regulator enforces strict pesticide maximum residue limits that shape cooperative cultivation protocols. The Weinviertel region anchors AGRANA's captive supply networks for premium bakery-grade currants.
United Kingdom
Resealable stand-up pouch formats accelerate format conversion in Tesco and Sainsbury's dried-fruit aisles, displacing traditional carton packaging. The Food Standards Agency monitors evolving import documentation requirements for post-Brexit EU fruit shipments. Greater Manchester distribution hubs consolidate cross-channel logistics for processors serving both UK and Irish retail markets.
Packaged Currants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with the former leveraging cross-fruit portfolios and the latter commanding margin premiums through organic certification depth. Market structure shows moderate consolidation at the processing level alongside fragmented cultivation bases in Polish and Austrian cooperatives. Two strategic archetypes dominate: integrated processors with captive supply networks, and formulation-focused ingredient houses serving industrial bakery compounders. Capacity expansion and cooperative backward integration represent the dominant competitive moves reshaping supply access.
Among California-based agricultural cooperatives, Sun-Maid Growers of California occupies a position exemplifying scale-driven integration across dried-fruit categories. Austrian-incorporated AGRANA Beteiligungs-AG anchors the European tier through cooperative supply relationships, while German-structured Döhler Group represents the formulation-partnership archetype serving industrial bakery customers with application-specific ingredient systems. These three entities collectively illustrate the geographic and strategic segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Sun-Maid Growers of California |
| Ocean Spray |
| AGRANA Beteiligungs-AG |
| Döhler Group |
| Welch's |
| Kabako Gruppe |
| Karelia Berries |
| Special Fruit NV |
| Lion Raisins |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between dual EU-USDA organic currants and conventional dried variants manifests in parallel pricing premiums and supply chain segregation, with certified processors commanding captive cooperative networks while commodity suppliers compete on spot-market sulfur dioxide thresholds.
Pricing Analysis
The unbundled service model dominates industrial procurement, with bakery compounders purchasing bulk currants on long-term offtake contracts while specialty retailers absorb premium markups for resealable pouch formats with oxygen-scavenging films. Price differentiation rests on certification depth and moisture-barrier packaging sophistication. Pricing pressure intensifies in conventional grades as Turkish sultanas erode inclusion ratios in cost-sensitive formulations. Industrial bakery procurement teams show highest price sensitivity, whereas Swiss and German organic retail channels exhibit inelastic demand for dual-certified lots.
Supply Chain Analysis
Regional distribution centers in Greater Manchester and Rotterdam anchor hub-and-spoke patterns for UK and Benelux retail channels, while direct rail links from Białystok serve Central European industrial compounders. Raw material flows concentrate in Poland, Austria, and Germany, with black currant cultivation tethered to Podlaskie province and Lake Constance cooperatives. Energy input costs—natural gas for thermal dehydration and electricity for heat-pump retrofits—constitute the primary supply chain vulnerability. Distribution runs through integrated processor networks for premium grades and fragmented spot markets for commodity lots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaged currants market functions as a stable compounder anchored by enduring bakery traditions in German-speaking Europe, where currant-based stollen and fruit-loaf consumption sustains predictable procurement cycles regardless of macroeconomic volatility.
For Market Incumbents: Anchor market position through backward integration into Polish and Austrian fruit cooperatives before EU F-Gas compliance deadlines strand conventional drying assets. Prioritize heat-pump technician training partnerships with German HVAC service networks to preempt maintenance bottlenecks. Defend against Turkish sultana substitution by locking multi-year contracts with industrial bakery chains requiring carbon-footprint disclosure.
For New Entrants and Emerging Players: The premium-to-economy price gap in US natural-food channels offers viable entry terrain, as American consumer recognition of currants lags raisins by substantial margins. Target specialty retail placement in California and Northeast corridors with education-focused sampling programs. Pursue co-manufacturing arrangements with established dehydrators rather than greenfield processing investments.
For Investors and Strategic Acquirers: Consolidation pressure builds where F-Gas retrofit capital requirements exceed smaller Polish cooperative balance sheet capacity. Frame long-term viability around organic certification depth and captive supply network control rather than commodity volume scale. Monitor ECHA enforcement timelines as inflection signals for distressed acquisition opportunities in Central European processing clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Drying Infrastructure Retrofit | Ensures EU F-Gas Regulation compliance ahead of refrigerant phase-down deadlines. |
| Cooperative Backward Integration | Locks black currant acreage in Podlaskie and Warmian-Masurian provinces against spot-market competition. |
| Dual Organic Certification Program | Captures price premiums in Swiss and German retail chains demanding EU-USDA verification. |
| Resealable Pouch Format Conversion | Aligns with Tesco and Sainsbury's packaging transitions in UK dried-fruit aisles. |
| Solar-Thermal Drying Expansion | Reduces natural gas exposure in Mediterranean processing zones through IoT-monitored sun-drying. |
Study Parameters
Bottom-up bakery and snack-channel modeling reconciled against top-down dehydration capacity tracking forms the analytical core of this study. Primary interviews with fruit cooperative managers, industrial bakery procurement directors, and retail category buyers at UK and German supermarket chains were validated against secondary sources including EU F-Gas Regulation implementation reports, ECHA REACH compliance databases, and customs trade records for dried fruit shipments. This dual approach enables cross-verification of volume flows with processor capital expenditure patterns.
Historical trendline analysis of procurement contract tenors and equipment replacement cycles informed the projection framework across the analysis window. Segmentation dimensions encompass product type, application channel, packaging format, and end-use industry, with organic certification status treated as a cross-cutting variable. CAGRs were derived from fitted growth curves applied to verified baseline volumes, incorporating energy cost trajectories and regulatory compliance timelines as industry-specific forecast inputs.
Caveats apply where natural gas price volatility or accelerated ECHA enforcement could materially shift the outlook for processor margin structures and cooperative consolidation timing. Forecasts reflect documented assumptions regarding F-Gas phase-down adherence and bakery substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Pasta Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Canned Soup Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Bangladesh Instant Noodles Market