
 Spreads Market | 2026-2036
Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Spreads Market Outlook
Breakfast-away-from-home consumption is shifting toward grab-and-go formats, redirecting spread demand from table-service restaurants to quick-service bakeries and café chains. Mondelēz International leverages its global biscuit-and-spread pairing strategy to sustain cross-category pull. The Kraft Heinz Company anchors North American retail shelf space through private-label and branded co-existence. Unilever competes in emerging markets with regionally adapted flavor profiles and localized sourcing.
Spreads are semi-solid food preparations formulated from fats, oils, proteins, or sweeteners, typically containing between 10% and 80% fat content depending on category, designed for application on bread, crackers, or as recipe ingredients. Nut butter commands premium positioning due to protein-density labeling and allergen-management requirements. Sweet flavor profiles dominate volume but savory variants are gaining traction in foodservice channels. Tub packaging leads household penetration while pouches are expanding in single-serve hospitality settings.
FDA nutrition labeling rules, EU F-Gas Regulation affecting cold-chain distribution, and EFSA health claim assessments collectively shape permissible formulations and marketing claims across jurisdictions. Compliance costs favor scaled manufacturers with dedicated regulatory affairs functions. Stakeholders must monitor evolving front-of-pack labeling schemes and their impact on consumer switching behavior between premium and private-label tiers.
Market Dynamics
Clean-label reformulation pressures are compressing development timelines as manufacturers reconcile FDA added-sugar disclosure mandates with consumer taste expectations. The tension between transparency requirements and sensory performance now dictates capital allocation across R&D functions.
Growth Catalysts
- Protein-density labeling:Nut butter positioning leverages nutritional transparency to command shelf space in United States retail channels.
- EU F-Gas Regulation:Cold-chain efficiency upgrades are accelerating distribution network modernization for temperature-sensitive spread categories.
- Quick-service bakery expansion:Grab-and-go breakfast formats are redirecting volume from traditional foodservice toward café-chain and bakery-café channels.
Market Restraints
- Edible oil price volatility:Palm and sunflower oil input costs fluctuate with climate-driven supply disruptions in Southeast Asian and Black Sea sourcing regions.
- Allergen management complexity:Segregated production lines for peanut, tree-nut, and seed-based spreads inflate facility capital requirements.
- Private-label substitution:Retailer-owned brands in mainstream United States channels compress margin realization for national branded portfolios.
Strategic Opportunities
- Savory spread white space:Foodservice operators in the United States are testing vegetable-forward and fermented profiles for sandwich and appetizer applications.
- Single-serve hospitality formats:Pouch packaging is displacing portion cups in hotel and airline breakfast programs.
- EFSA health claim pathways:Validated cardiovascular or satiety claims could unlock premium positioning in European retail.
Industry Challenges
- Reformulation talent scarcity:Food scientists with dual competence in clean-label ingredient functionality and sensory mapping command premium compensation.
- Front-of-pack labeling compliance:Divergent warning systems across United States, Mexican, and Canadian jurisdictions multiply packaging SKUs.
- Legacy equipment retrofit costs:Existing filling and sealing lines require modification for reduced-fat and alternative-protein formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spreads Market |
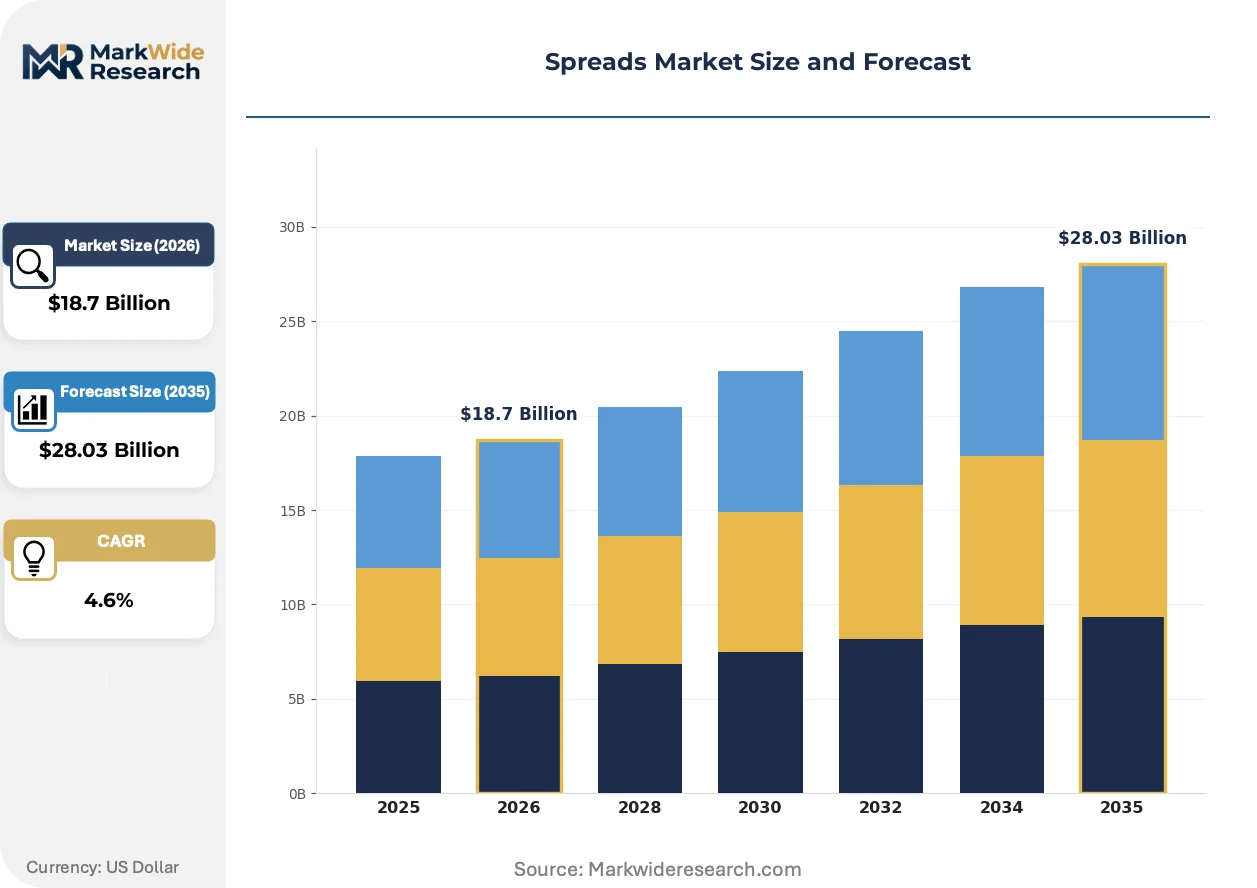
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Cream Cheese, Nut Butter Flavor Profile: Sweet, Savory, Spicy, Herbal Packaging Type: Tub, Jar, Pouch, Bottle End User: Households, Restaurants, Cafés, Bakeries |
| Companies Covered | Pioneer Food Group Ltd, Mondelēz International, The Kraft Heinz Company, Unilever, Mars, Nestlé S.A., The Hershey Company, Ferrero, Conagra Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spreads Market Strategic Shifts
Automation and regulatory transparency are converging to reshape how spreads are formulated, labeled, and distributed across retail and foodservice channels.
High-pressure processing technology is automating microbial reduction in nut-based and dairy-alternative spreads without thermal degradation of flavor compounds. Mid-sized United States manufacturers are piloting these systems to extend refrigerated shelf life while preserving clean-label positioning. The capital efficiency of automated pasteurization is compressing the historical advantage of large-scale thermal processing infrastructure.
The FDA's updated Nutrition Facts panel mandates for added sugars disclosure are forcing reformulation of sweetened spreads and fruit preserves. Manufacturers serving the United States market are accelerating sugar-reduction programs and exploring high-intensity natural sweeteners. Bakery applications face the steepest compliance curve given their dependence on browning reactions and moisture retention from sucrose.
Retail buyers are consolidating supplier relationships and demanding turnkey category management services from core spread vendors. United States supermarket chains are reducing the number of branded SKUs in favor of private-label and exclusive co-manufactured lines. This concentration is visible in peanut butter and fruit spread categories where shelf resets now occur on 18-month rather than 12-month cycles.
Spreads Market Segmentation
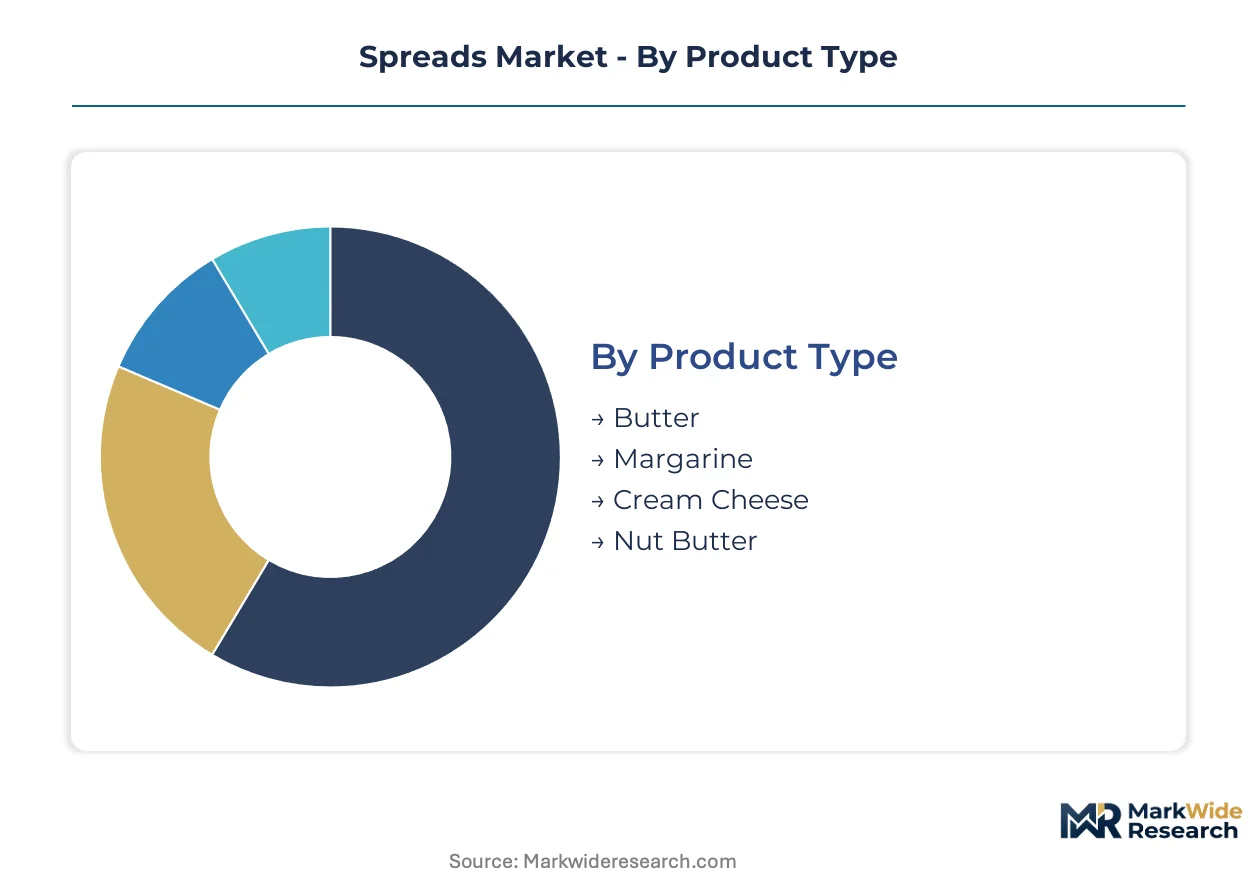
Spreads manufacturers align formulation, packaging, and distribution strategies against distinct buyer requirements across retail and foodservice channels. Segment boundaries determine capital allocation priorities from cold-chain infrastructure to portion-control formats.
Product Type:
Buyers in this category differentiate primarily by fat-content specifications and protein-density claims that determine shelf positioning and price tier access.
- Butter:Churned cream with minimum 80% milk fat content delivers irreplaceable flavor chemistry for laminated dough applications. United States retail buyers prioritize domestic sourcing credentials amid volatile global dairy trade flows.
- Nut Butter:Ground legume or tree-nut preparations with 25-30% protein density command premium placement through nutritional transparency labeling. FDA allergen disclosure mandates drive segregated production investments that inflate per-unit facility costs.
- Margarine:Vegetable oil emulsions with tunable fat content (10-80%) enable cost-engineered alternatives for institutional baking. Reformulation pressures intensify as palm oil sustainability scrutiny reshapes sourcing strategies.
- Cream Cheese:Fresh acid-set dairy spread with 33% milk fat minimum anchors bagel-shop and dessert applications. Cold-chain requirements constrain distribution radius for perishable formulations.
Butter leads volumes today; nut butter is gaining share fastest.
Flavor Profile:
Application context—breakfast occasion versus savory meal preparation—determines flavor procurement patterns and inventory turnover velocity.
- Sweet:Sugar-forward formulations (fruit preserves, chocolate-hazelnut) dominate household penetration through breakfast ritual anchoring. EFSA health claim restrictions limit permissible positioning around energy or satiety benefits.
- Savory:Vegetable-forward and fermented profiles target sandwich-build and appetizer applications in United States foodservice testing. Clean-label reformulation complexity exceeds sweet variants due to umami chemistry requirements.
- Spicy:Capsicum-infused spreads capture ethnic cuisine crossover demand in café-chain limited-time offerings. Heat-level standardization challenges constrain national rollout velocity.
- Herbal:Botanical infusions (basil, rosemary, tarragon) occupy niche positioning for premium cracker pairings and recipe ingredient use. Seasonal herb supply volatility compresses margin consistency.
Sweet formulations anchor current revenue; savory variants show steepest expansion trajectory.
Packaging Type:
Channel economics—household pantry stocking versus single-serve hospitality consumption—drive format selection and line-speed investments.
- Tub:Wide-mouth polypropylene containers maximize scoopability for household refrigerator storage and high-frequency use occasions. United States supermarket chains specify tamper-evident lidding as a category-entry requirement.
- Pouch:Flexible film formats displace rigid portion cups in hotel and airline breakfast programs through waste-reduction compliance. Filling equipment retrofit costs delay adoption among legacy manufacturers.
- Jar:Glass or polyethylene terephthalate containers preserve premium perception for gift and specialty retail channels. Weight-based freight penalties constrain e-commerce viability.
- Bottle:Squeeze dispensers target liquid and semi-liquid honey or syrup spreads in foodservice speed-scratch applications. Viscosity engineering requirements limit formulation flexibility.
Tub packaging dominates household penetration; pouch formats are displacing rigid alternatives fastest in hospitality.
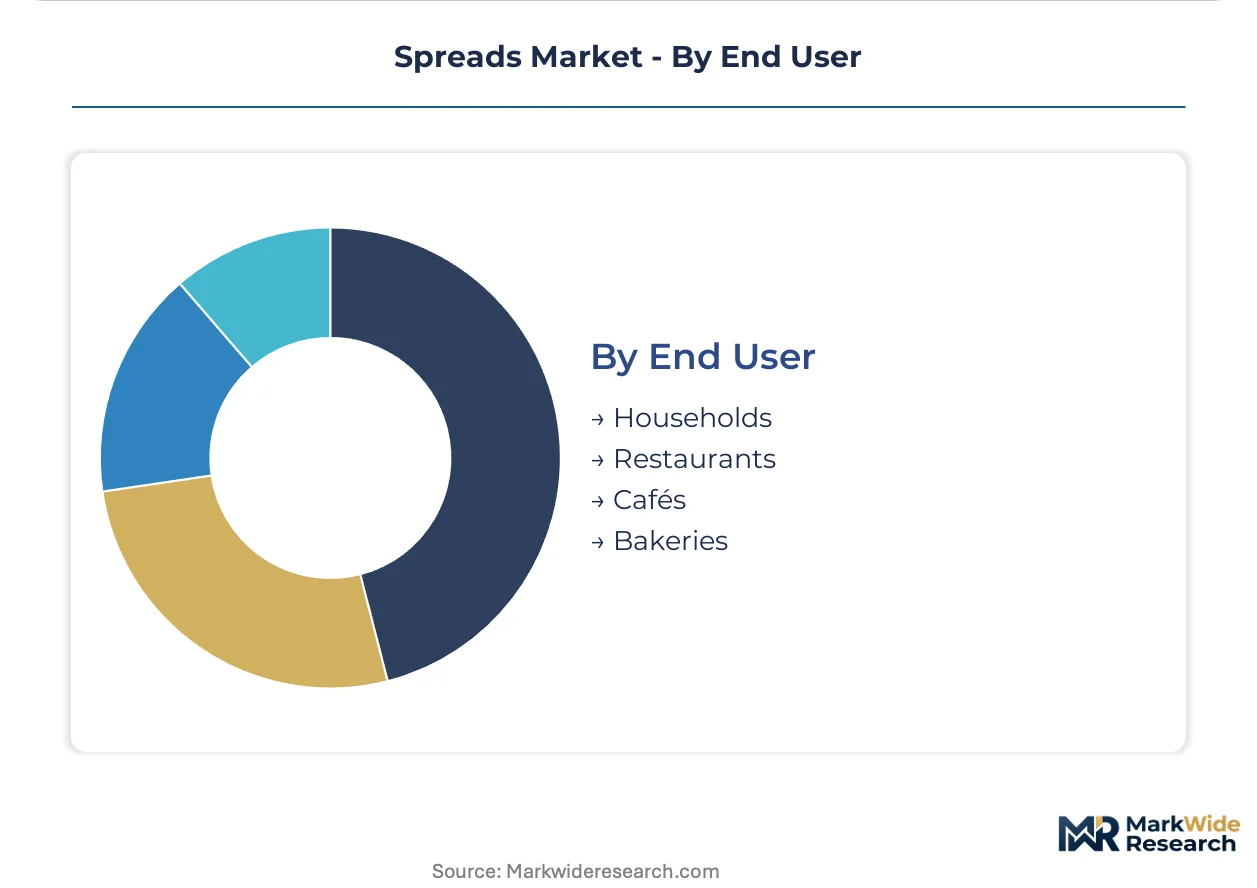
End User:
Operational scale and procurement authority concentration separate mass retail from fragmented foodservice buying centers.
- Households:Individual consumers select spreads based on front-of-pack labeling clarity and pantry-stock replenishment cycles. Private-label substitution accelerates as United States retailers consolidate supplier relationships.
- Restaurants:Full-service operators specify spreads for table-bread programs and recipe ingredients with cost-per-portion discipline. Labor-intensive portioning drives interest in pre-measured formats.
- Cafés:Quick-service bakery chains demand turnkey category management with consistent supply for grab-and-go breakfast attachment. Menu localization requirements multiply SKU complexity across regional markets.
- Bakeries:Artisan and industrial producers source spreads as formulation inputs for filled pastries and laminated products. Clean-label mandates from retail grocery clients cascade backward through ingredient specifications.
Households anchor volume absorption; cafés are redirecting demand fastest from traditional foodservice channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate formulation capacity to jurisdictions with streamlined compliance pathways. Cost-of-compliance gaps between the United States and emerging production hubs are accelerating facility investment decisions.
United States
Private-label penetration in mainstream retail channels is concentrating procurement authority among supermarket chains. FDA updated nutrition labeling mandates for added sugars disclosure are compressing reformulation timelines for sweetened spreads. Chicago and New Jersey corridor facilities are retrofitting legacy filling lines to accommodate reduced-fat and alternative-protein formulations.
Germany
EU F-Gas Regulation is driving cold-chain efficiency upgrades across temperature-sensitive spread distribution networks. EFSA health claim assessments are shaping permissible cardiovascular positioning for nut butter categories. Bavaria-based industrial bakeries are sourcing clean-label margarine alternatives for laminated dough applications.
United Kingdom
Grab-and-go breakfast formats are redirecting spread demand from traditional foodservice toward quick-service bakery chains. Front-of-pack labeling schemes are influencing consumer switching behavior between premium and private-label tiers. Greater London café-chain procurement is consolidating supplier relationships around turnkey category management services.
China
Urban household pantry stocking patterns are shifting toward protein-density labeled nut butters in tier-one cities. SAMR food safety standards are elevating facility certification requirements for imported spread formulations. Yangtze River Delta manufacturing clusters are scaling pouch packaging capacity for hospitality single-serve formats.
Brazil
ANVISA regulatory harmonization is reducing import friction for multinational spread portfolios. Palm oil sustainability scrutiny is reshaping sourcing strategies for margarine manufacturers. São Paulo-state industrial bakeries are testing savory vegetable-forward spread profiles for sandwich applications.
Spreads Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers reconcile clean-label mandates with sensory performance requirements. The vendor base stratifies across three tiers: multinational packaged-food conglomerates with dedicated regulatory affairs functions, regional specialists with localized flavor adaptation capabilities, and private-label co-manufacturers serving consolidated retail buyers. Strategic archetypes include scale-driven thermal processing operators, high-pressure processing technology adopters, and turnkey category management providers. M&A activity and capacity expansion in automated pasteurization systems represent the dominant competitive moves.
Within the multinational tier, Mondelēz International, The Kraft Heinz Company, and Unilever exemplify divergent geographic and channel strategies. Mondelēz International represents global biscuit-and-spread pairing integration. The Kraft Heinz Company anchors North American retail shelf space through branded and private-label co-existence. Unilever occupies emerging-market positioning through regionally adapted flavor profiles. Each exemplifies how scale, regulatory competence, and channel-specific format innovation determine competitive position.
| Leading Market Players |
|---|
| Pioneer Food Group Ltd |
| Mondelēz International |
| The Kraft Heinz Company |
| Unilever |
| Mars |
| Nestlé S.A. |
| The Hershey Company |
| Ferrero |
| Conagra Brands, Inc. |
| Others |
Value Chain & Pricing Dynamics
Palm oil futures and sunflower seed costs transmit volatility directly through margarine and nut butter pricing tiers, compressing margins at the economy end while premium positioning absorbs input spikes through brand equity buffers. Retailer consolidation in United States channels amplifies this dynamic, as national chains leverage procurement scale to extract concessions that reshape supplier margin allocation across standard and premium lines.
Pricing Analysis
Distributor margins in United States foodservice channels absorb the steepest compression as quick-service bakery chains consolidate purchasing around turnkey category management contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein-density certification and clean-label ingredient sourcing, with nut butter commanding shelf space premiums against commodity margarine. Pricing pressure stems from private-label substitution accelerating in mainstream retail channels. Household consumers exhibit highest price sensitivity, while institutional bakeries prioritize cost-per-portion stability over absolute unit cost.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale United States supermarket demand, while foodservice distribution runs through broadline distributors with regional cold-chain specialization. Manufacturing concentrates in United States Midwest dairy corridors, Malaysian palm oil processing zones, and Black Sea sunflower crushing facilities. Formulation draws from palm oil, sunflower oil, and tree-nut inputs with climate-driven harvest volatility. Single-source vulnerability in Southeast Asian palm supply exposes margin stability to El Niño disruption patterns. Segregated allergen production lines constrain capacity flexibility for nut butter categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spreads market functions as a stable compounder anchored by breakfast ritual persistence and reformulation-driven replacement cycles that sustain manufacturer relevance across decades.
For Market Incumbents: Anchor shelf space dominance through backward integration into tree-nut processing and segregated allergen production capacity that raises rivals' facility capital requirements. Accelerate clean-label certification investment ahead of FDA added-sugar disclosure enforcement timelines. Private-label co-manufacturing relationships defend volume position against retailer-owned brand expansion. For New Entrants and Emerging Players: Enter via savory spread white space in United States foodservice channels, where vegetable-forward and fermented profiles lack established national suppliers. Target quick-service bakery chains testing sandwich-build applications with localized flavor adaptation capabilities that multinational portfolios cannot match. Pursue co-packing arrangements with legacy manufacturers to bypass filling equipment retrofit barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs favor scaled manufacturers with dedicated FDA and EFSA affairs functions. Five-to-ten year viability hinges on cold-chain infrastructure ownership and high-pressure processing technology adoption. Mid-sized United States manufacturers with clean-label positioning and automated pasteurization capacity represent priority acquisition archetypes. Monitor EFSA cardiovascular health claim approvals as inflection signal for European premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | FDA added-sugar disclosure mandates force sugar-reduction investment ahead of compliance deadlines. |
| High-Pressure Processing Adoption | Automated pasteurization extends refrigerated shelf life without thermal flavor degradation in nut butters. |
| Private-Label Co-Manufacturing Expansion | Retailer consolidation demands turnkey category management capabilities from core spread vendors. |
| Savory Spread Product Line Launch | Foodservice operators test vegetable-forward profiles for sandwich applications with limited incumbent competition. |
| Pouch Packaging Capacity Addition | Hotel and airline breakfast programs displace rigid portion cups with flexible film waste-reduction formats. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with category buyers at United States supermarket chains, formulation scientists at industrial bakeries, regulatory affairs directors at multinational manufacturers, and procurement leads at quick-service bakery operators with secondary validation from FDA labeling guidance documents, EFSA health claim registers, Nielsen retail audit data, and customs trade flow records. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-checked for consistency.
Segment-weighting approaches modeled volume and value trajectories across product type, flavor profile, packaging format, and end-user channel dimensions throughout the forecast period. CAGRs were derived from regression analysis against input cost indices and channel penetration curves. Forecast inputs incorporated FDA compliance timeline assumptions, EU F-Gas Regulation cold-chain investment requirements, and private-label share shift patterns in United States retail.
Inputs from regulatory filings and retail audit databases were available through the study window; gaps in real-time foodservice procurement data introduce uncertainty bands around hospitality channel projections. Forecasts reflect assumptions about clean-label adoption velocity and reformulation cost pass-through rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
United States Online Grocery Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Canned Soup Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Ready Meal Trays Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Eco Bowls Market
Packaged Foods
Global Packed Food Market