
 United Arab Emirates Food Products Market | 2026-2036
United Arab Emirates Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Food Products Market Insights
Private-label manufacturing revenue is rewriting margin distribution across the UAE food sector. Almarai Co. leverages its integrated dairy farming and processing footprint to dominate fresh milk supply in Abu Dhabi and Dubai. The Savola Group anchors edible oil and sugar refining through its industrial facilities in Jebel Ali. Agthia competes aggressively in bottled water and flour milling, while Al Islami Foods specializes in halal frozen meat products for Gulf re-export markets.
Food products in the UAE comprise processed, semi-processed, and fresh consumables governed by halal certification protocols, cold-chain integrity standards, and shelf-life parameters measured in days for perishables to months for UHT and retort-packaged goods. These items serve household consumption, hospitality procurement, and food manufacturing feedstock requirements across the Gulf Cooperation Council trade zone. Dairy products command premium shelf positioning in UAE supermarkets due to short replenishment cycles and temperature-controlled logistics requirements. Online retail channels for packaged foods are expanding fastest among distribution segments as delivery platforms consolidate last-mile networks. The premium price tier captures disproportionate margin pools in Dubai and Abu Dhabi, while economy-tier packaged foods sustain volume throughput through wholesaler networks serving northern emirates and labor accommodation camps.
MOHAP enforces halal certification and nutritional labeling standards that determine import eligibility for all food products entering UAE ports. The country's national food regulator also coordinates with ESMA on shelf-life testing protocols and additive permissibility lists that shape formulation decisions by manufacturers. FSSAI-aligned Indian exporters and EFSA-aware European suppliers must both adapt documentation to MOHAP's electronic import clearance platform. Stakeholders must monitor how the UAE's local content requirements under Operation 300bn and food security strategies redirect procurement toward domestic manufacturing partnerships rather than pure import dependence.
Market Dynamics
MOHAP's electronic import clearance platform and halal certification mandates are compressing documentation timelines while redirecting procurement toward domestic manufacturing partnerships under Operation 300bn.
Growth Catalysts
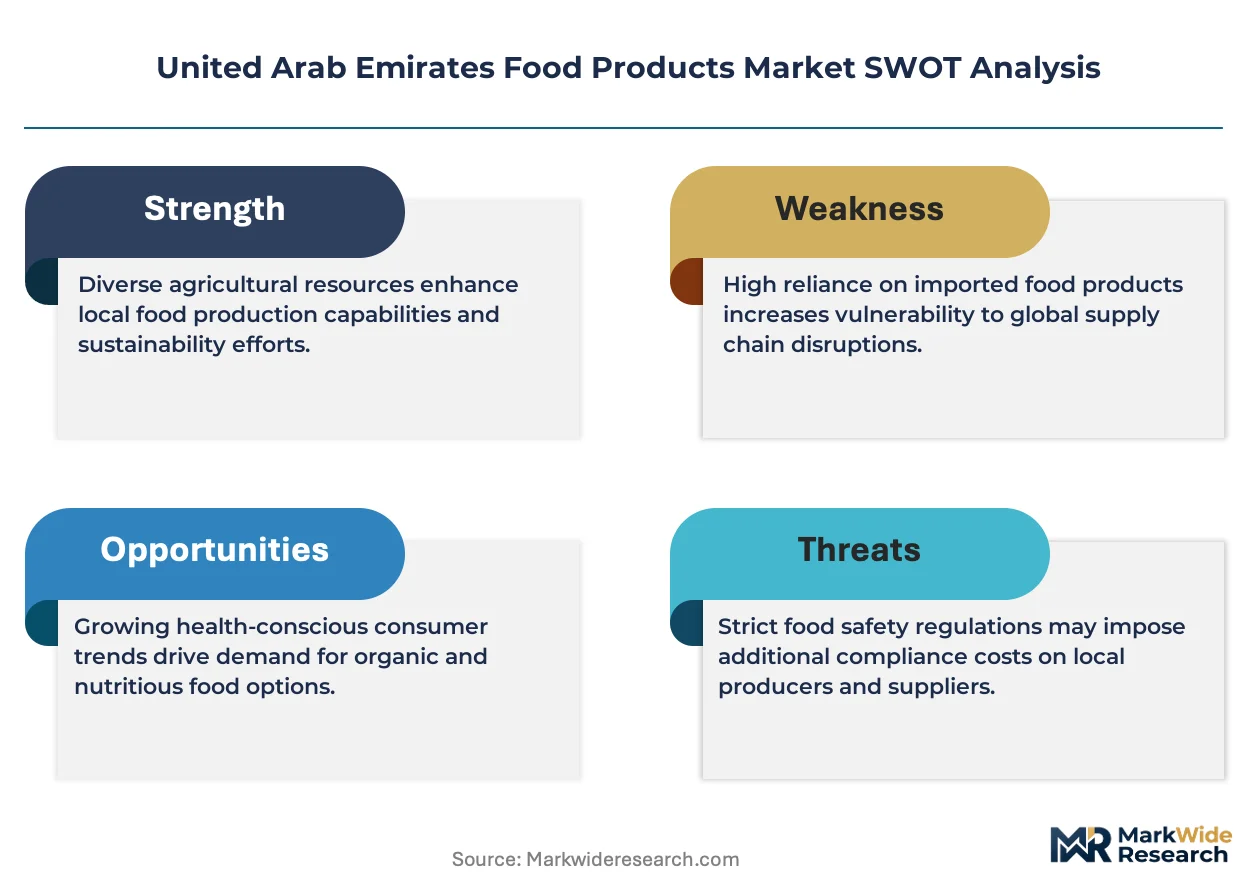
- Tourism capacity expansion:Hotel and restaurant procurement of packaged halal-certified goods is accelerating as Dubai and Abu Dhabi expand hospitality infrastructure to accommodate visitor inflows.
- MOHAP labeling mandates:Updated food safety documentation requirements are creating competitive advantage for suppliers with pre-certified halal supply chains and integrated traceability systems.
- Cold-chain clustering:Dubai's logistics corridor is concentrating temperature-controlled warehousing capacity that enables re-export trade into Saudi Arabia and Qatar.
Market Restraints
- Import dependency concentration:Over half of UAE food consumption relies on external supply sources, exposing margins to shipping cost volatility and port congestion at Jebel Ali.
- Halal certification friction:MOHAP's documentation requirements create timeline delays for FSSAI-aligned Indian exporters and EFSA-aware European suppliers unfamiliar with UAE protocols.
- Perishable logistics cost structure:Dairy and fresh meat categories require continuous cold-chain integrity that elevates last-mile delivery costs above dry-goods benchmarks.
Strategic Opportunities
- Domestic manufacturing partnerships:Operation 300bn local content incentives are opening contract manufacturing slots for international brands seeking UAE-based production qualification.
- Northern emirates distribution:Economy-tier packaged foods remain underpenetrated in Sharjah, Ajman, and Ras Al Khaimah relative to Dubai-Abu Dhabi saturation.
- Online retail channel consolidation:Delivery platform integration of last-mile networks is creating direct-to-household access for packaged goods previously constrained to supermarket shelf space.
Industry Challenges
- Halal compliance timeline compression:MOHAP's electronic clearance mandates require real-time documentation that strains legacy paper-based supplier systems.
- Cold-chain talent scarcity:Temperature-controlled logistics operations face qualified technician shortages for refrigeration maintenance and HACCP protocol enforcement.
- Re-export documentation complexity:Multi-country halal certification requirements for Saudi Arabia and Qatar markets create overlapping compliance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Food Products Market |
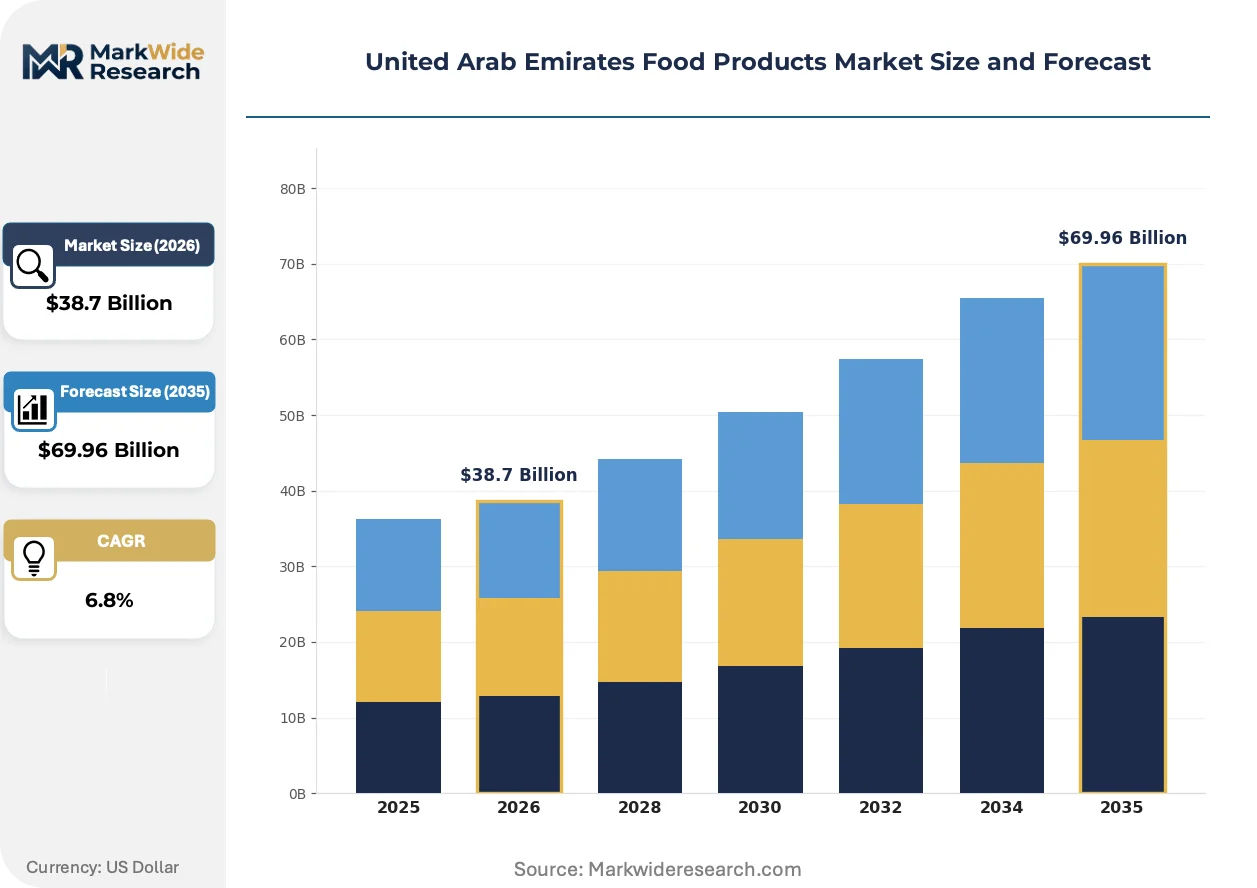
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy Products, Packaged Foods, Bakery Items, Fresh Produce Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers End User: Households, Restaurants, Catering Services, Food Processing Price Tier: Premium, Mid-Range, Economy, Discounted |
| Companies Covered | Nestlé S.A., Almarai Co., The Savola Group, Mars Incorporated, BRF S.A., Agthia, Al Islami Foods, IFFCO, Unilever, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Food Products Market Trends and Innovations
Digital traceability systems and automated warehousing are compressing replenishment cycles while reshaping how halal integrity is verified across multi-modal supply chains.
Blockchain-enabled halal traceability platforms are rendering obsolete paper-based certification chains that previously required manual verification at each border crossing. Major supermarket operators in Dubai and Abu Dhabi are mandating supplier adoption of these systems for private-label procurement. The technology is rendering obsolete traditional audit-based halal verification by enabling real-time temperature and custody documentation accessible to MOHAP inspectors.
MOHAP's coordination with ESMA on shelf-life testing protocols and additive permissibility lists is tightening formulation standards for imported processed foods. Manufacturers must now pre-validate ingredient compliance through UAE-registered laboratories before shipment authorization. Domestic dairy and meat processors are adapting fastest due to existing ESMA laboratory relationships, while new market entrants face extended qualification timelines.
Consolidation of last-mile delivery networks is compressing direct-to-consumer fulfillment windows for packaged foods across Dubai's dense residential corridors. Quick-commerce platforms are displacing traditional wholesaler intermediaries that previously served northern emirates labor accommodation camps. Sharjah and Ajman are experiencing the most visible channel restructuring as delivery radius economics favor centralized fulfillment over distributed retail footprints.
United Arab Emirates Food Products Market Segmentation
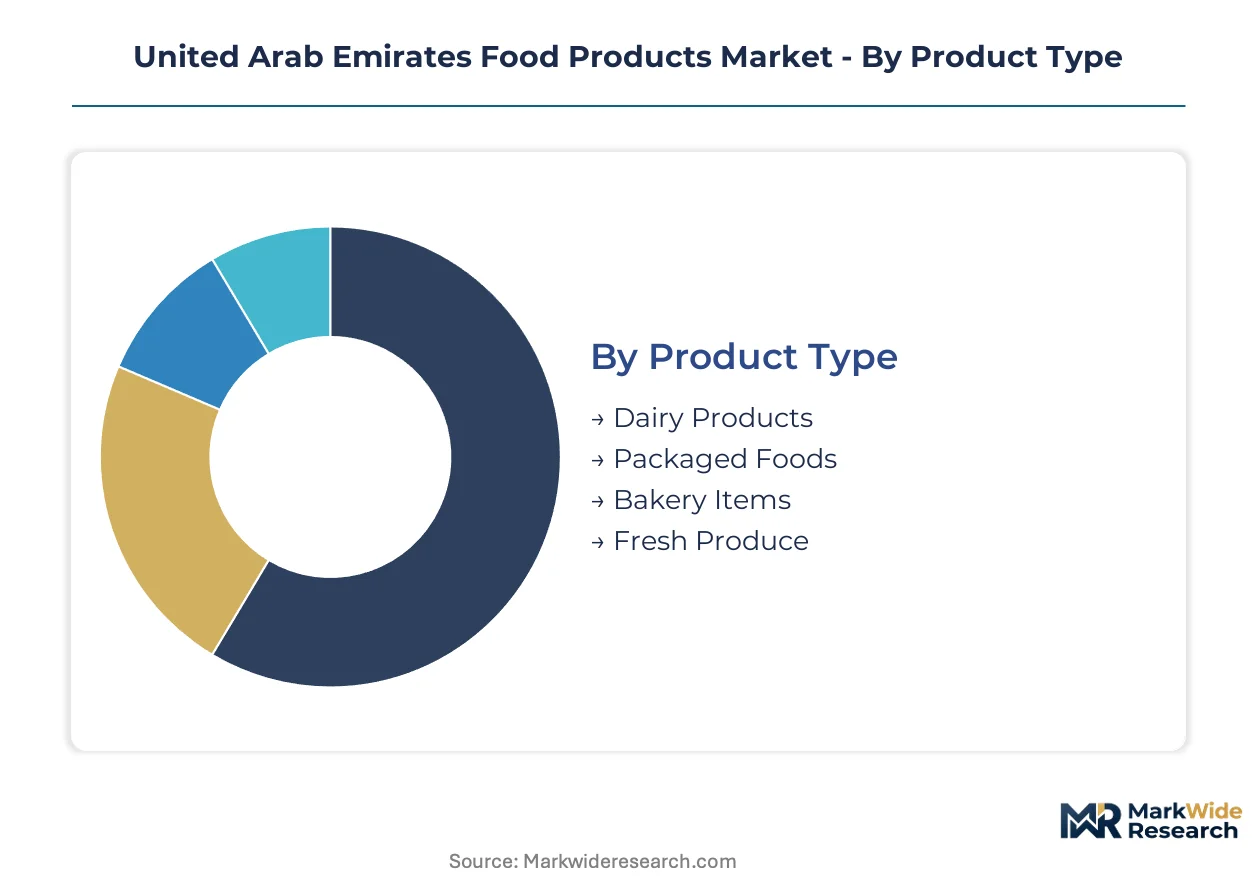
Segmentation in the UAE food products market reflects distinct procurement patterns across hospitality, retail, and re-export channels. Each dimension captures different margin structures and compliance requirements under MOHAP's regulatory framework.
Product Type:
Dairy products and packaged foods anchor contrasting ends of the use-case spectrum—fresh replenishment cycles versus extended shelf stability.
- Dairy Products:Fresh milk, yogurt, and cheese require continuous cold-chain integrity from UAE processing facilities through retail display. Hotel procurement in Dubai and Abu Dhabi concentrates demand for premium SKUs with halal certification traceability.
- Packaged Foods:UHT milk, retort meals, and shelf-stable goods enable re-export into Saudi Arabia and Qatar through Dubai's logistics corridor. MOHAP's labeling mandates compress documentation timelines for these high-volume categories.
- Bakery Items:Industrial bread and pastry production serves both household consumption and food manufacturing feedstock requirements across the Gulf Cooperation Council trade zone.
- Fresh Produce:Perishable fruits and vegetables move through Jebel Ali port consolidation with temperature-controlled warehousing clusters serving northern emirates distribution.
The dominant share belongs to Packaged Foods, while Dairy Products is closing the gap fastest as cold-chain infrastructure expands.
Distribution Channel:
Channel selection maps directly to customer density and delivery radius economics across Dubai's urban core versus northern emirates.
- Supermarkets:Temperature-controlled retail floorspace in Dubai and Abu Dhabi commands premium shelf positioning for dairy and halal-certified meat. Chains mandate blockchain-enabled traceability from suppliers under MOHAP coordination with ESMA.
- Online Retail:Quick-commerce platforms consolidate last-mile networks for direct-to-household fulfillment. Delivery radius economics favor centralized fulfillment over distributed retail footprints in Sharjah and Ajman.
- Convenience Stores:Small-format retail in labor accommodation camps sustains economy-tier packaged food volume throughput.
- Wholesalers:Traditional intermediaries serving northern emirates face displacement as online channels penetrate economy segments.
Supermarkets retain the largest transaction volume, though Online Retail is expanding most quickly as platform consolidation accelerates.
End User:
End-user segmentation separates household discretionary spending from institutional procurement governed by food service contracts.
- Households:Residential consumption in Dubai and Abu Dhabi concentrates in premium price tiers with halal certification requirements. Online retail penetration is highest among this segment.
- Restaurants:Hotel and restaurant procurement of packaged halal-certified goods accelerates as tourism capacity expands. MOHAP's updated labeling mandates create competitive advantage for pre-certified suppliers.
- Catering Services:Large-volume contracts for labor camps and corporate facilities sustain economy-tier throughput through wholesaler networks.
- Food Processing:Manufacturing feedstock requirements across the Gulf Cooperation Council trade zone drive bulk procurement of flour, edible oils, and sugar.
Households command the dominant consumption share, while Restaurants is gaining share fastest on tourism infrastructure expansion.
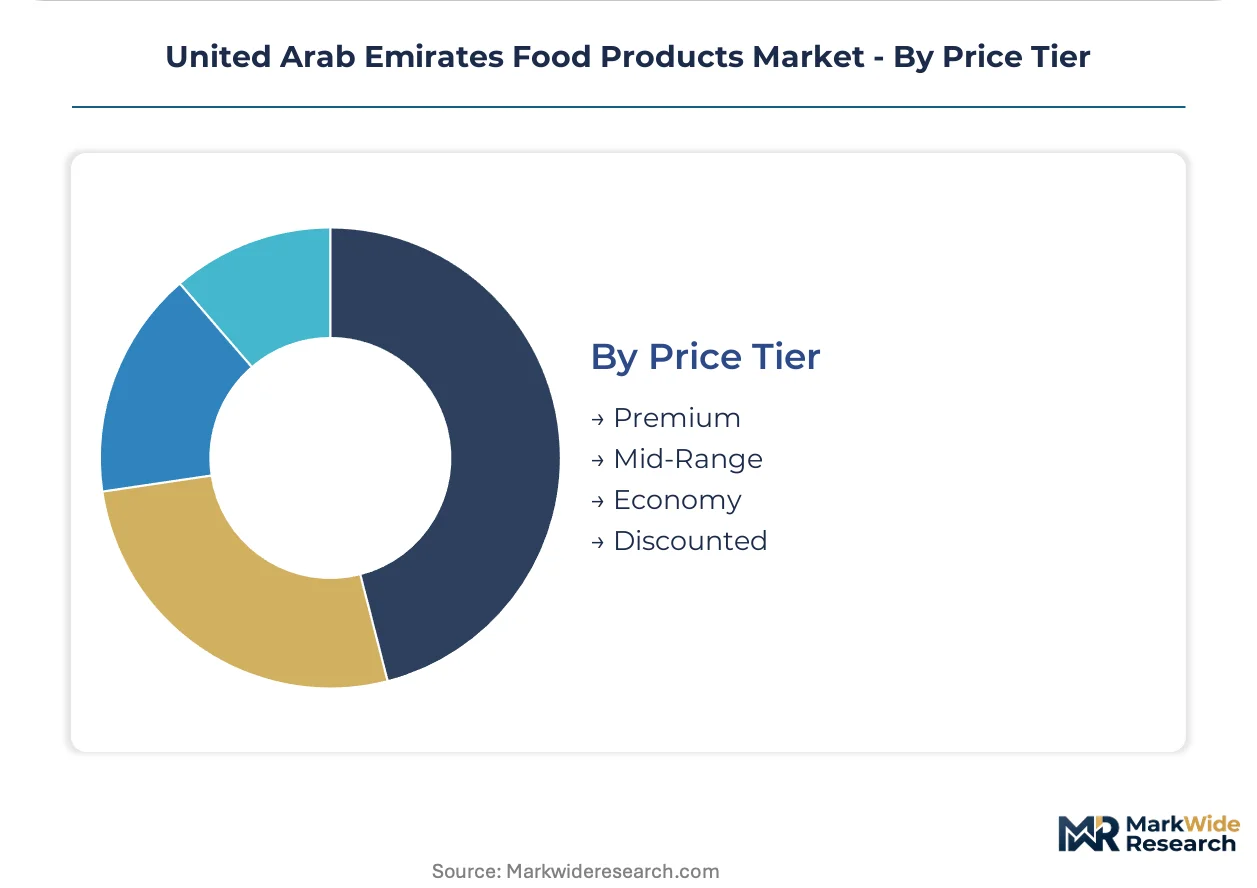
Price Tier:
Price tier differentiation aligns with geographic income concentration and halal certification grade requirements.
- Premium:Imported specialty goods and certified organic lines target Dubai's high-income residential corridors. These SKUs capture disproportionate margin pools relative to volume share.
- Mid-Range:Domestic dairy and packaged food brands balance quality positioning with mass-market accessibility across Abu Dhabi and Dubai.
- Economy:Private-label and bulk formats sustain volume throughput in northern emirates and labor accommodation camps through wholesaler networks.
- Discounted:Near-expiry and promotional inventory moves through secondary channels with compressed margin structures.
Premium tier captures the highest margin per unit, while Economy sustains the largest absolute volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the UAE's emirates. Dubai and Abu Dhabi buyers absorb premium pricing for halal-certified and imported specialty goods, while northern emirates procurement concentrates in economy-tier volume plays where price sensitivity dominates purchasing decisions.
Dubai
Tourism-driven hospitality procurement and high-income residential consumption anchor demand for premium SKUs with blockchain traceability. MOHAP's electronic import clearance platform processes the highest documentation volumes here. Jebel Ali port and Dubai South logistics corridor concentrate cold-chain warehousing capacity serving re-export into Saudi Arabia and Qatar.
Abu Dhabi
Government-led food security initiatives under Operation 300bn redirect procurement toward domestic manufacturing partnerships. The Khalifa Industrial Zone anchors dairy processing and edible oil refining facilities. ADQ's agri-food platform consolidates state-backed investments in local production capacity to reduce import dependency.
Sharjah
Economy-tier packaged foods sustain volume throughput through traditional wholesaler networks serving labor accommodation camps. Quick-commerce platforms are penetrating this segment fastest as delivery radius economics improve. Hamriyah Free Zone hosts secondary distribution hubs for northern emirates coverage.
Ras Al Khaimah
Underpenetrated retail infrastructure relative to Dubai-Abu Dhabi saturation creates whitespace for online channel expansion. Saqr Port handles bulk commodity imports for regional redistribution. Lower commercial real estate costs attract secondary logistics operators serving economy-segment procurement.
Fujairah
Strategic positioning on the Indian Ocean coastline diversifies import routing away from Strait of Hormuz congestion. The emirate's port infrastructure supports grain and bulk food commodity handling for UAE-wide distribution. Limited domestic processing capacity keeps Fujairah dependent on inter-emirate transfers for finished goods.
United Arab Emirates Food Products Market Competitive Landscape
Vertically integrated conglomerates and specialized halal processors split the market between margin-capture and volume-throughput strategies. Dairy and meat categories show tighter consolidation around farming-to-retail footprints, while packaged foods and beverages retain fragmented competition among multinational and regional brands. Two archetypes dominate: integrated agri-food platforms with captive supply chains, and brand licensors leveraging contract manufacturing for local production qualification. Competitive moves center on domestic manufacturing partnerships under Operation 300bn incentives, and cold-chain capacity expansion to secure hospitality procurement contracts.
Within the integrated agri-food tier, Almarai Co. and The Savola Group exemplify backward-controlled supply structures spanning farming through retail distribution. Al Islami Foods occupies a specialist position in halal frozen protein segments for Gulf re-export markets. Among diversified multinationals, Nestlé S.A. and Unilever represent brand-architecture approaches relying on local manufacturing partnerships rather than captive production assets. Agthia sits between these models with regional-scale manufacturing in bottled water and flour milling segments.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Almarai Co. |
| The Savola Group |
| Mars Incorporated |
| BRF S.A. |
| Agthia |
| Al Islami Foods |
| IFFCO |
| Unilever |
| Others |
Pricing and Supply Chain Analysis
Indian dairy farming and Australian wheat cultivation anchor input cost structures that compress margin pools for UAE-based processors while concentrating pricing power with Jebel Ali logistics operators. Cold-chain warehousing premiums and halal certification compliance costs cascade through to hospitality procurement contracts in Dubai and Abu Dhabi.
Pricing Analysis
After-sales service contracts for temperature-controlled logistics maintenance drive lifetime value retention among hotel and restaurant accounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by halal certification grade and blockchain traceability integration. Cost compression in economy-tier packaged goods intensifies because quick-commerce platforms displace traditional wholesaler intermediaries. Labor accommodation camps in northern emirates exhibit highest price sensitivity, while Dubai's hospitality sector absorbs premium positioning with minimal elasticity.
Supply Chain Analysis
Tariff exposure between India and the UAE dominates procurement risk calculations for grain and dairy feedstock imports. Supply draws from India, Australia, and Brazil for wheat, dairy, and protein inputs respectively. Single-source vulnerability concentrates in Jebel Ali port congestion, where over half of food imports consolidate. Distribution runs through Dubai South logistics corridor cold-chain clusters serving re-export into Saudi Arabia and Qatar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated quick-commerce platforms and integrated hospitality procurement groups, fragmenting traditional wholesaler influence across the UAE food sector.
For Market Incumbents: Pre-empt platform disintermediation by securing exclusive cold-chain partnerships with Dubai South logistics operators and embedding blockchain traceability into private-label lines before MOHAP mandates harden. Vertical integration into northern emirates distribution infrastructure defends against quick-commerce penetration of economy-tier volume pools. For New Entrants and Emerging Players: Establish a beachhead in halal-certified frozen protein segments for Saudi re-export markets, where Al Islami Foods' specialist positioning leaves whitespace for secondary players. Target Ras Al Khaimah's underpenetrated retail infrastructure with centralized fulfillment models that exploit lower commercial real estate costs versus Dubai saturation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cold-chain logistics operators scaling last-mile networks across Sharjah and Ajman. Five-to-ten year viability hinges on Operation 300bn domestic manufacturing qualification timelines. Watch MOHAP electronic clearance platform adoption rates as inflection signal for import-dependent versus local-production margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | MOHAP-mandated halal verification protocols render paper-based certification obsolete across Dubai supermarket procurement. |
| Cold-Chain Capacity Expansion | Dubai South warehousing clusters capture re-export margins into Saudi Arabia and Qatar hospitality sectors. |
| Domestic Manufacturing Partnership | Operation 300bn incentives redirect international brands toward UAE-based production qualification. |
| Quick-Commerce Platform Consolidation | Last-mile network integration displaces traditional wholesalers in northern emirates labor camp distribution. |
| Halal Certification Pre-Qualification | ESMA laboratory relationships compress documentation timelines for Indian and European supplier entrants. |
Research Methodology
Operator-level perspectives from cold-chain logistics directors, MOHAP compliance officers, hotel procurement managers, and supermarket category buyers anchored the qualitative base. Primary interview data combined with secondary validation from UAE customs records, ESMA additive permissibility lists, and hospitality sector procurement databases. Bottom-up volume estimates triangulated against top-down GDP elasticity models across the analysis window.
Scenario-bracketing framed demand projections under varying tourism capacity, import tariff, and domestic manufacturing incentive assumptions. Segmentation dimensions modeled include product type, distribution channel, end-user category, and price tier across the projection horizon. CAGRs derived from historical elasticity patterns and forward-looking regulatory trajectory assessments, with specific inputs from MOHAP electronic clearance adoption curves and Operation 300bn local content requirement schedules.
Stress conditions across shipping cost volatility, port congestion duration, and halal certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and cold-chain infrastructure buildout pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Freekeh Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Instant Soup Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Spreads Market