
 Condensed Canned Soups Market | 2026-2036
Condensed Canned Soups Market Size, Share, and Industry Trends Forecast 2026-2036
Condensed Canned Soups Market Insights
Foodservice buyer concentration is rebalancing as restaurant chains and institutional operators consolidate procurement volumes under national contracts. Campbell Soup Company leverages its brand equity and direct-store-delivery infrastructure to sustain shelf presence in fragmented retail channels. General Mills Inc. anchors its position through R&D intensity in sodium-reduction technologies. The Kraft Heinz Company competes on manufacturing scale and backward integration into tomato processing operations.
Condensed canned soups are thermally processed, water-reduced soup formulations requiring dilution with water or milk prior to consumption, typically packaged in steel or aluminum containers with shelf stability exceeding 24 months. Vegetable and chicken varieties dominate volume, while organic flavor profiles capture expanding margin pools in premium retail placements. Can packaging sustains cost leadership across mass-market households, though pouch formats are gaining traction in single-serve restaurant applications. Creamy segments retain higher per-unit profitability in North American grocery channels.
The FDA enforces sodium reduction targets and nutrition labeling standards that directly influence reformulation investments by domestic manufacturers. EFSA front-of-pack labeling schemes and EU Green Deal packaging waste directives are reshaping material specifications for European imports. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between reformulation capex or geographic portfolio rebalancing.
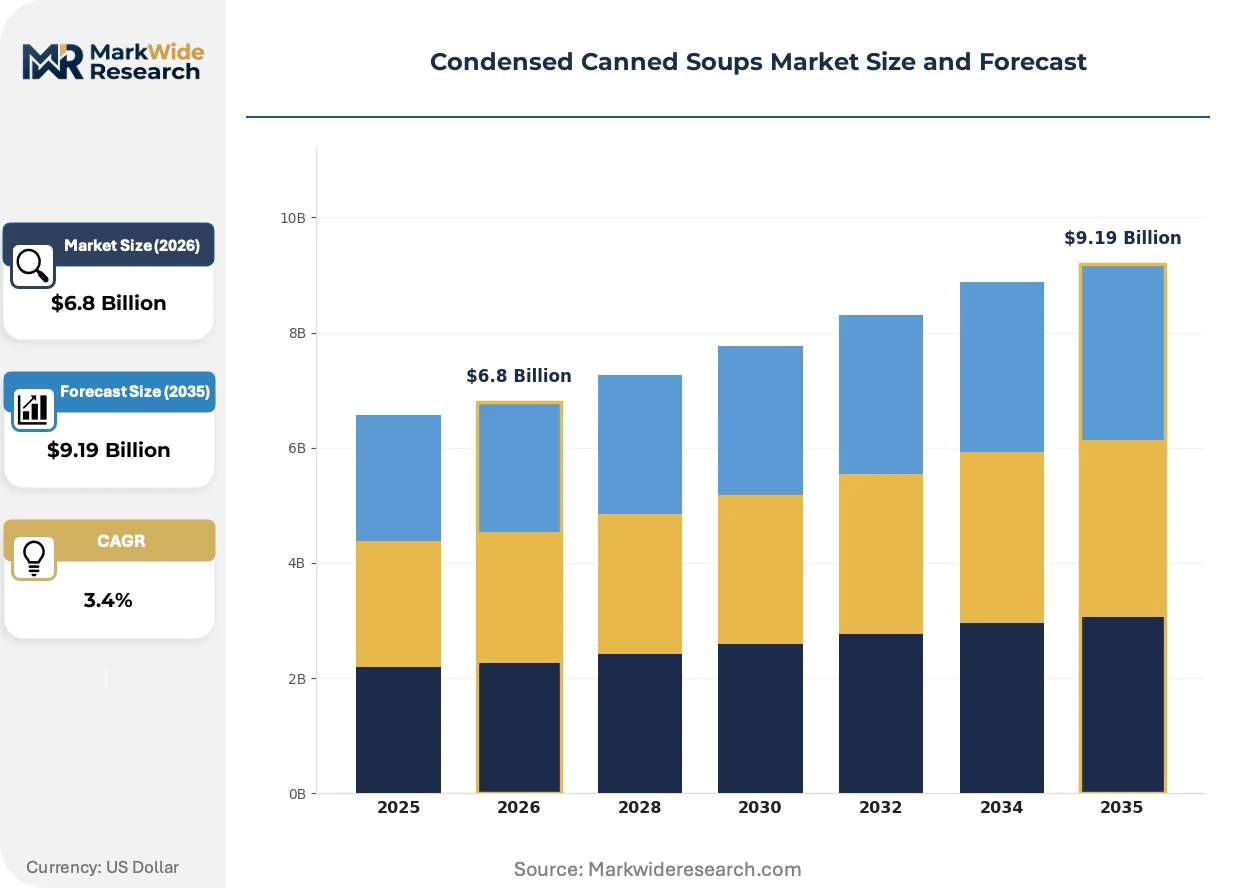
Market Dynamics
Foodservice procurement consolidation and sodium-reduction mandates from the FDA and EFSA are forcing simultaneous reformulation and supply-chain restructuring across condensed soup manufacturing. National restaurant chains now negotiate volume contracts that override traditional wholesale distribution tiers.
Growth Catalysts
- Extended Producer Responsibility frameworks:EU Green Deal packaging waste directives accelerate steel-to-aluminum can transitions and closed-loop recycling investments across European import supply chains.
- Private-label penetration:US grocery retailers deepen captive brand development in condensed soups, capturing margin pools previously held by branded manufacturers through direct sourcing relationships.
- Clean-label sodium reduction:Potassium chloride and yeast extract technologies enable 25-40% sodium reduction without taste degradation, satisfying FDA draft guidance targets.
Market Restraints
- Tomato paste input volatility:California drought cycles and processing tomato harvest variability compress margins for tomato-based condensed soup categories.
- Steel can supply concentration:North American tinplate production consolidates among three integrated mills, exposing manufacturers to price volatility and allocation risk.
- Pouch format substitution:Flexible retort pouches displace metal cans in single-serve foodservice applications, eroding volume in institutional channels.
Strategic Opportunities
- India urban retail expansion:Modern trade format growth in Mumbai, Delhi, and Bangalore creates shelf-space access for shelf-stable Western soup categories previously limited to imports.
- Plant-based cream bases:Oat and coconut milk formulations capture lactose-intolerant and vegan household segments in premium grocery placements.
- Direct-to-institutional e-procurement:Digital platforms connecting manufacturers to K-12 school districts and hospital systems bypass traditional broadline distributors.
Industry Challenges
- Retort thermal process optimization:Sodium-reduced formulations alter heat penetration curves, requiring validation of new Fo values without extending cook times that degrade texture.
- Front-of-pack label compliance:EFSA Nutri-Score and UK traffic-light schemes demand simultaneous reformulation across multiple European export markets with conflicting nutritional thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condensed Canned Soups Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable, Chicken, Beef, Seafood Packaging Type: Can, Tetra Pack, Pouch, Glass Jar Flavor Profile: Classic, Spicy, Creamy, Organic End User: Households, Restaurants, Institutions, Catering |
| Companies Covered | Campbell Soup Company, General Mills Inc., The Kraft Heinz Company, Nestlé S.A., Unilever, ConAgra Brands Inc., Baxters Food Group, BCI Foods Inc., Vanee Foods Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condensed Canned Soups Market Trends and Innovations
Reformulation science and packaging material transitions dominate capital allocation, with sodium-reduction chemistry and alternative format development consuming R&D budgets previously directed toward line extensions.
Retort pouch laminates with aluminum oxide barrier coatings are modularizing single-serve condensed soup distribution for quick-service restaurant back-of-house operations. Chains including Panera and Chipotle pilot these formats for speed-scratch preparation. The technology compresses shipping cube and heating energy requirements versus steel cans.
EFSA front-of-pack Nutri-Score labeling mandates are recalibrating European export formulations toward lower sodium and added-sugar thresholds. Manufacturers reformulate cream-based varieties with vegetable puree thickeners to improve color-coded ratings. German and French retail buyers now require B or higher Nutri-Score grades for shelf placement.
Chain restaurant procurement teams consolidate purchasing through group purchasing organizations that aggregate volume across hundreds of franchise locations. These GPOs displace independent distributor relationships with direct manufacturer contracts. The shift concentrates buying power among Aramark, Compass Group, and Sodexo in the United States.
Condensed Canned Soups Market Segmentation
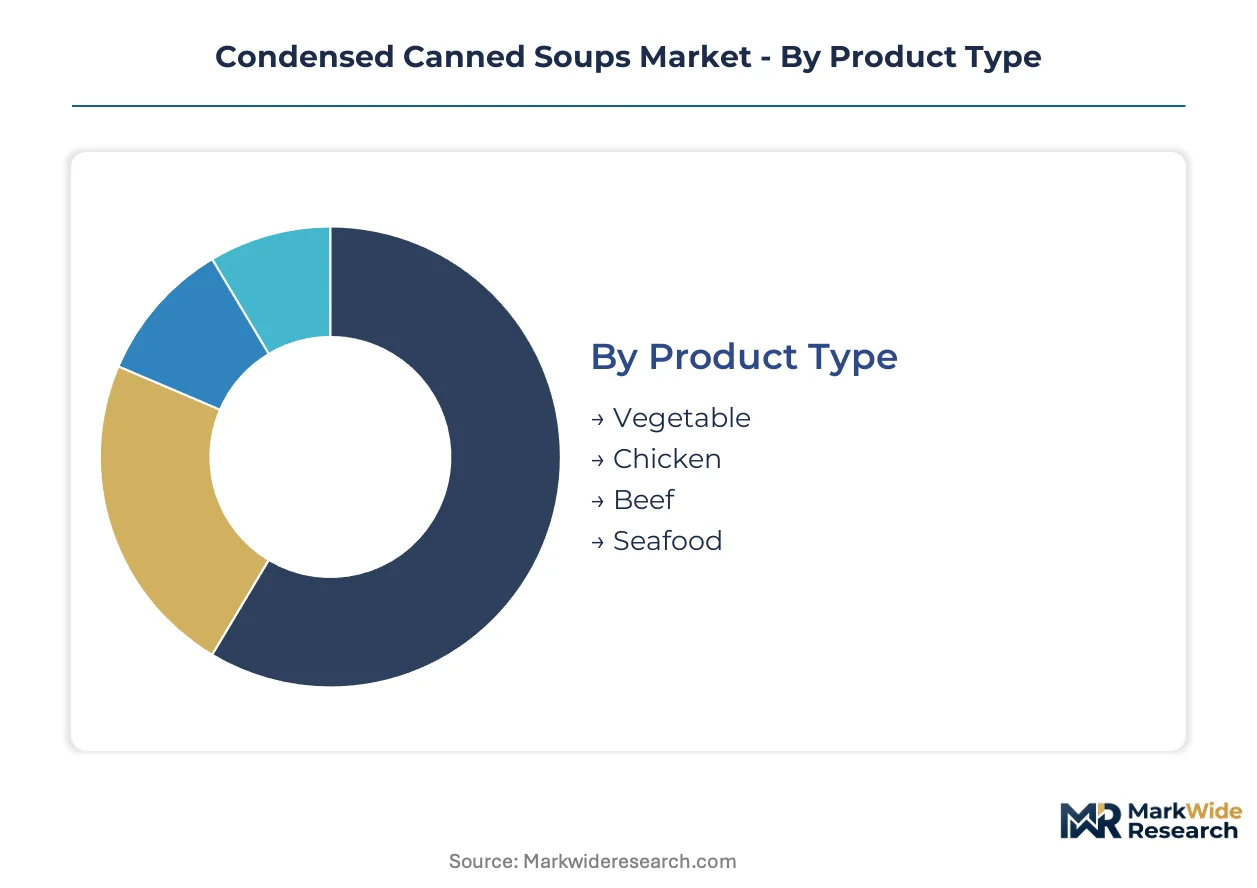
Condensed canned soup manufacturers configure production lines and inventory around four distinct segmentation axes. Product type and packaging format decisions determine thermal processing requirements, shelf-stability protocols, and distribution channel access. Flavor profile and end-user targeting govern reformulation investments for sodium reduction and clean-label positioning.
Product Type:
Regulatory scrutiny from the FDA and EFSA falls unevenly across product categories, with tomato-based and cream-based formulations facing distinct sodium reduction timelines and labeling thresholds.
- Vegetable:Tomato paste and vegetable puree bases dominate volume production. California processing tomato supply volatility compresses margins for this segment, while EFSA Nutri-Score mandates drive reformulation toward vegetable-thickened cream alternatives in European export markets.
- Chicken:Poultry broth concentrates require precise thermal processing to maintain protein stability. Demand concentrates in US households and institutional foodservice channels where chicken noodle varieties anchor menu rotations in K-12 school districts and hospital systems.
- Beef:Hearty flavor profiles serve Midwestern US retail strongholds and foodservice back-of-house operations.
- Seafood:Clam chowder and bisque varieties occupy premium shelf placements with higher per-unit margins.
Leading the category by volume: Vegetable. Growing fastest: Chicken.
Packaging Type:
Material selection drives compliance costs across EU Green Deal packaging waste directives and emerging extended producer responsibility frameworks in North American jurisdictions.
- Can:Steel and aluminum containers sustain 24-month shelf stability through hermetic sealing. North American tinplate production consolidation among three integrated mills exposes manufacturers to allocation risk and price volatility.
- Pouch:Flexible retort laminates with aluminum oxide barrier coatings compress shipping cube and heating energy requirements. Panera and Chipotle pilot these formats for speed-scratch preparation in quick-service restaurant back-of-house operations.
- Tetra Pack:Aseptic carton formats serve ambient distribution in European retail channels with lighter material weights.
- Glass Jar:Premium positioning in specialty grocery and direct-to-consumer channels commands price premiums.
Can formats retain cost leadership in mass-market retail. Pouch formats are expanding most quickly in foodservice applications.
Flavor Profile:
Clean-label positioning and front-of-pack scoring systems create tiered reformulation burdens, with organic and creamy segments facing distinct certification and nutritional threshold requirements.
- Classic:Traditional recipes face sodium reduction pressure under FDA draft guidance. Potassium chloride and yeast extract technologies enable 25-40% sodium reduction without taste degradation.
- Creamy:Dairy-based thickeners trigger lactose-intolerance exclusions. Oat and coconut milk formulations capture vegan household segments in premium grocery placements.
- Spicy:Ethnic flavor profiles expand in urban US retail clusters and foodservice innovation pipelines.
- Organic:USDA Organic and EU Organic certification requirements add audit and sourcing costs. German and French retail buyers now require B or higher Nutri-Score grades for shelf placement.
Classic flavors dominate absolute volume. Organic profiles command steepest expansion trajectory in premium retail channels.
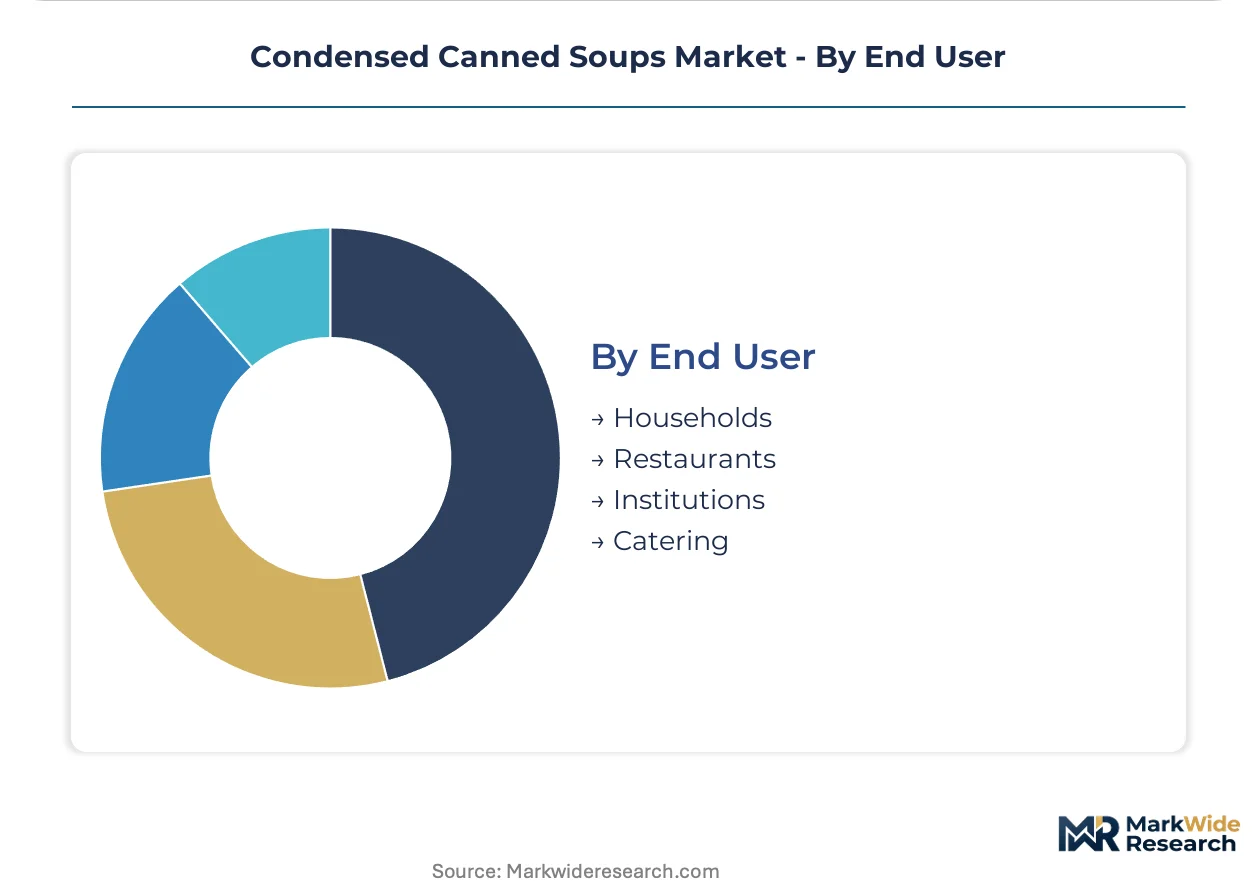
End User:
Procurement consolidation patterns and sodium reduction mandates vary sharply between fragmented household retail and concentrated institutional purchasing.
- Households:Grocery retail channels deepen private-label penetration. US retailers capture margin pools previously held by branded manufacturers through direct sourcing relationships.
- Restaurants:National chains negotiate volume contracts through group purchasing organizations. Aramark, Compass Group, and Sodexo consolidate buying power across hundreds of franchise locations.
- Institutions:K-12 school districts and hospital systems face USDA and CMS sodium targets respectively. Digital procurement platforms enable direct manufacturer relationships bypassing broadline distributors.
- Catering:Event-based demand concentrates in urban corridors with volatile seasonal patterns.
Households anchor absolute consumption volume. Institutions are gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California processing tomato harvests anchor North American supply chains for vegetable-based condensed soups, while regulatory divergence between FDA sodium targets and EFSA labeling schemes fragments formulation strategies across export markets.
United States
Private-label penetration in grocery retail deepens as Walmart and Kroger develop captive condensed soup brands through direct sourcing relationships. FDA draft guidance on sodium reduction pressures reformulation investments by domestic manufacturers. Chicago and Cincinnati host concentrated manufacturing infrastructure serving Midwestern household demand and institutional foodservice channels.
Germany
EFSA Nutri-Score labeling mandates drive reformulation toward lower sodium thresholds for cream-based varieties entering German retail. EU Green Deal packaging waste directives accelerate steel-to-aluminum can transitions across import supply chains. The Rhine-Ruhr industrial corridor hosts processing facilities serving Central European distribution networks.
United Kingdom
Traffic-light front-of-pack labeling schemes and post-Brexit regulatory divergence complicate export compliance for condensed soup manufacturers. NHS hospital systems and K-12 procurement digitization enable direct manufacturer relationships bypassing traditional distributors. Greater London anchors foodservice demand while Midlands manufacturing clusters serve retail distribution.
India
Modern trade format expansion in Mumbai, Delhi, and Bangalore creates shelf-space access for shelf-stable Western soup categories previously limited to imports. FSSAI labeling requirements and food safety standards shape import compliance costs for international manufacturers. Karnataka and Maharashtra host emerging retail infrastructure targeting urban middle-class households.
France
Nutri-Score B-grade minimums for retail shelf placement force vegetable-thickened cream reformulations in condensed soup export portfolios. Extended producer responsibility frameworks under EU circular economy directives reshape packaging material specifications. The Paris Basin and Lyon corridor concentrate foodservice procurement demand from contract catering operators.
Condensed Canned Soups Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label and plant-based positioning to capture premium retail placements. The vendor base concentrates among multinational food conglomerates with integrated manufacturing and direct-store-delivery infrastructure. Three archetypes dominate: brand-equity incumbents leveraging distribution scale, private-label suppliers capturing retailer margin pools, and specialty processors serving institutional channels. Competitive moves center on sodium-reduction R&D investments and backward integration into tomato processing operations.
Within the brand-equity tier, Campbell Soup Company and General Mills Inc. exemplify scale-driven positioning through established retail relationships and thermal processing expertise. The Kraft Heinz Company occupies a manufacturing-efficiency archetype with upstream control over ingredient supply chains. These three entities anchor competitive dynamics as procurement consolidation among foodservice group purchasing organizations concentrates volume negotiations.
| Leading Market Players |
|---|
| Campbell Soup Company |
| General Mills Inc. |
| The Kraft Heinz Company |
| Nestlé S.A. |
| Unilever |
| ConAgra Brands Inc. |
| Baxters Food Group |
| BCI Foods Inc. |
| Vanee Foods Company |
| Others |
Pricing and Supply Chain Analysis
Retort pouch laminates with aluminum oxide barrier coatings are compressing unit economics for foodservice buyers while fragmenting procurement power across national restaurant chains and institutional group purchasing organizations. This format transition simultaneously reduces shipping cube and heating energy requirements versus steel cans, yet concentrates volume negotiations among Aramark, Compass Group, and Sodexo in ways that erode manufacturer margin buffers.
Pricing Analysis
Service bundling separates direct-store-delivery relationships with inventory management from unbundled transactional spot purchases through broadline distributors. Three-tier pricing structure across premium organic, standard branded, and economy private-label levels tracks certification grade and sodium-reduction technology investment. Cost compression in standard tiers is intensifying because California processing tomato harvest variability and tinplate allocation risk squeeze input costs. Quick-service restaurant chains exhibit highest price sensitivity through GPO-aggregated volume contracts, while premium grocery retailers demonstrate lowest sensitivity for clean-label organic placements.
Supply Chain Analysis
Direct-to-institutional e-procurement platforms connecting manufacturers to K-12 school districts and hospital systems bypass traditional broadline distributor markups. Raw material sourcing draws from California processing tomato operations, North American tinplate mills, and Midwest dairy suppliers for cream-based formulations. Single-source vulnerability concentrates in steel can supply where three integrated mills control North American tinplate production. Distribution runs through direct-store-delivery networks for retail grocery, national broadline distributors for foodservice, and emerging digital procurement platforms for institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA sodium reduction mandates and EFSA front-of-pack labeling requirements create a cost-of-compliance barrier that favors incumbents with reformulation R&D scale and multi-market certification infrastructure, effectively moating compliant players from undercapitalized entrants.
For Market Incumbents: Anchor shelf presence through backward integration into tomato processing operations that buffer California drought cycle exposure. Defend against pouch format substitution in foodservice by piloting modular retort packaging with Panera and Chipotle. Prioritize potassium chloride and yeast extract R&D to validate 25-40% sodium reduction without extending thermal process times that degrade texture.
For New Entrants and Emerging Players: Quick-service restaurant back-of-house operations represent the most penetrable channel for retort pouch laminates with speed-scratch preparation protocols. Target India urban retail expansion in Mumbai, Delhi, and Bangalore where modern trade format growth creates shelf-space access for shelf-stable Western soup categories. Lead with plant-based cream bases using oat and coconut milk formulations to capture lactose-intolerant and vegan household segments in premium grocery placements.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational food conglomerates seeking sodium-reduction technology portfolios and direct-to-institutional e-procurement capabilities. Long-term viability favors manufacturers with validated clean-label reformulations and backward integration into processing tomato supply chains. Watch FDA final sodium reduction guidance publication as inflection indicator for reformulation capex acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sodium Reduction Technology Investment | Potassium chloride and yeast extract R&D satisfies FDA draft guidance targets without taste degradation. |
| Backward Integration into Tomato Processing | Campbell Soup Company and Kraft Heinz upstream control buffers California drought cycle margin compression. |
| Retort Pouch Format Expansion | Panera and Chipotle pilots compress shipping cube and heating energy versus steel cans. |
| Direct-to-Institutional E-Procurement | Digital platforms bypass broadline distributors for K-12 and hospital system volume contracts. |
| Plant-Based Cream Base Development | Oat and coconut milk formulations capture vegan segments in premium grocery channels. |
Research Methodology
Document review covered FDA guidance documents, EFSA regulatory filings, and EU Green Deal packaging waste directives, complemented by interviews with condensed soup category managers, foodservice procurement directors at Aramark and Compass Group, retail grocery buyers, and thermal processing engineers. Secondary validation drew from customs records, Nielsen retail audit data, and SEC 10-K filings from Campbell Soup Company, General Mills, and Kraft Heinz. Bottom-up volume modeling triangulated against top-down market sizing across product type, packaging format, flavor profile, and end-user segmentation dimensions.
Segment-level volume and value trajectories across the analysis window reflect granular modeling of sodium-reduction reformulation timelines, private-label penetration rates, and foodservice procurement consolidation patterns. CAGRs were derived from regression analysis of historical shipment data and elasticity-adjusted demand projections. Industry-specific forecast inputs included California processing tomato harvest variability coefficients and EU extended producer responsibility framework implementation schedules.
Several conditions sit outside the modeled scope, including unforeseen FDA final rule acceleration, abrupt California drought intensification, and retort pouch laminate supply disruptions. Forecasts reflect base-case assumptions about regulatory timeline adherence and input cost stabilization. Periodic stress-testing of base assumptions is recommended given tomato paste input volatility and steel can supply concentration risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Packaged Rice Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Instant Rice Market
Packaged Foods
Canned Goods Market
Packaged Foods
Canned Pasta Market