
 Global SUV Market | 2026-2036
Global SUV Market Size, Share, and Industry Trends Forecast 2026-2036
Global SUV Market Outlook
A shortage of battery engineering talent is unwinding production timelines for electrified SUV platforms across multiple assembly networks. Toyota Motor Corporation leverages its hybrid powertrain depth to sustain volume leadership in markets where charging infrastructure remains uneven. Volkswagen Group anchors its SUV portfolio on modular electric architecture that spans multiple brands and price bands. BYD Company Ltd dominates battery cost curves through in-house cell production, positioning its SUV lineup aggressively in price-sensitive segments.
A sport utility vehicle is a passenger automobile with elevated ground clearance, available all-wheel or four-wheel drive, and a body-on-frame or unibody construction designed for varied terrain and cargo utility. The category spans curb weights from roughly 1,500 kg for compact crossovers to over 2,500 kg for full-size body-on-frame variants, with power outputs ranging from 150 hp in entry models to exceeding 600 hp in performance configurations. Compact crossovers lead volume globally as they blend car-like fuel economy with elevated seating positions that appeal to urban families. Electric fuel type variants are expanding fastest where subsidy frameworks and zero-emission zones reshape purchase incentives. Luxury vehicle type segments command disproportionate margin pools despite representing a smaller share of unit sales.
The EPA tailpipe standards and EU F-Gas Regulation constrain refrigerant choices and emissions profiles for SUVs sold in the United States and European markets. China's MIIT mandates new energy vehicle production quotas that force multinational brands to localize electrified SUV output or surrender market access. India's BIS safety norms and crash-test protocols are tightening structural requirements for imported and domestically assembled SUVs alike. Stakeholders must monitor how divergent compliance calendars across EPA, EMA, and MIIT jurisdictions fragment platform engineering budgets and sourcing strategies.
Market Dynamics
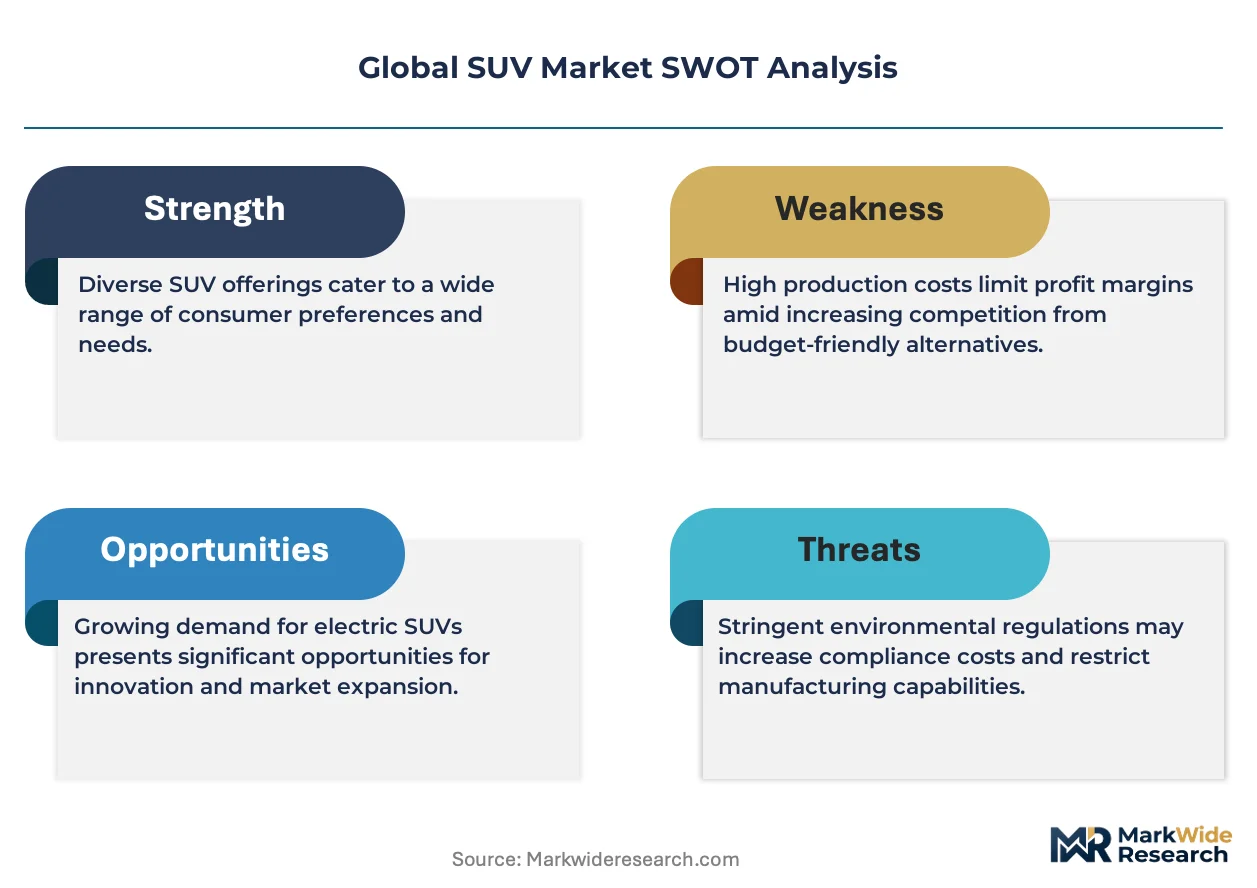
Powertrain electrification is fragmenting platform engineering budgets as automakers simultaneously develop internal combustion, hybrid, and battery-electric architectures to satisfy divergent regulatory calendars across major markets.
Growth Catalysts
- EU Green Deal tailpipe standards:The regulation accelerates fleet electrification mandates across Germany, France, and Italy, forcing OEMs to expand electrified SUV offerings to avoid penalties.
- Last-mile logistics procurement:Fleet operators in China and the United States are scaling SUV acquisitions for executive transport and urban delivery routes requiring elevated cargo capacity.
- Battery cost curves:In-house cell production and lithium-iron-phosphate chemistries are compressing pack costs, enabling price-competitive electric SUVs in mass-market segments.
Market Restraints
- Lithium supply concentration:Chile and Australia dominate upstream lithium extraction, exposing battery supply chains to geopolitical disruption and price volatility.
- Charging infrastructure gaps:Uneven deployment of fast-charging networks across India and Southeast Asia constrains electric SUV adoption outside premium urban clusters.
- Refrigerant compliance friction:The EU F-Gas Regulation and EPA standards impose conflicting refrigerant specifications, forcing redundant HVAC engineering for cross-regional models.
Strategic Opportunities
- India BIS safety norm upgrades:Tighter crash-test protocols for imported SUVs create openings for localized assembly partnerships with domestic manufacturers.
- Solid-state battery convergence:Toyota and Samsung SDI developments in solid-state electrolytes promise energy density gains that could reshape premium SUV range expectations.
- Direct-to-consumer channels:Digital sales platforms bypass traditional dealer networks, capturing margin and purchase data in China's tier-two cities.
Industry Challenges
- Battery engineering talent scarcity:Cell chemistry and thermal management expertise concentrates in China and South Korea, forcing Western OEMs into expensive relocation or acquisition strategies.
- Platform integration complexity:Modular electric architectures must accommodate wheelbases from compact crossovers to full-size body-on-frame variants without sacrificing crash performance.
- MIIT localization timelines:China's new energy vehicle production quotas demand rapid joint-venture restructuring or market exit for non-compliant multinational brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SUV Market |
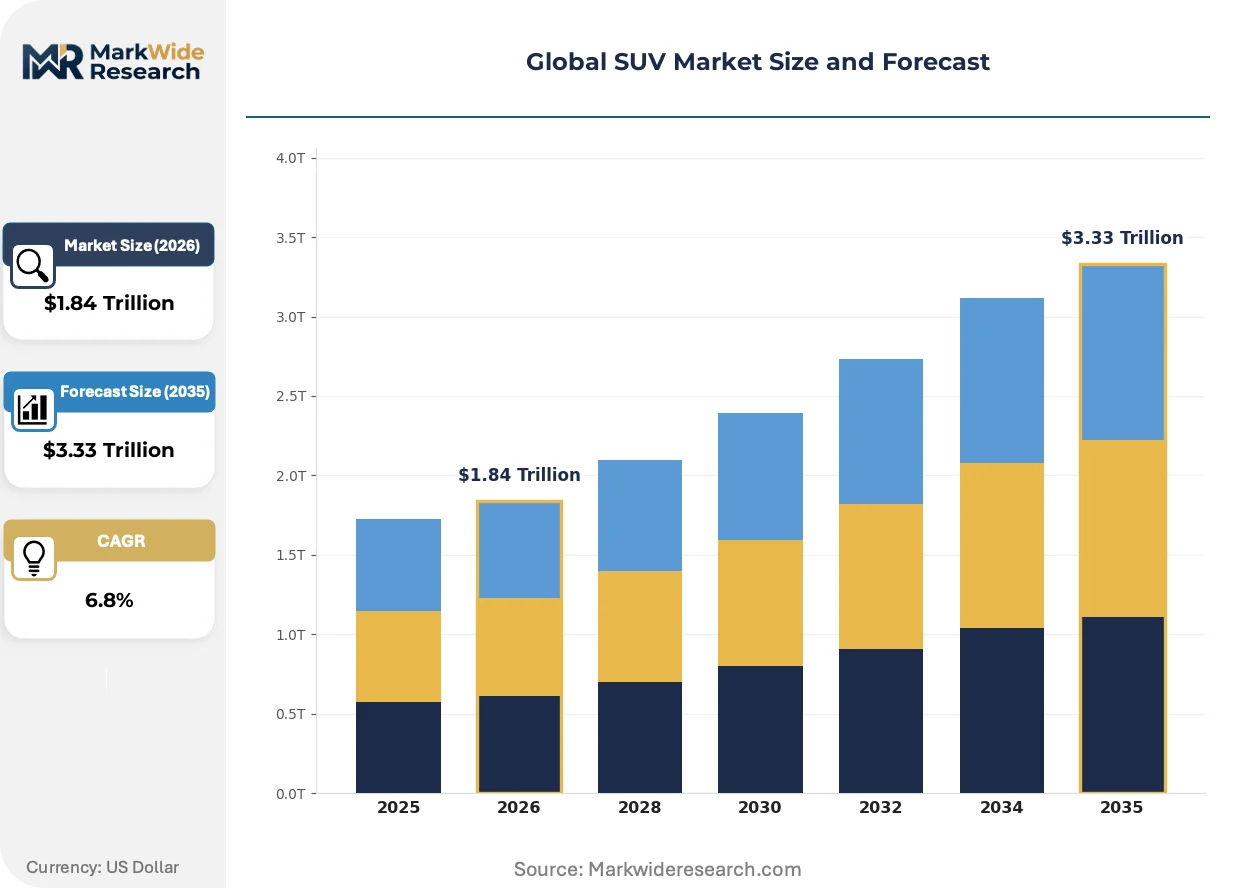
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.33 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Crossover, Full-Size, Luxury, Compact Fuel Type: Petrol, Diesel, Hybrid, Electric End User: Families, Individuals, Fleet Operators, Off-road Enthusiasts Market Distribution: Online Sales, Dealerships, Auction Houses, Car Rentals |
| Companies Covered | Toyota Motor Corporation, Volkswagen Group, Hyundai Motor Company, Ford Motor Company, General Motors, Stellantis, Honda Motor Co., Ltd., BYD Company Ltd, Kia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SUV Market Strategic Shifts
Electrification is compressing development cycles while fragmenting powertrain portfolios, forcing simultaneous investment in battery chemistry, thermal systems, and software-defined vehicle architectures.
Silicon carbide power electronics is miniaturizing inverter packaging and cutting switching losses in high-voltage electric SUV platforms. Premium German and Korean manufacturers are adopting 800-volt architectures faster than mass-market brands, enabling faster charging and lighter cabling. This technology is miniaturizing thermal management hardware, freeing interior volume and reducing curb weight in compact electric crossovers.
The EPA tailpipe standards and California Air Resources Board waivers are tightening fleet-average CO2 limits through 2032, requiring substantial electric SUV volume to offset internal combustion models. Manufacturers are responding by prioritizing plug-in hybrid variants for states with weaker charging infrastructure while pushing battery-electric SKUs in zero-emission vehicle mandate jurisdictions.
Fleet procurement departments are consolidating supplier relationships and demanding total-cost-of-ownership guarantees rather than upfront vehicle pricing. Leasing companies and corporate mobility providers in Germany and the United Kingdom are unbundling maintenance and residual risk from acquisition decisions, shifting margin pools toward data-driven service contracts and remarketing operations.
Global SUV Market Segmentation
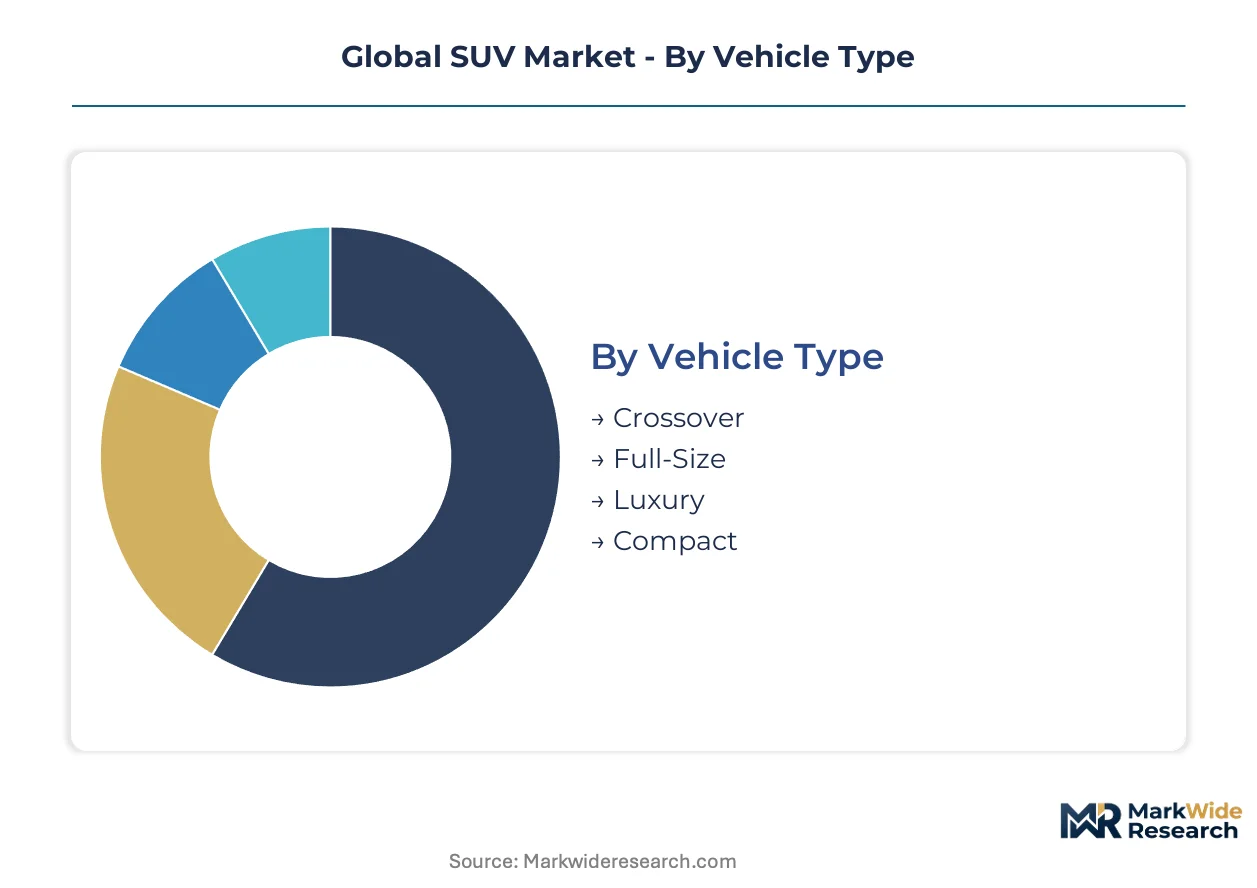
Segmentation in the SUV market determines how engineering budgets fragment across powertrain architectures and how procurement channels allocate volume between retail consumers and fleet operators. Manufacturers must align platform investments with where margin pools concentrate within each dimension.
Vehicle Type:
Luxury and compact crossovers capture disproportionate margin pools, while full-size body-on-frame variants sustain volume in specific geographies with towing and terrain requirements.
- Crossover:Unibody construction with car-like handling and elevated seating positions dominates urban family transport. Demand concentrates in China and the United States where compact dimensions suit dense parking constraints and fuel economy regulations favor lighter platforms.
- Luxury:Premium materials, advanced driver assistance systems, and bespoke powertrain calibrations command price premiums three to four times mass-market equivalents. Germany's KBA certification requirements and China's MIIT luxury vehicle tax thresholds shape specification decisions for this segment.
- Full-Size:Body-on-frame architecture supports towing capacities exceeding 3,500 kg for commercial and recreational applications.
- Compact:Entry-level positioning with standardized feature sets targets first-time buyers and emerging market penetration.
Crossover holds installed capacity. Luxury is rotating up the share rankings.
Fuel Type:
Cost tier stratification separates electrified variants from internal combustion, with hybrid architectures bridging infrastructure gaps in markets with uneven charging deployment.
- Electric:Battery-electric platforms with 400-800 volt architectures and lithium-ion or lithium-iron-phosphate cell chemistries. Demand concentrates in China, Germany, and California where zero-emission zones and IRA tax credits reshape purchase economics, though charging infrastructure gaps in India and Southeast Asia constrain adoption outside premium clusters.
- Hybrid:Parallel and series-parallel powertrains combining internal combustion with electric motor assist. Toyota's hybrid depth sustains volume leadership in markets where charging networks remain uneven, particularly across Japan and Australia's urban corridors.
- Petrol:Conventional spark-ignition engines with turbocharging and direct injection for power density optimization.
- Diesel:Compression-ignition powertrains with particulate filter and selective catalytic reduction aftertreatment for torque-heavy applications.
Petrol holds installed capacity. Electric is climbing the fastest.
End User:
Application-driven procurement patterns separate family-oriented safety specifications from fleet operator total-cost-of-ownership calculations.
- Fleet Operators:Corporate mobility providers and last-mile logistics companies demand total-cost-of-ownership guarantees, unbundled maintenance contracts, and residual value protection. Procurement concentrates in Germany and the United Kingdom where leasing companies consolidate supplier relationships and shift margin pools toward data-driven service agreements.
- Families:Multi-occupant safety ratings, child seat accommodation, and cargo flexibility drive specification priorities. China's tier-two cities and United States suburban corridors absorb volume where three-row seating and crash-test performance dominate purchase decisions.
- Individuals:Single-occupant urban commuters prioritizing maneuverability and technology integration.
- Off-road Enthusiasts:Specialized terrain capability with locking differentials, skid plates, and wading depth specifications.
Families hold installed capacity. Fleet Operators is gaining share fastest.
Market Distribution:
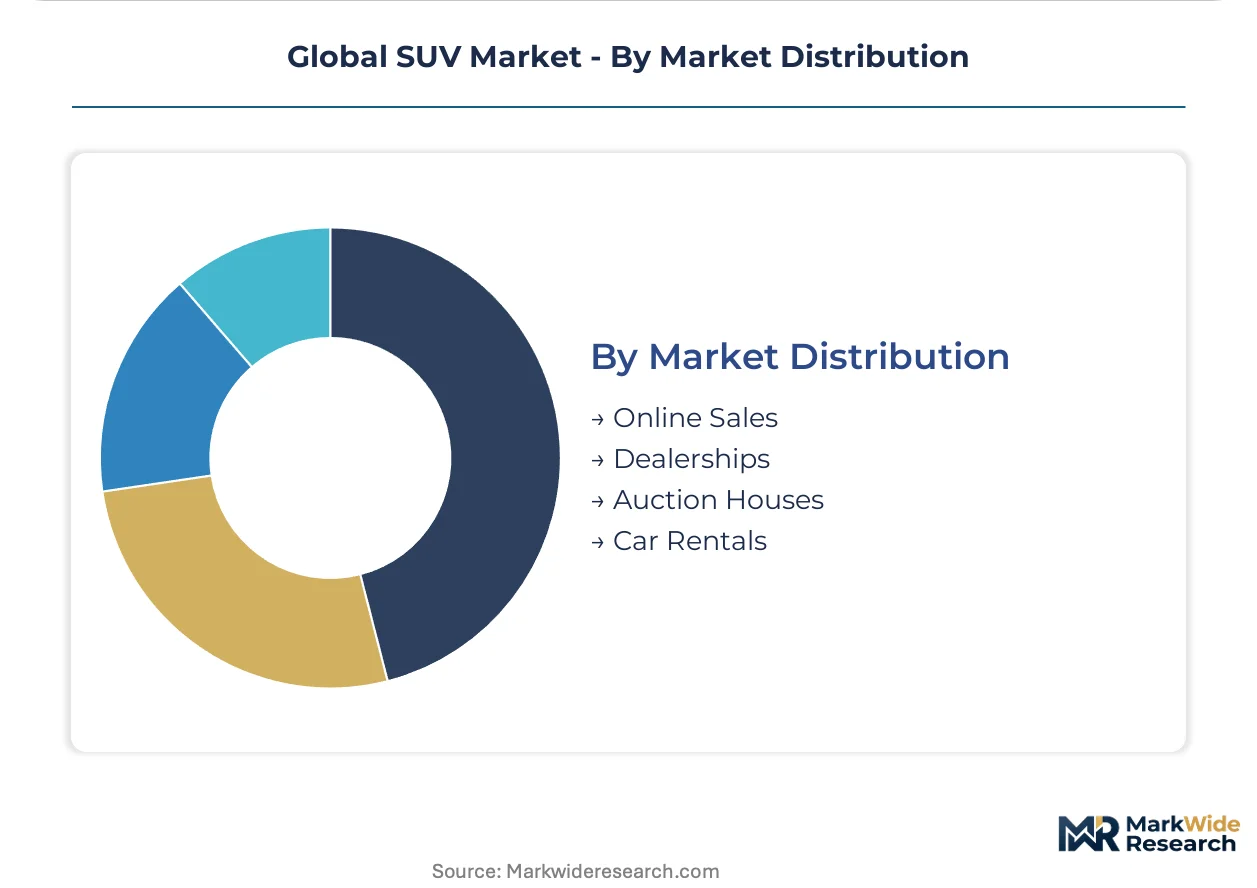
Customer type fragmentation separates digital-native purchase journeys from traditional dealer network dependencies, with geography determining channel viability.
- Dealerships:Physical retail networks with test drive facilities, financing arrangements, and service bay integration sustain volume in markets with established automotive retail infrastructure. Germany's KBA registration requirements and United States state-level franchise laws preserve dealer relevance despite digital disruption.
- Online Sales:Direct-to-consumer platforms with configurators, home delivery, and remote financing capture margin and purchase data. China's tier-two cities absorb aggressive digital channel expansion where smartphone-native consumers bypass traditional showroom visits.
- Car Rentals:Fleet procurement with standardized specifications and high-turnover utilization models.
- Auction Houses:Remarketing channels for off-lease and fleet-decommissioned vehicles with transparent pricing mechanisms.
Dealerships hold installed capacity. Online Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs electrified SUV volume through MIIT quota compliance, while the United States channels demand toward full-size body-on-frame variants for towing and fleet logistics. Germany concentrates premium electrified procurement under EU Green Deal timelines, diverging from India's price-sensitive compact crossover uptake where BIS safety norms reshape import economics.
China
Domestic brands capture share through in-house battery cell production and aggressive pricing in tier-two cities. MIIT new energy vehicle quotas force multinational joint-venture restructuring or market exit. The Yangtze River Delta cluster around Shanghai anchors localized electrified SUV output serving both domestic consumption and export markets.
United States
Fleet operators scale SUV procurement for last-mile logistics and executive transport across suburban corridors. EPA tailpipe standards and California Air Resources Board waivers tighten fleet-average CO2 limits through 2032. Detroit's manufacturing base pivots toward electrified full-size platforms while maintaining internal combustion capacity for states with weaker charging infrastructure.
Germany
Premium electrified variants command disproportionate margin pools despite smaller unit shares relative to mass-market segments. KBA certification requirements and EU Green Deal mandates accelerate powertrain diversification across Stuttgart and Munich industrial clusters. Leasing companies consolidate supplier relationships and shift margin pools toward data-driven service contracts.
India
Price-sensitive demand concentrates in compact crossovers suited to dense urban parking constraints and fuel economy regulations. BIS safety norms and crash-test protocols tighten structural requirements for imported and domestically assembled SUVs. The Delhi-NCR corridor and Maharashtra absorb volume where localized assembly partnerships create openings for multinational brands.
South Korea
Battery engineering talent concentration supports domestic OEM electrification roadmaps and thermal management expertise. MFDS and environmental ministry frameworks shape refrigerant and emissions compliance for vehicles sold domestically. The Seoul Capital Area anchors R&D investment while Busan-Ulsan handles export-oriented assembly for global markets.
Global SUV Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the former commanding platform architecture decisions and the latter filling niche powertrain or regional gaps. The market structure reflects consolidation around modular electric architectures that span multiple brands and price bands. Strategic archetypes include hybrid powertrain specialists leveraging uneven charging infrastructure, battery cost curve dominants with in-house cell production, and modular platform architects serving premium and mass-market segments simultaneously. Competitive moves center on joint-venture restructuring for MIIT compliance and silicon carbide power electronics adoption for 800-volt architectures.
Among Asia-Pacific-based manufacturers, Toyota Motor Corporation exemplifies hybrid powertrain depth sustaining volume leadership where charging networks remain uneven. Volkswagen Group occupies a position as modular electric architecture anchor spanning multiple brands and price bands under EU regulatory timelines. BYD Company Ltd represents battery cost curve dominance through in-house cell production, positioning aggressively in price-sensitive segments. These three entities illustrate how geographic origin and corporate structure shape competitive archetype allocation across electrification roadmaps.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Volkswagen Group |
| Hyundai Motor Company |
| Ford Motor Company |
| General Motors |
| Stellantis |
| Honda Motor Co., Ltd. |
| BYD Company Ltd |
| Kia Corporation |
| Others |
Value Chain & Pricing Dynamics
Lithium-iron-phosphate cell chemistry displacing nickel-cobalt-manganese formulations redraws procurement geography toward China while compressing pack cost curves and redistributing pricing power toward vertically integrated cell producers.
Pricing Analysis
Long-term offtake contracts dominate battery supply agreements while spot markets govern semiconductor and steel inputs. Three-tier pricing structure across premium, standard, and economy levels separates 800-volt silicon carbide platforms from 400-volt mass-market variants and entry-level internal combustion models. Cost compression in compact electric crossovers is intensifying because BYD and CATL captive cell production erodes tier-one supplier margins. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership contracting, while first-time buyers in India demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and nickel sulfate supersedes just-in-time preferences as automakers buffer against Chilean and Australian mining concentration. The supply chain draws from China for cell manufacturing, South Korea for cathode materials, and Germany for power electronics. Single-source vulnerability in rare earth processing creates chokepoint exposure. Distribution runs through regional assembly hubs in Shanghai, Detroit, and Stuttgart to minimize logistics cost and tariff exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in the SUV market hinge on modular electric architecture interoperability, where Volkswagen's MEB ecosystem and Toyota's hybrid powertrain standardization create winner-take-most dynamics across tier-one supplier networks.
For Market Incumbents: Shield proprietary 800-volt architectures through silicon carbide inverter exclusivity agreements with STMicroelectronics and Infineon. Deepen backward integration into lithium-iron-phosphate cell production to neutralize CATL and BYD cost advantages in China. Consolidate dealership networks in Germany and the United States before direct-to-consumer platforms erode service revenue pools.
For New Entrants and Emerging Players: Differentiate on solid-state battery range claims targeting premium German leasing channels where residual value guarantees matter most. Penetrate India's compact crossover segment through localized assembly partnerships with Mahindra and Tata Motors. Deploy direct-to-consumer digital platforms in China's tier-two cities to bypass entrenched joint-venture distribution.
For Investors and Strategic Acquirers: The market sits at a powertrain-transition phase that favors hybrid-specialist incumbents with uneven charging infrastructure exposure. Long-term viability rests on modular platform scalability across luxury and mass-market segments. Target acquisition archetypes include Tier 1 thermal management specialists with 800-volt expertise. Watch EPA tailpipe standard stringency adjustments as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD long-term offtakes secure lithium-iron-phosphate capacity for mass-market electric SUV platforms. |
| Platform Standardization | Volkswagen's MEB architecture spans Audi, Skoda, and SEAT brands to amortize R&D across price tiers. |
| Charging Infrastructure Partnership | IONITY and Electrify America alliances address range anxiety in EU Green Deal compliance corridors. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities shift margin pools from hardware sales to subscription service revenue. |
| Geographic Manufacturing Footprint | Shanghai and Chattanooga assembly localization satisfies MIIT quotas and IRA domestic content requirements. |
Study Parameters
Desk research of vehicle registration databases, EPA certification filings, and MIIT production bulletins preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement directors, fleet operator acquisition managers, and charging infrastructure developers. Secondary validation drew from IHS Markit production data, KBA type-approval records, and joint-venture disclosure filings. Bottom-up segment sizing triangulated against top-down macroeconomic demand modeling.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster shaped the analytical framework. CAGRs derived from logistic adoption curves fitted to electrification policy timelines and battery cost trajectory assumptions. Industry-specific inputs incorporated silicon carbide penetration rates and solid-state battery commercialization pathways across the projection horizon.
Material uncertainties — lithium price volatility, EPA standard stringency revisions, and MIIT quota enforcement discretion — sit outside the modeled envelope. Forecasts embody assumptions regarding charging infrastructure deployment pace and consumer willingness-to-pay premiums for electrified variants. Revision becomes warranted when lithium carbonate spot prices or EU Green Deal compliance penalties cross thresholds that alter OEM platform investment calculus.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Global Passenger Cars Market
Passenger Vehicles
Luxury Vehicles Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
India Automotive Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Convertible Vehicles Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
North America Automotive Market