
 China Luxury Car Market | 2026-2036
China Luxury Car Market Size, Share, and Industry Trends Forecast 2026-2036
China Luxury Car Market Intelligence
Domestic battery-electric production capacity in the Yangtze River Delta is decoupling from traditional gasoline engine supply chains. NIO leverages its proprietary battery-swap network to anchor premium positioning in urban corridors. BYD sustains manufacturing scale through in-house blade battery production, while Hongqi competes on state-backed brand heritage and ceremonial fleet contracts.
A China luxury car denotes a premium passenger vehicle engineered with advanced powertrains, intelligent cockpit systems, and refined interior materials, typically retailing above RMB 300,000 and serving status-conscious consumers and corporate transport needs. SUV configurations dominate volume due to family-oriented purchasing preferences across tier-one and tier-two cities, while electric powertrains capture the fastest expansion as MIIT production quotas and NEV plate privileges redirect consumer selection. Individual buyers represent the deepest margin pool, though corporate fleet procurement maintains steady absorption of flagship sedans for executive transport.
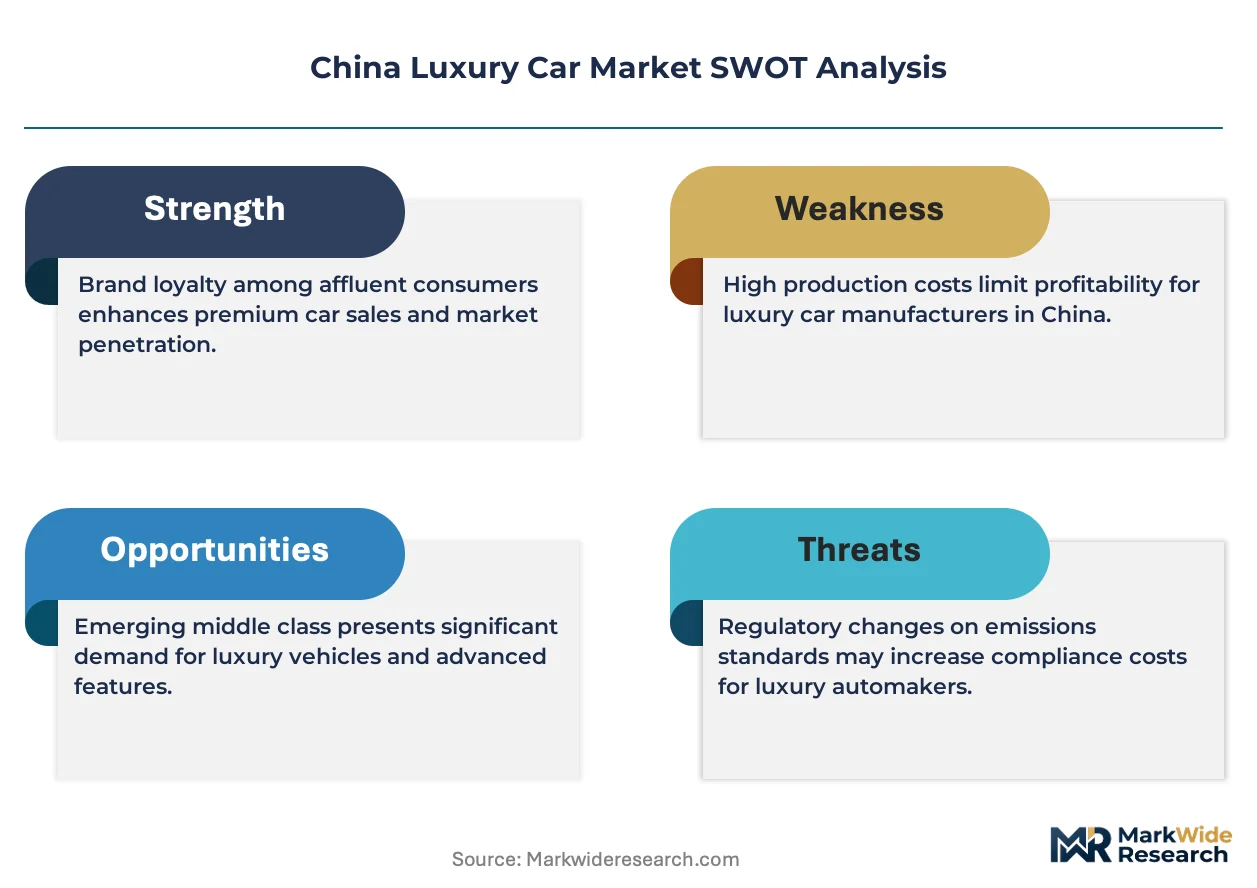
MIIT's dual-credit policy and NMPA's intelligent connected vehicle certification framework jointly dictate powertrain mix and autonomous driving feature deployment timelines. GB standards for electromagnetic compatibility and battery safety create compliance thresholds that filter smaller entrants from premium positioning. Stakeholders must monitor MIIT's evolving NEV subsidy taper schedule and local government plate lottery restrictions to anticipate demand inflection points in core urban markets.
Market Dynamics
MIIT's dual-credit policy and NEV plate privileges are structurally redirecting powertrain procurement toward battery-electric architectures, compressing gasoline engine development cycles and forcing luxury marques to recalibrate R&D allocation across intelligent cockpit and autonomous driving capabilities.
Growth Catalysts
- MIIT Production Quotas:Mandatory NEV credit requirements force domestic and joint-venture manufacturers to electrify premium lineups, accelerating battery-electric model launches in the RMB 300,000-plus segment.
- Battery-Swap Infrastructure Standards:National technical specifications for interchangeable battery packs reduce range anxiety among urban buyers, unlocking fleet adoption for executive transport services in dense metropolitan corridors.
- Yangtze River Delta Cluster Demand:Concentrated affluent household formation in Shanghai, Hangzhou, and Suzhou generates sustained order flow for intelligent electric SUVs with advanced driver-assistance systems.
Market Restraints
- Lithium-Ion Cell Cost Volatility:Cathode material price swings compress gross margins on battery-electric luxury vehicles, forcing OEMs to absorb input spikes or risk volume erosion.
- Semiconductor Supply Concentration:Advanced node chip fabrication for intelligent cockpits concentrates among Taiwan-based foundries, exposing premium brands to geopolitical disruption risks.
- GB Standards Compliance Burden:Electromagnetic compatibility and battery safety certification timelines extend product launch windows by 8-14 months versus gasoline equivalents.
Strategic Opportunities
- Greater Bay Area Penetration:Shenzhen and Guangzhou's technology-forward consumer base remains underpenetrated by battery-swap networks, offering first-mover expansion potential for infrastructure-anchored positioning.
- Autonomous Valet Parking Integration:Convergence of lidar perception stacks with high-definition mapping enables premium brands to differentiate through automated parking in constrained urban environments.
- State Fleet Electrification Mandates:Ceremonial and government procurement directives favor domestic luxury marques with established NEV portfolios, opening institutional volume channels.
Industry Challenges
- Intelligent Systems Integration Complexity:Harmonizing third-party autonomous driving software with proprietary vehicle architectures demands specialized embedded systems engineering talent scarce in traditional powertrain organizations.
- Battery Recycling Certification:MEE's evolving extended producer responsibility frameworks require OEMs to establish closed-loop material recovery infrastructure ahead of regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Luxury Car Market |
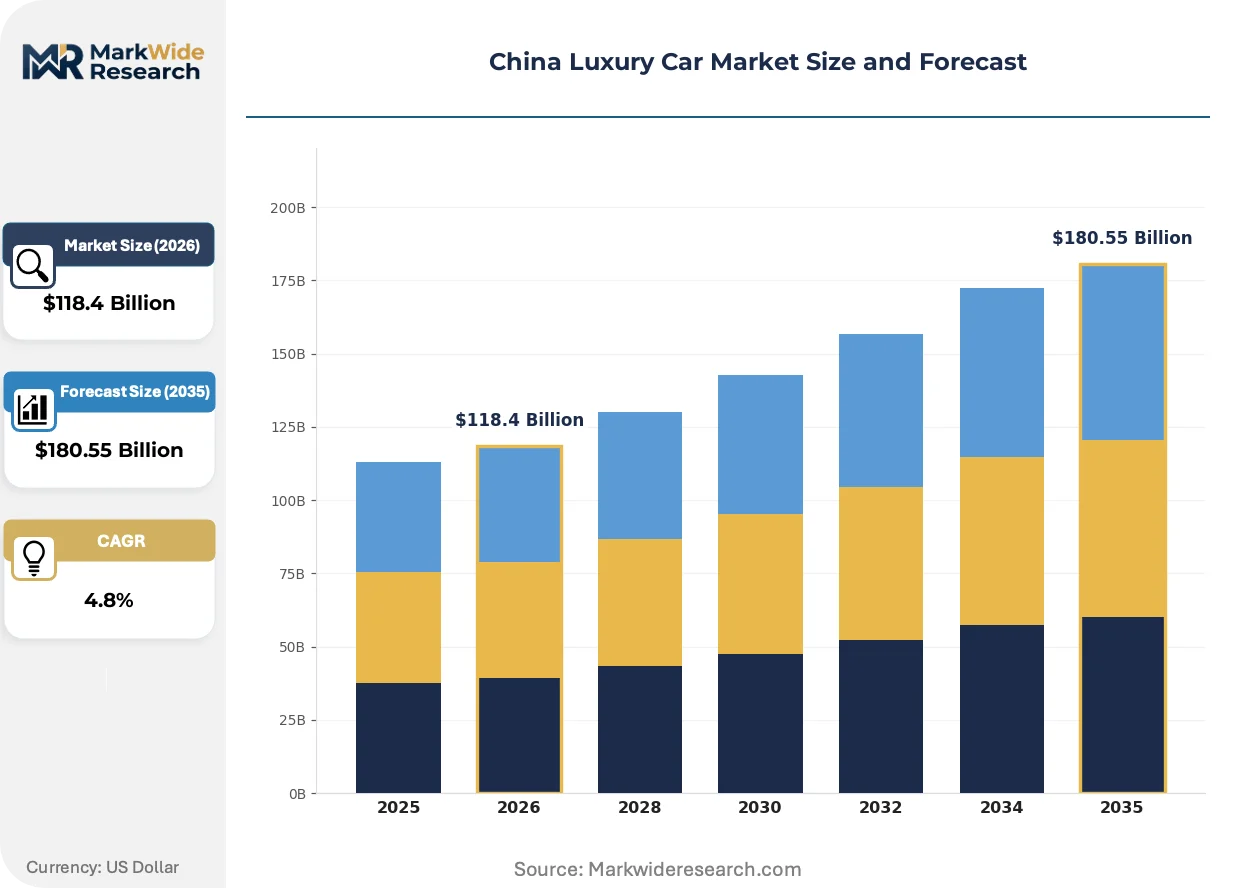
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $180.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Coupe, Convertible Drive Type: All-Wheel Drive, Rear-Wheel Drive, Front-Wheel Drive, Four-Wheel Drive Powertrain: Gasoline, Diesel, Hybrid, Electric End User: Corporate Fleets, Individual Buyers, Car Rental, Dealerships |
| Companies Covered | Li Auto, Zeekr, BYD, AITO, HiPhi, NIO, Hongqi, Avatar, XPeng, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Luxury Car Market Strategic Shifts & Innovations
Intelligent cockpit systems and solid-state battery chemistries are compressing traditional hardware-software boundaries, forcing luxury marques to restructure supplier relationships and internal development hierarchies around continuous over-the-air capability deployment.
Solid-state electrolyte technology is converging with silicon-anode architectures to deliver energy density improvements exceeding 40% versus conventional lithium-ion cells. Premium battery-electric SUVs targeting the RMB 500,000-plus segment are adopting these chemistries first, with pilot production lines operational in Jiangsu and Zhejiang provinces. This convergence is compressing charging duration benchmarks from 30 minutes to under 15 minutes, redefining convenience expectations among time-constrained executive buyers.
NMPA's intelligent connected vehicle certification framework mandates standardized data logging and cybersecurity protocols for all Level-2-plus autonomous driving features. The regulation forces luxury OEMs to redesign electronic architecture hierarchies, segregating safety-critical from infotainment domains. Flagship sedans with highway pilot capabilities face the steepest compliance costs, driving consolidation among domestic sensor fusion suppliers.
Direct-to-consumer configuration platforms are displacing traditional dealership inventory models in tier-one cities. Affluent buyers in Beijing and Shanghai now expect real-time production slot visibility and bespoke interior material selection, compressing order-to-delivery cycles from 12 weeks to under 4 weeks. This behavioral shift pressures legacy joint-venture distribution networks to digitize capital-intensive showroom assets or cede volume to native electric brands with asset-light retail footprints.
China Luxury Car Market Segmentation
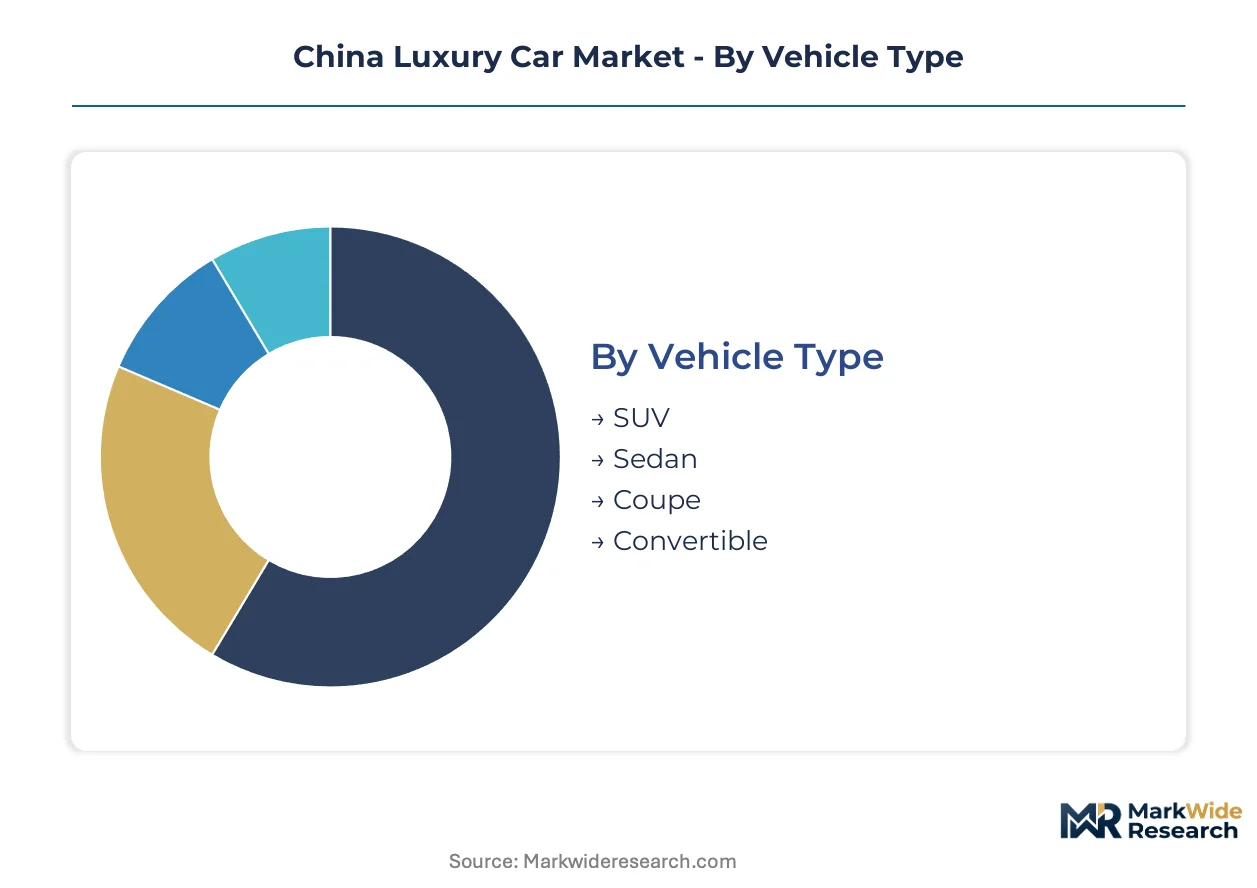
Segmentation in the China luxury car market reveals how MIIT regulations and regional purchasing power concentrate investment across distinct technical configurations. Understanding these divisions exposes where capital deployment meets policy compliance and consumer preference.
Vehicle Type:
Capital intensity varies sharply across body styles, with platform engineering and tooling costs scaling with vehicle size and structural complexity.
- SUV:Three-row and extended-wheelbase architectures dominate family purchasing in Shanghai and Hangzhou, where NEV plate privileges accelerate battery-electric SUV orders. MIIT production quotas favor electrified SUV platforms with higher credit generation potential.
- Sedan:Long-wheelbase configurations serve ceremonial fleet contracts and executive transport, requiring reinforced chassis engineering for rear-seat comfort. State procurement directives sustain absorption of domestic flagship sedans.
- Coupe:Low-volume specialty body style targeting younger affluent buyers in Shenzhen and Guangzhou.
- Convertible:Niche segment constrained by air quality concerns and limited seasonal demand in northern provinces.
SUV absorbs the bulk of installed capacity; Sedan is expanding most quickly through fleet electrification mandates.
Drive Type:
Engineering complexity and component sourcing depth separate all-wheel architectures from simpler configurations.
- All-Wheel Drive:Dual-motor electric implementations command premium positioning in the Yangtze River Delta, where torque-vectoring capabilities differentiate intelligent electric SUVs. Torque distribution algorithms require sophisticated ECU integration.
- Rear-Wheel Drive:Traditional layout retained for executive sedans serving state fleet customers.
- Front-Wheel Drive:Entry-luxury positioning with lower manufacturing complexity.
- Four-Wheel Drive:Off-road capability focus limited to specialized SUV variants.
All-Wheel Drive captures the highest engineering investment; Rear-Wheel Drive maintains institutional volume through ceremonial procurement.
Powertrain:
Regulatory pressure and battery supply chain scale determine where manufacturing capital flows most heavily.
- Electric:Blade battery and solid-state pilot lines in Jiangsu and Zhejiang provinces anchor premium positioning, with charging infrastructure density in tier-one cities reducing range anxiety. MIIT dual-credit policy accelerates model launches above RMB 300,000.
- Hybrid:Plug-in architectures bridge gasoline infrastructure and electrification requirements in cities with plate lottery restrictions.
- Gasoline:Compressed to performance variants and legacy fleet replacements.
- Diesel:Minimal presence restricted to commercial-adjacent applications.
Electric commands the steepest capital allocation; Hybrid gains share fastest in markets with charging infrastructure gaps.
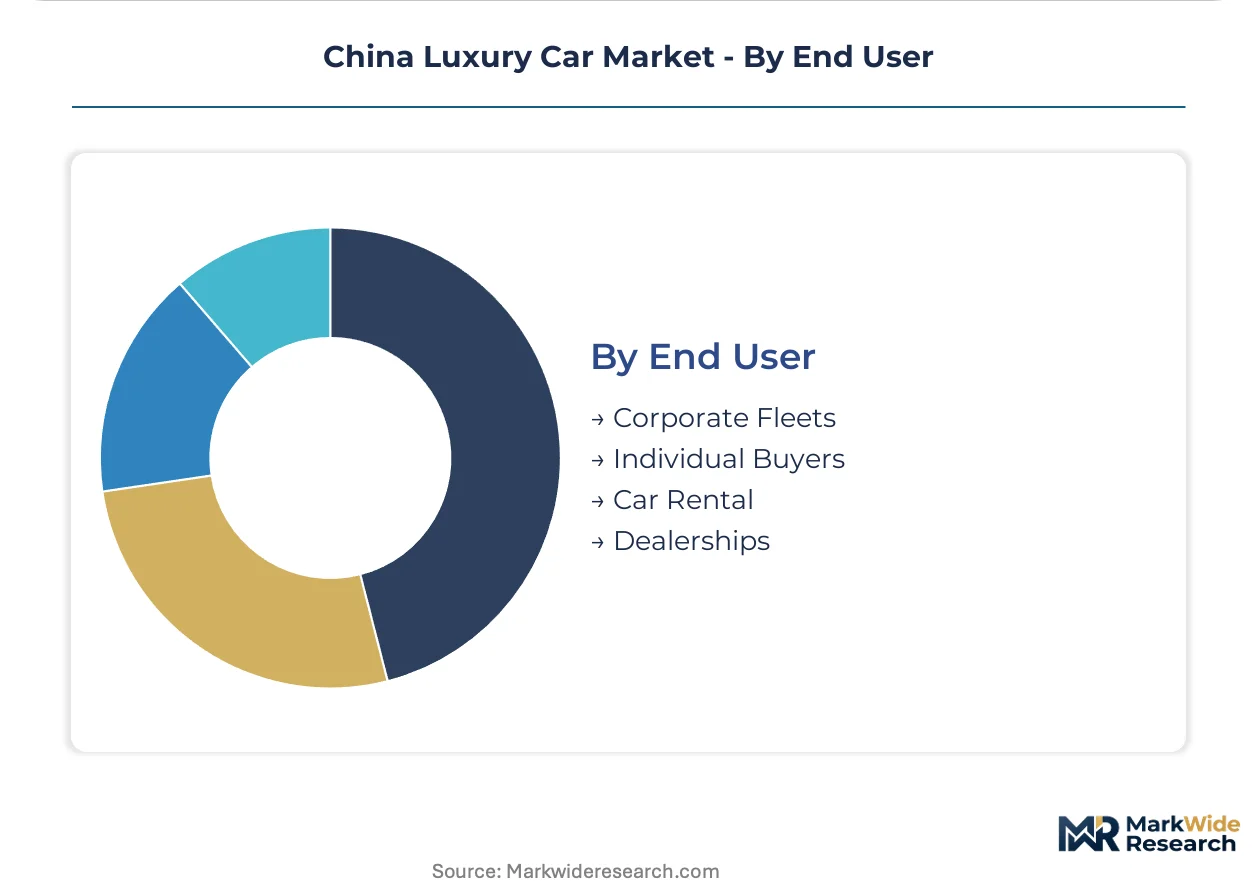
End User:
Customer type dictates margin structure, with direct-to-consumer platforms reshaping traditional distribution economics.
- Individual Buyers:Beijing and Shanghai consumers demand real-time configuration visibility and sub-four-week delivery cycles, compressing legacy dealership models. Bespoke interior material selection drives margin expansion.
- Corporate Fleets:State-owned enterprise procurement favors domestic marques with established NEV portfolios and battery-swap network coverage.
- Car Rental:Fleet operators prioritize battery-swap compatibility for utilization rate optimization.
- Dealerships:Traditional inventory models under pressure from direct-sales digitization.
Individual Buyers generate the deepest margin pool; Corporate Fleets deliver volume stability through institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate refining capacity in Qinghai and Sichuan provinces anchors battery supply chains that feed assembly plants across eastern China. Provincial governments in these mineral-rich zones compete to attract cathode material foundries through land concessions and power tariff discounts.
Yangtze River Delta
Shanghai, Hangzhou, and Suzhou concentrate affluent household formation and NEV plate lottery exemptions that accelerate battery-electric SUV orders. MIIT dual-credit quotas force joint-venture manufacturers to electrify premium lineups above RMB 300,000. NIO's battery-swap corridors and BYD's blade battery foundries in Jiangsu province anchor intelligent electric vehicle production.
Pearl River Delta
Shenzhen and Guangzhou technology-sector executives generate demand for intelligent cockpit systems and autonomous valet parking capabilities. Local governments extend NEV purchase subsidies beyond national taper schedules to sustain manufacturing employment. XPeng anchors software-defined vehicle development in Guangzhou, while supply chains for lidar perception stacks concentrate in Dongguan precision manufacturing zones.
Beijing-Tianjin-Hebei
State-owned enterprise headquarters and government procurement offices sustain ceremonial fleet demand for domestic flagship sedans. SAMR enforcement of GB standards for electromagnetic compatibility filters smaller entrants from premium positioning. Hongqi leverages state-backed heritage contracts in Beijing, while Li Auto targets family buyers in suburban Hebei corridors with extended-range architectures.
Sichuan-Chongqing
Western China consumption growth and lithium mining proximity attract cathode material investments from Yangtze River Delta suppliers. Provincial infrastructure spending targets charging density parity with coastal tier-one cities by 2027. AITO and Avatar position intelligent electric SUVs for inland affluent buyers seeking differentiation from coastal brand saturation.
Shandong Peninsula
Qingdao and Yantai industrial bases host German joint-venture assembly plants adapting gasoline-era capacity for plug-in hybrid production. Local port infrastructure supports cobalt and nickel concentrate imports for precursor chemical processing. HiPhi and Zeekr target peninsula consumers with design-forward battery-electric configurations distinct from state-centric Beijing preferences.
China Luxury Car Market Key Industry Players
Global majors compete with regional champions across powertrain electrification timelines and intelligent system integration depth. The vendor base stratifies between legacy joint-ventures with gasoline heritage, state-backed domestic marques with ceremonial fleet access, and native electric specialists with asset-light retail footprints. Three archetypes dominate: infrastructure-anchored battery-swap operators, vertically integrated battery producers, and software-defined vehicle platforms. Competitive moves concentrate on charging network territorial expansion and solid-state battery pilot line commissioning.
Within the native electric specialist tier, NIO, BYD, and XPeng exemplify divergent strategic positioning. NIO occupies the infrastructure-anchored position through proprietary battery-swap network deployment. BYD represents captive battery supply chain control via in-house blade cell manufacturing. XPeng sits within the software-defined vehicle archetype, emphasizing autonomous driving algorithm development. These three Chinese Co., Ltd. structures illustrate how domestic capital allocation now favors intelligent system integration over traditional powertrain engineering.
| Leading Market Players |
|---|
| Li Auto |
| Zeekr |
| BYD |
| AITO |
| HiPhi |
| NIO |
| Hongqi |
| Avatar |
| XPeng |
| Others |
Cost & Logistics Intelligence
State-owned enterprise procurement offices anchor institutional demand for domestic flagship sedans, sustaining contract-based long-term offtake pricing that insulates Hongqi and similar marques from retail margin volatility. This buyer concentration compresses price transparency in the ceremonial fleet tier while amplifying cost pass-through leverage for battery-electric SUVs targeting individual buyers in Shanghai and Hangzhou.
Pricing Analysis
Warranty and battery-swap service bundling separates NIO's subscription-anchored pricing from BYD's transactional per-unit model, with the former capturing recurring revenue streams against the latter's upfront margin recognition. Three-tier pricing structure across premium, standard, and economy levels stratifies by intelligent cockpit certification grade and autonomous driving capability tier. Pricing pressure stems from lithium carbonate cathode material cost swings that OEMs must absorb to maintain volume. Corporate fleet buyers exhibit highest price sensitivity due to total-cost-of-ownership procurement mandates, while individual buyers in Beijing and Shanghai show lowest sensitivity to base vehicle pricing when bespoke interior configuration is available.
Supply Chain Analysis
MIIT domestic-content mandates for NEV production quotas reshape sourcing patterns, compelling joint-venture manufacturers to localize battery pack assembly and electric motor production within Jiangsu and Zhejiang provinces. The supply chain draws from South Korean cathode material foundries, Australian lithium spodumene concentrate, and Japanese silicon-anode pilot lines. Single-source vulnerability concentrates in Taiwan-based advanced node semiconductor fabrication for intelligent cockpit systems. Distribution runs through direct-to-consumer configuration platforms displacing legacy dealership inventory models in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery pilot line commissioning bottlenecks prop pricing power for early movers, constraining supply expansion faster than Yangtze River Delta demand absorption.
For Market Incumbents: Deploy battery-swap network territorial expansion to lock in infrastructure-anchored positioning before competitors replicate NIO's urban corridor coverage. Deepen in-house blade cell production capacity to insulate gross margins from cathode material volatility. Counter emerging software-defined vehicle specialists by accelerating over-the-air capability deployment timelines. For New Entrants and Emerging Players: MIIT's dual-credit policy in China opens a window for battery-electric SUV launches above RMB 300,000 targeting underpenetrated Greater Bay Area metropolitan corridors. Exploit white-space in Shenzhen and Guangzhou autonomous valet parking integration where lidar perception stack suppliers concentrate. Pursue asset-light direct-sales digitization to bypass capital-intensive legacy dealership networks. For Investors and Strategic Acquirers: The window for entry favors vertically integrated battery producers with captive cathode material sourcing and solid-state pilot line operational readiness. Long-term viability hinges on intelligent system integration depth rather than traditional powertrain engineering scale. Monitor MIIT NEV subsidy taper schedules as inflection indicator for demand velocity shifts in core urban markets.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode material offtake from Qinghai lithium refining capacity for premium SUV production. |
| Software-Defined Vehicle Investment | Accelerates NMPA Level-2-plus autonomous driving certification timelines for highway pilot features. |
| Charging Infrastructure Partnership | Expands battery-swap corridor density across Yangtze River Delta metropolitan clusters beyond NIO's proprietary network. |
| Geographic Manufacturing Footprint | Establishes assembly presence in Sichuan-Chongqing corridor proximate to lithium mining and western consumption growth. |
| Platform Standardization | Reduces engineering complexity across electric SUV and sedan variants to compress GB standards compliance timelines. |
Research Approach
Document review covered MIIT production quota filings, NMPA intelligent connected vehicle certification records, and provincial NEV subsidy schedules, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, battery cell manufacturing executives, and dealership operations managers. Secondary validation drew from vehicle production databases, customs records of lithium concentrate imports, and IHS Markit registration data. Bottom-up model triangulation against top-down macroeconomic absorption capacity checks ensured cross-verification.
Segment-level volume and value trajectories across the analysis window reflect powertrain architecture, vehicle class, and regional production cluster dimensions. CAGRs were derived from regression against MIIT credit generation requirements and NEV plate lottery exemption schedules. Model inputs incorporated solid-state battery pilot line commissioning timelines and intelligent cockpit semiconductor availability constraints.
Caveats apply where MIIT subsidy taper acceleration, Taiwan semiconductor supply disruption, or GB standards compliance timeline extensions could materially shift the outlook. Forecasts embed assumptions around cathode material price stabilization and battery-swap infrastructure standardization adoption velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
North American Lightweight Car Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Automotive Luxury Vehicle Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Europe Luxury Car Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
North America MUV Rental Market
Passenger Vehicles
Family Car Market