
 Spain Mobile Payment Market | 2026-2036
Spain Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Mobile Payment Market Analytics
Mobile payment engineering talent scarcity in Spain is bifurcating platform development between Madrid's fintech clusters and outsourced technical teams. Banco Santander leverages its proprietary digital infrastructure to control merchant onboarding at scale. CaixaBank S.A. anchors its position through deep integration with the domestic ATM and POS network. Bizum specializes in peer-to-peer instant transfers, dominating the social payment niche among Spanish consumers.
Spain mobile payment systems encompass software architectures enabling fund transfer via smartphones using NFC, QR codes, or tokenized card credentials, operating through encrypted APIs connected to banking cores and card schemes. These systems serve commercial purpose by collapsing checkout friction for merchants while giving consumers unified transaction history across fragmented retail channels. Wallets lead transaction volume among payment methods due to super-app bundling of loyalty and transit functions. P2P payments within transaction types capture the fastest growth trajectory as social splitting and informal commerce expand. Integrated payments in service type command the deepest margin pools by locking merchants into full-stack acquiring and analytics.
Banco de España supervises payment service licensing under EU PSD2 mandates, while the CNMC enforces interoperability and anti-competitive barriers among domestic networks. GDPR compliance requirements shape how transaction data flows between wallets, merchants, and analytics providers, constraining personalization revenue models. Stakeholders must monitor whether upcoming EU Digital Euro pilots redirect transaction volume away from private wallet ecosystems.
Market Dynamics
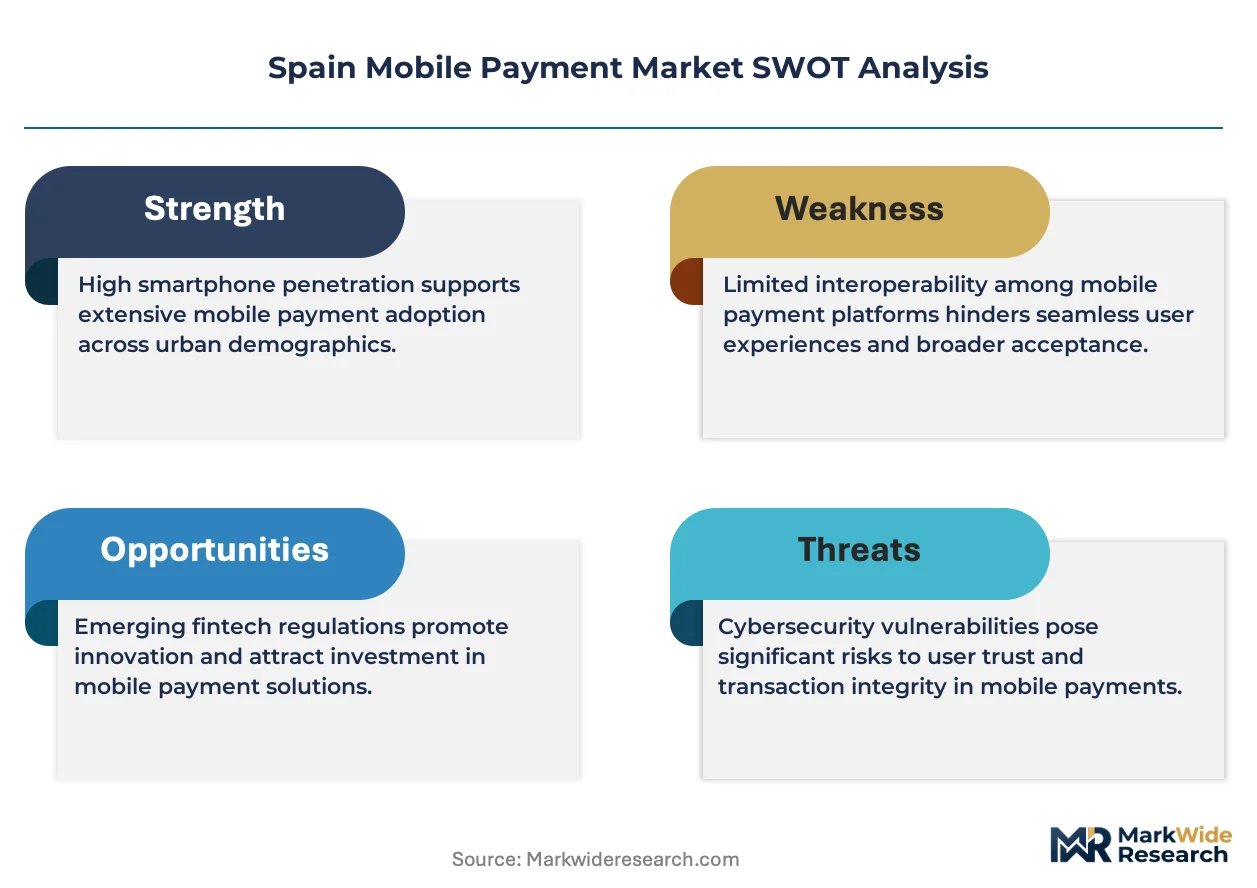
PSD2 Strong Customer Authentication mandates are forcing Spanish banks and wallet providers to rebuild checkout flows around biometric verification and tokenized credentials, compressing legacy card-not-present architectures.
Growth Catalysts
- PSD2 Open Banking Framework:Regulatory mandates for account-to-account payment initiation are opening core banking infrastructure to licensed third-party providers, expanding wallet interoperability.
- NFC Transit Integration:Barcelona and Madrid metropolitan transit authorities are embedding fare payment directly into mobile wallets, driving habitual daily usage.
- P2P Social Splitting:Informal commerce and group expense sharing among Spanish consumers are accelerating real-time transfer volumes through domestic instant payment rails.
Market Restraints
- Merchant Acquiring Concentration:Domestic ATM and POS network control by incumbent banks limits fintech pricing power and onboarding speed for independent retailers.
- GDPR Data Friction:Transaction history personalization for loyalty analytics requires explicit consent workflows that reduce conversion rates at wallet enrollment.
- Interchange Fee Compression:EU-wide caps on card scheme fees constrain revenue pools available to fund consumer cashback and merchant incentive programs.
Strategic Opportunities
- Andalusia and Valencia Expansion:Underpenetrated merchant corridors outside Madrid and Barcelona offer first-mover advantage for QR-code wallet deployment in mid-sized retail.
- Super-App Bundling:Convergence of loyalty points, transit, and insurance into single wallet interfaces is deepening user retention and session frequency.
- Digital Euro Pilot Participation:Early integration with European Central Bank retail CBDC trials positions wallets for programmable payment features and settlement finality.
Industry Challenges
- Engineering Talent Scarcity:Mobile payment platform development expertise concentrates in Madrid fintech clusters, forcing reliance on outsourced technical teams for core architecture.
- Legacy Core Integration:Banking infrastructure built on batch-processing mainframes requires expensive API middleware to support real-time wallet transaction posting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Mobile Payment Market |
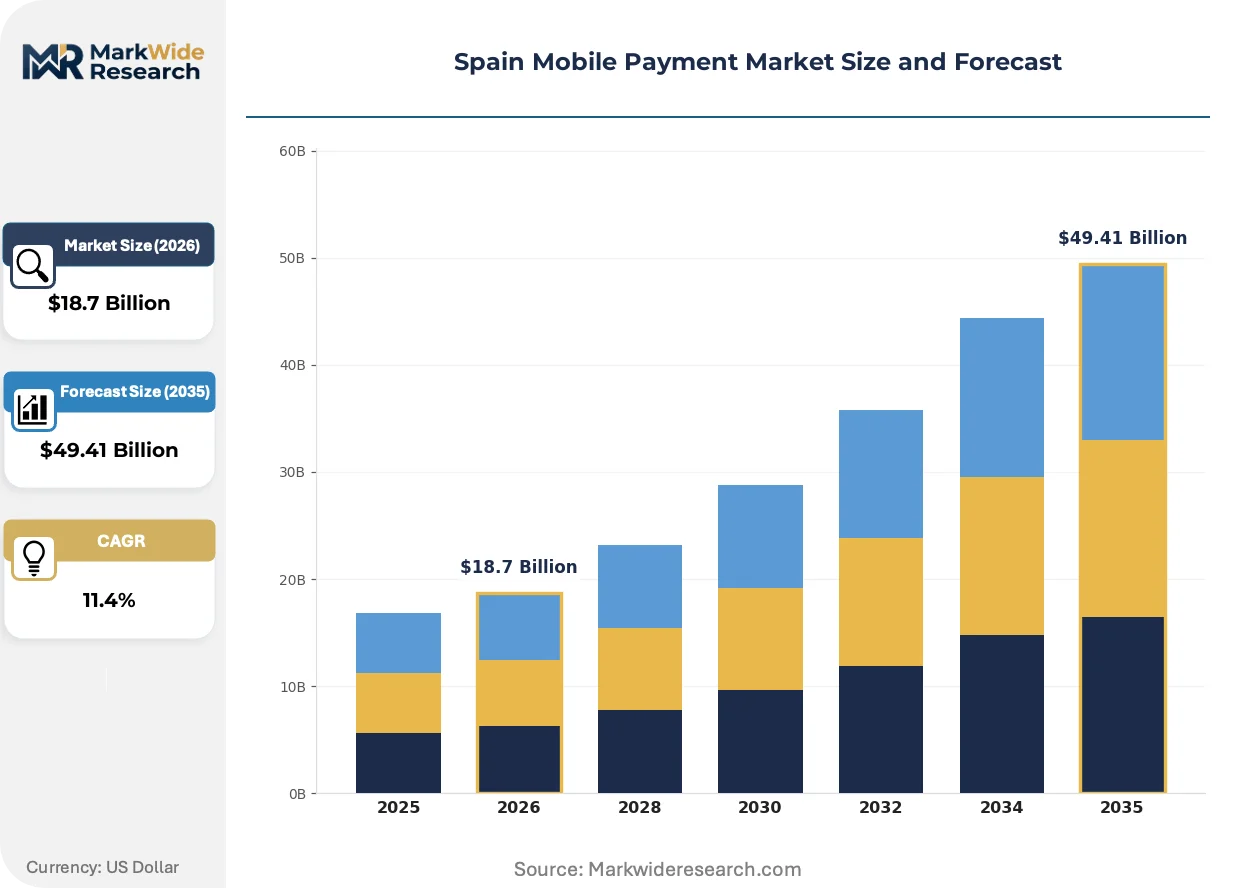
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Wallets, Credit Cards, Direct Bank Transfers, QR Code Payment End User: Retailers, Restaurants, E-commerce Platforms, Consumers Transaction Type: P2P Payments, In-store Payments, Online Payments, Recurring Payments Service Type: Integrated Payments, Standalone Solutions, Payment Processing, Transaction Security |
| Companies Covered | Banco Bilbao Vizcaya Argentaria S.A., Banco Santander, PayPal Holdings, Inc., Redsys, Telefonica, Apple Inc., CaixaBank S.A., Bizum, Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Mobile Payment Market Evolving Landscape
Spanish mobile payment architecture is pivoting from card credential storage toward tokenized identity and biometric verification layers, with regulatory compliance and user experience convergence driving vendor roadmaps.
Decentralized identity verification is fragmenting traditional know-your-customer workflows. Wallet providers are adopting reusable digital credentials issued by Banco de España-supervised entities. Mid-market fintechs are piloting bank-grade biometric onboarding without branch visits. This fragmentation is compressing customer acquisition costs while raising compliance audit complexity for smaller platforms.
EU AI Act risk classification rules are reshaping fraud detection algorithm deployment. Payment service providers must document automated decision-making logic for transaction blocking. Spanish issuers are retraining models on explainable feature sets rather than black-box neural networks. High-risk merchant categories face heightened scrutiny and manual review queue expansion.
Merchant switching cycles are compressing as integrated payment-acquiring bundles displace standalone POS terminals. Spanish retailers now evaluate wallet acceptance alongside inventory analytics and working capital lending in single procurement decisions. Independent software vendors are embedding checkout into vertical SaaS for hospitality and healthcare, capturing merchant relationships before banks can onboard directly.
Spain Mobile Payment Market Segmentation
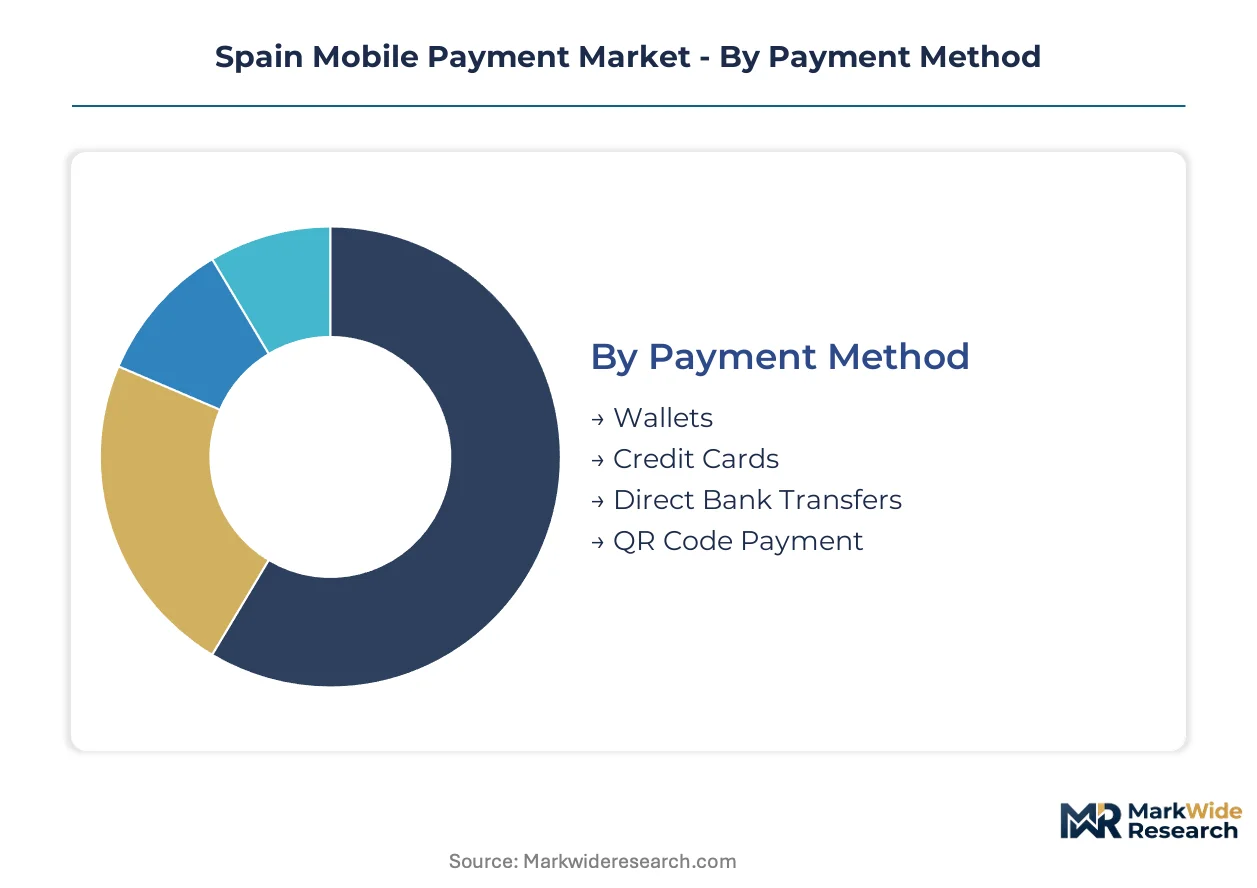
Mobile payment segmentation in Spain reveals how regulatory frameworks and infrastructure maturity create divergent growth trajectories across transaction modes and service architectures. Understanding these divisions exposes where Banco de España oversight and PSD2 compliance obligations concentrate competitive investment.
Payment Method:
PSD2 Strong Customer Authentication mandates differentiate technical requirements across credential storage architectures, with biometric verification layers creating compliance cost tiers.
- Wallets:NFC-enabled smartphone applications tokenize card credentials through encrypted secure elements. Barcelona and Madrid transit integration drives habitual daily usage among urban commuters. Merchants capture unified transaction history across fragmented retail channels.
- Credit Cards:Tokenized card-not-present credentials operate through 3D Secure protocols with biometric step-up authentication. Legacy interchange fee compression constrains cashback funding for consumer incentive programs.
- Direct Bank Transfers:Account-to-account payment initiation leverages open banking APIs under PSD2 licensing. SEPA Instant Credit Transfer rails enable real-time settlement without card scheme intermediaries.
- QR Code Payment:Static and dynamic barcode generation enables low-cost merchant acceptance without POS terminal investment. Andalusia and Valencia mid-sized retailers adopt for offline-to-online conversion.
Established volume favors Wallets; emerging adoption favors QR Code Payment.
End User:
Merchant scale and technical sophistication determine integration complexity, with enterprise procurement cycles diverging from sole proprietor onboarding patterns.
- Retailers:Brick-and-mortar merchants demand inventory analytics integration alongside checkout functionality. CaixaBank S.A. anchors acquiring relationships through domestic ATM network control.
- Restaurants:Tableside payment and tip distribution workflows require hospitality-specific software embedding. Independent software vendors capture merchant relationships before direct bank onboarding.
- E-commerce Platforms:Marketplace operators need split payment routing and escrow functionality for multi-vendor settlements. GDPR consent workflows reduce conversion rates at wallet enrollment.
- Consumers:Peer-to-peer social splitting and informal commerce drive real-time transfer demand through Bizum's domestic rails.
Merchant concentration favors Retailers; platform expansion favors E-commerce Platforms.
Transaction Type:
Settlement timing and authentication friction separate instant social payments from scheduled recurring architectures.
- P2P Payments:Real-time transfers between individuals exploit SEPA Instant rails for social expense splitting. Spanish consumers dominate this channel for informal commerce and group cost sharing.
- In-store Payments:NFC tap-to-pay and QR scanning collapse checkout friction at physical merchant locations. Transit authority embedding in Barcelona and Madrid metropolitan networks deepens habitual usage.
- Online Payments:Card-not-present transactions require stepped-up biometric verification under PSD2 mandates. Tokenized credentials reduce fraud exposure for e-commerce checkout.
- Recurring Payments:Subscription billing and utility direct debits demand mandate management and pre-notification compliance. SEPA Direct Debit Core and B2B schemes handle periodic settlement.
Volume concentration favors In-store Payments; steepest expansion trajectory favors P2P Payments.
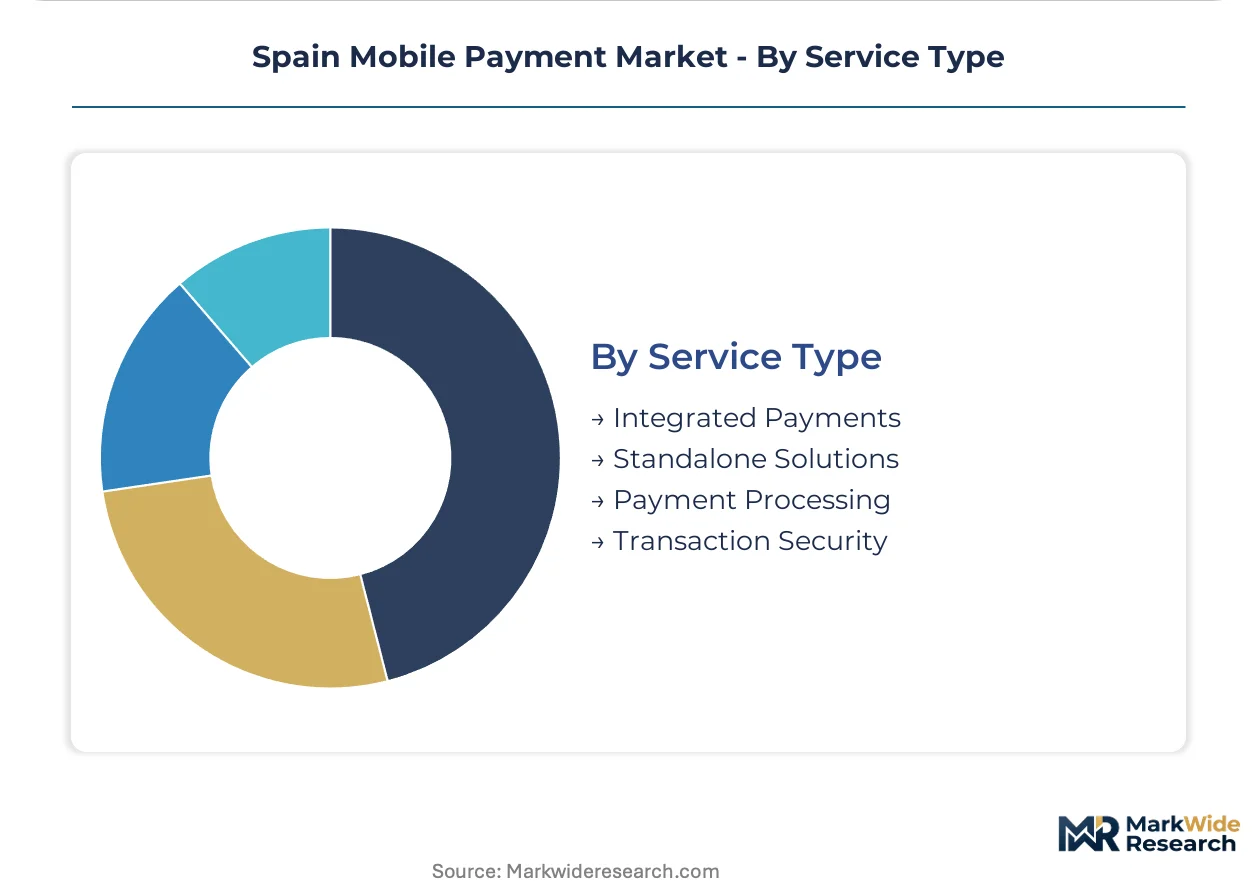
Service Type:
Margin depth correlates with stack completeness, with full-suite acquiring bundles commanding premium positioning over standalone transaction processing.
- Integrated Payments:Full-stack acquiring combines checkout, analytics, and working capital lending in single procurement decisions. Spanish retailers now evaluate wallet acceptance alongside inventory management systems.
- Standalone Solutions:Discrete payment gateway services without value-added merchant analytics compete on transaction fee compression. Independent fintechs target price-sensitive micro-merchants.
- Payment Processing:Technical middleware connecting wallets to banking cores and card schemes operates on per-transaction revenue models. Banco Santander leverages proprietary digital infrastructure for scale control.
- Transaction Security:Fraud detection algorithms and biometric verification layers face EU AI Act documentation requirements for automated decision-making. Spanish issuers retrain models on explainable feature sets.
Margin depth favors Integrated Payments; modular demand favors Standalone Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's mobile payment consumption concentrates in Madrid and Barcelona's urban corridors, while Andalusia and Valencia exhibit divergent merchant adoption patterns rooted in infrastructure maturity and demographic density differentials.
Madrid
Capital region commuters drive habitual wallet usage through integrated transit fare payment systems. Banco de España's PSD2 licensing framework governs third-party provider access to core banking infrastructure. The city's fintech cluster houses engineering talent pools that Banco Santander and CaixaBank S.A. compete to retain for platform development.
Catalonia
Barcelona metropolitan transit authority embedding sustains daily NFC tap-to-pay frequency among urban consumers. GDPR consent workflows constrain personalization revenue models for loyalty analytics providers operating across Catalan merchant networks. The region's hospitality sector demands tableside payment software embedding that independent vendors capture before direct bank onboarding.
Basque Country
Industrial SME density generates B2B instant payment demand for supply chain settlement acceleration. The country's national banking supervisor mandates biometric verification layers for account-to-account payment initiation services. Bilbao's merchant acquiring relationships remain anchored through domestic ATM network control by incumbent financial institutions.
Andalusia
Mid-sized retail corridors present first-mover opportunity for QR-code wallet deployment without POS terminal investment. EU interchange fee caps constrain cashback funding available for consumer incentive programs in price-sensitive segments. Seville and Málaga merchant clusters exhibit rising informal commerce volumes that accelerate peer-to-peer social splitting through domestic instant payment rails.
Valencia
Underpenetrated offline-to-online conversion potential attracts fintech pricing competition for independent retailer onboarding. The EU AI Act's risk classification rules reshape fraud detection algorithm deployment for transaction blocking documentation. The metropolitan area's tourism-dependent merchants prioritize unified transaction history across fragmented retail channels for revenue reconciliation.
Spain Mobile Payment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic banking conglomerates controlling merchant acquiring infrastructure while technology platforms and fintech specialists fragment the consumer-facing wallet layer. Incumbent financial institutions leverage proprietary digital infrastructure and ATM network dominance to constrain fintech pricing power. Three archetypes define competitive positioning: banking-led full-stack acquirers, technology platform enablers, and domestic instant payment rail specialists. Consolidation pressure manifests through merchant switching acceleration toward integrated payment-acquiring bundles, while engineering talent scarcity forces reliance on outsourced technical teams for core architecture development.
Among Spain-based banking conglomerates, Banco Santander and CaixaBank S.A. exemplify the integrated acquirer archetype through control of domestic ATM and POS network infrastructure. Banco Bilbao Vizcaya Argentaria S.A. occupies a parallel position within this tier. Within the specialist segment, Bizum represents the domestic instant payment rail archetype through peer-to-peer transfer dominance, while Redsys anchors technical middleware connectivity between wallets and banking cores.
| Leading Market Players |
|---|
| Banco Bilbao Vizcaya Argentaria S.A. |
| Banco Santander |
| PayPal Holdings, Inc. |
| Redsys |
| Telefonica |
| Apple Inc. |
| CaixaBank S.A. |
| Bizum |
| Google LLC |
| Others |
Value Network & Pricing Analysis
Platform scale economies at major Spanish banks compress merchant acquiring costs while elevating price floors for independent fintechs lacking ATM network control. Banco de España's PSD2 licensing requirements add fixed compliance burdens that disproportionately burden smaller wallet providers, concentrating pricing power among integrated incumbents.
Pricing Analysis
Contract structures in Spanish mobile payments stratify between long-term acquiring bundles and per-transaction SaaS tiers. Three-tier pricing separates integrated full-stack packages from standalone gateway services and micro-merchant QR-code solutions. Price differentiation hinges on transaction volume scale and PSD2 certification tier. Pricing pressure stems from EU interchange fee caps constraining cashback funding for consumer incentives. Independent retailers in Andalusia and Valencia exhibit highest price sensitivity, while Madrid enterprise merchants prioritize analytics integration over fee minimization.
Supply Chain Analysis
Spain and Germany anchor core banking infrastructure development, with Ireland hosting EU regulatory technology centers and India supplying outsourced engineering talent for platform architecture. Critical components include tokenization secure elements from Netherlands-based semiconductor fabricators, biometric verification SDKs licensed from Israeli specialists, and cloud hosting from Irish and German hyperscale facilities. Supply chain risk centers on single-source vulnerability for SEPA Instant rail connectivity through Redsys middleware. Distribution runs through direct bank sales forces for enterprise merchants and independent software vendor marketplaces for hospitality and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spanish mobile payment value creation is shifting toward recurring revenue layers, with integrated analytics and working capital lending expanding faster than transaction processing hardware. Service attach rates for merchant software bundles now exceed standalone terminal deployment economics.
For Market Incumbents: Consolidate merchant relationships through exclusive transit authority partnerships before fintechs capture habitual daily usage. Deepen vertical integration into biometric verification technology to reduce third-party SDK licensing costs. Defend against independent software vendors embedding checkout into hospitality SaaS by accelerating direct API partnerships with restaurant management platforms. For New Entrants and Emerging Players: Embedded finance gaps in healthcare and logistics verticals offer white-space penetration where CaixaBank S.A. and Banco Santander maintain thin direct coverage. Target Andalusia and Valencia mid-sized retail corridors with QR-code deployment requiring zero POS terminal investment. Pursue go-to-market alignment with regional business associations for merchant onboarding at scale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-agnostic middleware specialists over hardware-dependent terminal manufacturers. Long-term viability hinges on PSD2 license portability and SEPA Instant rail access durability. Acquisition screening should prioritize firms with Banco de España supervision history and explainable AI compliance documentation under EU AI Act risk classification. Watch Digital Euro pilot participation announcements as inflection signal for programmable payment capability valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Transit Authority Partnership | Barcelona and Madrid metropolitan embedding locks in habitual daily wallet usage frequency. |
| Biometric Verification Investment | Proprietary onboarding layers reduce third-party SDK dependency and GDPR consent friction. |
| Vertical SaaS Embedding | Independent software vendor checkout integration captures merchant relationships before bank direct sales. |
| Digital Euro Pilot Integration | Early ECB retail CBDC positioning enables programmable payment features and settlement finality. |
| Andalusia QR Deployment | Zero-terminal merchant acceptance expands addressable market beyond POS infrastructure constraints. |
Research Methodology
Initial hypotheses were tested against primary input from payment platform engineers, merchant acquiring executives, regulatory compliance officers, and independent software vendor product managers and refined through secondary validation. Primary fieldwork drew from Banco de España regulatory filings, SEPA scheme statistics, EU PSD2 implementation reports, and Spanish banking association disclosures. Bottom-up transaction volume modeling and top-down GDP-linked payment penetration estimates were triangulated against regional commuter transit data and merchant POS terminal installation records.
Variance decomposition across the projection horizon isolates regulatory implementation timing, transit authority contract renewal cycles, and instant payment rail adoption curves as primary uncertainty sources. Segmentation dimensions modeled include payment method credential architecture, end-user merchant scale tier, transaction type settlement timing, and service type stack completeness. CAGRs were derived from logistic diffusion curves fitted to SEPA Instant volume trajectories and NFC-enabled smartphone penetration benchmarks. Industry-specific forecast inputs incorporate Banco de España licensing pipeline data and GDPR consent workflow conversion benchmarks.
Underlying assumptions cover PSD2 enforcement continuity, SEPA Instant rail technical stability, and EU AI Act documentation requirement phasing, with deviation risk concentrated in Digital Euro pilot scope expansion and interchange fee cap regulatory revisions. Recalibration cycles align with material shifts in Banco de España supervisory guidance and ECB central bank digital currency roadmap updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Transit Cards Market
Payments
Africa Mobile Money Market
Payments
India Buy Now Pay Later Services Market
Payments
Global Mobile Payment Technology Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Argentina Payments Market
Payments
Enterprise Payment Software Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Canada Prepaid Cards Market
Payments
Brazil POS Terminal Market
Payments
Japan Payments Market
Payments
US Virtual Cards Market
Payments
Remote Mobile Payment Market
Payments
Netherlands POS Terminal Market
Payments
Global Utility Billing Software Market
Payments
Australia Payments Market