
 Asia Pacific Buy Now Pay Later Service Market | 2026-2036
Asia Pacific Buy Now Pay Later Service Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Buy Now Pay Later Service Market Outlook
Subscription-based repayment scheduling is decoupling credit risk assessment from traditional banking relationships across the Asia Pacific Buy Now Pay Later Service Market. Grab PayLater leverages its super-app ecosystem to embed installment lending within ride-hailing and food delivery workflows. Kredivo anchors its position in Indonesia through proprietary credit scoring algorithms tailored to thin-file borrowers. Atome differentiates via merchant-funded promotional zero-interest campaigns that drive conversion at physical retail touchpoints.
Buy now pay later services constitute short-term consumer credit instruments enabling purchasers to split transaction costs into equal installments, typically spanning three to six pay cycles, with merchant fees substituting for borrower interest in many structures. The primary commercial purpose centers on reducing cart abandonment and expanding addressable customer bases for merchants serving underbanked or credit-averse demographics. E-commerce and retail product types currently dominate transaction volumes, though healthcare applications are gaining traction as elective procedure financing expands across Thailand and Malaysia. Mobile app platform types lead deployment, while integrated solutions connecting directly to merchant ERP systems represent the fastest-growing configuration as enterprise adoption deepens.
India's Reserve Bank of India digital lending guidelines, Australia's National Consumer Credit Protection Act, and Singapore's Payment Services Act collectively reshape permissible fee structures, disclosure requirements, and cross-border data handling across the region. These frameworks elevate compliance costs for new entrants while favoring established platforms with dedicated regulatory technology infrastructure. Stakeholders must monitor evolving usury interpretations and open banking mandate timelines to anticipate where underwriting advantage will shift next.
Market Dynamics
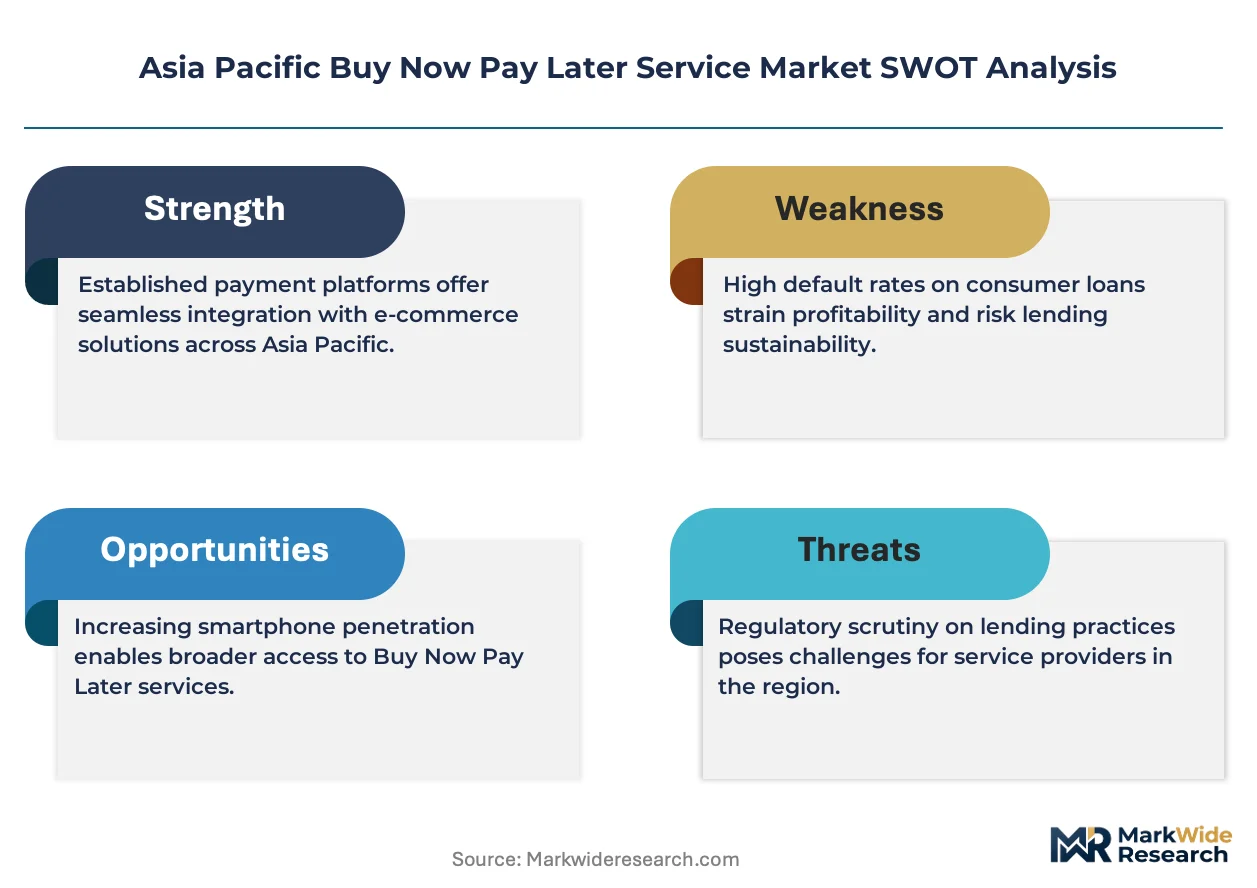
India's Reserve Bank of India digital lending guidelines are forcing platform consolidation across the Asia Pacific Buy Now Pay Later Service Market, favoring scaled operators with dedicated regulatory technology infrastructure over thinly capitalized entrants.
Growth Catalysts
- Indonesia's smartphone penetration:Unbanked consumer pools intersect with mobile-first commerce infrastructure, creating addressable demand for installment credit at digital checkout.
- Singapore's Payment Services Act:Licensing clarity reduces compliance uncertainty for cross-border payment flows, accelerating regional platform expansion into adjacent ASEAN markets.
- Healthcare elective procedures:Elective procedure financing gains traction across Thailand and Malaysia as consumers seek alternatives to traditional medical credit cards.
Market Restraints
- India's usury interpretation risk:Evolving judicial readings of permissible fee structures create uncertainty around merchant-fee sustainability models.
- Australia's National Consumer Credit Protection Act:Mandatory responsible lending assessments extend underwriting timelines and elevate compliance staffing requirements.
- Thin-file algorithmic bias:Proprietary credit scoring systems face scrutiny from regional data protection authorities over exclusionary outcomes for informal sector workers.
Strategic Opportunities
- Vietnam's underpenetrated e-commerce:Low credit card penetration and rising digital commerce adoption create white space for installment lending at checkout.
- ERP-integrated solutions:Direct merchant system connectivity represents the fastest-growing configuration as enterprise retail adoption deepens across the region.
- Thailand's open banking mandate timeline:Scheduled data-sharing protocols will shift underwriting advantage toward platforms with pre-positioned consent-management infrastructure.
Industry Challenges
- Cross-border data handling complexity:Fragmented ASEAN data localization requirements complicate unified credit decisioning across multi-country super-app operations.
- Legacy banking system integration:Real-time settlement protocols with incumbent financial institutions require bespoke API development, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Buy Now Pay Later Service Market |
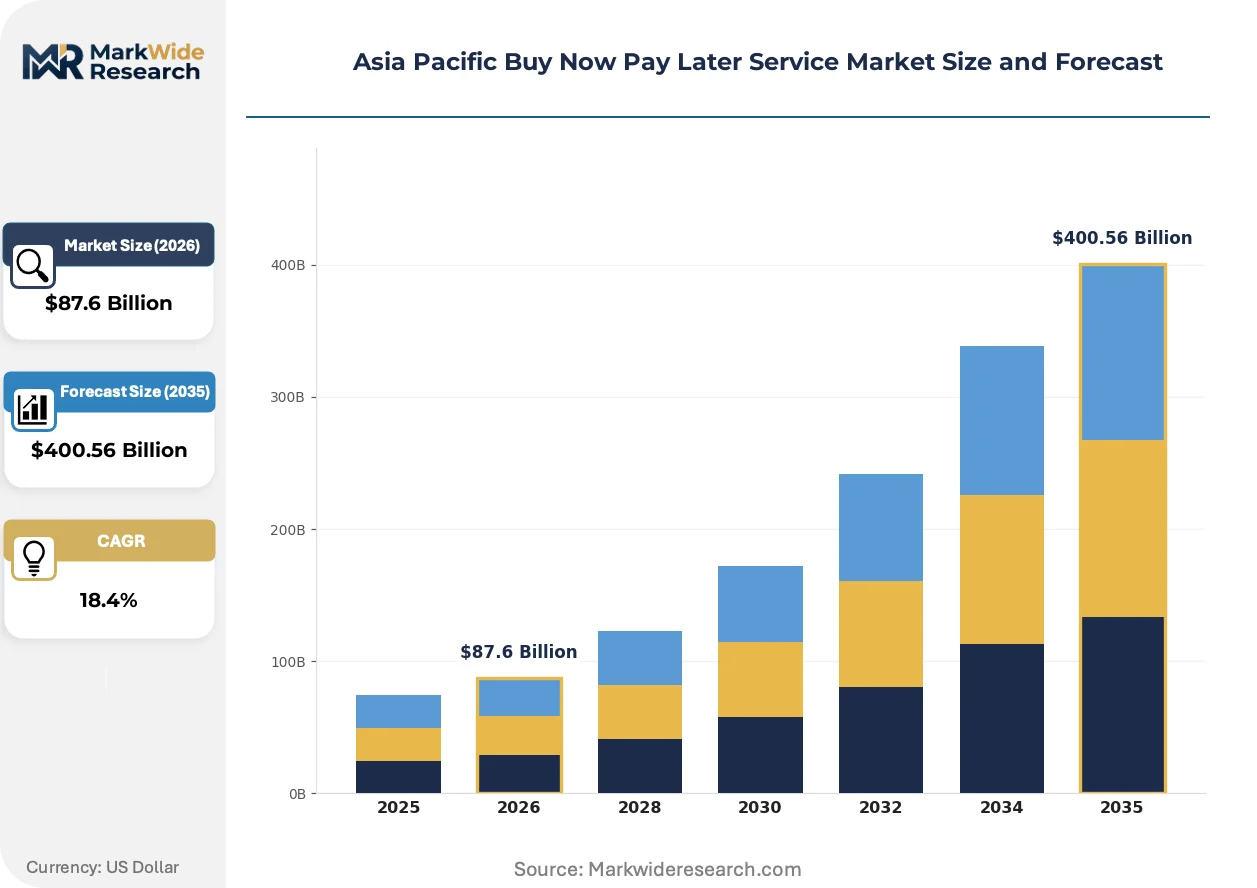
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retail, E-Commerce, Travel, Healthcare Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer End User: Millennials, Gen Z, Small Businesses, Corporates Platform Type: Mobile App, Web Platform, Integrated Solutions, Affiliate Platforms |
| Companies Covered | Afterpay, Grab PayLater, ZestMoney, Shopee PayLater, Kredivo, Atome, PayPay, Klarna, Zip Co, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Buy Now Pay Later Service Market Strategic Shifts
Embedded finance architecture is dissolving traditional boundaries between commerce and credit across Southeast Asia, with super-apps and standalone platforms converging on similar merchant-facing value propositions.
AI-powered alternative credit scoring is expanding into thin-file borrower segments previously excluded from formal financial services. Indonesian platforms deploy machine learning models trained on non-traditional data signals including mobile wallet transaction histories and utility payment patterns. This capability compression is enabling real-time underwriting decisions at sub-second latency, matching the speed expectations of digital-native consumers.
Australia's National Consumer Credit Protection Act amendments are tightening responsible lending disclosure requirements for point-of-sale credit providers. The regulatory consequence elevates operational costs for platforms serving the Australian market while creating compliance differentiation for established operators. Buy now pay later providers are responding by restructuring fee presentations and embedding enhanced hardship protocols into customer journeys.
Merchant-funded promotional campaigns are displacing borrower-interest models as the dominant commercial structure across physical retail touchpoints. Atome and comparable platforms negotiate zero-interest installment terms funded entirely by merchant acquisition spend, compressing consumer price sensitivity. This behavioral shift is most visible in Singapore's premium retail corridor and Jakarta's expanding mall network, where conversion rate optimization drives merchant willingness to absorb financing costs.
Asia Pacific Buy Now Pay Later Service Market Segmentation
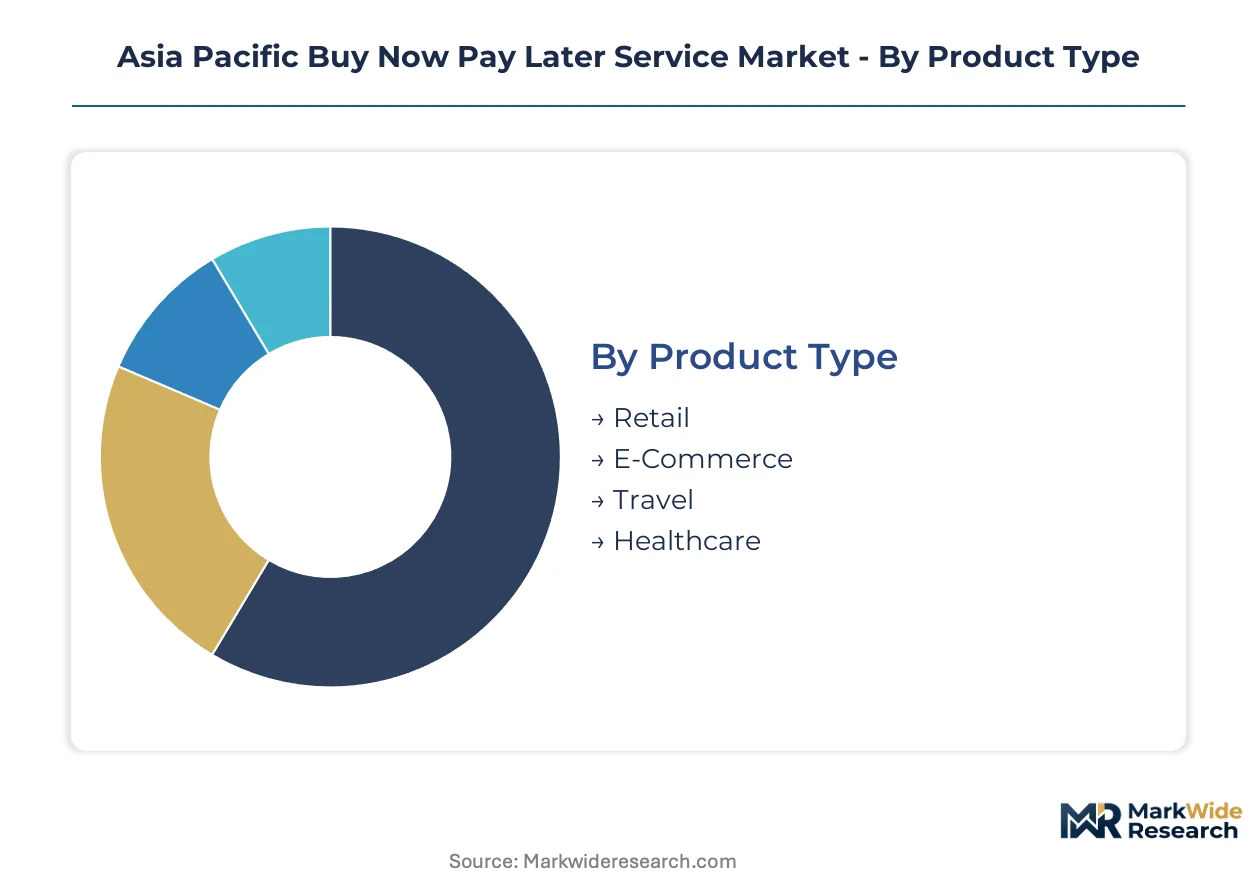
Installment credit providers across Asia Pacific calibrate product architecture around distinct transaction contexts, payment rails, and user demographics. Each segmentation dimension carries specific underwriting implications, merchant integration requirements, and regulatory exposure profiles that shape platform strategy.
Product Type:
Replacement cycles for legacy point-of-sale financing vary dramatically across transaction categories, with digital-native merchants upgrading to embedded installment solutions faster than traditional retail channels.
- E-Commerce:Online checkout integration enables real-time credit decisions at cart completion, with merchant fee absorption replacing consumer interest. Indonesia and Vietnam drive volume concentration as smartphone commerce penetration outpaces credit card issuance.
- Retail:Physical point-of-sale deployment requires QR-code or NFC-enabled terminal infrastructure, extending implementation timelines. Mall operators in Singapore and Jakarta negotiate exclusive platform partnerships to drive foot traffic conversion.
- Healthcare:Elective procedure financing spans cosmetic surgery, dental work, and fertility treatments across Thailand and Malaysia.
- Travel:Airline and hospitality merchants use installment options to reduce booking abandonment during high-ticket purchase consideration.
E-Commerce sits at the top of the volume ranking, with Healthcare climbing the fastest.
Payment Method:
Cost tier differentiation in platform economics flows directly from payment rail selection, with bank transfer structures minimizing interchange leakage compared to card-based alternatives.
- Digital Wallet:Super-app ecosystems in Indonesia and Singapore embed installment repayment within existing wallet balances, reducing friction through unified account management. Grab PayLater and comparable platforms leverage this integration to compress customer acquisition costs.
- Credit Card:Card-linked installment plans preserve existing bank relationships while splitting transactions across billing cycles. Australian issuers face National Consumer Credit Protection Act disclosure requirements that extend onboarding workflows.
- Bank Transfer:Direct account debiting dominates in markets with thin credit card penetration, particularly rural India and Vietnam.
- Debit Card:Real-time balance verification enables conservative underwriting for subprime segments excluded from revolving credit.
Digital Wallet commands the largest transaction share, with Bank Transfer expanding most quickly in underbanked corridors.
End User:
Customer type segmentation determines risk model complexity, with thin-file borrowers requiring alternative data ingestion that established corporate clients bypass entirely.
- Gen Z:First-time credit access without formal banking history drives demand for smartphone-based behavioral scoring. Indonesian platforms deploy machine learning on telco and utility payment patterns to underwrite this cohort.
- Millennials:Salaried employment with documented income supports higher approval limits and shorter repayment tenors. Urban India and metropolitan Southeast Asia concentrate this segment's transaction volume.
- Small Businesses:Working capital smoothing for inventory purchases and supplier payments, distinct from consumer installment structures.
- Corporates:Travel and procurement expense management through centralized billing and reconciliation workflows.
Millennials anchor current volume leadership, with Gen Z gaining share fastest as platform onboarding ages downward.
Platform Type:
Merchant technical maturity dictates deployment architecture, with enterprise retailers demanding ERP-integrated solutions that small merchants replace through lightweight affiliate arrangements.
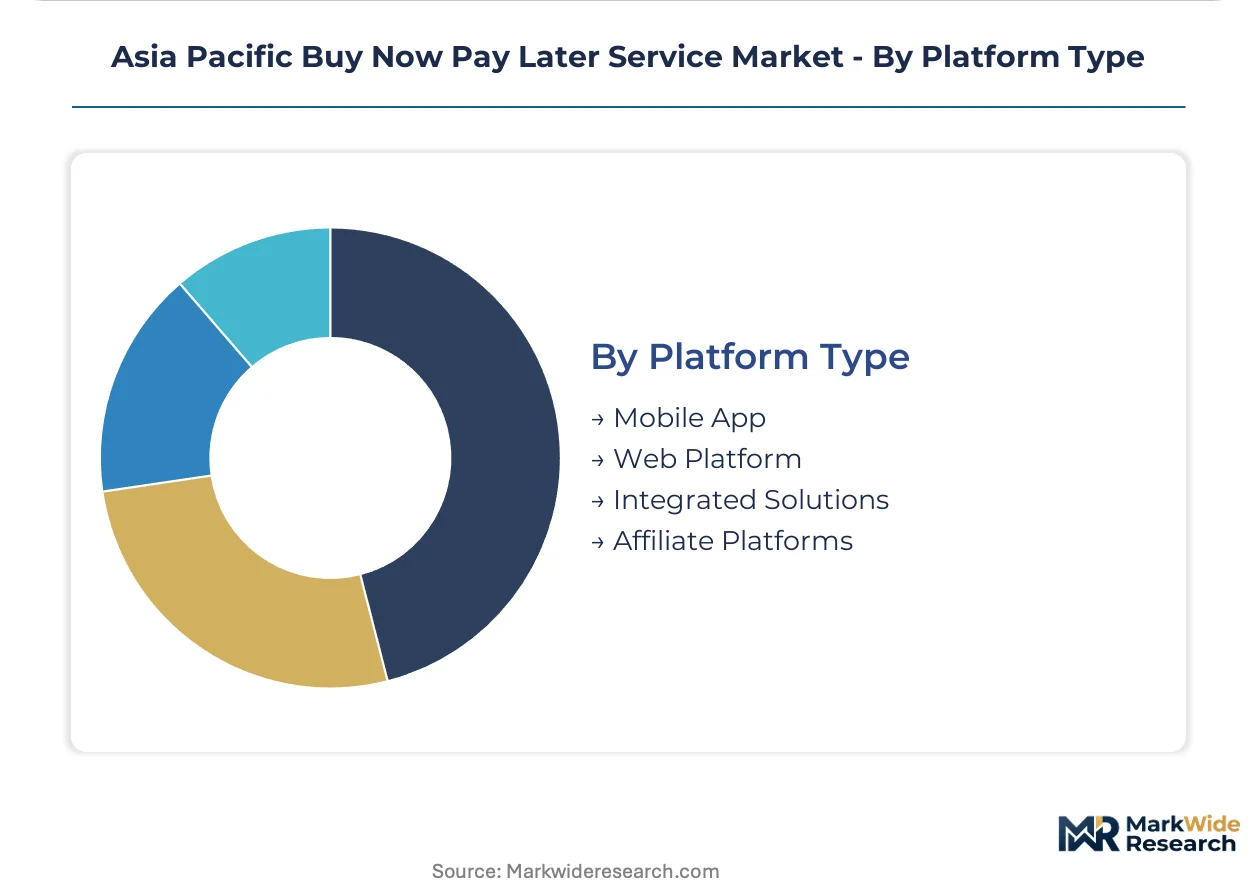
- Mobile App:Native iOS and Android applications dominate consumer-facing discovery and repayment management. Kredivo and Atome compete on app store visibility and push notification engagement across Indonesia and Singapore.
- Integrated Solutions:Direct merchant system connectivity through API and plugin architectures represents the steepest expansion trajectory as enterprise retail adoption deepens.
- Web Platform:Browser-based checkout integration serves merchants without dedicated mobile development resources.
- Affiliate Platforms:Referral-based customer acquisition through comparison sites and financial marketplaces.
Mobile App holds the volume advantage, with Integrated Solutions climbing fastest as enterprise procurement modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's smartphone penetration and unbanked consumer pools create larger addressable demand than Australia's mature credit card infrastructure, though regulatory divergence between these markets shapes divergent platform strategies.
Indonesia
Smartphone commerce penetration outpaces formal banking access across Java and Sumatra, concentrating demand for installment credit at digital checkout. The country's financial services authority maintains licensing requirements for peer-to-peer lending platforms that extend to buy now pay later operators. Jakarta's expanding mall network hosts merchant-funded promotional campaigns that drive conversion at physical retail touchpoints.
India
Unbanked consumer pools in rural corridors intersect with rising digital commerce adoption, creating thin-file borrower demand for alternative credit scoring. The Reserve Bank of India digital lending guidelines tighten permissible fee structures and disclosure requirements for point-of-sale credit providers. Maharashtra and Karnataka concentrate platform development activity as regulatory technology infrastructure investments cluster in Mumbai and Bangalore.
Australia
Mature credit card infrastructure supports card-linked installment plans, though consumer protection scrutiny elevates compliance costs. The National Consumer Credit Protection Act amendments mandate responsible lending assessments that extend underwriting timelines. Sydney and Melbourne anchor platform operations as hardship protocol investments concentrate in these metropolitan centers.
Singapore
Premium retail corridors generate merchant-funded zero-interest campaign demand as conversion rate optimization drives financing cost absorption. The Payment Services Act licensing clarity reduces compliance uncertainty for cross-border payment flows. The city-state's super-app ecosystem embeds installment lending within ride-hailing and food delivery workflows.
Vietnam
Low credit card penetration and rising digital commerce adoption create white space for installment lending at checkout in underpenetrated e-commerce corridors. The country's central bank maintains evolving guidelines for digital credit providers that shape permissible operating models. Ho Chi Minh City and Hanoi concentrate merchant integration activity as smartphone-first commerce infrastructure expands.
Asia Pacific Buy Now Pay Later Service Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with super-app ecosystems and standalone platforms converging on similar merchant-facing value propositions. The vendor base fragments across mobile-first entrants and legacy financial institutions extending into point-of-sale credit. Three strategic archetypes dominate: super-app embedded lenders leveraging unified account management, standalone installment specialists deploying proprietary alternative scoring, and traditional banks retrofitting existing credit infrastructure. Competitive moves concentrate on merchant acquisition partnerships and regulatory technology infrastructure investments that accelerate licensing timelines.
Within the super-app embedded tier, Grab PayLater and Shopee PayLater represent the ecosystem-anchored archetype, while Kredivo exemplifies the standalone specialist model with proprietary credit scoring capabilities. Atome occupies a position bridging physical retail promotional campaigns with digital checkout integration. These three companies illustrate the strategic divergence between merchant-funded acquisition spend models and borrower-interest sustainability structures across Southeast Asian markets.
| Leading Market Players |
|---|
| Afterpay |
| Grab PayLater |
| ZestMoney |
| Shopee PayLater |
| Kredivo |
| Atome |
| PayPay |
| Klarna |
| Zip Co |
| Others |
Value Chain & Pricing Dynamics
Merchant-funded promotional campaigns across Indonesia and Singapore are compressing consumer price sensitivity and forcing platforms to absorb financing costs through acquisition spend rather than borrower interest. This demand-side shift toward zero-interest installment structures reshapes how supply-side credit infrastructure must configure underwriting economics and merchant fee sustainability.
Pricing Analysis
Capacity additions in Vietnam and the Philippines are reshaping price floors for digital lending infrastructure as new entrants compete on merchant acquisition terms. The dominant pricing structure centers on merchant-fee absorption models where retailers fund promotional zero-interest campaigns, with price differentiation driven by credit scoring sophistication and regulatory compliance tier. Pricing pressure stems from India's RBI digital lending guidelines tightening permissible fee structures, elevating operational costs. Small merchants in underbanked corridors exhibit highest price sensitivity, while enterprise retailers in Singapore's premium corridor demonstrate lowest sensitivity due to conversion rate optimization priorities.
Supply Chain Analysis
Dual-sourcing requirements from enterprise merchants in Indonesia and Singapore mandate multi-platform qualification for checkout integration, fragmenting vendor concentration across Jakarta, Bangalore, and Singapore. The supply chain draws from India's regulatory technology development clusters, Indonesia's alternative data scoring infrastructure, and Australia's compliance protocol investments. Key dependencies include cloud computing infrastructure, real-time payment rails, and proprietary machine learning models for thin-file underwriting. Single-source vulnerability concentrates in super-app ecosystem dominance. Distribution runs through direct API integrations with merchant ERP systems and affiliate marketplace partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific Buy Now Pay Later Service Market functions as a stable compounder anchored by persistent underbanked demand intersecting with smartphone commerce penetration across Southeast Asian corridors.
For Market Incumbents: To counter regulatory technology cost escalation from India's RBI guidelines and Australia's NCCP amendments, incumbents should deepen proprietary credit scoring infrastructure investments in Indonesia and pre-position consent-management systems ahead of Thailand's open banking mandate. Vertical integration into merchant ERP connectivity accelerates enterprise adoption timelines and raises switching costs. For New Entrants and Emerging Players: The price-point gap between premium super-app ecosystems and economy-tier standalone platforms creates entry white space in Vietnam's underpenetrated e-commerce corridors and rural India's thin-file borrower segments. Healthcare elective procedure financing across Thailand and Malaysia represents the most penetrable application vertical. A partnership-first go-to-market angle with regional hospital networks and clinic chains bypasses super-app distribution dominance. For Investors and Strategic Acquirers: Asymmetric upside sits with standalone installment specialists possessing proprietary alternative scoring algorithms and pre-licensed regulatory technology infrastructure. Long-term viability across a 5-10 year window favors platforms with demonstrated merchant-funded campaign economics and multi-country ASEAN operational scale. The signal to watch as inflection indicator is Thailand's open banking mandate implementation timeline, which will shift underwriting advantage toward consent-management-ready platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Infrastructure Investment | RBI and NCCP compliance requirements elevate operational barriers for thinly capitalized entrants across India and Australia. |
| ERP Integration Partnership | Direct merchant system connectivity represents the fastest-growing configuration as enterprise retail adoption deepens regionally. |
| Alternative Credit Scoring Development | Machine learning models trained on telco and utility payment patterns expand thin-file borrower access in Indonesia and Vietnam. |
| Healthcare Vertical Expansion | Elective procedure financing gains traction across Thailand and Malaysia as consumers seek alternatives to traditional medical credit. |
| Cross-Border Payment Licensing | Singapore's Payment Services Act clarity reduces compliance uncertainty for regional platform expansion into adjacent ASEAN markets. |
Study Parameters
Multiple input streams — primary interviews with BNPL platform executives, regulatory affairs specialists, and merchant integration leads, alongside secondary validation from RBI circulars, ASIC disclosure requirements, and MAS licensing databases — were reconciled through bottom-up transaction volume modeling and top-down market sizing triangulation across the analysis window.
Data-stream reconciliation anchored the forecast framework across product type, payment method, end user demographic, and platform deployment architecture dimensions. CAGRs were derived from trend extrapolation of smartphone penetration curves, e-commerce adoption trajectories, and regulatory implementation timelines. Industry-specific forecast inputs included merchant-funded campaign economics and alternative credit scoring deployment rates.
Caveats apply where judicial reinterpretation of usury limits, open banking mandate delays, or super-app ecosystem consolidation could materially shift the outlook. Deviation in India's digital lending guideline enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
In Vehicles Payment Market
Payments
Global Payment Processor Market
Payments
Fingerprint Payment Market
Payments
Gift Card and Incentive Card Market
Payments
US Virtual Cards Market
Payments
Mobile Payment Transaction Market
Payments
Global Accounts Payable Automation Market
Payments
Digital Debit Market
Payments
Transit Cards Market
Payments
China POS Terminals Market
Payments
Belgium POS Terminals Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Germany Mobile Payments Market
Payments
Forex Cards Market
Payments
Fuel Cards Market
Payments
United Kingdom Payment Market