
 Europe Automotive Finance Market | 2026-2036
Europe Automotive Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Finance Market Insights
Germany's captive finance infrastructure is fragmenting as digital entrants and non-bank platforms erode traditional dominance. Volkswagen Financial Services leverages its manufacturer-backed balance sheet to sustain below-market lease rates across the passenger segment. Santander Consumer Finance competes through broker network density in Southern Europe, while BNP Paribas Personal Finance anchors prime retail lending through established banking channels in France and the Benelux.
Europe automotive finance encompasses credit extension, lease structuring, and asset-backed funding instruments collateralized by vehicle titles across multiple jurisdictions. Contract terms typically span 24 to 60 months with residual value guarantees calibrated to manufacturer depreciation curves and EU emissions performance standards. Lease structures dominate the passenger segment as fleet operators and individual consumers prioritize usage rights over ownership, while direct financing retains margin concentration in commercial vehicle portfolios where asset longevity supports term extension. Electric vehicle financing exhibits the fastest trajectory as battery residual value methodologies mature and green loan certifications unlock preferential capital costs.
EU Green Deal emissions benchmarks, EBA sustainable finance disclosure requirements, and national central bank consumer credit directives collectively reshape product design and capital allocation across the region. EBA stress testing now incorporates transition risk scenarios that elevate capital charges for fossil fuel vehicle portfolios relative to electrified alternatives. Stakeholders must monitor evolving residual value models for battery electric platforms and the competitive entry of technology platforms into subscription-based mobility services.
Market Dynamics
EU Green Deal emissions benchmarks are forcing automotive lenders to recalibrate residual value models and capital allocation frameworks across their vehicle portfolios. This regulatory pressure is accelerating the displacement of fossil fuel financing structures with electrified alternatives.
Growth Catalysts
- EU Green Deal:Emissions performance standards mandate fleet electrification timelines, expanding demand for battery electric vehicle lease products with preferential capital charges.
- Corporate fleet procurement:Large-scale buyers across Germany, France, and the Netherlands are consolidating vehicle acquisition through captive finance arms to secure volume-based residual guarantees.
- Battery residual value methodologies:Standardized degradation curves and second-life valuation frameworks are unlocking institutional investor participation in electric vehicle asset-backed securities.
Market Restraints
- Lithium supply concentration:Battery raw material dependency on concentrated extraction geographies introduces collateral value volatility into electric vehicle financing structures.
- EBA transition risk capital charges:Stress testing frameworks elevate regulatory capital requirements for internal combustion engine portfolios relative to electrified alternatives.
- Depreciation curve uncertainty:Limited historical data for battery electric platforms constrains residual value forecasting precision across 48-60 month lease terms.
Strategic Opportunities
- Subscription mobility services:Technology platforms are entering European urban markets with usage-based models that bundle insurance, maintenance, and charging infrastructure.
- Benelux green loan certifications:National central bank frameworks in Belgium and the Netherlands provide preferential refinancing terms for qualifying sustainable vehicle portfolios.
- Vehicle-to-grid integration:Bidirectional charging capabilities create new revenue streams that enhance lease affordability calculations for fleet operators.
Industry Challenges
- Battery health assessment standardization:Lenders lack uniform diagnostic protocols to verify state-of-health claims at contract inception and termination.
- Legacy system integration:Established finance platforms require substantial reconfiguration to accommodate real-time telematics data and dynamic pricing models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Finance Market |
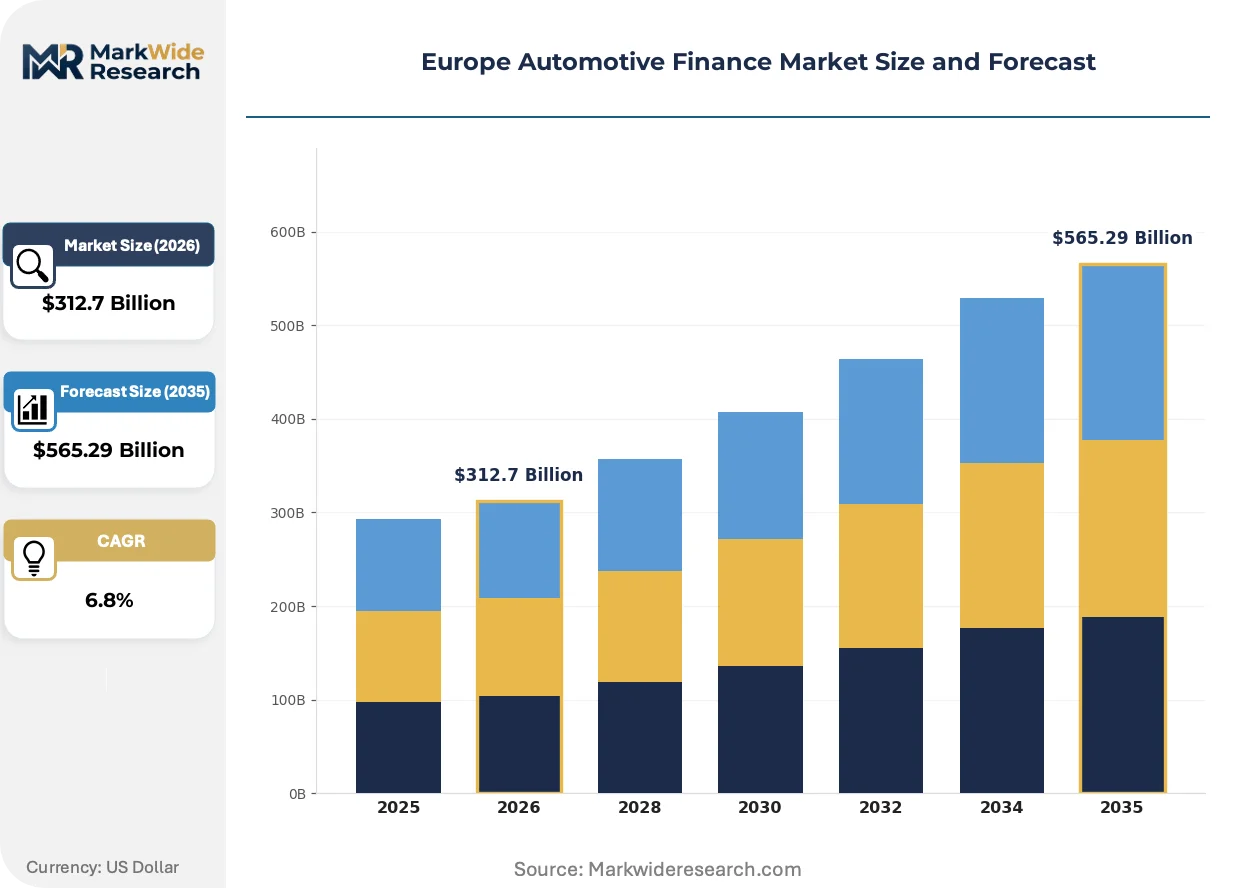
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Lease, Loan, Hire Purchase, Subscription Customer Type: Individual Consumers, Small Enterprises, Large Corporations, Fleet Operators Service Model: Direct Financing, Broker Services, Dealer Financing, Online Platforms Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles |
| Companies Covered | CA Auto Bank, Ayvens, Volkswagen Financial Services, Credit Agricole Auto Bank, Mercedes-Benz Financial Services, Santander Consumer Finance, Alphera Financial Services, BMW Financial Services, BNP Paribas Personal Finance, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Finance Market Trends and Innovations
Digital origination platforms are compressing approval timelines and eroding the branch-based distribution advantage historically held by incumbent banking networks. This technological shift is redistributing market access toward agile non-bank entrants.
Artificial intelligence-driven credit scoring is collapsing traditional bureau-dependent underwriting models by incorporating alternative data streams including telematics behavior and employment platform verification. Subprime and near-prime segments across Southern Europe are adopting these tools fastest. The structural consequence is collapsing geographic coverage constraints that previously limited lender participation in cross-border portfolios.
EBA sustainable finance disclosure requirements mandate granular reporting on financed vehicle emissions profiles and transition risk exposure. Lenders must now embed climate scenario analysis into product pricing and residual value guarantees. France and Germany are experiencing the most pronounced portfolio rebalancing as institutions divest fossil fuel concentrations ahead of compliance deadlines.
Fleet procurement patterns are consolidating around total cost of ownership frameworks that internalize carbon pricing and fuel volatility risk. Corporate buyers are displacing open-end lease structures with closed-end products that transfer residual risk to manufacturer captives. This concentration is most visible among German automotive groups managing multi-country vehicle programs.
Europe Automotive Finance Market Segmentation
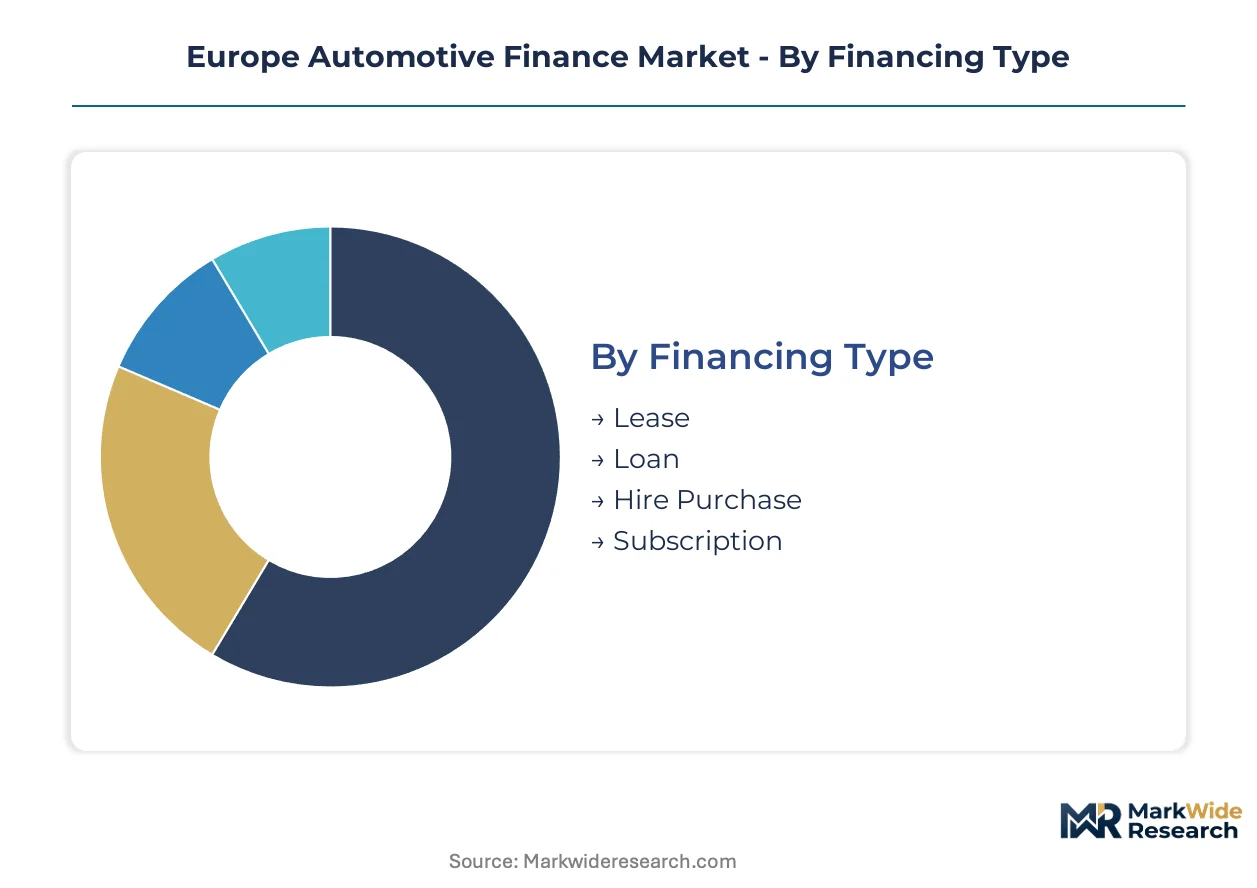
European automotive finance structures diverge sharply across financing instruments, customer risk profiles, and distribution architectures. Each segmentation dimension carries distinct capital intensity, regulatory treatment, and residual value methodology requirements that shape lender specialization.
Financing Type:
Use-case spectrum spans pure usage rights through full ownership transfer, with capital allocation efficiency varying by depreciation certainty and collateral liquidity.
- Lease:Closed-end structures dominate German and French passenger segments, transferring residual risk to manufacturer captives while corporate fleet buyers prioritize balance sheet efficiency. Volkswagen Financial Services and BNP Paribas Personal Finance compete aggressively on monthly rate positioning.
- Loan:Direct lending retains margin concentration in commercial vehicle portfolios where asset longevity supports 60-month terms and secondary market liquidity underpins collateral coverage. German and Benelux banking channels anchor prime retail distribution.
- Hire Purchase:Balloon payment structures align with Southern European consumer preferences for eventual ownership, with Santander Consumer Finance leveraging Iberian broker density.
- Subscription:Bundled mobility services are penetrating Amsterdam, Berlin, and Paris urban corridors, combining insurance, maintenance, and charging infrastructure under single monthly fees.
The dominant share belongs to Lease, while Subscription is closing the gap fastest.
Customer Type:
Cost tier differentiation separates mass retail from institutional procurement, with capital charges and residual guarantee structures calibrated to portfolio scale.
- Individual Consumers:Credit bureau-dependent underwriting dominates, though AI-driven scoring using telematics behavior and employment platform verification is collapsing geographic coverage constraints in Southern Europe.
- Small Enterprises:Limited financial disclosure requirements favor asset-based lending with personal guarantees, constraining term extension beyond 36 months.
- Large Corporations:Multi-country vehicle programs consolidate through German automotive group captives, leveraging volume-based residual guarantees and total cost of ownership frameworks that internalize carbon pricing.
- Fleet Operators:Open-end lease displacement accelerates as closed-end products transfer residual risk, with EU Green Deal emissions benchmarks forcing electrification timelines across Netherlands and France procurement.
Large Corporations command the deepest capital reserves, though Fleet Operators are expanding contract volume most rapidly.
Service Model:
Distribution architecture determines origination cost and regulatory perimeter, with digital platforms eroding branch-based historical advantages.
- Direct Financing:Captive finance arms leverage manufacturer balance sheets to sustain below-market lease rates, particularly across German passenger segments where Volkswagen Financial Services anchors competitive positioning.
- Broker Services:Network density concentrates in Southern Europe, with Santander Consumer Finance competing through intermediary relationships rather than proprietary branch infrastructure.
- Dealer Financing:Point-of-sale origination remains sticky in commercial vehicle segments where relationship banking and asset inspection requirements favor physical presence.
- Online Platforms:Digital entrants compress approval timelines from days to hours, redistributing market access toward agile non-bank competitors in UK and Scandinavian markets.
Dealer Financing retains the largest contract stock, though Online Platforms are gaining origination share fastest.
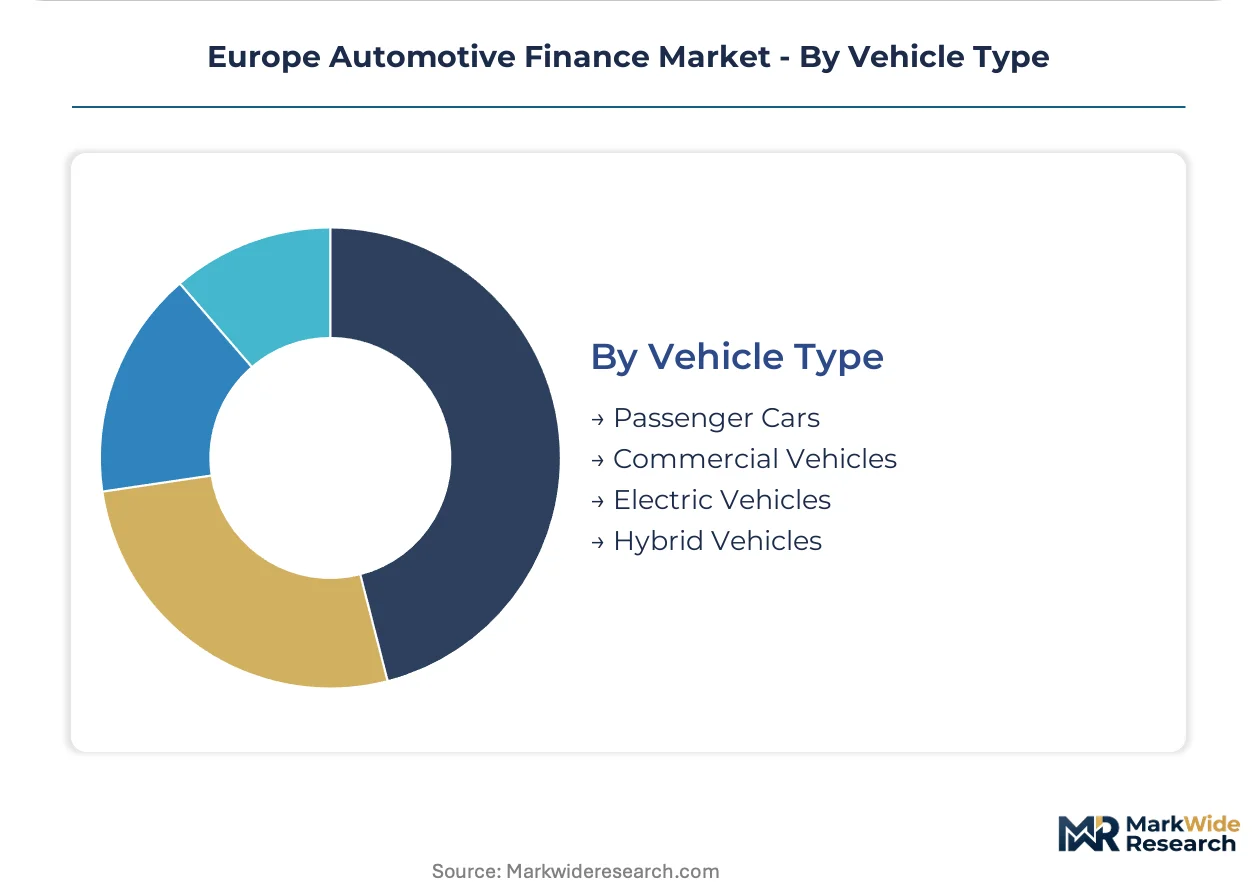
Vehicle Type:
Technology maturity and residual value predictability create divergent risk-return profiles across propulsion platforms.
- Passenger Cars:Lease structures dominate as individual consumers prioritize usage rights, with EBA transition risk capital charges elevating regulatory requirements for fossil fuel concentrations relative to electrified alternatives.
- Commercial Vehicles:Asset longevity supports term extension to 60 months, with direct financing retaining margin concentration where secondary market liquidity underwrites collateral coverage.
- Electric Vehicles:Battery residual value methodologies are maturing through standardized degradation curves and second-life valuation frameworks, unlocking institutional investor participation in asset-backed securities across German and French markets.
- Hybrid Vehicles:Transitional technology positioning attracts risk-averse corporate fleets awaiting full electrification infrastructure deployment, particularly in Benelux urban corridors.
Passenger Cars maintain the broadest contract base, though Electric Vehicles are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor underwrites Germany's centrality to European automotive finance distribution, connecting manufacturing clusters in Stuttgart and Munich to Rotterdam's port infrastructure and the broader continental leasing network.
Germany
Captive finance arms dominate contract origination as corporate fleet buyers consolidate multi-country vehicle programs through manufacturer balance sheets. The KBA enforces type-approval standards that cascade into residual value calibration for electrified fleets. Stuttgart anchors Volkswagen Financial Services' competitive positioning, while Munich hosts BMW Financial Services' prime retail operations.
France
Corporate procurement through closed-end lease structures accelerates as total cost of ownership frameworks internalize carbon pricing. The Autorité de Contrôle Prudentiel et de Résolution supervises sustainable finance disclosure alignment with EU Green Deal benchmarks. Paris concentrates BNP Paribas Personal Finance's banking channel distribution across the Île-de-France corridor.
United Kingdom
Digital origination platforms erode branch-based advantages fastest here, with non-bank entrants capturing broker-mediated subprime segments. The Financial Conduct Authority mandates consumer duty standards that reshape point-of-sale disclosure requirements. London's fintech cluster incubates subscription mobility services penetrating urban corridors.
Netherlands
Fleet operator electrification timelines concentrate demand for battery electric vehicle lease products with preferential capital charges. De Nederlandsche Bank's green loan certification framework unlocks refinancing advantages for qualifying sustainable portfolios. Amsterdam anchors technology platform entry into bundled mobility services combining charging infrastructure and insurance.
Spain
Southern Europe's broker network density sustains intermediary-dependent origination models across near-prime consumer segments. The Banco de España coordinates EBA stress testing implementation that elevates capital charges for fossil fuel vehicle concentrations. Madrid hosts Santander Consumer Finance's Iberian distribution infrastructure.
Europe Automotive Finance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The European automotive finance market exhibits tiered concentration around manufacturer captives, universal banking networks, and agile digital entrants. Three archetypes dominate: balance-sheet-backed captives sustaining below-market lease rates, broker-network-dependent intermediaries penetrating subprime segments, and technology platforms compressing origination timelines through algorithmic underwriting. Competitive dynamics center on portfolio electrification speed and residual value guarantee restructuring.
Within the captive finance tier, Volkswagen Financial Services and BMW Financial Services exemplify manufacturer-backed structures leveraging depreciation curve control to anchor passenger segment positioning. BNP Paribas Personal Finance occupies a position representing universal banking channel density across French and Benelux retail markets. Santander Consumer Finance sits within the broker-specialist archetype, its network concentration exemplifying Southern European intermediary-dependent origination models.
| Leading Market Players |
|---|
| CA Auto Bank |
| Ayvens |
| Volkswagen Financial Services |
| Credit Agricole Auto Bank |
| Mercedes-Benz Financial Services |
| Santander Consumer Finance |
| Alphera Financial Services |
| BMW Financial Services |
| BNP Paribas Personal Finance |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Southern European broker networks is compressing origination margins and forcing intermediaries toward volume-based fee structures that erode unit economics across near-prime consumer segments. German captive finance arms exploit manufacturer balance sheet capacity to sustain below-market lease rates, creating a bifurcated pricing landscape where balance-sheet scale determines competitive survival.
Pricing Analysis
EU Green Deal emissions benchmarks dictate the pricing tier structure across European automotive finance, separating electrified portfolios with preferential capital charges from fossil fuel concentrations carrying elevated regulatory risk weights. Three-tier pricing structure across premium captive-backed, standard banking-channel, and economy broker-mediated segments reflects origination cost differentials and residual guarantee depth. Cost compression in the broker-mediated tier is intensifying because digital platforms collapse geographic coverage constraints and eliminate branch infrastructure overhead. Fleet operators exhibit the highest price sensitivity due to total cost of ownership frameworks that internalize carbon pricing, while individual prime retail borrowers show lowest sensitivity where manufacturer brand loyalty anchors rate acceptance.
Supply Chain Analysis
EU critical raw material regulations and export control frameworks on battery technology are reshaping collateral value chains across electric vehicle financing structures. Lithium extraction concentrates in Australia, Chile, and Argentina, while cathode processing and cell manufacturing anchor in China, South Korea, and Poland. Battery raw material dependencies on concentrated geographies introduce collateral value volatility that feeds directly into residual value guarantee calibration. Distribution runs through manufacturer captive arms in Germany, universal banking networks in France and the Benelux, and broker-mediated channels across Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent automotive lenders face substitution pressure from technology platforms bundling mobility services into usage-based models that displace traditional ownership finance. Platform entrants threaten to capture urban consumer relationships and erode the point-of-sale origination advantage historically held by manufacturer captives.
For Market Incumbents: Entrench residual value guarantee capabilities through backward integration into battery health assessment technology and second-life valuation frameworks. Deepen balance sheet deployment into closed-end lease structures that transfer electrification risk away from corporate fleet buyers. Platform substitution in urban mobility segments demands captive finance arms accelerate subscription service pilots in Amsterdam, Berlin, and Paris.
For New Entrants and Emerging Players: Establish a beachhead in Southern European near-prime segments where AI-driven credit scoring collapses traditional bureau-dependent underwriting barriers. Target Spain and Portugal broker networks where intermediary relationships remain sticky and digital origination platforms have lowest penetration. Lead with telematics-integrated pricing models that reward low-mileage, low-carbon-intensity usage patterns with dynamic rate adjustments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric vehicle lease portfolios as battery residual value uncertainty demands thicker equity cushions and longer-dated funding structures. Long-term viability favors acquirers of broker network infrastructure with embedded data assets capable of supporting algorithmic underwriting transitions. Watch EBA stress test calibration announcements as the signal indicating when fossil fuel portfolio divestiture accelerates and distressed asset opportunities emerge.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in lithium and cathode material flows from Australian and Chilean extraction geographies. |
| Residual Value Guarantee Restructuring | Recalibrates electrified fleet pricing to absorb EBA transition risk capital charge differentials. |
| Subscription Mobility Platform Launch | Captures urban usage-based demand in Amsterdam and Berlin corridors before technology entrants consolidate. |
| AI-Driven Credit Scoring Deployment | Collapses geographic coverage constraints across Southern Europe through telematics behavior integration. |
| Green Loan Certification Program | Unlocks De Nederlandsche Bank preferential refinancing terms for qualifying sustainable vehicle portfolios. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, vehicle registration databases, and central bank sustainable finance disclosures across the European Economic Area. Primary interviews engaged captive finance executives, automotive OEM platform engineers, fleet procurement directors, broker network operators, and EBA supervisory staff. Secondary sources included KBA type-approval records, De Nederlandsche Bank green loan certification frameworks, and EBA stress testing methodology documents. Bottom-up contract origination modeling triangulates against top-down macroeconomic scenario analysis.
Forecast inputs span vehicle class, propulsion architecture, customer risk tier, and distribution channel across the analysis window. Segmentation dimensions incorporate financing instrument type, OEM captive affiliation, and national regulatory cluster. CAGRs derive from regression analysis against historical fleet procurement patterns and electrification timeline assumptions. Battery residual value degradation curves and second-life valuation frameworks inform electric vehicle portfolio projections.
Stress conditions across lithium price volatility, EBA capital charge calibration, and battery technology obsolescence cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on EU Green Deal compliance trajectory and corporate fleet electrification adoption curves. Material shifts in battery chemistry breakthrough timelines or critical mineral export restriction regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Car Finance Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market