
 Outdoor Payment Terminal Market | 2026-2036
Outdoor Payment Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Payment Terminal Market Intelligence
Subscription-based terminal management software is repositioning vendor revenue models from hardware sales to recurring service contracts. Gilbarco Inc. leverages its installed base of fuel dispensers to anchor software-as-a-service offerings for payment processing. Verifone, Inc. competes through cloud-connected terminal architectures that enable remote firmware updates and security patching. Dover Fueling Solutions differentiates by integrating loyalty program management directly into its outdoor payment hardware stack.
An outdoor payment terminal is a weather-hardened electronic device designed to process card and mobile transactions in uncontrolled environments, typically featuring IP65+ ingress protection, vandal-resistant enclosures, and temperature operating ranges from minus twenty to plus fifty degrees Celsius. These terminals serve petroleum retailers, parking operators, and transit agencies that require unattended revenue collection at distributed physical points. Contactless terminals lead product type demand as NFC tap-to-pay volumes displace magnetic stripe dependency across forecourt deployments. EMV technology dominates transaction security architecture while QR code acceptance accelerates fastest among budget-focused food service kiosks and temporary event installations. Fixed mount installations occupy the largest revenue pool though portable configurations capture expanding share in pop-up retail and seasonal parking applications.
The Federal Communications Commission governs wireless communication modules embedded in outdoor terminals across the United States, while PCI Security Standards Council certification dictates encryption and tokenization protocols for all card-present transactions. The European Union's Payment Services Directive and GDPR framework constrain data storage architectures for terminals deployed across member states, compelling manufacturers to engineer region-specific firmware configurations. Stakeholders must monitor evolving contactless transaction limits and real-time fraud detection mandates that will determine next-generation hardware specifications and compliance investment thresholds.
Market Dynamics
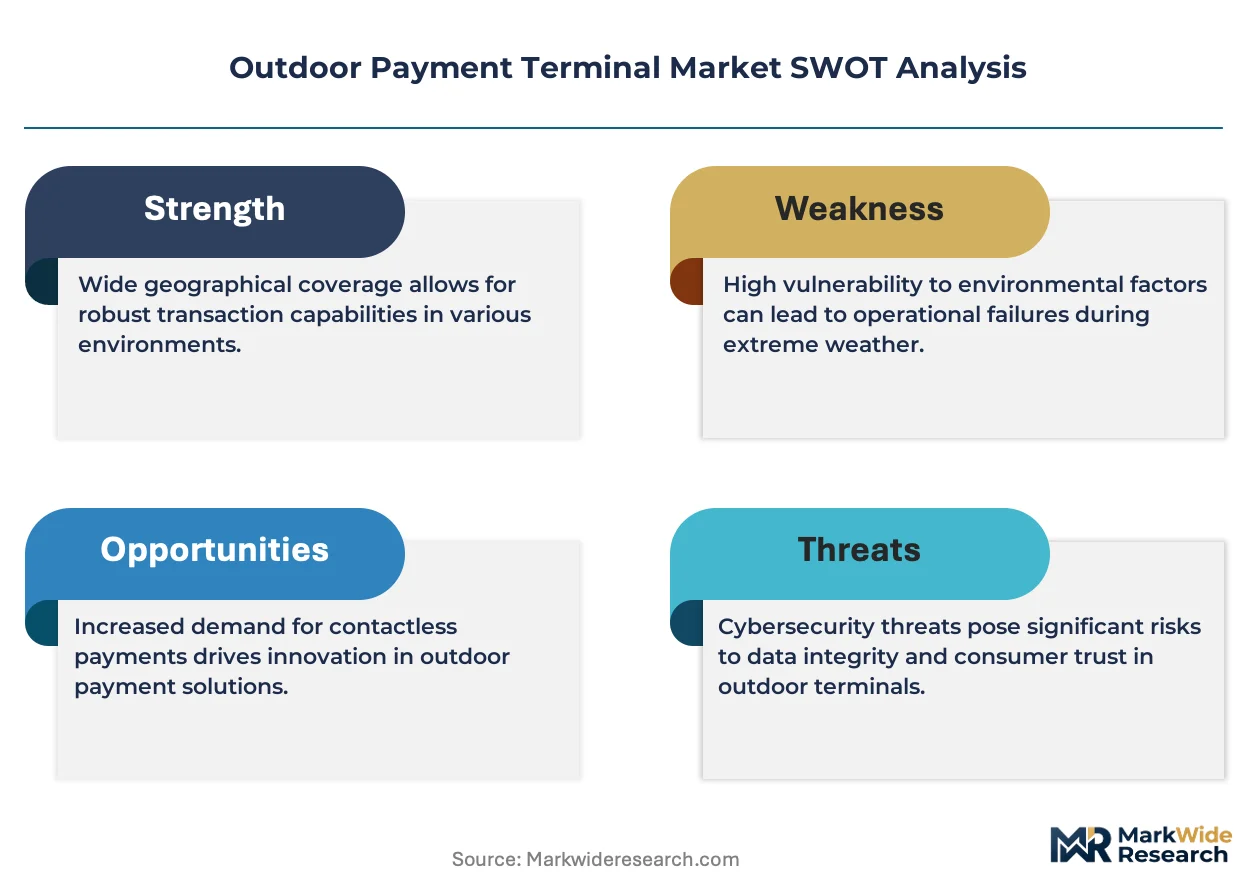
PCI DSS compliance mandates and EMV certification requirements are compressing hardware procurement cycles while forcing petroleum retailers into accelerated terminal refresh programs across North American forecourts.
Growth Catalysts
- NFC Tap-to-Pay Volumes:Contactless transaction thresholds at fuel dispensers are rising as consumers abandon magnetic stripe dependency, pulling terminal upgrades at major petroleum chains.
- GDPR Data Architecture:European Union data residency rules compel manufacturers to engineer region-specific firmware, creating replacement demand for non-compliant legacy deployments.
- Self-Service Forecourt Expansion:Fuel retailers are unbundling cashier labor from revenue collection, installing unattended terminals to extend operating hours without proportional staff increases.
Market Restraints
- Semiconductor Supply Concentration:Secure element chip fabrication concentrates in East Asian foundries, exposing terminal manufacturers to allocation volatility and extended lead times.
- EMV Certification Backlogs:Laboratory testing queues at accredited facilities stretch hardware launch timelines, delaying revenue recognition for vendors with product-ready designs.
- Mobile Wallet Substitution:In-app fuel payment platforms at major petroleum brands reduce transaction dependency on physical terminal infrastructure at equipped locations.
Strategic Opportunities
- Pop-Up Retail Channel:Portable terminal configurations capture seasonal parking operations and temporary event installations where fixed-mount hardware proves economically unviable.
- India Fuel Retail Modernization:State-owned petroleum marketing companies are piloting unattended payment infrastructure at highway corridors and urban forecourts.
- Cloud-Connected Architecture:Remote firmware management capabilities are converging with subscription revenue models, enabling vendors to monetize terminal lifecycles beyond initial hardware sale.
Industry Challenges
- Embedded Systems Security Talent:Firmware engineering expertise for payment-grade cryptographic implementations remains scarce, elongating development timelines and inflating compensation costs.
- Legacy Pump Integration:Retrofitting IP-enabled terminals into decades-old dispenser communication protocols demands custom middleware development for each petroleum chain's installed base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Payment Terminal Market |
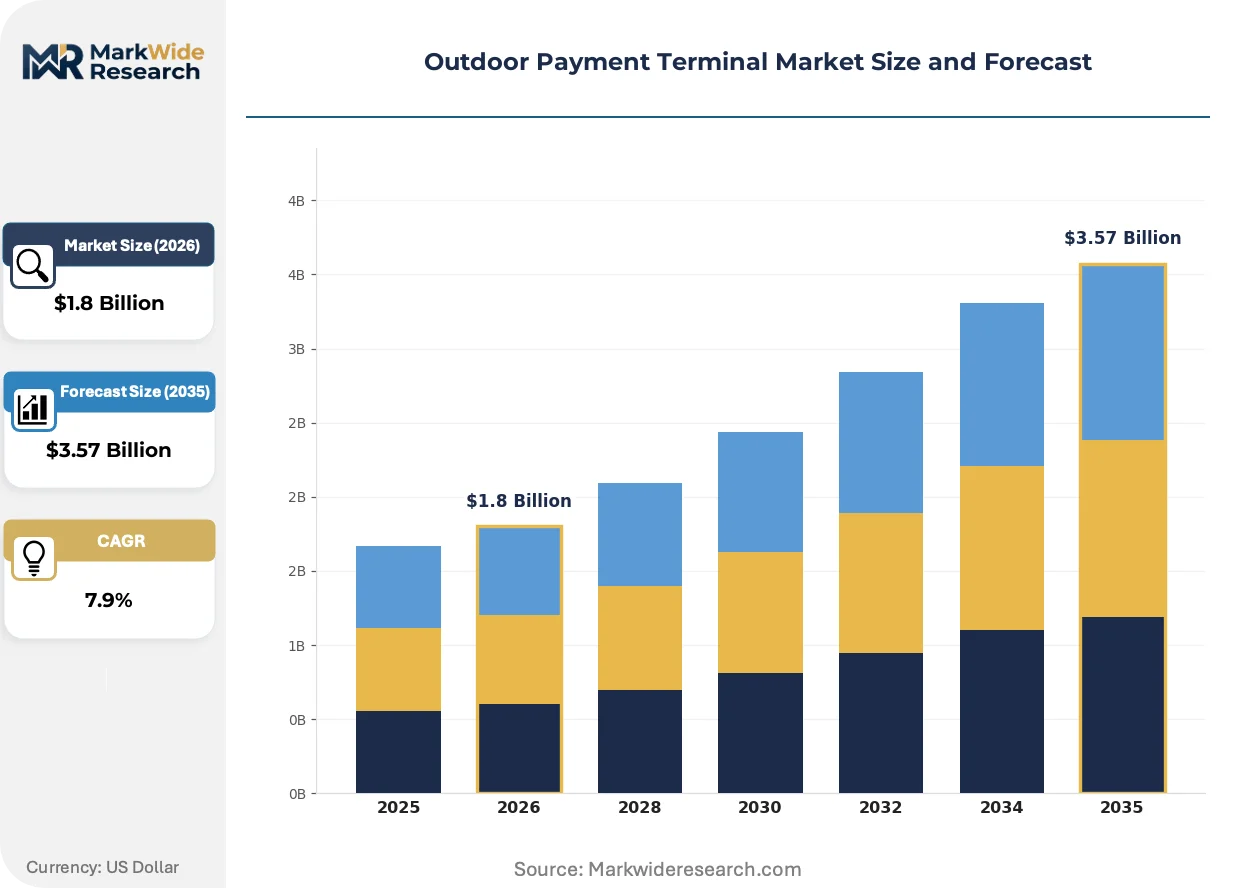
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.57 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Terminals, Mobile Payment Devices, Kiosks, Card Readers Installation: Fixed Mount, Portable, Embedded, Temporary Technology: NFC, EMV, QR Code, Bluetooth End User: Retailers, Food Service, Transportation, Events |
| Companies Covered | NCR Corporation, Gilbarco Inc., Invenco Group Ltd., Verifone, Inc., Dover Fueling Solutions, Scheidt & Bachmann GmbH, Apple Inc., Temenos AG, Capgemini SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Payment Terminal Market Strategic Shifts & Innovations
Terminal architecture is pivoting from isolated payment devices toward software-defined platforms that monetize transaction data and integrate loyalty ecosystems beyond pure payment processing.
Biometric authentication modules are converging with outdoor payment hardware as fuel retailers pilot palm-vein and facial recognition systems for card-not-present transactions. Major petroleum chains in the United States are testing these systems at high-volume urban forecourts where transaction speed directly correlates to throughput capacity. This convergence is compressing the competitive window for vendors lacking biometric-ready hardware designs.
The FCC's evolving spectrum allocation rules for cellular IoT modules are forcing terminal manufacturers to redesign radio subsystems for 5G resilience and fallback compatibility. Industrial consequence includes mandatory hardware revisions for terminals deployed in remote forecourts dependent on cellular backhaul. Petroleum retailers in rural United States markets face accelerated obsolescence risk for 4G-only terminals as carrier sunset timelines advance.
Petroleum procurement officers are unbundling terminal hardware from payment processing contracts, creating direct purchasing relationships with hardware vendors separate from acquiring bank arrangements. This channel disintermediation is most visible among mid-sized regional fuel chains seeking cost transparency and multi-processor flexibility. Vendors responding with hardware-only SKUs and open-payment-platform compatibility are capturing share from integrated-stack competitors.
Outdoor Payment Terminal Market Segmentation
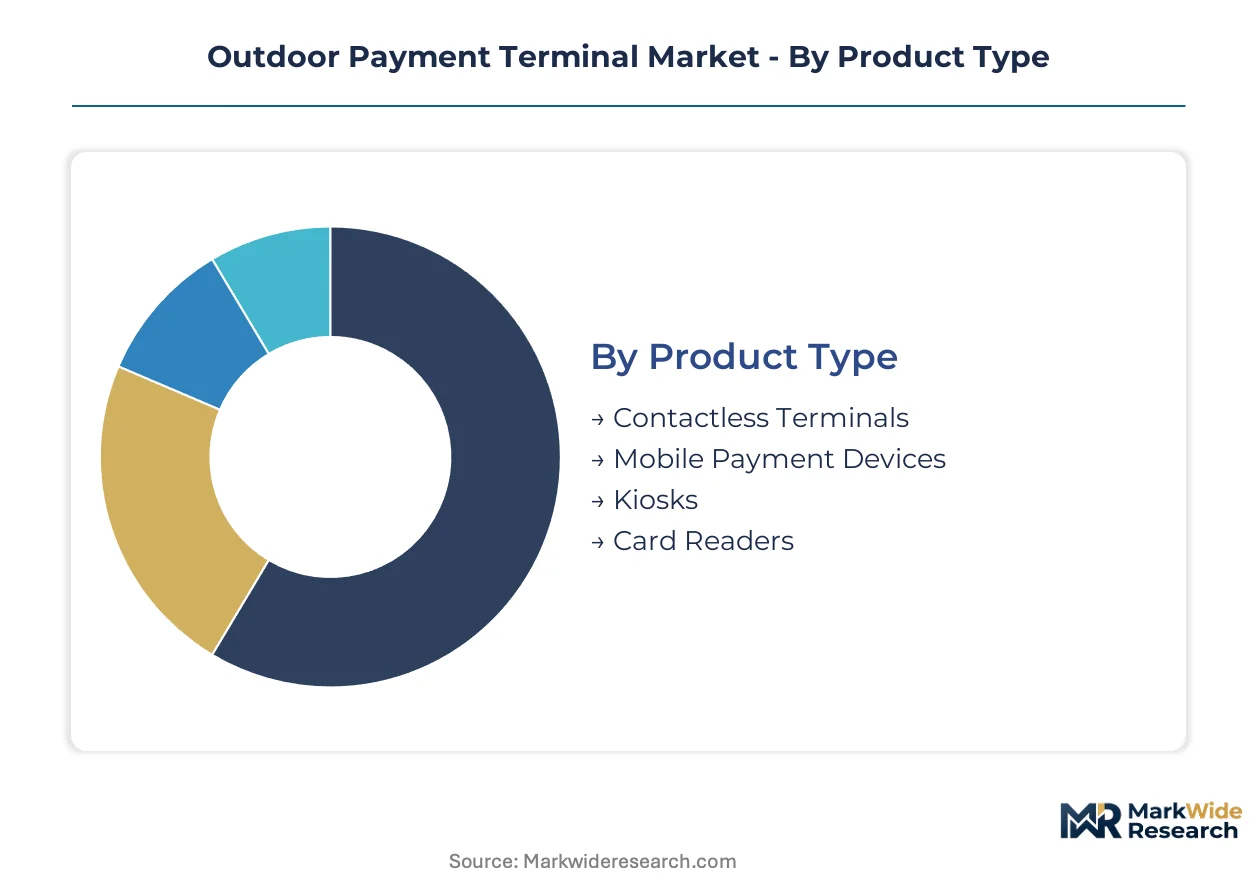
Outdoor payment terminal segmentation reveals distinct capital requirements across hardware configurations, with weather-hardened enclosures and secure element integration driving procurement decisions. Petroleum retailers prioritize fixed-mount infrastructure while temporary event operators favor portable deployments with lower upfront commitment.
Product Type:
Capital intensity varies sharply across form factors, with integrated kiosk systems demanding the highest upfront investment in vandal-resistant enclosures and multi-module architecture.
- Contactless Terminals:NFC-enabled devices with IP65+ ingress protection and temperature-rated components dominate petroleum forecourt retrofits. United States fuel chains are displacing magnetic stripe hardware as tap-to-pay thresholds rise at dispensers.
- Kiosks:Self-contained units integrate payment processing with loyalty management and receipt printing in weather-hardened cabinets. Food service operators at highway corridors deploy these for extended-hour revenue collection without proportional labor expansion.
- Mobile Payment Devices:Handheld terminals with cellular backhaul serve pop-up retail and seasonal parking operations.
- Card Readers:Compact magnetic stripe and chip-reading modules attach to existing dispenser communication protocols.
Contactless terminals absorb the bulk of installed capacity; kiosks are expanding most quickly.
Installation:
Deployment permanence shapes total cost of ownership calculations, with fixed infrastructure amortizing over decade-long lifecycles versus rental economics for temporary configurations.
- Fixed Mount:Permanently affixed terminals with hardwired power and Ethernet connectivity anchor petroleum forecourt architecture. Major chains in the United States are retrofitting legacy pump terminals with IP-enabled replacements to satisfy EMV certification mandates.
- Portable:Battery-powered cellular terminals with rapid-deployment mounting serve municipal parking operations and festival infrastructure. Seasonal demand peaks at sporting venues and agricultural fairs where permanent installation proves economically unviable.
- Embedded:Factory-integrated payment modules ship pre-installed within fuel dispenser manufacturing lines.
- Temporary:Short-term rental configurations support construction site cafeterias and emergency response payment collection.
Fixed mount installations command the largest revenue pool; portable configurations gain share fastest in non-petroleum applications.
Technology:
Security architecture differentiation determines hardware procurement cycles, with certification requirements compressing refresh timelines for legacy deployments.
- EMV:Chip-card authentication with cryptographic secure elements dominates transaction security architecture across North American forecourts. PCI DSS compliance mandates are forcing petroleum retailers into accelerated terminal replacement programs.
- NFC:Near-field communication modules enable tap-to-pay at fuel dispensers and parking meters. Consumer abandonment of magnetic stripe dependency is pulling terminal upgrades at major petroleum chains.
- QR Code:Optical scanning for mobile wallet integration accelerates in budget-focused food service kiosks.
- Bluetooth:Short-range wireless supports in-app payment handshakes at equipped locations.
EMV technology carries the heaviest compliance investment burden; QR code acceptance climbs the fastest among temporary event installations.
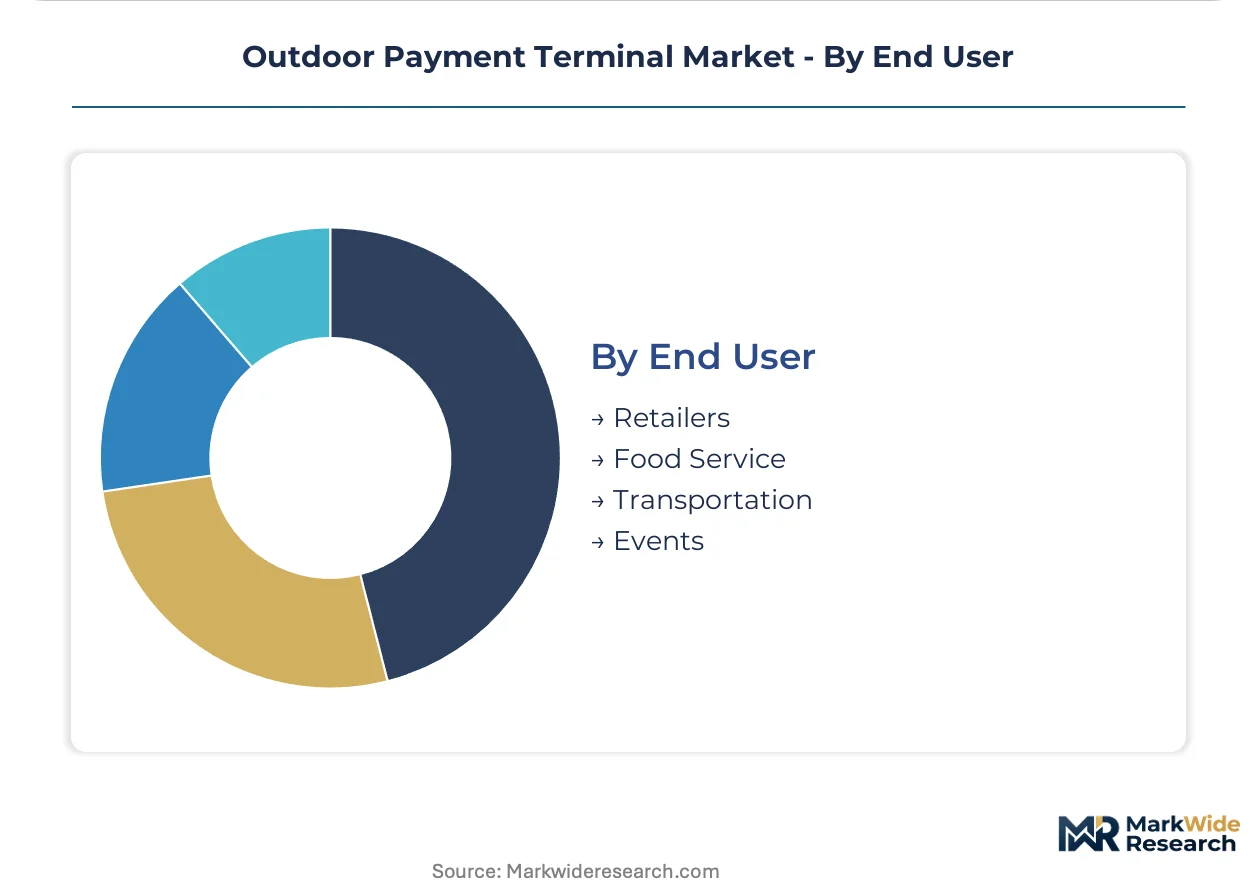
End User:
Customer transaction patterns dictate hardware specifications, with high-throughput petroleum operations demanding ruggedized designs versus lighter-duty event deployments.
- Retailers:Petroleum marketing companies and convenience store operators deploy unattended terminals to unbundle cashier labor from revenue collection. Self-service forecourt expansion extends operating hours without proportional staff increases.
- Transportation:Transit agencies and parking operators require distributed payment collection at physical points with minimal maintenance access. Municipal procurement favors fixed-mount cellular terminals for remote lot management.
- Food Service:Quick-service restaurants and highway corridor operators pilot kiosk integration for order-ahead payment.
- Events:Temporary installation operators prioritize rapid deployment and takedown with rental economics.
Retailers deploy the largest terminal volume; transportation authorities are scaling fastest as municipal parking modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal manufacturing concentrates in German industrial clusters and Chinese electronics corridors, while consumption pulls heaviest from United States petroleum retail networks and Indian highway modernization programs. This geographic split creates supply chain exposure for vendors dependent on East Asian secure element fabrication.
United States
Petroleum chains including Circle K and Shell are retrofitting legacy pump terminals across 150,000+ forecourt locations to satisfy EMV certification deadlines. The FCC governs wireless communication modules embedded in outdoor terminals, mandating 5G resilience and fallback compatibility for cellular backhaul. Dallas-Fort Worth anchors a cluster of payment technology integrators serving regional fuel marketing companies.
Germany
Industrial automation specialists supply precision-engineered terminal enclosures to European petroleum retailers modernizing unattended infrastructure. The EU Payment Services Directive and GDPR framework constrain data storage architectures, compelling manufacturers to engineer region-specific firmware configurations. Munich hosts engineering centers for fuel dispenser payment integration serving BP and Aral networks.
China
Domestic secure element chip fabrication supports terminal manufacturing for state-owned petroleum marketing companies piloting unattended highway corridor infrastructure. MIIT standards govern cellular IoT module certification for payment-grade devices. Shenzhen electronics corridors supply weather-hardened enclosure components to global terminal assemblers.
India
State-owned petroleum marketing companies including Indian Oil and Bharat Petroleum are piloting outdoor payment terminals at 5,000+ highway corridor and urban forecourt locations. RBI payment security guidelines mandate tokenization protocols for card-present transactions at fuel dispensers. Gujarat industrial zones manufacture vandal-resistant terminal housings for domestic deployment and regional export.
United Kingdom
Transit agencies and municipal parking operators deploy fixed-mount cellular terminals for distributed revenue collection with minimal maintenance access. The Financial Conduct Authority enforces contactless transaction limits and real-time fraud detection mandates determining hardware specifications. London hosts pilot programs for biometric authentication integration at high-volume urban forecourts.
Outdoor Payment Terminal Market Key Industry Players
Top-tier vendors anchor integrated hardware-software stacks, while mid-tier specialists compete on regional customization and petroleum chain relationships. The vendor base stratifies across three tiers: multinational payment technology platforms with cloud-connected architectures, industrial equipment manufacturers leveraging fuel dispenser installed bases, and regional integrators focused on compliance-heavy European markets. Two dominant competitive moves are reshaping positioning: subscription-based terminal management software repositioning revenue from hardware sales to recurring service contracts, and petroleum procurement officers unbundling terminal hardware from payment processing contracts to establish direct purchasing relationships.
Among payment technology platforms, Verifone, Inc. and NCR Corporation exemplify the cloud-connected architecture archetype, anchoring positions through remote firmware management capabilities. Gilbarco Inc. occupies a distinct tier as an industrial equipment manufacturer with captive fuel dispenser relationships, while Invenco Group Ltd. represents regional specialization in Asia-Pacific petroleum retail modernization. Dover Fueling Solutions and Scheidt & Bachmann GmbH sit within the European industrial automation tradition, serving compliance-intensive markets with precision-engineered hardware configurations.
| Leading Market Players |
|---|
| NCR Corporation |
| Gilbarco Inc. |
| Invenco Group Ltd. |
| Verifone, Inc. |
| Dover Fueling Solutions |
| Scheidt & Bachmann GmbH |
| Apple Inc. |
| Temenos AG |
| Capgemini SE |
| Others |
Cost & Logistics Intelligence
Captive integration into secure element chip fabrication anchors both supply security and pricing power for terminal manufacturers serving PCI DSS-certified deployments. This backward integration choice separates vendors capable of weathering semiconductor allocation volatility from assemblers exposed to spot-market component costs.
Pricing Analysis
Cost-down pressure on standard-tier hardware accelerates because petroleum procurement officers are unbundling terminal purchases from payment processing contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by EMV certification grade and after-sales service bundling. Pricing pressure stems from mobile wallet substitution reducing transaction dependency at equipped forecourts. Regional fuel chains exhibit highest price sensitivity; multinational petroleum brands prioritize certification reliability over unit cost.
Supply Chain Analysis
PCI DSS and EMV certification gating compresses vendor qualification timelines while concentrating procurement relationships among pre-approved hardware suppliers. Secure element fabrication centers on Taiwan and South Korea; weather-hardened enclosure manufacturing draws from China and Germany. Supply chain risk hinges on single-source vulnerability for cryptographic chip supply. Distribution runs through petroleum equipment distributors and direct OEM relationships with fuel dispenser manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure element fabrication capacity constraints prop pricing power for qualified vendors, creating a supply-constrained market structure favoring incumbents with captive chip relationships.
For Market Incumbents: Extend subscription-based terminal management software penetration to capture recurring revenue beyond hardware refresh cycles. Defensive consolidation through certification investment in biometric-ready hardware designs counters emerging authentication substitution threats. Capacity addition in Indian manufacturing clusters addresses regional procurement localization mandates. For New Entrants and Emerging Players: Launch via portable terminal rental models targeting seasonal parking operations and festival infrastructure where fixed-mount economics fail. The most penetrable segment lies in Indian highway corridor modernization programs piloting unattended payment infrastructure. White-space capture demands cloud-connected architecture with open-payment-platform compatibility. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial equipment manufacturers seeking fuel dispenser payment integration capabilities. Long-term viability favors vendors with software-defined platform architectures monetizing transaction data beyond pure payment processing. The signal to watch is petroleum procurement officer unbundling velocity accelerating direct hardware purchasing relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Platform Migration | Enables Verifone and NCR to monetize terminal lifecycles through remote firmware management subscriptions. |
| Biometric Authentication Integration | Positions Gilbarco and Dover Fueling Solutions for pilot programs at high-volume urban forecourts. |
| India Manufacturing Localization | Addresses state-owned petroleum marketing company procurement preferences for domestic assembly. |
| Open-Payment-Platform Compatibility | Captures share from integrated-stack competitors as procurement officers unbundle hardware from processing contracts. |
| 5G Cellular Module Redesign | Satisfies FCC resilience mandates while future-proofing rural forecourt deployments against carrier sunset timelines. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with petroleum procurement officers, terminal firmware engineers, fuel dispenser OEM product managers, and PCI DSS compliance consultants provided operational validation. Secondary sources encompassed FCC spectrum allocation notices, PCI Security Standards Council certification databases, SEC 10-K equipment disclosures, and petroleum retail trade association infrastructure surveys. Bottom-up unit economics triangulated against top-down market sizing across hardware configuration tiers.
Granularity-level modeling disaggregated volume and value outputs by product type, installation permanence, security technology architecture, and end-user operational intensity across the projection horizon. CAGRs derived from logistic adoption curves fitted to EMV certification deadline impacts and contactless transaction threshold trajectories. Industry-specific forecast inputs incorporated petroleum chain retrofit pipeline data and cellular carrier sunset timeline disclosures.
Semiconductor allocation volatility, EMV laboratory certification backlogs, and mobile wallet substitution acceleration are the dominant revision risks to installed base projections. Forecasts reflect documented assumptions regarding regulatory compliance timeline adherence and petroleum retailer capital allocation priorities. A model refresh is warranted upon material change in FCC spectrum reallocation schedules or major petroleum chain in-app payment platform deployment velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Retail Cash Management Market
Payments
E-Wallet Market
Payments
Asia-Pacific Payments Market
Payments
Europe Credit Cards Market
Payments
Singapore Payments Market
Payments
Qatar Payments Market
Payments
Europe Payment Gateways Market
Payments
Credit Card Issuance Services Market
Payments
Japan Mobile Payments Market
Payments
Buy Now Pay Later Platform Market
Payments
Cyprus POS Terminals Market
Payments
France Buy Now Pay Later Services Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
North America Payment Gateway Market
Payments
Crypto Payment Gateway Market
Payments
Singapore Remittance Market