
 Global Mobile Point of Sale (Mpos) Terminals Market | 2026-2036
Global Mobile Point of Sale (Mpos) Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Point of Sale (Mpos) Terminals Market Intelligence
The MPOS terminal category is repositioning around a sharp split between premium integrated systems and commodity Bluetooth readers. PAX Technology leverages manufacturing scale to dominate hardware supply across Asia and Latin America. VeriFone anchors its position through deep channel control in North American enterprise accounts. Ingenico specializes in NFC-first designs that command stronger margins in European retail environments.
A mobile point of sale terminal is a portable electronic device that processes card payments through wireless connectivity, typically incorporating EMV chip readers, magnetic stripe heads, and PIN entry pads within a battery-powered form factor under 500 grams. These devices enable merchants to accept credit, debit, and digital wallet transactions outside fixed retail locations. Handheld devices and NFC terminals lead volume shipments, while cloud-based POS technology captures expanding software-recurring revenue pools. QR code scanning functionality grows fastest among technology segments, particularly in markets where smartphone penetration outpaces traditional banking infrastructure. Offline POS capability retains structural importance for field sales and remote agents operating beyond reliable connectivity zones.
FCC certification requirements in the United States govern radio transmission standards for wireless payment devices, while the EU AI Act and GDPR impose escalating data governance obligations on European terminal deployments. India's RBI mandates tokenization protocols that reshape hardware security architecture for devices serving micro merchants. Stakeholders must monitor how Brazil's central bank instant payment integration and India's UPI expansion alter the competitive balance between proprietary terminal ecosystems and smartphone-native acceptance solutions.
Market Dynamics
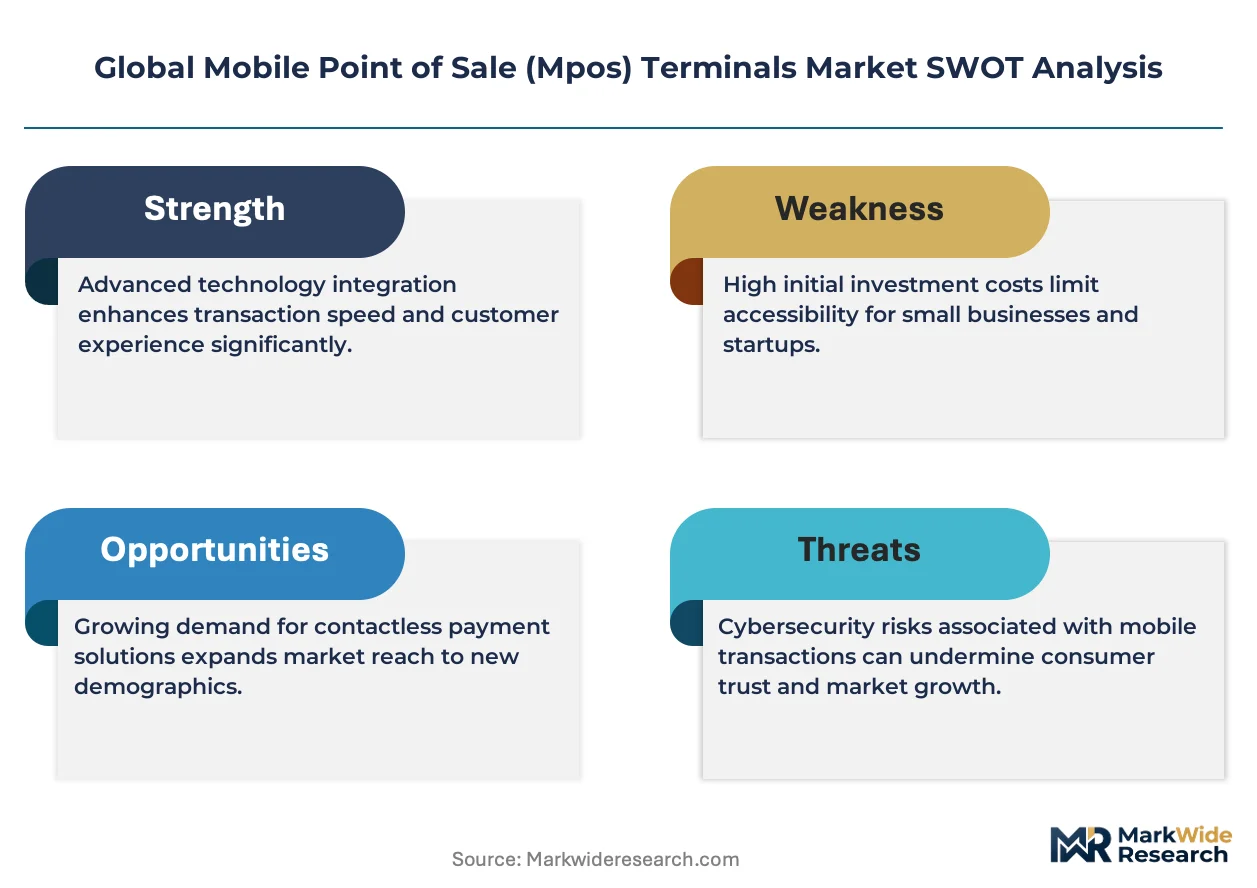
The MPOS terminal market is fragmenting around two competing acceptance models: dedicated hardware devices versus smartphone-native software solutions enabled by NFC tap-to-phone technology. This bifurcation is compressing margins at the mid-tier while expanding addressable merchant populations previously excluded from electronic payments.
Growth Catalysts
- India's UPI expansion:The Reserve Bank of India's interoperable payment infrastructure drives micro-merchant onboarding through low-cost QR and sound-based transaction protocols, creating hardware demand for hybrid terminals.
- Brazil's instant payment mandate:ANVISA-aligned health sector mobile payment requirements and PIX integration push terminal deployment into informal street commerce and ambulatory care settings.
- Cloud POS migration:Software-as-a-service POS platforms reduce merchant capital barriers and accelerate refresh cycles for connected handheld devices across Southeast Asian retail.
Market Restraints
- Semiconductor supply concentration:Secure element chip fabrication concentrates in Taiwan and South Korea, exposing terminal manufacturers to geopolitical supply disruptions and extended lead times.
- Smartphone substitution threat:Soft-POS applications on standard NFC-enabled phones displace dedicated terminal demand among sole proprietors and low-volume merchants.
- GDPR compliance friction:European data localization and consent management requirements impose architectural costs that slow deployment timelines for cross-border payment service providers.
Strategic Opportunities
- Sub-Saharan underpenetration:Nigeria, Kenya, and Ghana present white space where mobile money interoperability creates demand for hybrid terminals bridging card and wallet acceptance.
- Offline capability premium:Field sales forces and remote agents in connectivity-constrained environments require store-and-forward transaction processing, commanding hardware price premiums.
- ISO 20022 convergence:Rich data messaging standards enable value-added services—invoice reconciliation, loyalty integration, inventory sync—differentiating integrated terminal-software bundles.
Industry Challenges
- EMV certification bottlenecks:Laboratory testing queues and scheme-specific approval processes extend product launch timelines by 6-14 months for new terminal designs.
- Payment scheme fragmentation:Proprietary contactless protocols from closed-loop wallets complicate firmware development and require ongoing certification maintenance across regional variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Point of Sale (Mpos) Terminals Market |
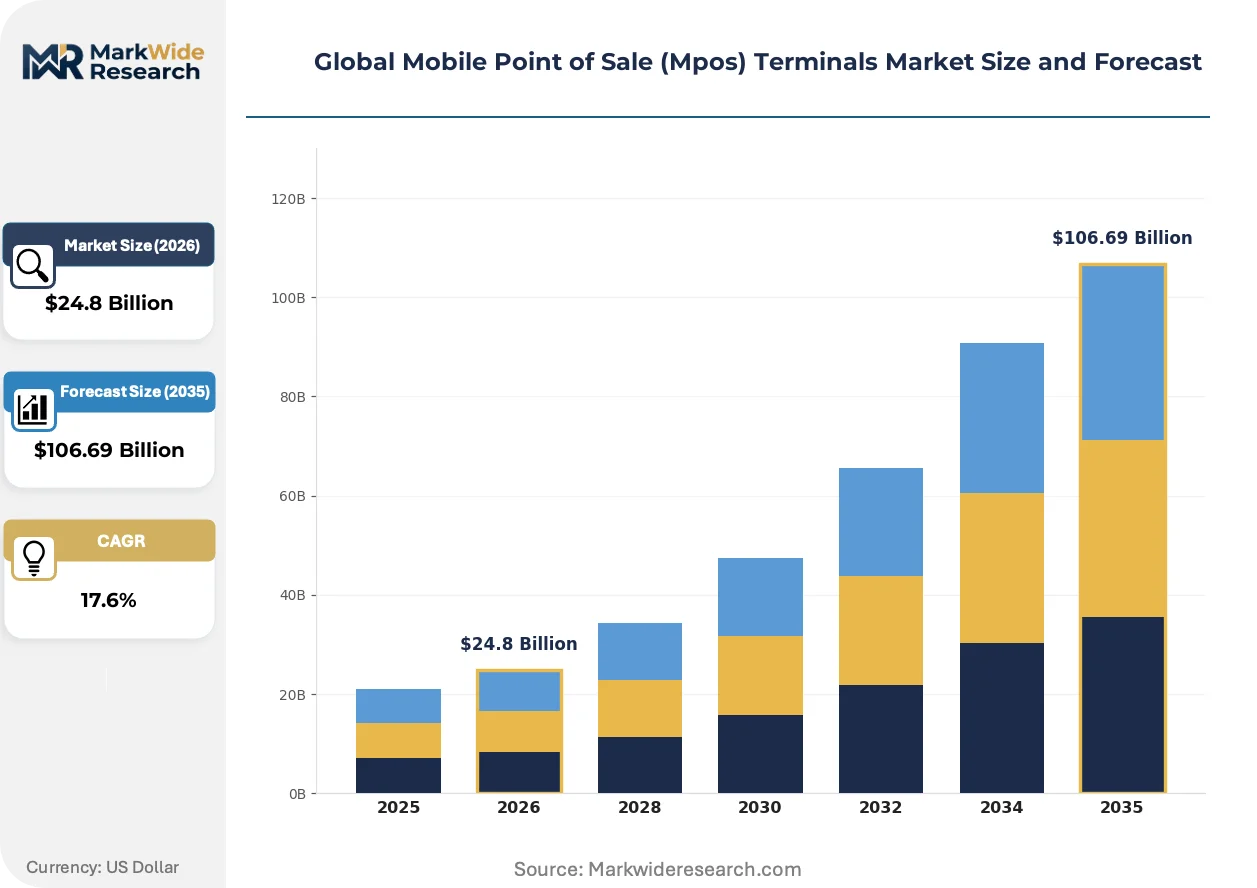
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $106.69 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Wearable Terminals, Smart Card Readers, Bluetooth POS, NFC Terminals, Barcode Scanners Technology: Cloud-Based POS, Offline POS, Hybrid POS, Chip and Pin, Magnetic Stripe, QR Code Scanning Application: Food Trucks, Pop-Up Shops, Event Transactions, Street Vendors, Mobile Retailers, Field Sales End User Type: Small Businesses, Micro Merchants, Specialty Retailers, Courier Services, Remote Agents, Freelance Sellers |
| Companies Covered | PAX Technology, VeriFone, Ingenico, Block Inc., Fiserv Inc., Oracle, HP Development Company, Toshiba Global Commerce Solutions, Newland Payment Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Point of Sale (Mpos) Terminals Market Strategic Shifts & Innovations
Hardware-software decoupling is accelerating as merchant acquirers unbundle terminal supply from processing contracts. This shift enables independent software vendors to capture recurring revenue while commoditizing device margins.
Soft-POS architecture is modularizing payment acceptance infrastructure. The technology transforms standard smartphones and tablets into certified payment terminals through downloadable applications and external PIN pads. Micro-merchants in Indonesia and Vietnam adopt these solutions fastest, bypassing dedicated hardware procurement entirely. This convergence is compressing the addressable market for basic Bluetooth card readers while expanding software licensing pools.
Europe's AI Act imposes algorithmic transparency obligations on fraud detection systems embedded in terminal software. Payment service providers must document automated decision-making logic and enable human override protocols. High-risk merchant categories—gambling, cryptocurrency exchange, cross-border remittance—face heightened documentation burdens and extended compliance review cycles before terminal activation.
Merchant procurement preferences are rotating toward subscription-based hardware provisioning. Small retailers in Mexico and Colombia reject upfront capital expenditure models in favor of per-transaction leasing arrangements bundled with software access. This shift transfers device obsolescence risk to acquirers and accelerates replacement cycles as terminal-as-a-service providers refresh fleets on 24-month rotations.
Global Mobile Point of Sale (Mpos) Terminals Market Segmentation
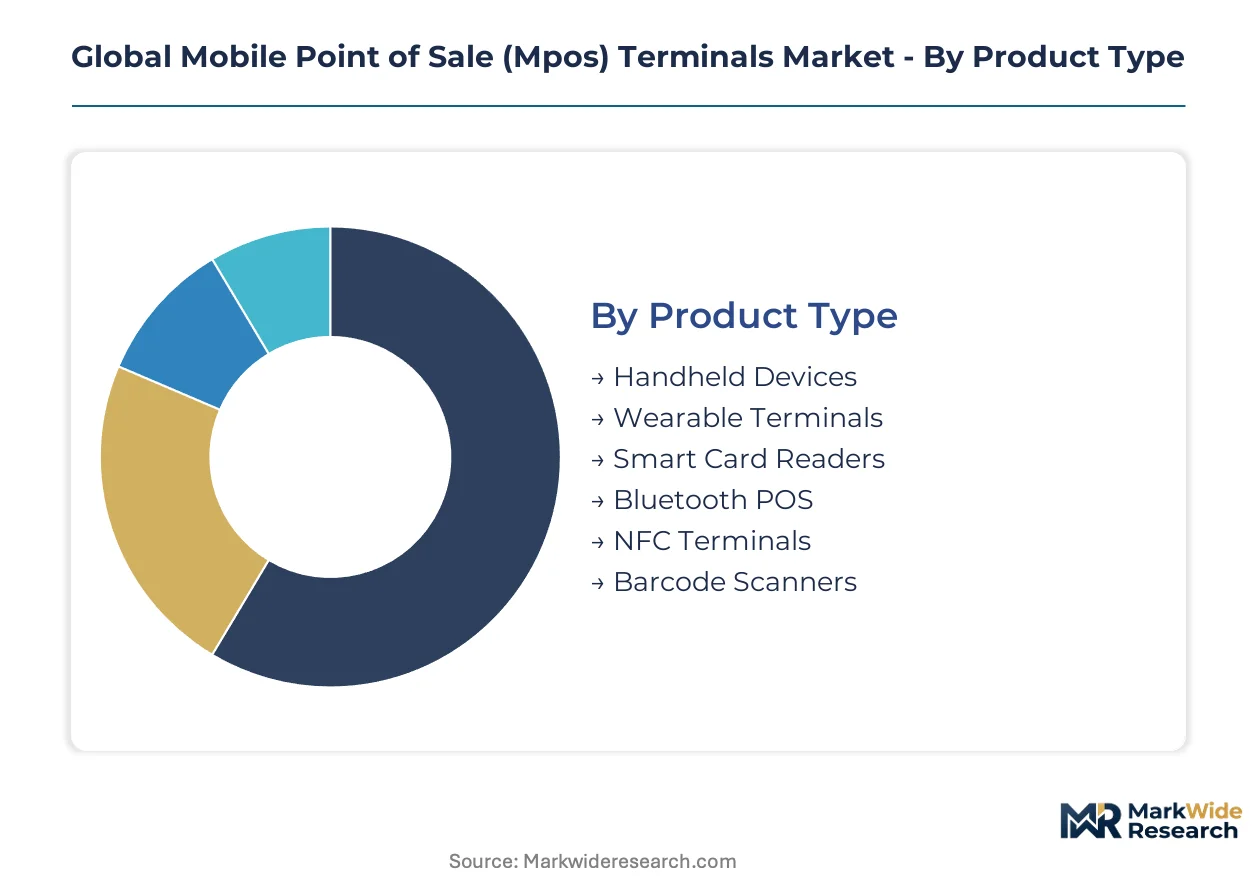
Hardware configurations and connectivity architectures determine deployment economics across merchant tiers. Segmentation reveals where capital requirements concentrate and which acceptance modalities are displacing legacy infrastructure.
Product Type:
Capital intensity varies sharply—integrated terminals demand semiconductor secure elements and EMV certification investments, while peripheral readers ride on smartphone compute cycles.
- Handheld Devices:Battery-powered units under 500 grams integrate EMV chip readers, magnetic stripe heads, and PIN entry pads in a single form factor. India's micro merchants drive volume through RBI-mandated tokenization-compliant hardware, though certification queues extend launch timelines.
- NFC Terminals:Contactless-first designs command premium positioning in European retail environments where GDPR and EU AI Act obligations elevate data governance costs. These units capture recurring software revenue through cloud-tethered transaction routing.
- Wearable Terminals:Wrist-mounted or clip-on devices for field sales forces in connectivity-constrained zones.
- Smart Card Readers:Chip-centric peripherals favored by courier services requiring rapid card-present authentication.
- Bluetooth POS:Low-cost tethered readers commoditizing as soft-POS alternatives penetrate sole proprietor segments.
- Barcode Scanners:QR-enabled hybrids bridging card and wallet acceptance in Southeast Asian markets.
Handheld devices absorb the bulk of installed capacity; NFC terminals are expanding most quickly.
Technology:
Merchant technical sophistication and connectivity reliability dictate architecture selection across deployment contexts.
- Cloud-Based POS:SaaS platforms reduce merchant capital barriers and accelerate refresh cycles across Indonesian and Vietnamese retail. Subscription provisioning transfers obsolescence risk to acquirers.
- QR Code Scanning:Smartphone-native functionality grows fastest where banking infrastructure lags device penetration. Brazil's PIX integration and India's UPI expansion drive hybrid terminal demand bridging proprietary and interoperable protocols.
- Offline POS:Store-and-forward processing commands hardware premiums for remote agents beyond reliable connectivity zones.
- Hybrid POS:Dual-mode architectures switching between cloud-tethered and offline operation.
- Chip and Pin:EMV-compliant authentication remaining mandatory for high-value transaction categories.
- Magnetic Stripe:Legacy compatibility layer phasing out under regulatory sunset timelines.
Cloud-based POS captures the majority of new software-recurring revenue; QR code scanning is climbing the fastest.
Application:
Physical mobility requirements and transaction velocity shape device specifications across use cases.
- Street Vendors:Brazil's informal commerce digitization and ANVISA-aligned health sector mobile payments create dense terminal deployment. Low-cost QR and sound-based protocols dominate.
- Field Sales:Connectivity-constrained environments require offline-capable units with extended battery performance.
- Food Trucks:Weather-resistant handheld units with thermal receipt printing.
- Pop-Up Shops:Temporary retail configurations favoring rapid provisioning and teardown.
- Event Transactions:High-volume burst processing demanding robust queue management.
- Mobile Retailers:Inventory-integrated terminals enabling real-time stock reconciliation.
Street vendors account for the largest addressable merchant expansion; field sales is gaining share fastest.
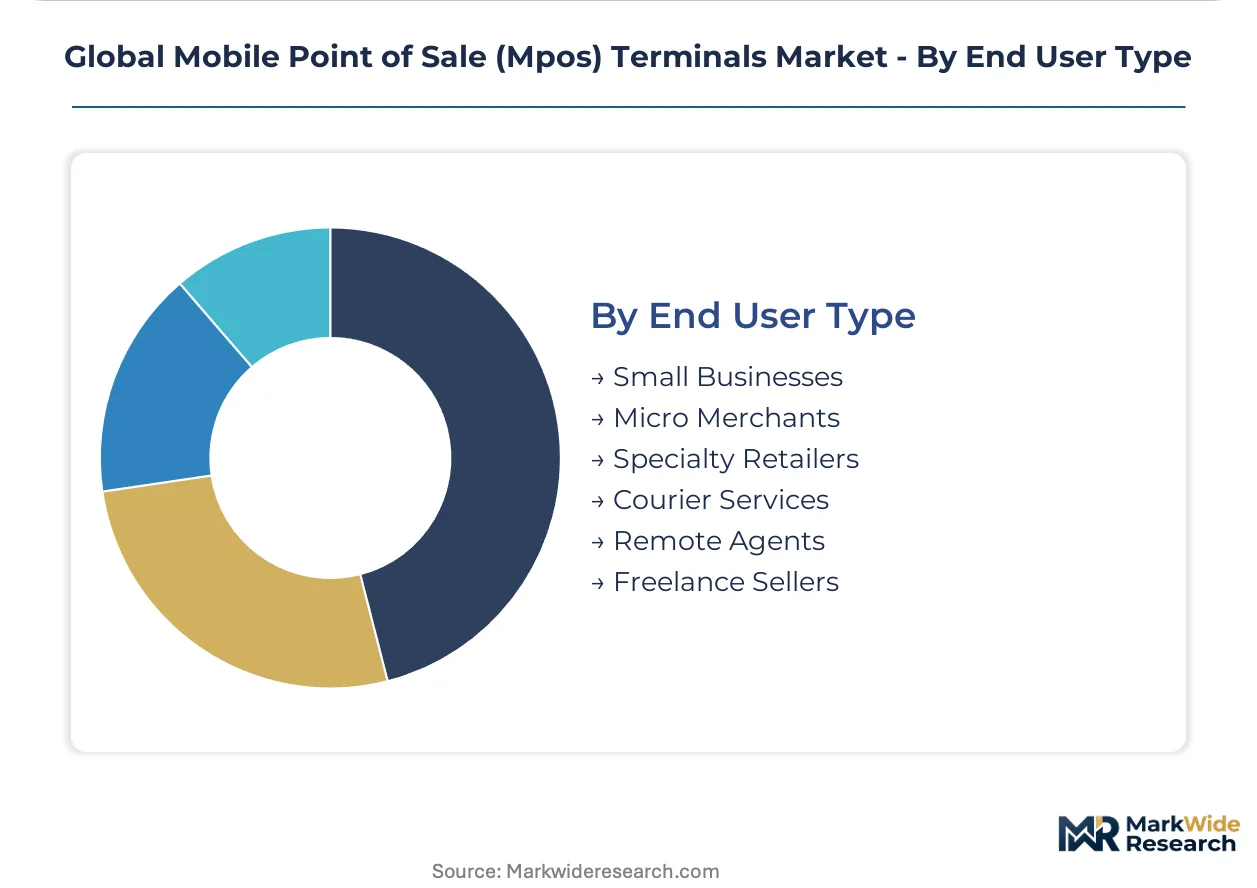
End User Type:
Merchant scale and payment volume determine hardware procurement models and service bundling preferences.
- Micro Merchants:India's UPI expansion drives onboarding through low-cost acceptance solutions. Per-transaction leasing arrangements in Mexico and Colombia reject upfront capital expenditure.
- Small Businesses:Subscription-based hardware provisioning accelerates replacement cycles on 24-month rotations.
- Specialty Retailers:Niche category merchants requiring loyalty integration and inventory synchronization.
- Courier Services:Mobility-optimized devices with rapid authentication protocols.
- Remote Agents:Field-deployed personnel requiring store-and-forward transaction capabilities.
- Freelance Sellers:Individual service providers adopting soft-POS smartphone solutions.
Micro merchants represent the deepest volume pool; small businesses are scaling terminal deployment most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors terminal manufacturing capacity through PAX Technology's production base, while São Paulo's street commerce digitization and Mumbai's micro-merchant onboarding reshape demand geography across three continents.
United States
FCC certification governs wireless transmission standards for payment devices entering the market. Enterprise merchants in Chicago and Atlanta drive demand for integrated terminal-software bundles with loyalty synchronization. The Department of Commerce's semiconductor export controls indirectly affect secure element sourcing timelines.
Brazil
ANVISA-aligned health sector mobile payment mandates and PIX instant payment integration push terminal deployment into ambulatory care and informal street commerce. São Paulo's dense vendor populations adopt hybrid QR-card terminals fastest. The central bank's regulatory sandbox accelerates fintech-acquirer partnerships for micro-merchant onboarding.
India
RBI-mandated tokenization protocols reshape hardware security architecture for devices serving micro merchants. Mumbai and Bangalore's fintech corridors concentrate acquirer operations and terminal distribution networks. The Payments Infrastructure Development Fund subsidizes device costs for merchants in tier-2 and tier-3 cities.
Germany
GDPR data localization and EU AI Act algorithmic transparency obligations elevate compliance costs for terminal software deployments. Frankfurt's financial services cluster demands NFC-first designs with rich-data ISO 20022 messaging. The KBA does not regulate this sector; instead, BaFin oversees payment institution licensing.
Indonesia
Bank Indonesia's QRIS standardization drives interoperability between proprietary wallets and card networks. Jakarta and Surabaya's retail corridors adopt cloud-based POS platforms with per-transaction leasing models. Micro-merchants bypass dedicated hardware entirely through soft-POS smartphone solutions.
Global Mobile Point of Sale (Mpos) Terminals Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a bifurcated structure where manufacturing scale anchors one pole and software-recurring revenue captures the other. The vendor base concentrates around three strategic archetypes: integrated hardware-software stack owners, pure-play terminal fabricators, and payment-platform-agnostic device suppliers. Consolidation pressure intensifies as acquirers unbundle terminal supply from processing contracts, forcing hardware specialists to defend margin position through manufacturing efficiency or niche certification expertise.
Among Asia-Pacific-based fabricators, PAX Technology exemplifies the scale-driven archetype through Shenzhen-centered production capacity. VeriFone occupies a position within the enterprise-channel-control tier, while Ingenico represents the NFC-first design specialist commanding premium positioning in European retail environments.
| Leading Market Players |
|---|
| PAX Technology |
| VeriFone |
| Ingenico |
| Block Inc. |
| Fiserv Inc. |
| Oracle |
| HP Development Company |
| Toshiba Global Commerce Solutions |
| Newland Payment Technology |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up terminal specialists anchor supply discipline through Shenzhen-centered manufacturing networks, translating semiconductor secure element scarcity into subscription-based hardware provisioning that transfers obsolescence risk downstream to merchant acquirers.
Pricing Analysis
Transaction-throughput pricing anchors merchant acquisition economics, with per-transaction leasing arrangements in Mexico and Colombia displacing upfront capital expenditure. Price differentiation separates EMV-certified integrated terminals from commodity Bluetooth readers, with certification tier and geographic delivery cost as primary drivers. Cost compression in entry-level readers intensifies because soft-POS smartphone alternatives bypass dedicated hardware procurement entirely. Micro merchants exhibit highest price sensitivity, while enterprise accounts in Chicago and Atlanta absorb premium positioning for loyalty-integrated bundles.
Supply Chain Analysis
EMV certification laboratory queues gate production release timelines, extending product launches by 6-14 months for new terminal designs. Secure element chip fabrication concentrates in Taiwan and South Korea, drawing from specialty semiconductor foundries and battery cell manufacturers in China. Single-source vulnerability in secure element supply exposes terminal manufacturers to geopolitical disruption. Distribution runs through acquirer channel partnerships and independent software vendor platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where RBI-mandated tokenization protocols and EU AI Act algorithmic transparency obligations erect barrier-to-entry moats favoring incumbent certification holders over unqualified entrants.
For Market Incumbents: Acquire cloud-native POS software platforms to unbundle terminal supply from processing contracts and capture recurring revenue pools. Defensive consolidation should prioritize certification maintenance infrastructure against EMV laboratory testing bottlenecks. Capacity addition in Brazilian fintech-acquirer partnerships addresses ANVISA-aligned health sector deployment demand.
For New Entrants and Emerging Players: Direct-to-merchant digital onboarding routes bypass entrenched acquirer channel control in Sub-Saharan African markets. Nigeria, Kenya, and Ghana present white space where mobile money interoperability creates demand for hybrid terminals bridging card and wallet acceptance. ISO 20022 messaging expertise enables value-added service differentiation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor software-recurring revenue specialists with established EMV certification pipelines in European retail environments. Long-term viability hinges on terminal-as-a-service model adoption accelerating replacement cycles. The signal to watch is central bank instant payment integration altering competitive balance between proprietary terminal ecosystems and smartphone-native acceptance solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| EMV Certification Pipeline Investment | Reduces laboratory queue exposure and accelerates product launch timelines for new terminal designs. |
| Cloud-Native POS Platform Acquisition | Captures software-recurring revenue pools as acquirers unbundle terminal supply from processing contracts. |
| Sub-Saharan Distribution Partnership | Establishes first-mover position in Nigeria, Kenya, and Ghana mobile money interoperability corridors. |
| Tokenization-Compliant Hardware Refresh | Aligns device architecture with RBI mandates reshaping security requirements for micro-merchant segments. |
| ISO 20022 Messaging Capability Buildout | Enables invoice reconciliation and loyalty integration differentiating integrated terminal-software bundles. |
Research Approach
Document review covered SEC filings, central bank regulatory circulars, and EMVCo certification databases, complemented by interviews with terminal hardware engineering directors, merchant acquirer product managers, and fintech partnership leads. Primary fieldwork across São Paulo, Mumbai, and Jakarta retail corridors validated deployment velocity assumptions. Bottom-up merchant onboarding estimates triangulated against top-down semiconductor secure element demand forecasts.
Market size outputs reflect installed base modeling across handheld devices, NFC terminals, and peripheral reader categories, segmented by connectivity architecture, merchant tier, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and subscription provisioning adoption curves. Forecast inputs incorporated PIX integration velocity in Brazil, UPI expansion penetration in Indian tier-2 cities, and soft-POS displacement rates in Southeast Asian micro-merchant populations.
The model holds under stable certification laboratory capacity and intact semiconductor supply chains; deviation in Taiwan foundry utilization or extended EMV scheme approval timelines would shift hardware availability assumptions. A model refresh is warranted upon material change in central bank instant payment mandate scope or merchant acquirer unbundling acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Blockchain Payments Software Market
Payments
Japan Prepaid Cards Market
Payments
South Africa Real Time Payments Market
Payments
Payment Card Market
Payments
Hungary POS Terminal Market
Payments
Digital Debit Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Payment Security Software Market
Payments
Payment Analytics Software Market
Payments
Japan Mobile Payments Market
Payments
Outdoor Payment Terminal Market
Payments
Biometric Payment Cards Market
Payments
Electronic Payment System for Transportation Market
Payments
Epayment System Market
Payments
Freight Audit and Payment Service Market
Payments
Mobile Wallet Market