
 Global Smart Payment Systems Market | 2026-2036
Global Smart Payment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Payment Systems Market Foresight
The EU Green Deal's digital finance taxonomy is recalibrating how payment infrastructure providers account for energy consumption in data centers. Apple Inc. leverages its closed-loop hardware-software architecture to sustain premium transaction security standards across iOS ecosystems. PayPal Holdings Inc. anchors cross-border merchant settlement flows through its two-sided network density in North America and Europe. Visa Inc. dominates tokenization protocol adoption by embedding network-level fraud detection across issuing bank partnerships.
Smart payment systems encompass hardware and software infrastructure that enables authenticated, real-time fund transfer between transacting parties using encrypted digital protocols, typically processing transactions under 300 milliseconds through tokenized credential exchange. These systems serve commercial and consumer markets by replacing physical currency with cryptographically secured electronic value transfer. Near Field Communication technology leads physical retail deployment due to established POS terminal compatibility, while biometric authentication captures the fastest growth trajectory as liveness detection algorithms mature for facial and fingerprint verification. Cloud-based deployment models concentrate margin pools among hyperscale providers offering PCI-DSS compliant infrastructure, whereas on-premise systems retain preference among tier-one banking institutions with legacy core banking dependencies.
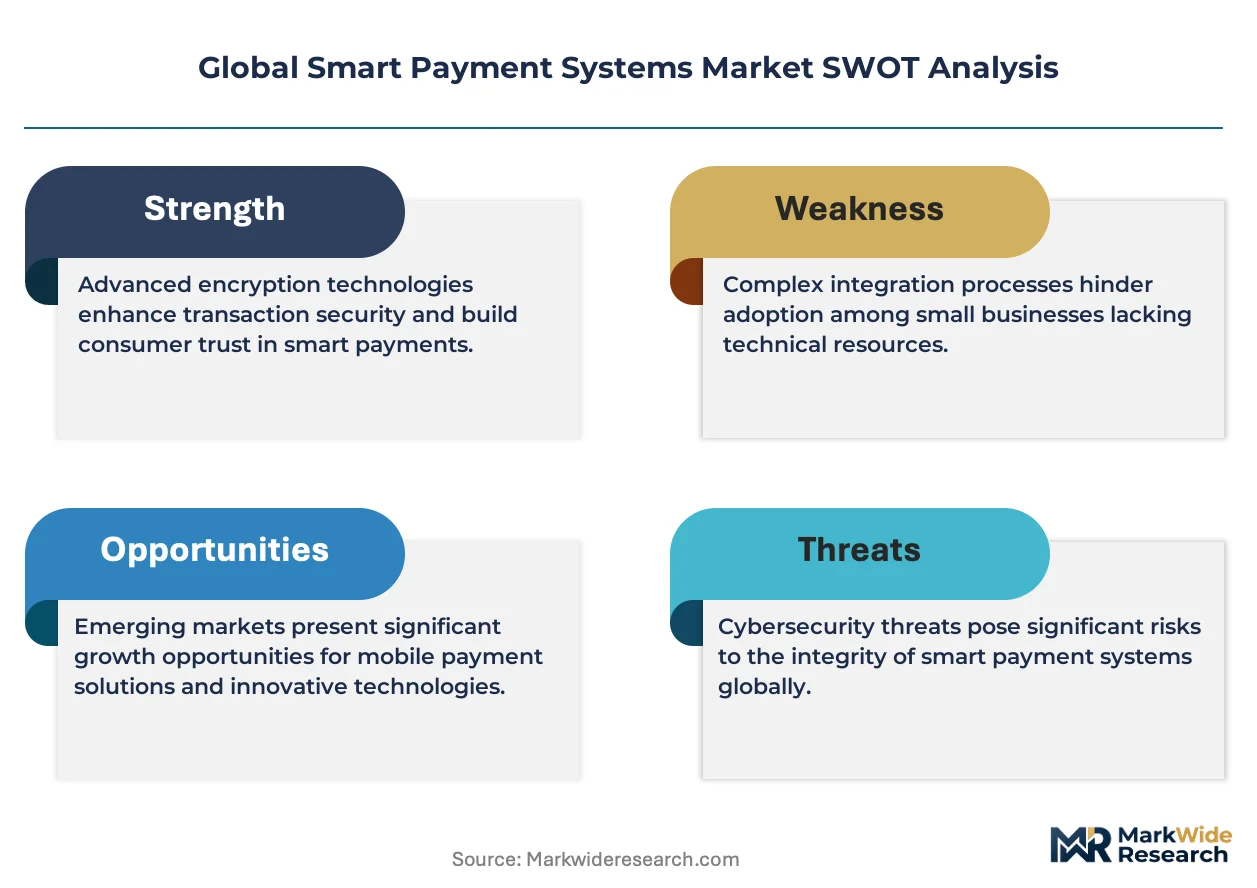
The European Banking Authority enforces PSD2 strong customer authentication requirements that shape product development roadmaps for API-integrated payment platforms. India's RBI mandates tokenization of card data for domestic transactions, compelling infrastructure rebuilds across merchant acquirers. The US Federal Reserve's FedNow instant payment rail is forcing real-time settlement capability investments among core banking vendors. Stakeholders must monitor which regulatory jurisdictions will next mandate open banking data portability standards and calibrate geographic expansion priorities accordingly.
Market Dynamics
Real-time settlement rails and tokenization mandates are compressing transaction processing windows while forcing infrastructure rebuilds across merchant acquirers and core banking vendors. The shift from batch to instant clearing is electrifying competitive positioning among payment processors.
Growth Catalysts
- India's UPI ecosystem:Transaction volume surges are compelling wallet providers and banks to expand API infrastructure for peer-to-peer and merchant payments.
- Biometric liveness detection:Facial and fingerprint verification algorithms are maturing for retail banking deployment, displacing PIN-based authentication at point-of-sale terminals.
- Europe's PSD2 framework:Strong customer authentication requirements are accelerating API-integrated platform development among fintech infrastructure providers.
Market Restraints
- PCI-DSS compliance costs:Cloud infrastructure certification and audit cycles impose capital intensity on mid-tier payment service providers.
- Core banking legacy dependencies:Tier-one institutions retain on-premise systems due to integration complexity with real-time settlement rails, slowing cloud migration.
- Tokenization infrastructure fragmentation:Divergent national mandates across India, Europe, and the United States force redundant credential vault builds.
Strategic Opportunities
- FedNow instant payment rail:The US Federal Reserve's settlement infrastructure creates white space for core banking vendors to embed real-time capabilities.
- Cross-border merchant settlement:Two-sided network density in North America and Europe enables friction reduction for international e-commerce flows.
- NFC-biometric convergence:Near Field Communication terminals combined with liveness detection open unattended retail and transit payment applications.
Industry Challenges
- API interoperability talent scarcity:Engineering teams with expertise in open banking protocol integration command premium compensation, constraining vendor scaling.
- Multi-jurisdiction certification timelines:Parallel compliance with RBI tokenization rules, PSD2 SCA requirements, and FedNow technical specifications extends product launch cycles.
- Legacy core banking integration:Real-time settlement capability deployment requires reconfiguration of batch-oriented ledger systems at established financial institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Payment Systems Market |
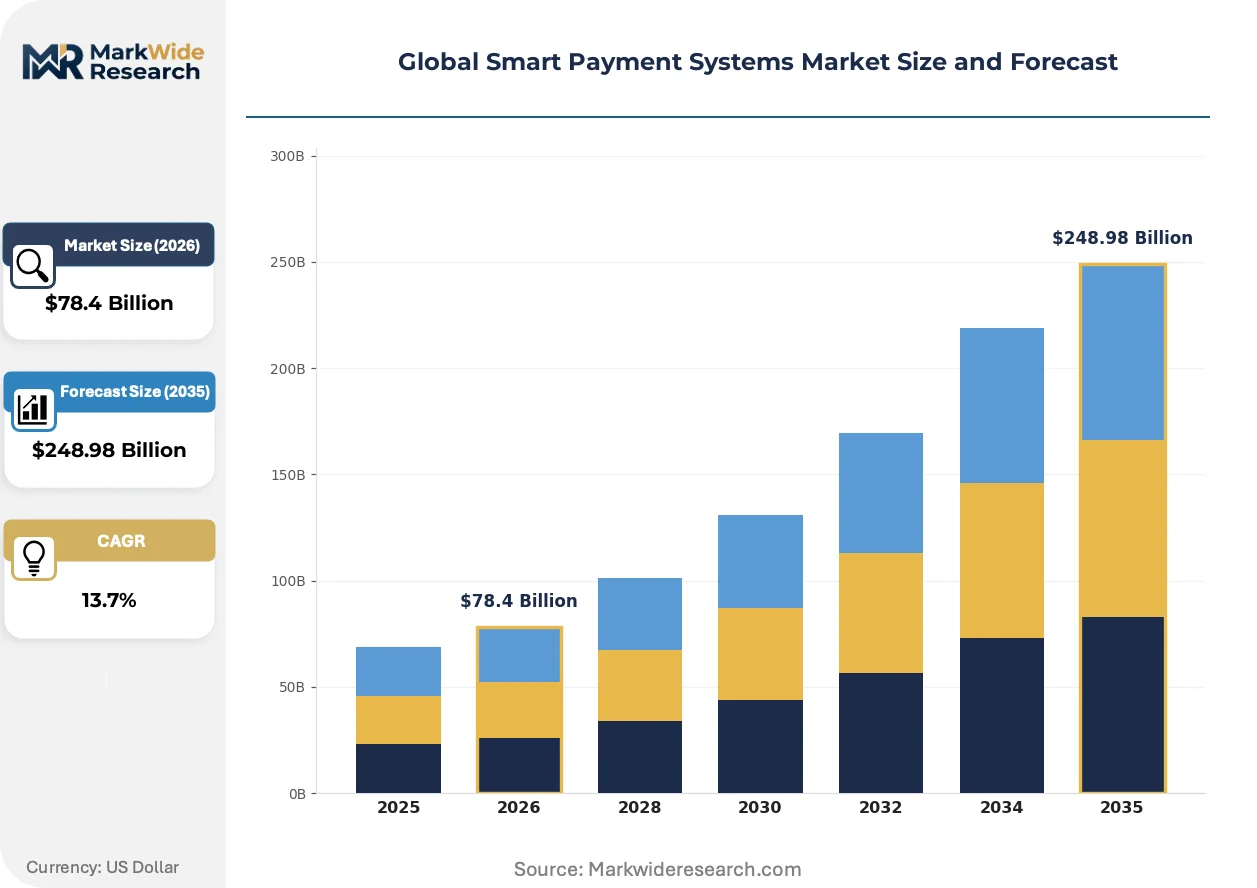
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $248.98 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Technology: Near Field Communication, QR Code, Biometric Authentication, Tokenization, Blockchain, Contactless Cards End User Sector: Banking Institutions, E-commerce Platforms, Hospitality Chains, Transportation Services, Education Providers, Government Agencies Deployment Model: Cloud-Based, On-Premise, Hybrid, Mobile Application, API Integration, SaaS Solutions Transaction Mode: Online Payment, Mobile Wallet, Point of Sale, Peer-to-Peer Transfer, Automated Clearing House, Digital Currency |
| Companies Covered | Apple Inc., PayPal Holdings Inc., Google LLC, Visa Inc., Mastercard Incorporated, FIS, Amazon Pay, Stripe Inc., Adyen N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Payment Systems Market Shifts & Advancements
Payment infrastructure is converging around three vectors: biometric authentication at the edge, regulatory-mandated open data protocols, and cloud-native core banking replacement. These forces are compressing incumbent technology refresh cycles.
Biometric liveness detection is electrifying physical retail deployment. Facial recognition algorithms with anti-spoofing capabilities now process authentication in under 300 milliseconds. Tier-two banks and transit authorities in South Korea and Singapore are adopting fingerprint-plus-face multi-factor systems at turnstiles and checkout counters. This compression of verification time is enabling unattended payment scenarios previously requiring human oversight.
Europe's Digital Finance taxonomy under the EU Green Deal is recalibrating data center energy accounting for payment infrastructure providers. The framework mandates disclosure of carbon intensity per transaction processed. Cloud hyperscalers and co-location operators are responding with renewable energy procurement and liquid cooling deployments. Issuing banks with European operations now embed energy metrics into vendor selection criteria for tokenization services.
Merchant procurement of payment acceptance hardware is rotating toward subscription-based device-as-a-service models. Small and mid-sized retailers in Brazil and Mexico are displacing capital purchase of POS terminals with monthly fee structures bundling software updates and compliance management. Independent sales organizations are capturing this shift by offering integrated acquiring-plus-hardware packages with embedded insurance against obsolescence.
Global Smart Payment Systems Market Segmentation
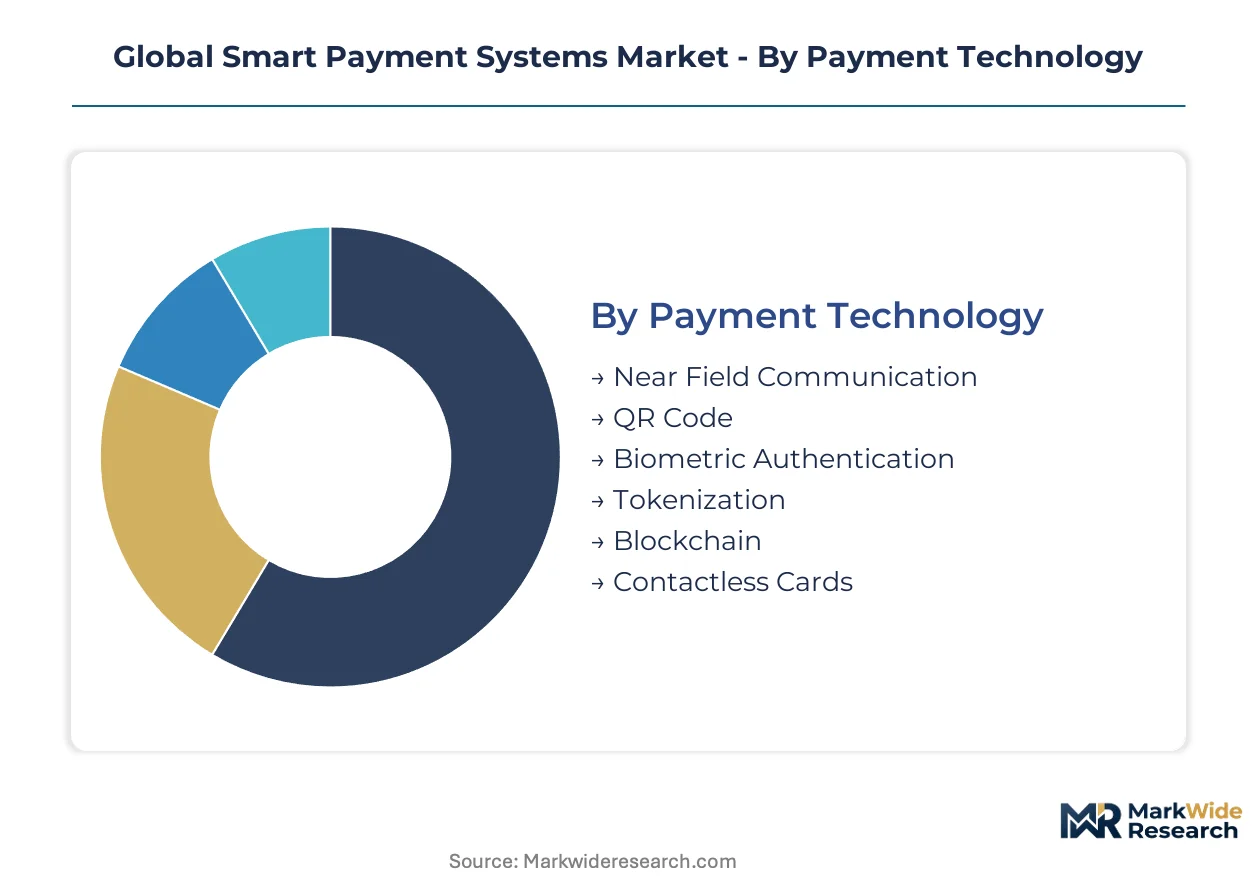
Smart payment infrastructure exhibits divergent margin profiles across technology layers and deployment architectures. Segmentation reveals where capital is concentrating and which integration pathways are forcing vendor consolidation.
Payment Technology:
Supply concentration clusters around protocols with established terminal penetration and regulatory endorsement, while emerging standards fragment engineering resources.
- Near Field Communication:Radio-frequency protocols operating at 13.56 MHz enable tap-to-pay functionality through established POS terminal infrastructure. India's UPI ecosystem and Brazil's transit authorities are deploying NFC at turnstiles and retail counters, driven by sub-300-millisecond transaction speed requirements.
- Biometric Authentication:Liveness detection algorithms for facial and fingerprint verification displace PIN-based security at physical retail. South Korean banks and Singaporean transit operators are adopting multi-factor biometric systems, compelled by PSD2 strong customer authentication mandates in Europe spreading to Asian regulatory frameworks.
- QR Code:Optical scanning protocols dominate peer-to-peer transfers in emerging markets with lower terminal infrastructure investment.
- Tokenization:Credential vaulting substitutes primary account numbers with cryptographically generated tokens, mandated by India's RBI for domestic card transactions.
- Blockchain:Distributed ledger settlement remains experimental for wholesale cross-border flows, constrained by throughput limitations.
- Contactless Cards:EMV chip cards with proximity antennas retain dominance in European physical retail due to issuer bank legacy card base.
NFC absorbs the bulk of installed capacity; biometric authentication is expanding most quickly.
End User Sector:
Cost tier stratification separates regulated financial institutions from commercial entities with lighter compliance burdens.
- Banking Institutions:Tier-one and tier-two banks deploy core-integrated payment rails with real-time settlement capabilities. European institutions are rebuilding infrastructure for PSD2 API interoperability, while US banks invest in FedNow instant payment connectivity.
- E-commerce Platforms:Online merchants demand cross-border settlement optimization and fraud detection embedded at checkout. Two-sided network density in North America and Europe enables friction reduction for international transaction flows.
- Hospitality Chains:Hotels and restaurants prioritize tableside payment terminals with integrated tipping functionality.
- Transportation Services:Transit authorities in Singapore and South Korea adopt account-based fare collection with open-loop payment acceptance.
- Education Providers:Universities deploy campus card systems converging payment and access control functions.
- Government Agencies:Tax authorities and social welfare programs mandate disbursement through traceable digital channels.
Banking institutions absorb the bulk of installed capacity; e-commerce platforms are climbing the fastest.
Deployment Model:
Margin pools concentrate among hyperscale cloud providers offering PCI-DSS certified infrastructure, while legacy dependencies sustain on-premise preference at tier-one institutions.
- Cloud-Based:Hyperscale data centers with renewable energy procurement and liquid cooling meet EU Green Deal carbon intensity disclosure requirements. European issuing banks embed energy metrics into vendor selection criteria for tokenization services.
- On-Premise:Legacy core banking dependencies at established financial institutions require batch-oriented ledger reconfiguration for real-time settlement capability deployment.
- Hybrid:Mixed architectures balance sensitive credential vaulting on-premise with scalable transaction processing in cloud environments.
- Mobile Application:Smartphone-native wallets leverage device security enclaves for biometric-protected credential storage.
- API Integration:Open banking protocol connectivity demands scarce engineering expertise commanding premium compensation.
- SaaS Solutions:Subscription-based payment acceptance bundles software updates and compliance management for mid-tier merchants.
Cloud-based deployments absorb the bulk of installed capacity; API integration is gaining share fastest.
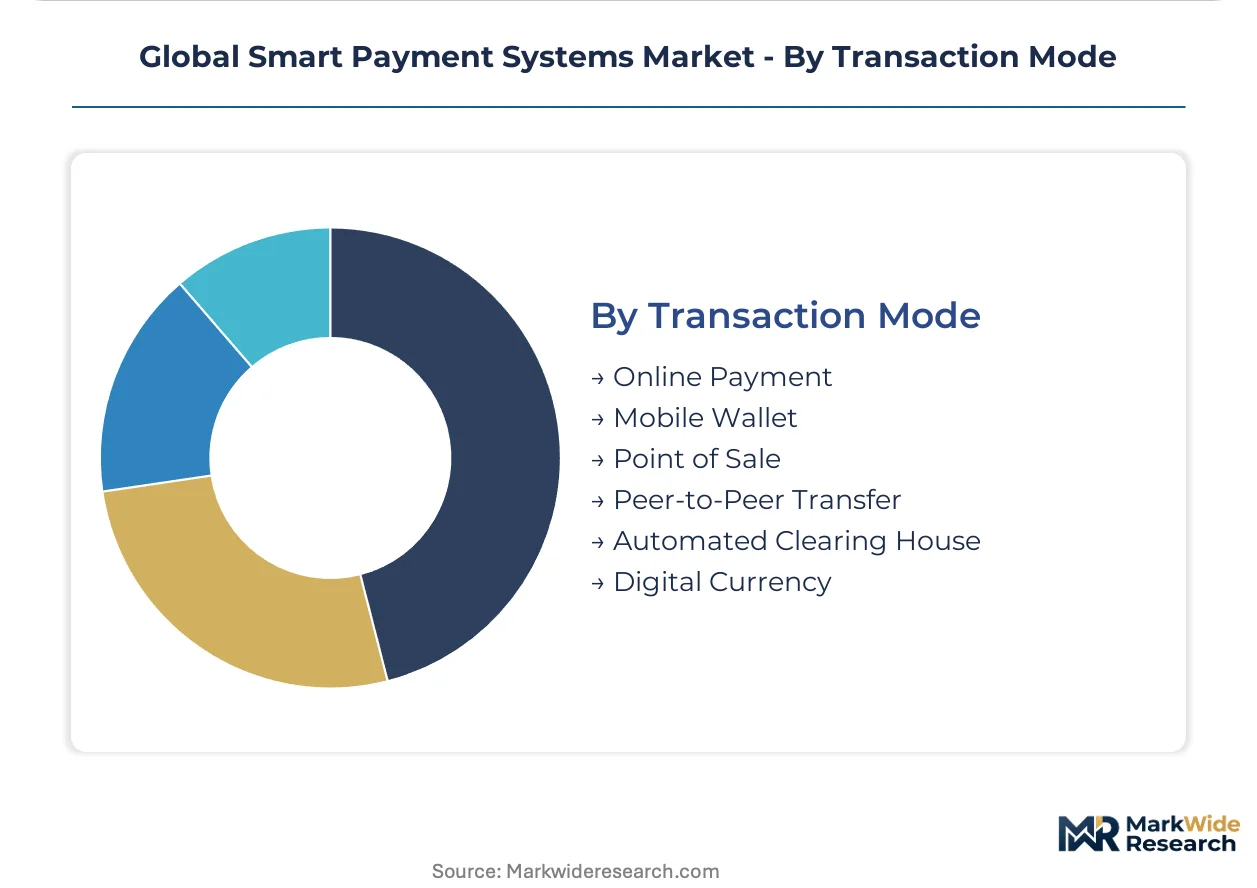
Transaction Mode:
Application requirements differentiate between immediate settlement needs and batch-optimized cost efficiency.
- Online Payment:Card-not-present transactions with 3D Secure authentication redirect through issuer bank verification portals. E-commerce platforms in North America and Europe optimize checkout conversion through embedded tokenization.
- Mobile Wallet:Smartphone-based value storage enables peer-to-peer and merchant payments through app-native interfaces. India's UPI ecosystem compels wallet providers and banks to expand API infrastructure for surging transaction volumes.
- Point of Sale:Physical retail terminals process chip, contactless, and magnetic stripe credentials.
- Peer-to-Peer Transfer:Account-to-account settlement bypasses card network interchange through real-time payment rails.
- Automated Clearing House:Batch-processed debit and credit transactions retain cost advantage for non-urgent disbursements.
- Digital Currency:Central bank digital currency pilots and private stablecoin settlement remain peripheral to mainstream infrastructure.
Online payment absorbs the bulk of installed capacity; mobile wallet is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru anchors payment infrastructure development with dense concentrations of fintech engineering talent and API-native startups. The city's technology corridor hosts core banking modernization projects serving India's UPI ecosystem.
United States
Real-time settlement demand from FedNow deployment drives core banking vendor investments. The Federal Reserve's instant payment rail mandates infrastructure upgrades across regional banks. Silicon Valley clusters concentrate tokenization protocol development for merchant acquirers.
India
UPI transaction volume surges compel wallet providers to expand API infrastructure for peer-to-peer flows. RBI tokenization rules force credential vault rebuilds across domestic merchant networks. Mumbai's financial district hosts acquiring bank data center expansions for compliance.
Germany
PSD2 strong customer authentication requirements accelerate open banking platform development. The EU Green Deal's digital finance taxonomy recalibrates data center energy accounting for Frankfurt-based payment processors. Bavarian engineering clusters supply POS terminal hardware across European retail.
Singapore
Transit authorities adopt account-based fare collection with open-loop payment acceptance. The Monetary Authority of Singapore enforces API interoperability standards for digital banking licenses. The city-state's technology zone hosts biometric liveness detection pilot programs for retail banking.
Brazil
Merchant procurement rotates toward subscription-based device-as-a-service models for POS terminals. Central bank instant payment infrastructure PIX drives real-time settlement capability investments. São Paulo's fintech corridor concentrates independent sales organizations bundling acquiring-plus-hardware packages.
Global Smart Payment Systems Market Competitive Landscape
The competitive structure tilts toward network-effect platforms with established two-sided density. Consolidation concentrates among card networks and closed-loop ecosystems with hardware-software integration capabilities. Three archetypes dominate: tokenization protocol providers, API-native infrastructure vendors, and closed-loop platform operators. Strategic moves center on real-time settlement rail partnerships and biometric authentication technology licensing.
Within the closed-loop ecosystem tier, Apple Inc. and Google LLC exemplify hardware-software integration approaches that sustain premium security standards through device-native credential storage. Visa Inc. anchors network-level tokenization protocol adoption among issuing bank partnerships. These three occupy positions that reflect divergent competitive vectors: device-centric control versus open-network scale versus merchant-acquiring specialization.
| Leading Market Players |
|---|
| Apple Inc. |
| PayPal Holdings Inc. |
| Google LLC |
| Visa Inc. |
| Mastercard Incorporated |
| FIS |
| Amazon Pay |
| Stripe Inc. |
| Adyen N.V. |
| Others |
Supply & Pricing Matrix
Tokenization infrastructure migration simultaneously compresses unit economics and concentrates procurement leverage among hyperscale cloud providers offering PCI-DSS certified environments. Tier-one banking institutions retain on-premise preference due to legacy core banking dependencies, fragmenting vendor pricing power across deployment architectures.
Pricing Analysis
Transaction throughput-based pricing anchors merchant acquiring contracts, with fees scaling to processed volume and chargeback rates. Three-tier pricing structure across premium, standard, and economy levels separates tier-one banks with dedicated infrastructure from mid-tier payment service providers on shared cloud instances. Pricing pressure stems from FedNow instant payment rail deployment forcing real-time capability investments without immediate revenue offset. Mid-tier payment service providers exhibit highest price sensitivity due to PCI-DSS compliance audit cycles consuming operating margin.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for advanced semiconductor fabrication of secure element chips embedded in POS terminals and mobile devices. Hardware manufacturing concentrates in China, Vietnam, and Mexico for terminal assembly and component integration. Cloud infrastructure draws from hyperscale data centers in the United States, Ireland, and Singapore with renewable energy procurement mandates under EU Green Deal frameworks. Tariff exposure on semiconductor imports from Taiwan threatens terminal hardware cost structures. Distribution runs through independent sales organizations bundling acquiring-plus-hardware packages with embedded software updates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market functions as a vertical-integration race where control over biometric authentication algorithms and tokenization credential vaults determines margin capture. Players pursue downstream leverage through merchant acquiring relationships and upstream control over secure hardware manufacturing.
For Market Incumbents: Cement network-effect density by embedding real-time settlement capabilities into existing issuing bank partnerships before FedNow infrastructure matures. Acquire API-native infrastructure vendors to preempt fintech disintermediation of core banking relationships. Defensive consolidation must address biometric liveness detection patent portfolios as facial verification displaces PIN-based authentication. For New Entrants and Emerging Players: Begin with device-as-a-service subscription models for POS hardware in Brazil and Mexico where independent sales organizations lack integrated acquiring-plus-software bundles. Target transit authorities in Southeast Asia adopting account-based fare collection with open-loop payment acceptance. Go-to-market leverage rests on NFC-biometric convergence pilots demonstrating unattended retail applications. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by card networks seeking biometric authentication technology licensing. Long-term viability favors vendors with embedded FedNow connectivity and renewable energy-compliant cloud infrastructure serving European issuing banks. Watch RBI tokenization mandate enforcement in India as volume inflection forcing credential vault rebuilds across merchant acquirers.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Licensing | Facial liveness detection patents enable premium positioning as PSD2 SCA requirements spread beyond Europe. |
| FedNow Integration Partnership | Real-time settlement capability anchors core banking vendor relationships with US regional banks. |
| Renewable Energy Certification | EU Green Deal carbon intensity disclosure mandates reshape vendor selection criteria for Frankfurt-based processors. |
| Device-as-a-Service Expansion | Subscription POS terminal models capture merchant procurement rotation in São Paulo's fintech corridor. |
| API-Native Infrastructure Acquisition | Open banking protocol expertise commands premium compensation, constraining organic vendor scaling. |
Research Methodology
Independent corroboration across payment processor executives, core banking modernization leads, merchant acquiring specialists, and regulatory compliance officers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation against RBI circulars, PSD2 technical standards, and FedNow service specifications. SEC filings from listed payment networks, hyperscaler capex disclosures, and customs records for POS terminal imports furnished quantitative anchors. Bottom-up transaction volume modeling and top-down infrastructure investment triangulation cross-checked segment-level outputs.
Comparable-period anchoring to historical real-time payment rail deployments in India and Europe calibrated the forecast framework across the projection horizon. Segmentation dimensions modeled include payment technology protocol, end-user sector compliance tier, deployment architecture, and transaction settlement mode. CAGRs derived from infrastructure investment run-rates and merchant adoption curve analysis. Industry-specific inputs encompassed UPI transaction volume trajectories and tokenization mandate implementation timelines.
Underlying measurement precision varies by segment; cloud-based deployment models carry tighter precision than on-premise legacy systems with opaque integration costs. Forecasts reflect assumptions regarding regulatory enforcement consistency and merchant hardware refresh cycles. Deviation in FedNow adoption velocity or RBI tokenization compliance deadlines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Latin America Mobile Payment Market
Payments
Malta POS Terminal Market
Payments
North America Payments Market
Payments
Europe Clearing Houses and Settlements Market
Payments
North America POS Terminal Market
Payments
Global Payments Market
Payments
Medical Payment Fraud Detection Market
Payments
Global Telecom Billing Market
Payments
Spain Mobile Payment Market
Payments
Global Accounts Payable (AP) Automation Software Market
Payments
Europe Accounts Payable Automation Market
Payments
South Korea Digital Payments Market
Payments
Canada Mobile Payments Market
Payments
Online Charging System (OCS) Market
Payments
South Korea POS Terminals Market
Payments
Hong Kong Payments Market