
 Slovenia Point of Sale (POS) Terminal Market | 2026-2036
Slovenia Point of Sale (POS) Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Slovenia Point of Sale (POS) Terminal Market Analytics
Slovenian POS hardware assembly capacity is restructuring around EU-sourced chipsets and localized firmware customization. Quattro POS leverages its Ljubljana engineering base to dominate domestic kiosk deployments. SETCCE sustains competitive positioning through deep integration with national fiscalization protocols. Datalab Tehnologije d.d. anchors the mid-market with hybrid cloud-on-premise configurations tailored to Slovenian accounting standards.
A Point of Sale (POS) Terminal constitutes an electronic device combining a processor, secure encryption module, card reader, and network interface to authenticate and record commercial transactions at the moment of purchase. The system typically integrates thermal printers, barcode scanners, and touchscreen displays to process payments, apply taxes, and transmit encrypted data to acquiring banks or payment processors. Fixed POS terminals still occupy the majority of installed bases in Slovenian supermarkets and department stores, though mobile POS units are capturing the fastest expansion in restaurant tableside and delivery contexts. Cloud-based POS deployments are concentrating margin pools among software-integrated providers, while self-service kiosk adoption remains nascent outside fuel retail and quick-service food.
BIS certification requirements for imported electronics, EU REACH substance restrictions on device materials, and PSD2-mandated strong customer authentication standards collectively shape hardware procurement timelines and technical specifications for Slovenian merchants. The country's national fiscalization authority enforces real-time invoice reporting, which forces terminal vendors to maintain continuously certified firmware stacks. Stakeholders must monitor whether Slovenia transposes forthcoming EU Digital Operational Resilience Act requirements into payment infrastructure compliance deadlines.
Market Dynamics
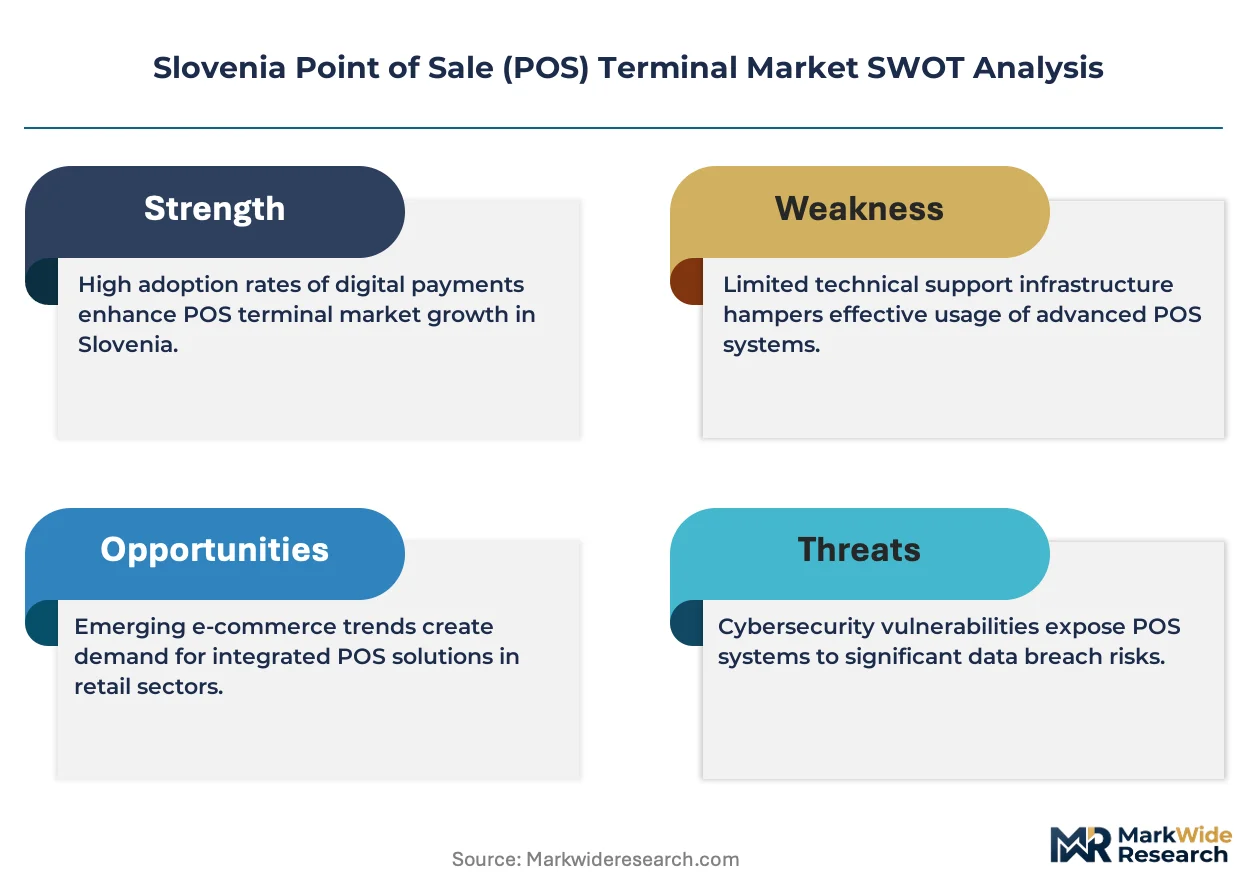
EU-mandated PSD2 strong customer authentication rules are compressing replacement cycles across Slovenian merchant estates, forcing hardware upgrades that ripple through retail grocery networks and coastal hospitality zones.
Growth Catalysts
- PSD2 SCA Mandate:The EU directive requires EMV-compliant terminals with biometric or two-factor authentication, compelling Ljubljana retailers to refresh installed bases ahead of enforcement deadlines.
- Coastal Tourism Density:Piran and Portorož hospitality clusters are deploying mobile POS units for tableside payment, accelerating unit volume in seasonal high-traffic corridors.
- National Fiscalization Protocol:Real-time invoice reporting requirements from Slovenian tax authorities necessitate certified firmware stacks, locking merchants into compliant hardware ecosystems.
Market Restraints
- EU REACH Substance Restrictions:Material compliance for circuit boards and enclosures extends procurement timelines by 8-14 weeks for non-EU component suppliers.
- Chipset Supply Concentration:Dependency on Netherlands and Germany-based semiconductor foundries creates vulnerability to allocation shocks during demand spikes.
- Fixed Terminal Obsolescence Risk:Supermarket and department store legacy hardware faces accelerated functional depreciation as software-defined payment architectures advance.
Strategic Opportunities
- Self-Service Kiosk White Space:Fuel retail and quick-service food verticals in Maribor and Celje remain underpenetrated relative to Western European adoption benchmarks.
- Cloud-Edge Convergence:Hybrid architectures combining local transaction processing with centralized reconciliation are opening mid-market merchant segments previously served by on-premise-only systems.
- EU Digital Operational Resilience Act:Anticipated transposition into Slovenian law will mandate operational continuity standards, creating certified-hardware preference effects.
Industry Challenges
- Firmware Certification Velocity:Continuous recertification demands from the national fiscalization authority strain vendor engineering bandwidth and compress product release windows.
- Legacy System Integration Friction:Merchants running Datalab accounting backends face middleware complexity when bridging to modern API-native payment processors.
- Specialized Hardware Engineering Talent:Ljubljana's concentrated POS assembly base competes for embedded systems expertise against broader automotive and industrial automation sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovenia Point of Sale (POS) Terminal Market |
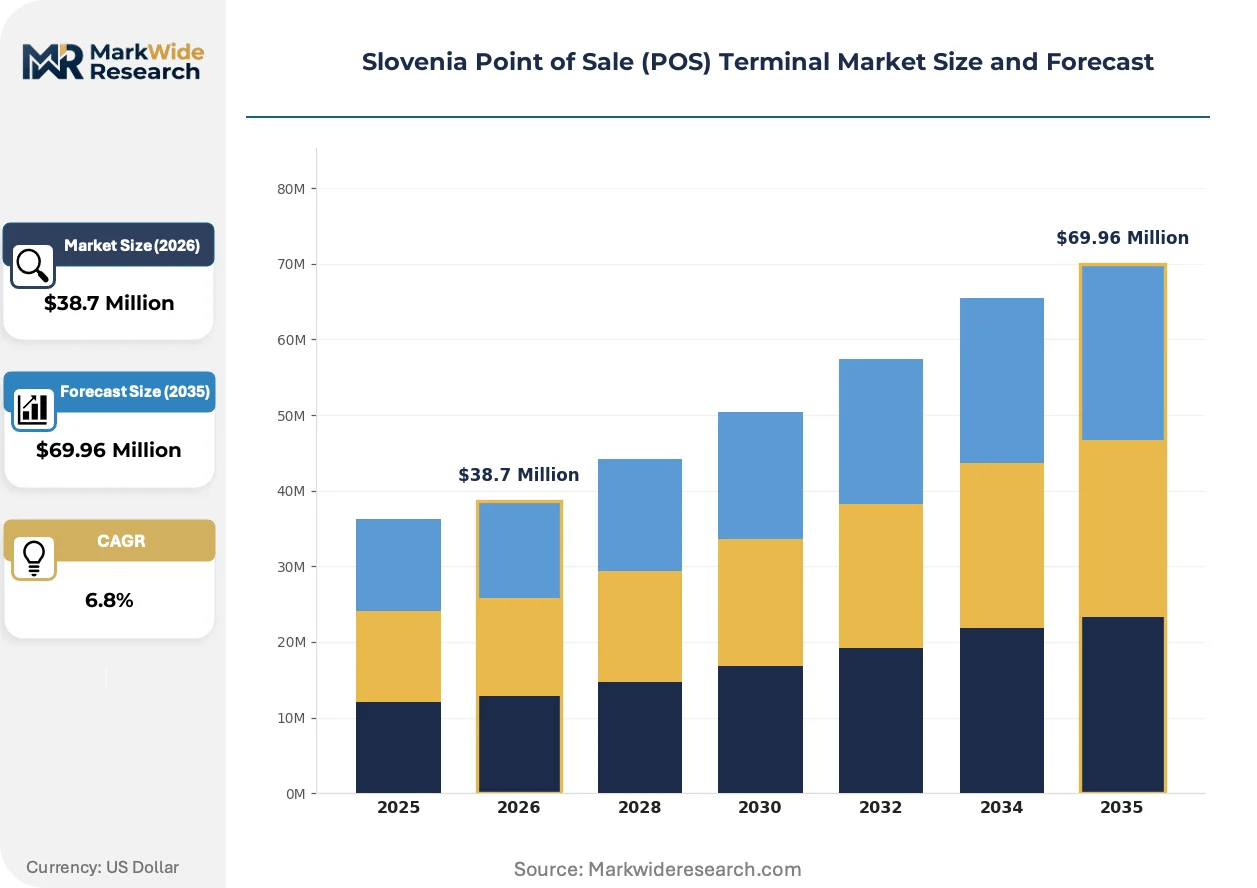
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Self-Service Kiosk, Cloud-Based POS Technology: Contactless Payment, EMV, Magnetic Stripe Reader, QR Code Payment End User: Retail, Hospitality, Healthcare, Entertainment Deployment: On-Premise, Cloud, Hybrid, Integrated |
| Companies Covered | Quattro POS, SETCCE, Datalab Tehnologije d.d., Ingenico Group, Lab4Pay, Comtron, Positiva, NCR Corporation, Micro Team, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovenia Point of Sale (POS) Terminal Market Evolving Landscape
Payment hardware architecture is converging around software-defined functionality, with terminal form factors shrinking while security modules expand capability. This shift is compressing margin structures for pure hardware vendors while elevating integrated platform providers.
SoftPOS technology is unifying smartphone and dedicated terminal functions into a single certified environment. Boutique retailers in Ljubljana's old town are piloting NFC-enabled merchant phones for queue-busting checkout. This convergence is collapsing the distinction between mobile acceptance devices and full-featured countertop units, forcing vendors to recalibrate SKU strategies.
EU REACH substance restrictions on cadmium and lead in electronics are tightening material specifications for terminal enclosures and solder joints. Slovenian importers now face extended supplier qualification cycles for Asian-manufactured components. Retail grocery chains are responding by consolidating procurement around EU-certified contract manufacturers with pre-validated material declarations.
Merchant acquisition patterns are rotating toward integrated software-hardware bundles. Independent restaurants in coastal zones are abandoning standalone terminal purchases for subscription-based platforms combining POS, inventory, and payment acceptance. This preference shift is most pronounced in Istrian-border municipalities where seasonal staffing volatility favors low-upfront, scalable systems.
Slovenia Point of Sale (POS) Terminal Market Segmentation
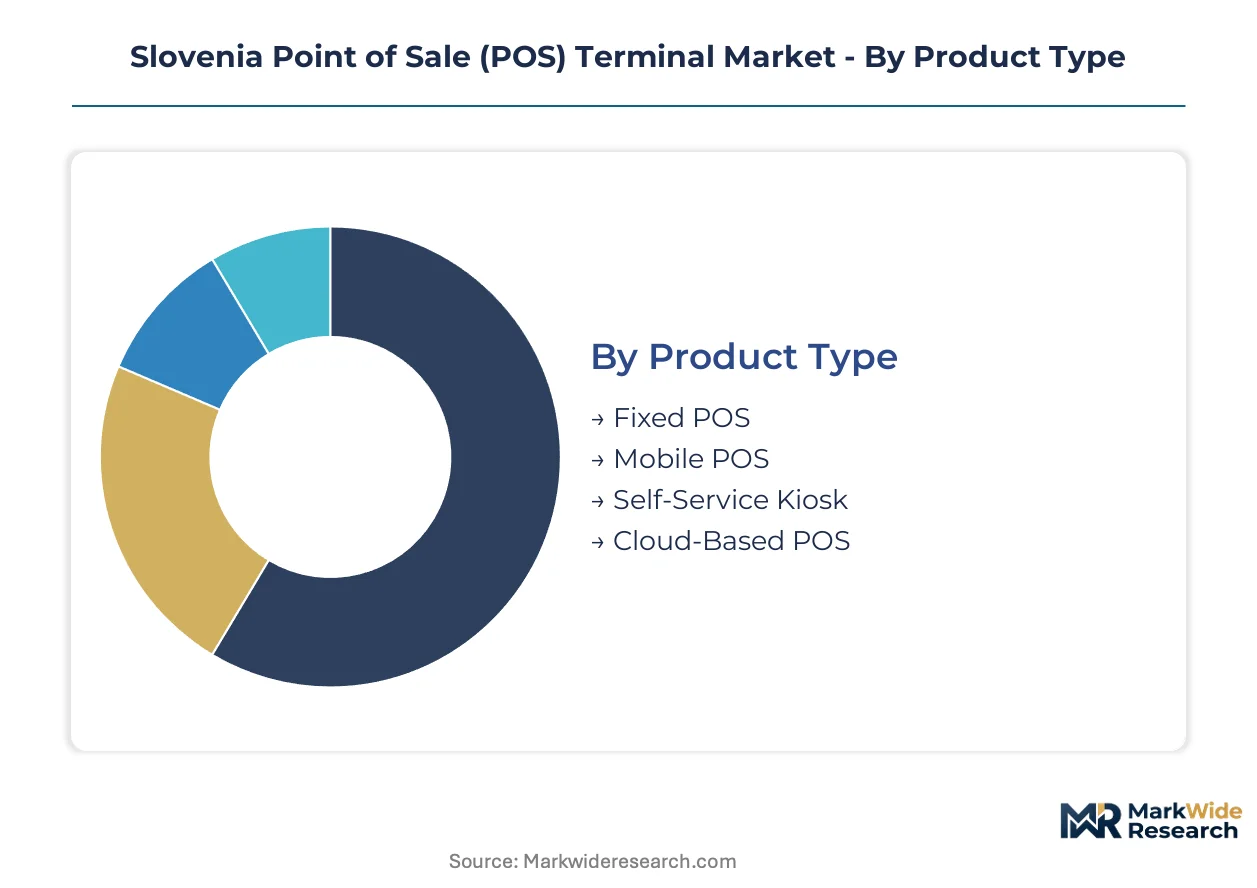
POS terminal segmentation in Slovenia reveals distinct procurement patterns across merchant tiers. National fiscalization requirements and PSD2 compliance deadlines create divergent hardware upgrade timelines by product category and deployment model.
Product Type:
Hardware form factor dictates integration complexity with Slovenian fiscalization protocols and merchant workflow patterns.
- Fixed POS:Countertop units with integrated thermal printers and secure PIN pads dominate Ljubljana supermarket checkouts. Legacy estates in Mercator and Spar networks face compressed replacement cycles as PSD2 strong authentication mandates take effect.
- Mobile POS:Tablet-based and handheld terminals with Bluetooth card readers are expanding most quickly in Piran and Portorož hospitality corridors. Seasonal tourism volatility favors low-capital deployment models for waterfront restaurants.
- Self-Service Kiosk:Unattended payment stations with touchscreen ordering integrate fiscal printers for real-time invoice transmission. Petrol stations along A1 motorway corridors represent primary adoption nodes.
- Cloud-Based POS:Browser-native transaction processing with local caching for offline resilience addresses intermittent connectivity in Julian Alps tourism zones.
Mature deployment sits with Fixed POS. Newer deployment is concentrated in Mobile POS.
Technology:
Payment authentication architecture determines hardware certification burden under EU regulatory frameworks.
- Contactless Payment:NFC-enabled terminals with tap-to-pay functionality process transactions under 50 euros without PIN verification. Ljubljana retail grocery chains accelerated rollout following PSD2 contactless limit adjustments.
- EMV:Chip-card authentication with cryptographic transaction certificates satisfies Slovenian national fiscalization authority requirements for secure audit trails. All new terminal procurements mandate EMV Level 1 and Level 2 certification.
- Magnetic Stripe Reader:Legacy swipe interfaces persist in hospitality backup configurations but face phased obsolescence under SCA rules.
- QR Code Payment:Camera-based scanning for mobile wallet integration attracts boutique retailers in Ljubljana's old town pedestrian zones.
Established infrastructure centers on EMV. Emerging adoption clusters around Contactless Payment.
End User:
Vertical-specific transaction patterns shape terminal feature requirements and replacement cadence.
- Retail:High-volume grocery and specialty stores require durable keyboards, integrated scales, and multi-lane synchronization. Urban centers from Maribor to Celje concentrate hardware refresh demand.
- Hospitality:Restaurants and hotels prioritize tableside mobility, tip adjustment workflows, and split-check functionality. Coastal tourism municipalities drive seasonal procurement spikes.
- Healthcare:Clinics and pharmacies need HIPAA-aligned encryption for patient payment data alongside national fiscal compliance.
- Entertainment:Cinemas and event venues demand high-throughput processing with offline queue buffering for peak admission rushes.
Volume concentration rests with Retail. Steepest expansion trajectory appears in Hospitality.
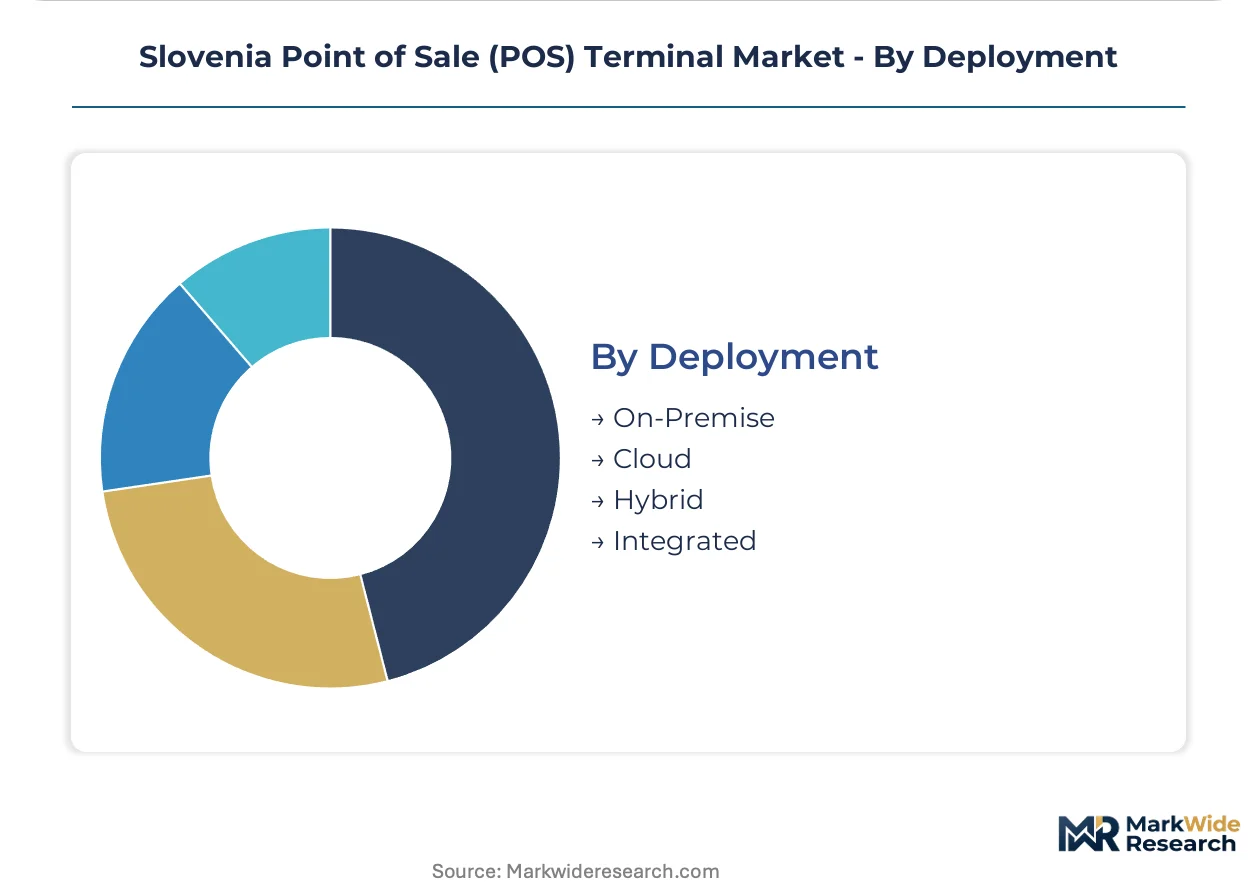
Deployment:
Infrastructure architecture determines vendor lock-in intensity and operational continuity risk exposure.
- On-Premise:Local server installations with dedicated fiscalization gateways suit large-format retailers with internal IT capabilities. Datalab accounting system integration drives preference among established Slovenian merchants.
- Cloud:Centralized transaction routing with edge caching for offline resilience appeals to multi-location hospitality operators seeking unified reporting.
- Hybrid:Local transaction processing with nightly cloud reconciliation balances real-time fiscal compliance with centralized analytics. Mid-market specialty stores in Kranj and Novo Mesto favor this architecture.
- Integrated:Bundled hardware-software-payment platforms with subscription pricing reduce upfront capital requirements for independent restaurants.
Dominant installed base runs On-Premise. Fastest share gain occurs in Hybrid configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundries in the Netherlands and Germany supply the chipsets anchoring POS terminal production across Central European merchant networks. Ljubljana's engineering base shapes domestic assembly capacity while coastal tourism corridors concentrate seasonal hardware demand.
Central Slovenia
Retail grocery chains and specialty stores in Ljubljana drive fixed POS terminal refresh cycles. The national fiscalization authority enforces real-time invoice reporting requirements. Mercator and Spar networks in the capital are upgrading legacy estates to meet PSD2 strong customer authentication deadlines.
Coastal Slovenia
Piran and Portorož hospitality clusters deploy mobile POS units for tableside payment processing. EU REACH substance restrictions on device materials extend procurement timelines for imported components. Waterfront restaurants in these municipalities favor low-capital deployment models suited to seasonal staffing volatility.
Northeast Slovenia
Maribor's fuel retail and quick-service food verticals represent underpenetrated self-service kiosk opportunities. The country's alignment with EU-wide PSD2 rules pushes merchants toward EMV-compliant hardware. Petrol stations along A1 motorway corridors are primary adoption nodes for unattended payment stations.
Southeast Slovenia
Celje's retail and hospitality sectors show emerging hybrid cloud-on-premise POS configurations. Slovenian tax authority certification demands continuously certified firmware stacks. Mid-market merchants in this sub-region balance real-time fiscal compliance with centralized analytics capabilities.
Slovenia Point of Sale (POS) Terminal Market Competitive Landscape
Global majors compete with regional champions across certification velocity and fiscal protocol integration. The vendor base stratifies between integrated platform providers and hardware specialists. Three archetypes dominate: EU-certified firmware developers, hybrid cloud-on-premise configurators, and mobile-first hospitality specialists. Competitive moves concentrate on strategic partnerships with national fiscalization authorities and portfolio diversification toward software-defined payment architectures.
Among Ljubljana-based specialists, Quattro POS and SETCCE exemplify the firmware certification archetype. Datalab Tehnologije d.d. occupies a position representing hybrid cloud-on-premise configuration for Slovenian accounting standards. These domestic entities anchor the mid-market against inbound competition from Ingenico Group and NCR Corporation, whose scale-driven positions sit within the global integrated platform tier.
| Leading Market Players |
|---|
| Quattro POS |
| SETCCE |
| Datalab Tehnologije d.d. |
| Ingenico Group |
| Lab4Pay |
| Comtron |
| Positiva |
| NCR Corporation |
| Micro Team |
| Others |
Value Network & Pricing Analysis
PSD2-mandated EMV certification requirements are forcing Slovenian merchants toward pre-certified hardware bundles, compelling suppliers to absorb firmware validation costs and compressing margin structures for non-integrated vendors. This specification lock-in elevates pricing power for domestic firmware developers while squeezing pure hardware assemblers.
Pricing Analysis
Warranty and firmware update bundling separates premium-tier domestic providers from economy-tier importers in the Slovenian POS terminal market. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and after-sales service inclusion. Pricing pressure stems from EU REACH substance compliance costs, which extend procurement timelines for Asian-manufactured components. Retail grocery chains exhibit highest price sensitivity due to volume scale, while healthcare clinics prioritize encryption-grade certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Netherlands and Germany-based semiconductor foundries supplying secure encryption chipsets for EMV compliance. Slovenian assembly operations draw from Taiwanese component suppliers, German semiconductor foundries, and domestic firmware engineering bases. Raw material dependencies center on EU-sourced chipsets, REACH-compliant solder alloys, and certified thermal printer mechanisms. Tariff exposure on non-EU electronics creates procurement risk concentration. Distribution runs through Ljubljana-based system integrators with direct merchant relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Slovenia POS terminal market functions as a cost-of-compliance arena where national fiscalization protocols and PSD2 mandates erect substantial barriers to non-certified competitors. These regulatory moats protect incumbent firmware developers while filtering out undifferentiated hardware importers.
For Market Incumbents: Cement market position by deepening integration with Slovenian tax authority certification pipelines and acquiring embedded systems talent from Ljubljana's automotive sector. Threat from SoftPOS-enabled smartphones demands accelerated cloud-edge hybrid development. Vertical integration into firmware stack ownership is the critical defensive lever. For New Entrants and Emerging Players: Begin with self-service kiosk deployments in Maribor and Celje fuel retail corridors, the most penetrable white-space segment. Coastal hospitality mobile POS subscriptions offer recurring revenue entry with lower certification burden. Go-to-market angle should emphasize seasonal scalability for tourism-dependent operators. For Investors and Strategic Acquirers: The window for entry favors firmware-certified domestic specialists with established fiscalization authority relationships. Long-term viability hinges on software-defined payment architecture transition completion. Acquisition target archetype: hybrid cloud-on-premise configurators with Datalab accounting integration. Signal to watch: EU Digital Operational Resilience Act transposition timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Certification Pipeline Investment | Deepens moat against non-compliant importers by securing Slovenian tax authority pre-approval. |
| Hybrid Cloud-Edge Architecture Development | Captures mid-market merchants balancing real-time fiscal compliance with centralized analytics. |
| Self-Service Kiosk Geographic Expansion | Addresses underpenetrated fuel retail and quick-service food verticals in secondary cities. |
| SoftPOS Technology Partnership | Positions for smartphone-based payment convergence in Ljubljana boutique retail segments. |
| EU REACH Compliance Pre-Validation | Compresses procurement timelines by eliminating supplier qualification cycles for merchant buyers. |
Research Methodology
Document review covered EU regulatory filings, Slovenian tax authority certification databases, and semiconductor trade flow records, complemented by interviews with POS terminal procurement managers at retail grocery chains, hospitality technology directors in coastal zones, firmware engineering leads at Ljubljana-based developers, and fiscalization compliance officers. Secondary validation drew from EU REACH substance restriction updates, PSD2 implementation guidance, and payment processor API documentation. Bottom-up unit demand estimates triangulated against top-down merchant estate replacement cycle analysis.
Historical replacement cycle patterns cross-referenced against panel input from system integrators and merchant IT directors informed the analytical framework across the analysis window. Segmentation dimensions modeled include hardware form factor, payment authentication technology, end-use vertical, and deployment architecture. CAGR derivation incorporated firmware certification velocity constraints, coastal tourism seasonality patterns, and national fiscalization protocol evolution. Industry-specific inputs encompassed EMV Level 1 and Level 2 certification timelines and EU Digital Operational Resilience Act anticipation effects.
Regulatory enforcement timing shifts, semiconductor allocation shocks, and merchant consolidation waves are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding PSD2 transposition consistency and fiscalization authority certification throughput. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Taiwan Mobile Payments Market
Payments
Global Virtual Cards Market
Payments
Europe Credit Cards Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Malta POS Terminal Market
Payments
Mobile Payment Security Market
Payments
Money Transfer Agencies Market
Payments
New Zealand Payments Market
Payments
In Vehicles Payment Market
Payments
QR Codes Payment Market
Payments
India Gift Card and Incentive Card Market
Payments
Mobile Payment Data Protection Market
Payments
North America POS Terminal Market
Payments
Japan Credit Cards Market
Payments
Payment Security Software Market
Payments
Asia Pacific Mobile Wallet Market