
 Brazil Real Time Payments Market | 2026-2036
Brazil Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Real Time Payments Market Outlook
Merchant buyer concentration is rebalancing as micro-retailers and informal vendors fragment across Brazil's payment ecosystem, diluting historically bank-centric transaction flows. Nubank leverages its digital-native infrastructure to sustain low-friction onboarding for underbanked merchants. StoneCo anchors physical retail penetration through point-of-sale integration with PIX rails. PicPay competes on social payment features that capture peer-to-peer volume in dense urban corridors.
Brazil real time payments denote settlement systems that clear and credit funds within seconds through the PIX protocol, operating on ISO 20022 messaging standards with 24/7 availability and sub-10-second confirmation windows. These systems eliminate interbank float and reduce cash-handling costs for businesses dependent on immediate liquidity. Mobile payments and QR code payments represent the fastest-expanding method categories, driven by smartphone penetration and zero-fee PIX person-to-person transfers that habituate consumers toward digital settlement. Among end users, merchant adoption outpaces retail consumer growth as businesses seek to minimize card network interchange and accelerate working capital cycles.
Banco Central do Brasil governs PIX infrastructure through mandatory participation rules and fee caps that shape competitive dynamics for payment service providers. ANVISA oversight of health-sector payment flows and Brazil's LGPD data privacy framework constrain how transaction data monetizes across platforms. Stakeholders must monitor regulatory adjustments to PIX commercial pricing tiers and interoperability mandates that will determine margin sustainability for non-bank fintech operators.
Market Dynamics
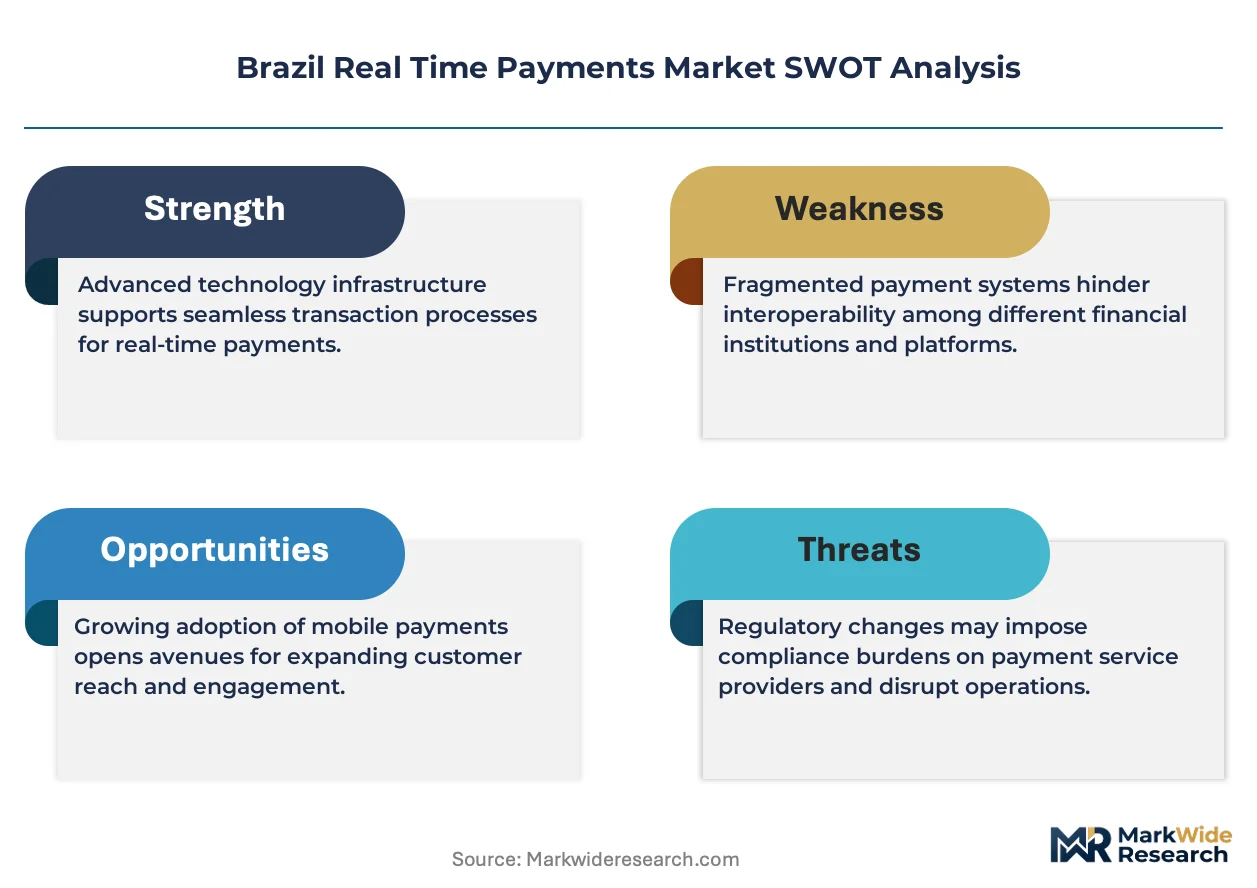
PIX universal interoperability mandates from Banco Central do Brasil are compressing settlement timelines and eroding traditional card network dominance across Brazil's payment infrastructure. This regulatory architecture forces payment service providers to compete on service differentiation rather than proprietary rails.
Growth Catalysts
- LGPD Data Framework:Brazil's data privacy law creates compliant pathways for transaction data monetization, enabling fintechs to build credit-scoring products atop PIX flows.
- QR Code Infrastructure:Zero-cost PIX person-to-person transfers habituate consumers toward mobile settlement, expanding merchant acceptance networks in informal retail corridors.
- Southeast Concentration:São Paulo and Rio de Janeiro retail density concentrates payment volume, allowing infrastructure providers to achieve network effects through geographic clustering.
Market Restraints
- Fee Compression:Banco Central do Brasil's commercial pricing caps constrain revenue per transaction for non-bank payment service providers operating on PIX rails.
- Smartphone Dependency:QR code and mobile-first PIX settlement excludes segments with limited device penetration, particularly in Brazil's rural Northeast and Amazon regions.
- Interbank Float Elimination:Instant settlement architecture removes overnight liquidity management opportunities that historically subsidized payment infrastructure investment.
Strategic Opportunities
- Northeast Expansion:Underpenetrated merchant networks in Recife, Fortaleza, and Salvador offer first-mover advantages for QR code onboarding in informal commerce.
- Cross-Border Settlement:ISO 20022 messaging standards enable future interoperability with Latin American real-time payment systems, creating regional corridor opportunities.
- Embedded Finance Convergence:PIX rails integrate with accounting software and inventory management platforms, enabling working capital advances tied to transaction history.
Industry Challenges
- Legacy Core Migration:Traditional banks face multi-year system overhauls to achieve sub-10-second confirmation windows mandated by PIX technical specifications.
- Fraud Detection Latency:Real-time settlement compresses transaction monitoring windows, requiring machine-learning infrastructure investments that strain mid-tier fintech balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Real Time Payments Market |
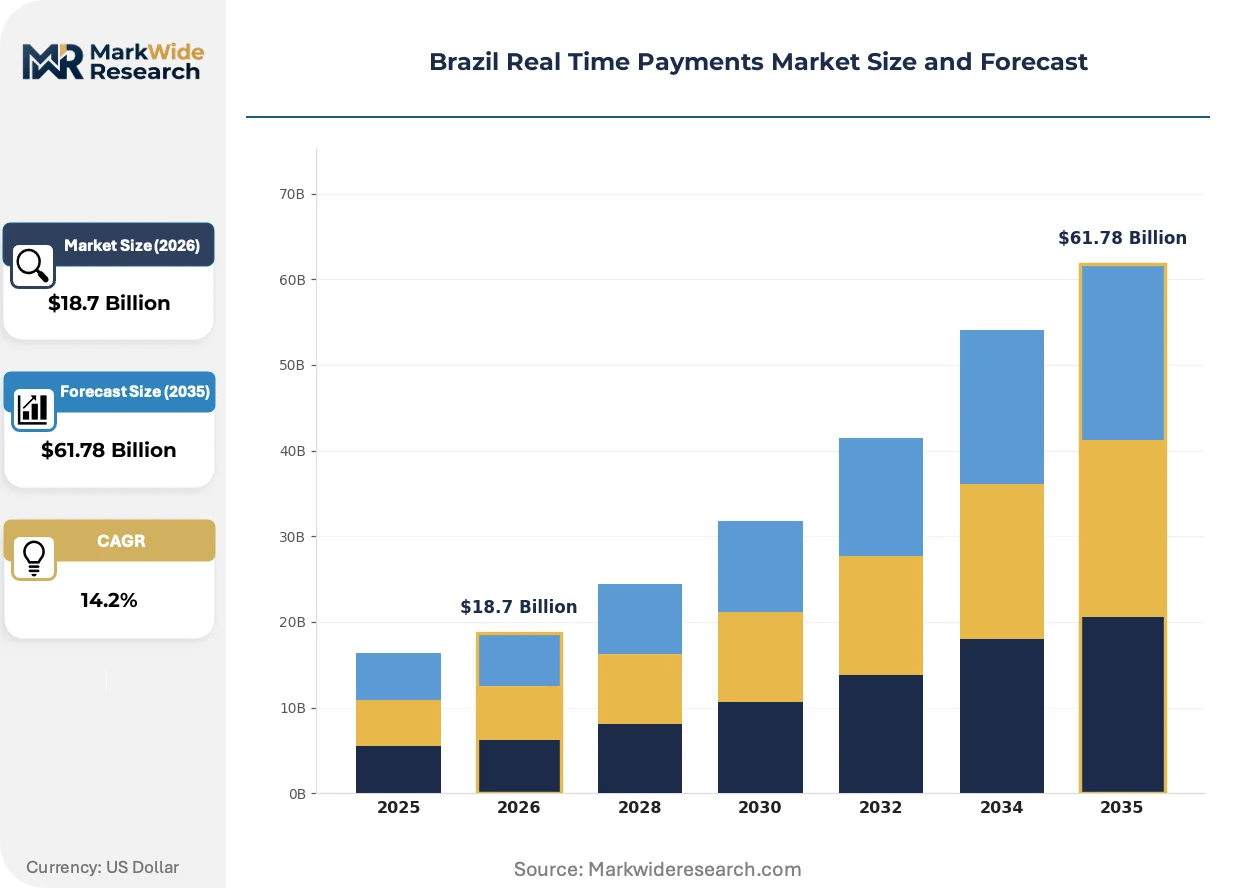
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Mobile Payments, Bank Transfers, QR Code Payments, Card Payments End User: Retail Consumers, Merchants, Corporates, Financial Institutions Transaction Type: Peer-to-Peer, Bill Payments, E-commerce Transactions, Remittances Technology: Blockchain, NFC, Instant Payment Platforms, API Integration |
| Companies Covered | Banco Central do Brasil, Nubank, PicPay, StoneCo, Inter, C6 Bank, Neon, PagBank, CloudWalk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Real Time Payments Market Strategic Shifts
Payment infrastructure in Brazil is fragmenting across specialized rails as merchants seek alternatives to card network economics. Three distinct vectors are reshaping competitive positioning and value capture mechanisms.
PIX instant settlement protocols are converging with open banking APIs to enable account-to-account payment initiation directly from merchant checkout flows. E-commerce platforms and utility billing systems are adopting this architecture to bypass card network interchange entirely. The structural consequence is a compression in payment aggregator margins as direct bank integration becomes technically accessible.
Banco Central do Brasil's evolving commercial pricing tier regulations are forcing payment service providers to rebalance revenue models toward value-added services. The industrial consequence is accelerated investment in credit, insurance, and software products bundled atop transaction processing. Mid-tier fintech aggregators in Brazil's Southeast region are most affected, pivoting from transaction volume growth toward merchant lifetime value optimization.
Merchant procurement of payment acceptance is fragmenting across specialized providers rather than consolidating with universal banks. Small retailers in dense urban corridors are selecting niche acquirers based on settlement speed and software integration depth. This pattern is most visible among street vendors and micro-merchants in São Paulo's peripheral commercial districts, where cash displacement is nearing completion.
Brazil Real Time Payments Market Segmentation
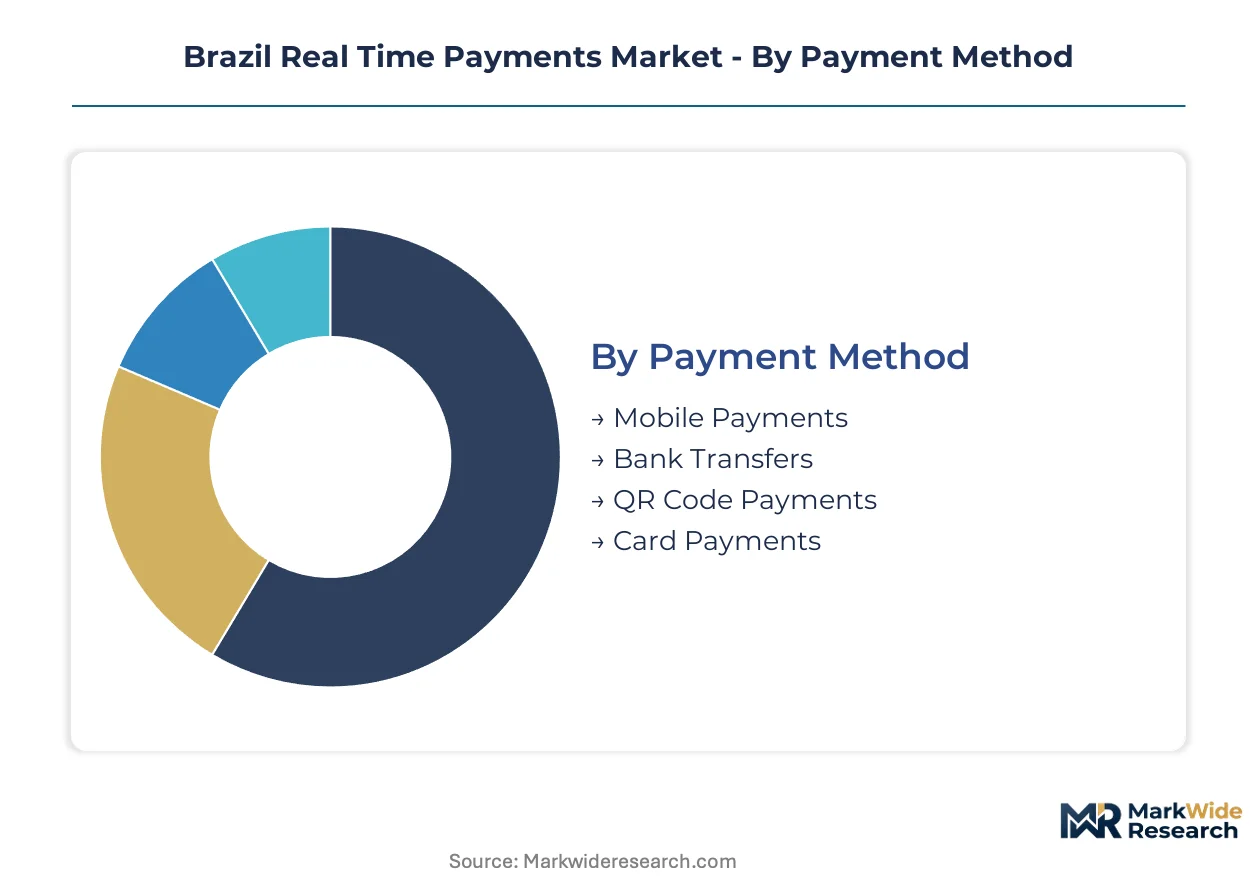
PIX infrastructure specifications from Banco Central do Brasil create distinct technical requirements across settlement modalities. Each segmentation axis reveals where payment service providers concentrate investment and where regulatory mandates shape competitive boundaries.
Payment Method:
Technical architecture determines which rails capture volume in Brazil's dense urban corridors versus dispersed rural networks.
- Mobile Payments:Smartphone-native settlement dominates São Paulo and Rio de Janeiro retail corridors where PIX-enabled apps displace cash transactions. QR code generation and camera-based initiation compress onboarding friction for underbanked merchants in peripheral commercial districts.
- QR Code Payments:Static and dynamic QR standards enable zero-cost acceptance for micro-retailers without point-of-sale hardware. Merchant adoption concentrates in informal commerce clusters where interchange elimination provides immediate margin relief.
- Bank Transfers:Account-to-account settlement through internet banking portals serves corporate treasury operations and high-value B2B flows.
- Card Payments:Debit and credit rails retain volume in segments requiring chargeback protection or installment financing unavailable through PIX.
Mature deployment sits with card payments. Newer deployment is concentrated in QR code infrastructure.
End User:
Customer type dictates service-level requirements and monetization pathways across Brazil's payment ecosystem.
- Merchants:Working capital acceleration drives adoption among São Paulo street vendors and Rio de Janeiro neighborhood retailers seeking same-day settlement. Software integration demands from accounting platforms reshape acquirer selection criteria.
- Retail Consumers:Peer-to-peer habituation through zero-fee PIX transfers builds daily-use patterns that migrate toward merchant payments. Smartphone penetration gaps in Brazil's Northeast and Amazon regions constrain addressable population.
- Corporates:Treasury automation and supplier payment rationalization concentrate demand among Southeast region headquarters operations.
- Financial Institutions:Infrastructure participation mandates from Banco Central do Brasil require core system upgrades for universal PIX interoperability.
Volume concentration rests with retail consumers. Revenue margin expansion targets corporate segments.
Transaction Type:
Use case specifications determine confirmation speed requirements and fraud tolerance thresholds.
- Bill Payments:Utility and tax settlement through PIX QR codes eliminates paper voucher processing for Brazilian municipalities and state-owned enterprises. São Paulo metropolitan utility providers anchor volume concentration.
- E-commerce Transactions:Checkout integration demands sub-10-second confirmation windows that compress cart abandonment rates. Southeast region e-commerce platforms drive technical specification evolution.
- Peer-to-Peer:Social payment features capture dense urban corridor volume through contact-based initiation.
- Remittances:Cross-border corridor development awaits ISO 20022 interoperability with Latin American real-time systems.
Bill payments anchor current infrastructure load. E-commerce transactions are climbing the fastest.
Technology:
Stack selection determines compliance posture and partnership requirements with Banco Central do Brasil infrastructure.
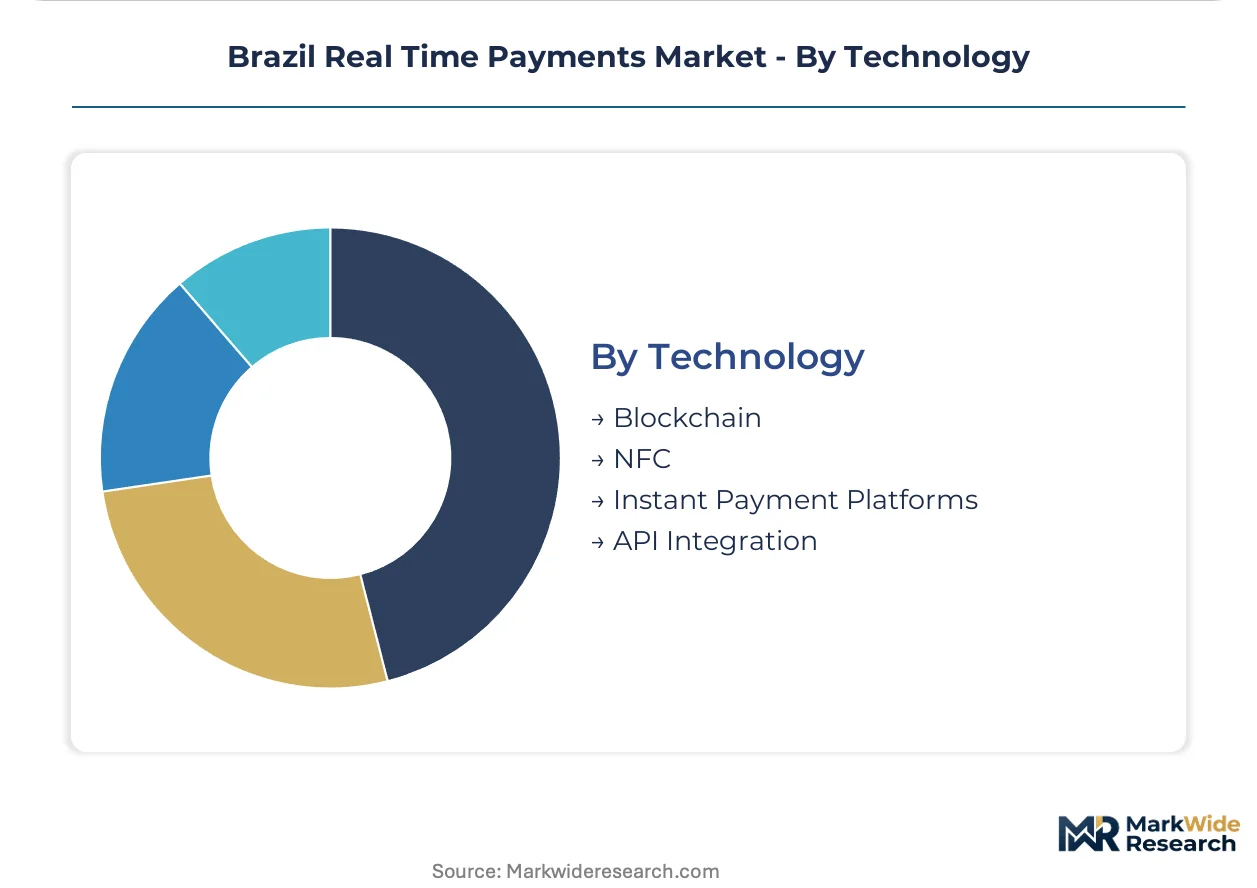
- Instant Payment Platforms:PIX protocol implementation on ISO 20022 messaging standards enables 24/7 settlement with sub-10-second confirmation. Southeast region fintech aggregators concentrate platform development investment.
- API Integration:Open banking connectivity allows direct account initiation from merchant checkout flows, bypassing traditional aggregator layers. E-commerce platform adoption accelerates in São Paulo and Rio de Janeiro.
- NFC:Contactless proximity settlement retains relevance for transit and closed-loop campus environments.
- Blockchain:Distributed ledger exploration remains peripheral to central bank-governed settlement architecture.
API integration is gaining share fastest. Blockchain deployment remains experimental.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PIX transaction density concentrates in Brazil's Southeast corridor, where São Paulo and Rio de Janeiro metropolitan areas generate disproportionate payment volume. Merchant adoption rates diverge sharply between coastal urban centers and interior states, creating distinct infrastructure investment priorities across sub-regional markets.
São Paulo
Street vendors and micro-retailers in São Paulo's peripheral commercial districts drive QR code onboarding volume, displacing cash transactions at accelerating rates. Banco Central do Brasil's universal interoperability mandates enable fintech aggregators to serve underbanked merchants without proprietary rail investments. The São Paulo metropolitan utility providers anchor bill payment infrastructure load, processing municipal tax and service settlements through PIX-enabled platforms.
Rio de Janeiro
Neighborhood retailers in Rio de Janeiro seek same-day settlement acceleration to optimize working capital cycles amid seasonal revenue fluctuations. ANVISA oversight of health-sector payment flows shapes how pharmaceutical distributors and clinic networks structure supplier settlements. Dense urban corridors in Rio's Zona Sul and Centro districts concentrate peer-to-peer social payment volume through contact-based initiation features.
Minas Gerais
Corporate treasury operations in Belo Horizonte headquarters rationalize supplier payments through instant settlement protocols, reducing interbank float exposure. The country's central bank mandates ISO 20022 messaging standards that enable B2B transaction automation for mining and manufacturing conglomerates. Industrial clusters in the state's metal-mechanical sector pilot embedded finance convergence with inventory management platforms.
Rio Grande do Sul
Agricultural commodity traders in Porto Alegre corridor leverage real-time settlement for spot market transactions requiring immediate liquidity confirmation. LGPD data privacy frameworks constrain how transaction histories monetize into credit-scoring products for rural cooperatives. Meatpacking and grain processing clusters in the state's northern production zones test cross-border settlement interoperability with Mercosur partners.
Bahia
Informal commerce networks in Salvador's historic center and peripheral markets present first-mover opportunities for QR code merchant onboarding. Smartphone penetration gaps in rural interior municipalities constrain addressable population for mobile-first settlement architectures. State-owned enterprises and municipal governments in the Northeast region pilot utility billing integration to reduce paper voucher processing costs.
Brazil Real Time Payments Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue embedded finance and software integration vectors to differentiate beyond transaction processing. The vendor base stratifies across three maturity tiers: universal banks with legacy infrastructure, digital-native fintechs with API-first architectures, and specialized acquirers with vertical software depth. Dominant competitive moves include strategic partnerships with accounting platforms and geographic expansion into underpenetrated interior states.
Within the digital-native tier, Nubank and PicPay exemplify low-friction onboarding strategies for underbanked merchant segments. StoneCo anchors physical retail penetration through point-of-sale integration with PIX rails. Among challenger banks, C6 Bank and Inter occupy positions emphasizing treasury automation and working capital products bundled atop transaction processing.
| Leading Market Players |
|---|
| Banco Central do Brasil |
| Nubank |
| PicPay |
| StoneCo |
| Inter |
| C6 Bank |
| Neon |
| PagBank |
| CloudWalk |
| Others |
Value Chain & Pricing Dynamics
Merchant procurement preferences for zero-fee settlement and instant liquidity confirmation are forcing payment service providers to absorb infrastructure costs while competing on software value-adds, compressing transaction margins and reshaping supplier economics across Brazil's payment ecosystem.
Pricing Analysis
Volume concentration among micro-merchants in São Paulo and Rio de Janeiro runs counter to margin expansion, as Banco Central do Brasil's fee caps on PIX commercial transactions eliminate traditional interchange revenue pools. Three-tier pricing structure across premium API integration, standard aggregator services, and economy QR-only acceptance segments reflects software depth and settlement speed differentiation. Cost compression in the economy tier is intensifying because fintech aggregators compete for street vendor onboarding with subsidized hardware. Corporate treasury clients in Belo Horizonte and Porto Alegre show least price sensitivity, prioritizing working capital automation over per-transaction cost.
Supply Chain Analysis
Logistics and freight costs for point-of-sale hardware and smartphone distribution concentrate supplier power among Southeast region electronics distributors serving São Paulo-based fintech aggregators. Core PIX infrastructure draws from Banco Central do Brasil's centralized settlement architecture, while API middleware and fraud detection layers rest on cloud computing resources anchored in São Paulo and Rio de Janeiro data centers. Single-source vulnerability sits with smartphone penetration gaps in Brazil's Northeast interior, constraining addressable merchant networks. Distribution runs through direct digital onboarding for software-only services, with physical retail corridors requiring localized acquirer partnerships for QR code deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Banco Central do Brasil's LGPD data privacy framework and PIX interoperability mandates create a cost-of-compliance moat that favors established players with dedicated regulatory affairs infrastructure and penalizes undercapitalized entrants lacking legal-technical integration capabilities.
For Market Incumbents: Anchor market position through backward integration into fraud detection machine-learning infrastructure, addressing real-time settlement monitoring gaps that strain mid-tier fintech balance sheets. Deepen software integration partnerships with accounting platforms and inventory management systems to capture merchant lifetime value beyond transaction processing, defending against open banking API disintermediation that bypasses traditional aggregator layers. For New Entrants and Emerging Players: QR code merchant onboarding in Salvador, Recife, and Fortaleza informal commerce corridors offers lowest competitive density and highest cash displacement potential among underbanked micro-retailers. Embedded finance convergence with agricultural cooperatives in Rio Grande do Sul and Bahia presents white-space opportunity for working capital advances tied to transaction history. API-first architecture enabling direct bank integration from merchant checkout flows provides the most penetrable technical wedge against incumbent aggregator models. For Investors and Strategic Acquirers: The window for entry favors digital-native fintechs with ISO 20022 messaging compliance and existing Banco Central do Brasil infrastructure participation certificates, as legacy bank core migration timelines extend competitive vulnerability. Acquisition targets should demonstrate Southeast region network effects with clear pathways to Northeast expansion. Monitor Banco Central do Brasil commercial pricing tier adjustments as the critical inflection signal for margin sustainability across non-bank payment service providers.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Partnership | Direct bank connectivity from merchant checkout flows bypasses card network interchange entirely. |
| Fraud Detection Infrastructure Investment | Machine-learning layers address real-time monitoring compression mandated by PIX settlement speeds. |
| Northeast Geographic Expansion | First-mover QR code onboarding in Salvador and Recife captures underpenetrated informal commerce. |
| Embedded Finance Product Launch | Working capital advances tied to PIX transaction history monetize merchant data within LGPD bounds. |
| Accounting Software Integration | Inventory management platform partnerships lock in merchant switching costs beyond transaction pricing. |
Study Parameters
Independent corroboration across primary interviews with payment platform executives, regulatory affairs specialists at Banco Central do Brasil, merchant acquiring operations managers, and fintech product directors underwrites the qualitative findings. Secondary validation draws from Banco Central do Brasil PIX transaction disclosures, ANVISA health-sector payment flow regulations, SEC filings for listed payment service providers, and LGPD compliance documentation. Bottom-up merchant adoption modeling and top-down payment volume aggregation triangulate market size estimates across the analysis window.
Comparable-period anchoring to historical PIX deployment phases from initial launch through universal interoperability mandates structures the forecast framework. Segmentation dimensions modeled include payment method, end user type, transaction category, and technology stack deployment, with regional adoption patterns across Brazil's Southeast, South, and Northeast corridors. CAGRs derive from trend extrapolation of merchant onboarding velocity and consumer habituation curves, incorporating smartphone penetration trajectories and Banco Central do Brasil infrastructure investment schedules as key inputs.
Inputs from Banco Central do Brasil statistical releases and fintech regulatory filings were available through the study window; gaps in informal sector transaction reporting and cash displacement velocity in peripheral commercial districts introduce uncertainty bands around merchant adoption forecasts. Stakeholders should weight assumptions against their own operating context and monitor regulatory adjustments to PIX commercial pricing tiers as potential forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Prepaid Cards Market
Payments
Poland POS Terminal Market
Payments
Germany Payments Market
Payments
B2B Payments Market
Payments
Transaction Monitoring Market
Payments
Retail Point of Sale (POS) Market
Payments
United Arab Emirates Payment Market
Payments
Denmark POS Terminals Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Electronic Payment Processing Software Market
Payments
Biometric Payment Market
Payments
Digital Money Transfer Market
Payments
Convergent Billing Market
Payments
GCC Payment Gateway Market
Payments
Electronic Cash Register Market
Payments
Singapore Remittance Market