
 Payment Card Market | 2026-2036
Payment Card Market Size, Share, and Industry Trends Forecast 2026-2036
Payment Card Market Outlook
Card-plus-wallet bundling is pivoting toward modular API-based issuance where issuers unbundle rewards, credit, and payment rails for fintech partners. Visa Inc. leverages its network tokenization infrastructure to sustain issuer loyalty across multiple digital wallet integrations. Mastercard Inc. anchors its growth through biometric card certification programs that differentiate physical products in European markets. American Express Company specializes in premium customer segments where annual fee structures compete on concierge and travel benefits rather than interchange alone.
A payment card is a physical or digital instrument issued by a financial institution that encodes account credentials via magnetic stripe, EMV chip, or tokenized credential for authorization through card association networks. These instruments facilitate consumer and commercial transactions by transmitting encrypted data to acquiring banks for settlement through centralized clearing systems. Debit cards dominate transaction volume globally due to direct account linkage and lower issuer risk exposure, while prepaid cards represent the fastest-growing category among underbanked populations and corporate disbursement programs. Cross-border payment functionality commands premium interchange structures as currency conversion and compliance costs concentrate margin pools with network operators.
PCI DSS standards govern data security architecture for all card-accepting entities, while the EU's PSD2 framework mandates strong customer authentication for electronic transactions across European markets. The US Federal Reserve's Regulation II caps debit interchange rates, directly constraining issuer revenue models and redirecting product development toward credit and prepaid alternatives. Stakeholders must monitor central bank digital currency pilots in major economies, as programmable money infrastructure could displace traditional card rails for government benefit distribution and retail settlement.
Market Dynamics
Network tokenization infrastructure is fragmenting issuer-processor relationships as financial institutions unbundle legacy card manufacturing and personalization services into API-accessible components.
Growth Catalysts
- EMV chip mandates:Brazil's national banking regulator accelerates contactless card issuance standards, forcing acquirers to upgrade terminal infrastructure nationwide.
- Digital wallet interoperability:Southeast Asian e-commerce platforms integrate card-based checkout rails as regional payment schemes enable cross-wallet credential sharing.
- Biometric certification:European markets adopt fingerprint-authenticated cards for high-value transaction segments, differentiating physical products against mobile-only alternatives.
Market Restraints
- Regulatory friction:The US Federal Reserve's Regulation II caps debit interchange rates, compressing issuer margins and redirecting product development toward credit alternatives.
- Supply concentration:EMV chip fabrication concentrates among three semiconductor foundries, exposing card manufacturers to allocation constraints during demand surges.
- Substitution threat:Central bank digital currency pilots in major economies threaten to displace traditional card rails for government benefit distribution and retail settlement.
Strategic Opportunities
- Underpenetrated rural corridors:India's contactless infrastructure deployment concentrates in urban retail clusters, leaving tier-2 and tier-3 cities as expansion targets for terminal deployment.
- Corporate disbursement programs:Prepaid card categories capture payroll and expense management flows from underbanked workforce segments across emerging markets.
- Technology convergence:Network tokenization merges with real-time payment rails, enabling credential portability across closed-loop wallet ecosystems.
Industry Challenges
- PCI DSS compliance timelines:Card-accepting entities face 18-month recertification cycles for data security architecture audits, delaying product launches.
- Legacy system integration:Core banking platforms require middleware development to support modular API-based issuance, stretching IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payment Card Market |
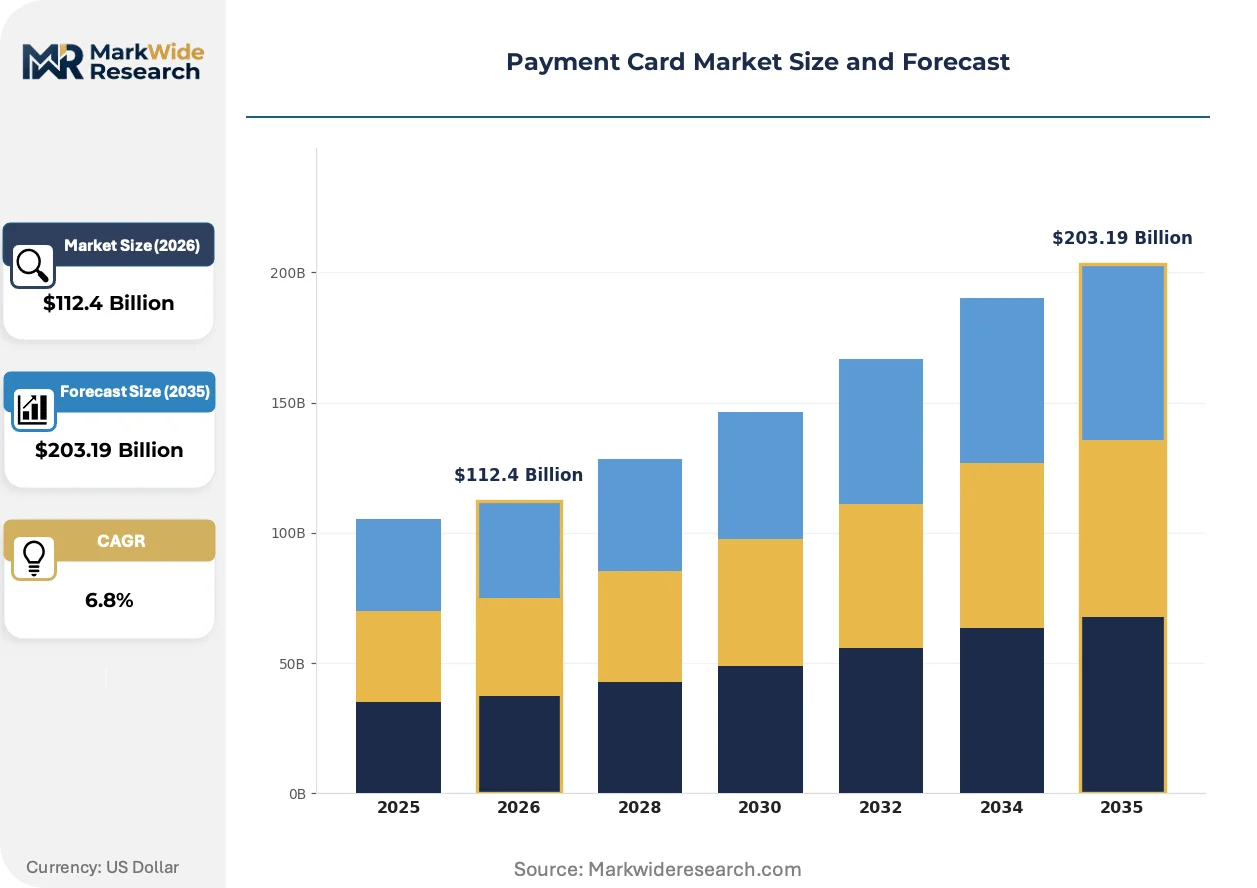
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Credit Card, Debit Card, Prepaid Card, Charge Card Customer Segment: Individuals, Small Businesses, Corporates, Non-Profit Organizations Transaction Type: Online Transactions, In-store Purchases, Recurring Payments, Cross-border Payments Service Provider: Visa, MasterCard, American Express, Discover |
| Companies Covered | Visa Inc., Mastercard Inc., JPMorgan Chase & Co., Fiserv, FIS (Worldpay), American Express Company, PayPal Holdings Inc., Global Payments Inc., Block (Square), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payment Card Market Strategic Shifts
Payment credential architecture is unbundling into discrete, interoperable services that separate authentication, authorization, and settlement functions across competing technology stacks.
Network tokenization is modularizing card credential management by replacing static primary account numbers with dynamic, merchant-specific tokens. Major issuers in North America and Europe are migrating 60% of card-not-present volume to tokenized rails within 24 months of implementation. This shift is modularizing fraud liability structures and enabling credential portability across digital wallet providers without reissuing physical plastics.
PSD2 strong customer authentication mandates across European markets require two-factor verification for electronic transactions exceeding threshold limits. Acquiring banks must upgrade 3-D Secure protocols to support biometric and device-bound authentication methods. Premium card segments in France and Germany absorb compliance costs through annual fee structures rather than interchange compression.
Corporate treasury departments now demand virtual card issuance with spend controls and real-time reconciliation APIs, displacing traditional purchasing card programs. Travel and expense management platforms in the United Kingdom and Singapore embed these capabilities as native features. Procurement patterns favor issuers offering granular merchant category blocking and dynamic limit adjustments over static credit products.
Payment Card Market Segmentation
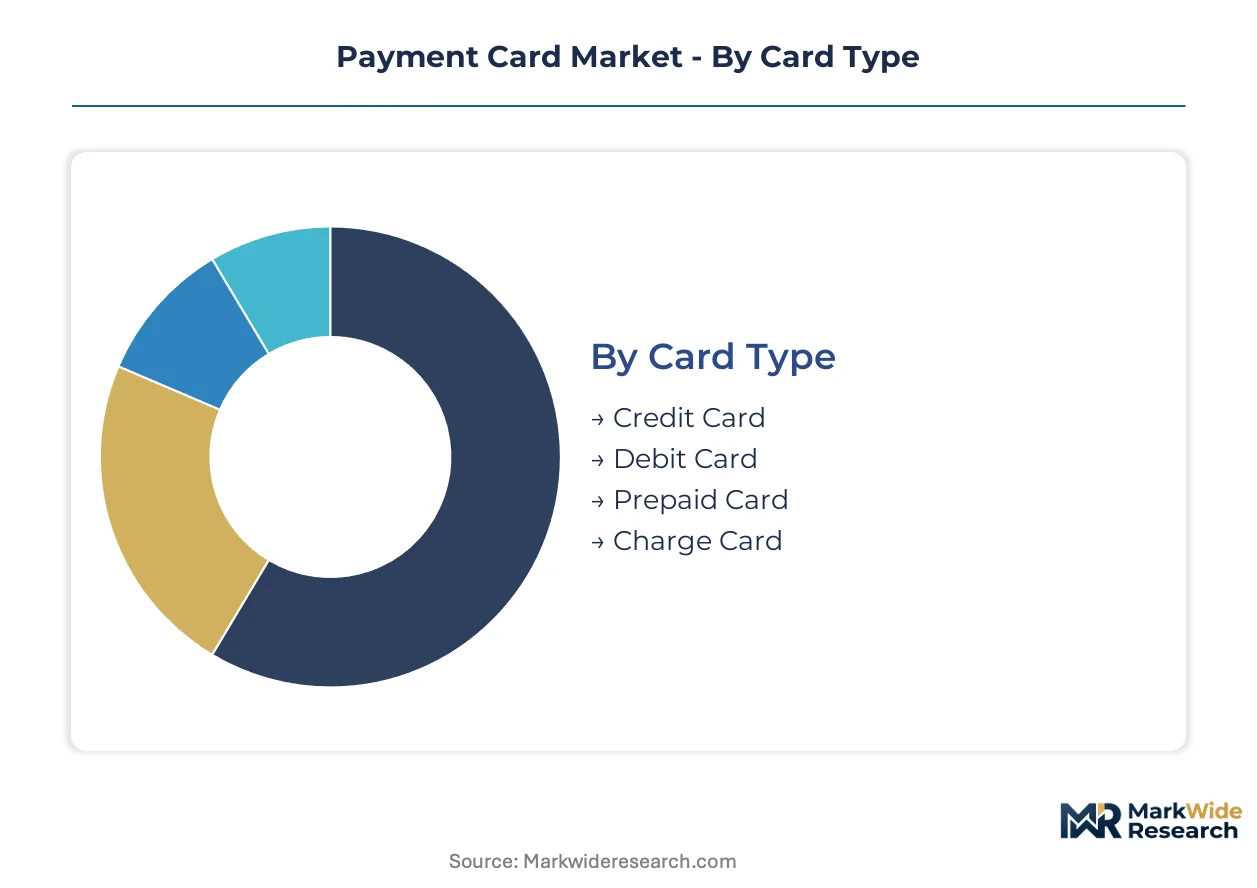
Payment card segmentation reveals how credential architecture, customer risk profiles, and transaction rails intersect to determine issuer economics. Network operators and financial institutions calibrate product design across these dimensions to optimize interchange yield and fraud exposure.
Card Type:
Technology specifications differentiate credential security architecture and liability structures across issuance categories.
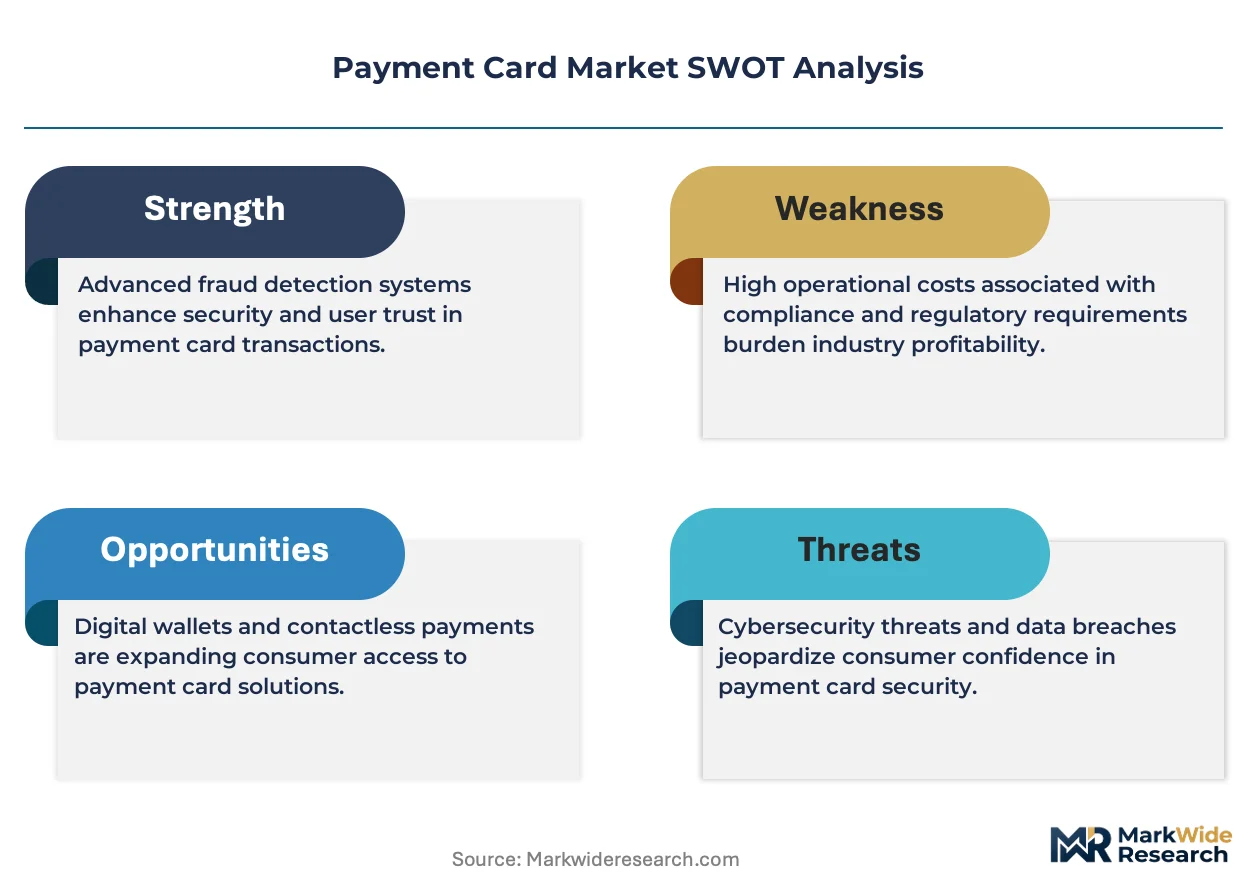
- Credit Card:Revolving credit instruments carry higher interchange rates due to issuer risk absorption and fraud liability. Demand concentrates among premium customer segments in urban corridors where rewards optimization drives product selection.
- Debit Card:Direct account linkage enables real-time settlement with lower issuer risk exposure. Volume dominance persists across retail payment corridors in India and Brazil where contactless infrastructure deployment accelerates.
- Prepaid Card:Stored-value credentials serve underbanked populations and corporate disbursement programs with defined spend controls. Payroll and expense management flows in Southeast Asian emerging markets favor this structure.
- Charge Card:Balance-in-full requirements concentrate among high-net-worth segments where annual fee structures subsidize concierge and travel benefits rather than interchange revenue alone.
Mature deployment sits with Debit Card. Newer deployment is concentrated in Prepaid Card.
Customer Segment:
Cost tier differentiation shapes product economics as issuer risk models and service levels scale across entity types.
- Individuals:Mass-market issuance dominates transaction volume through standardized credit and debit products. Brazil's EMV chip mandates accelerate contactless migration across this segment.
- Small Businesses:Commercial card programs combine expense tracking with revolving credit facilities. Demand clusters among service-sector enterprises in European markets seeking granular spend controls.
- Corporates:Virtual card issuance with real-time reconciliation APIs displaces traditional purchasing card programs. Treasury departments in the United Kingdom and Singapore embed these capabilities into travel and expense platforms.
- Non-Profit Organizations:Specialized disbursement credentials manage donor-restricted funds with audit-trail requirements. Grant distribution programs favor prepaid structures with merchant category blocking.
Revenue concentration anchors with Individuals. Steepest expansion trajectory emerges in Corporates.
Transaction Type:
Application context determines authentication protocols and interchange structures as digital and physical rails diverge.
- Online Transactions:Card-not-present volume migrates to tokenized rails for fraud liability reduction. Network tokenization infrastructure enables credential portability across wallet providers without physical reissuance.
- In-store Purchases:EMV chip and contactless protocols dominate physical terminal infrastructure. India's urban retail corridors outpace rural penetration for tap-to-pay deployment.
- Recurring Payments:Subscription billing models favor stored credentials with account updater services. Merchant demand concentrates in SaaS and media streaming verticals.
- Cross-border Payments:Currency conversion functionality commands premium interchange rates. Compliance costs and FX margin pools concentrate with network operators.
Volume leadership rests with In-store Purchases. Gaining share fastest is Online Transactions.
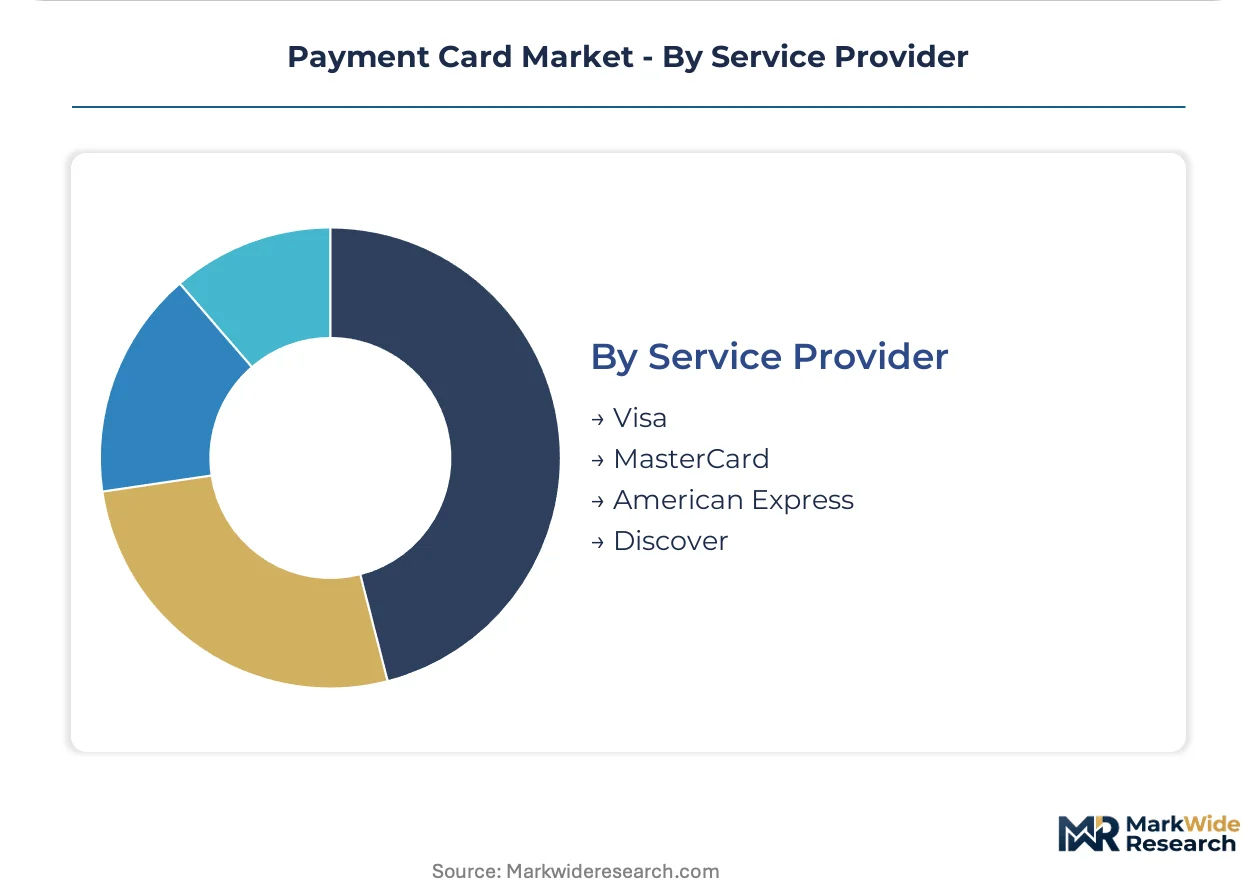
Service Provider:
Network scale and certification programs differentiate competitive positioning across association tiers.
- Visa:Network tokenization infrastructure sustains issuer loyalty across multiple digital wallet integrations. API-based credential management dominates North American and European migration paths.
- MasterCard:Biometric card certification programs differentiate physical products in European markets. Fingerprint-authenticated credentials target high-value transaction segments.
- American Express:Closed-loop network and premium positioning compete on concierge and travel benefits. Annual fee structures absorb compliance costs in France and Germany.
- Discover:Domestic concentration in the United States with expanding international acceptance through network partnerships. Issuer-processor relationships emphasize mid-market financial institutions.
Incumbent scale favors Visa. Competitive intensity is climbing fastest around MasterCard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Card manufacturing concentrates in Asian semiconductor foundries while consumption clusters in North American and European retail corridors. Brazil and India represent the fastest-growing issuance markets as EMV migration accelerates. Network tokenization infrastructure deployment favors developed economies with mature digital wallet ecosystems.
United States
Debit interchange compression under Federal Reserve Regulation II redirects issuer product development toward credit and prepaid alternatives. The country's central bank maintains strict caps on signature debit network fees. New York and San Francisco financial corridors drive virtual card adoption for corporate treasury departments seeking real-time reconciliation APIs.
Brazil
EMV chip mandates from the national banking regulator force terminal infrastructure upgrades across retail payment corridors. Contactless issuance standards accelerate as acquirers modernize hardware nationwide. São Paulo anchors issuance volume while Rio de Janeiro corridors concentrate premium credit segment demand.
India
RBI guidelines on contactless transaction limits and tokenization frameworks reshape credential architecture across urban retail clusters. The central bank's push for digital payments concentrates infrastructure deployment in Delhi-Mumbai-Bangalore corridors. Tier-2 and tier-3 cities remain underpenetrated for terminal deployment despite urban acceleration.
Germany
PSD2 strong customer authentication mandates require two-factor verification for electronic transactions above threshold limits. The EU framework drives 3-D Secure protocol upgrades across acquiring banks. Frankfurt and Munich industrial clusters absorb compliance costs through premium annual fee structures rather than interchange compression.
United Kingdom
FCA oversight of payment services and Open Banking standards reshape credential portability across digital wallet providers. The regulatory framework enables network tokenization migration for card-not-present volume. London's fintech corridor drives corporate virtual card issuance with embedded spend controls for travel and expense platforms.
Payment Card Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across network, processing, and issuance layers. The market structure fragments across four distinct tiers: global card networks, integrated payment processors, bank-owned issuers, and fintech-native platforms. Strategic archetypes include network-scale operators leveraging tokenization infrastructure, processor-issuer hybrids unbundling legacy services, and platform-native entrants embedding payment credentials into commerce ecosystems. Dominant competitive moves center on API-based modularization of card manufacturing and geographic expansion through local partnership structures.
Among network-scale operators, Visa Inc. and Mastercard Inc. occupy positions as archetypal infrastructure providers, with American Express Company representing the closed-loop premium segment. These entities exemplify divergent strategic positioning—open-loop network scale versus closed-loop customer captivity—while JPMorgan Chase & Co. anchors the bank-issuer tier through integrated consumer and commercial card programs.
| Leading Market Players |
|---|
| Visa Inc. |
| Mastercard Inc. |
| JPMorgan Chase & Co. |
| Fiserv |
| FIS (Worldpay) |
| American Express Company |
| PayPal Holdings Inc. |
| Global Payments Inc. |
| Block (Square) |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot indices cascade through EMV chip fabrication tiers into differentiated pricing for contactless credentials across Brazil, India, and European markets. Foundry allocation constraints concentrate margin pressure on card manufacturers while terminal infrastructure upgrades absorb downstream cost volatility.
Pricing Analysis
Margin tightening in standard debit issuance reflects Federal Reserve Regulation II rate caps compressing issuer yields. Three-tier pricing structure across premium, standard, and economy levels differentiates biometric-certified cards from basic EMV products. Cost-down pressure on prepaid categories accelerates because corporate disbursement programs demand API-based issuance at volume scale. Small business segments exhibit highest price sensitivity while charge card holders absorb annual fees without interchange-driven product switching.
Supply Chain Analysis
Freight cost volatility from Asian semiconductor hubs to Brazilian and Indian personalization centers strains just-in-time card delivery schedules. EMV chip fabrication concentrates in Taiwan, South Korea, and China, drawing from silicon wafers, gold wire bonding materials, and polycarbonate substrates. Single-source vulnerability in advanced node semiconductor allocation exposes manufacturers to foundry prioritization shifts. Distribution runs through regional personalization bureaus that embed credential data before last-mile fulfillment to issuing banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over tokenization infrastructure and EMV chip supply anchors competitive durability. Players pursue backward integration into semiconductor sourcing and forward integration into digital wallet credential management.
For Market Incumbents: Anchor network loyalty through exclusive tokenization API partnerships that lock issuers into proprietary rails. Deepen fraud liability protections for card-not-present volume to defend against real-time payment substitution. Acquire biometric certification capabilities in European markets before regulatory mandates harden competitive moats. For New Entrants and Emerging Players: Modular API-based issuance platforms offer the most penetrable wedge for fintech-native market entry. Target India's tier-2 and tier-3 cities where terminal infrastructure gaps exceed incumbent deployment capacity. Embed spend-control features as native capabilities rather than bolt-on services to differentiate corporate virtual card offerings. For Investors and Strategic Acquirers: Distressed-cycle entries favor processor-issuer hybrids with captive EMV chip allocation agreements in Asian foundries. Long-term viability hinges on credential portability across closed-loop wallet ecosystems rather than physical card volume. Monitor central bank digital currency pilot expansions as the critical inflection signal for traditional rail displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Network Tokenization Infrastructure Deployment | Visa's API ecosystem locks issuer loyalty across multiple digital wallet integrations in North America. |
| Biometric Card Certification Investment | Mastercard's fingerprint-authenticated programs differentiate physical products in high-value European segments. |
| Modular Issuance Platform Development | Unbundled rewards and payment rails enable fintech partnership velocity without core banking overhaul. |
| Corporate Virtual Card API Integration | Real-time reconciliation capabilities displace traditional purchasing cards in UK and Singapore treasury departments. |
| Contactless Terminal Infrastructure Expansion | India's urban retail corridors outpace rural penetration, creating tier-2 and tier-3 deployment opportunities. |
Study Parameters
Multi-period observation of EMV migration timelines, tokenization adoption curves, and interchange rate regulatory shifts anchored the trend analysis, supplemented by interviews with payment network strategists, issuer product executives, merchant acquiring heads, and central bank policy officers. Secondary validation drew from SEC 10-K filings, RBI payment system reports, Federal Reserve regulatory notices, and EMVCo specification releases. Bottom-up card volume projections triangulated against top-down network operator revenue disclosures.
Segment-weighting across card type, customer segment, transaction type, and service provider dimensions calibrated the analytical framework throughout the forecast period. CAGRs derived from historical issuance velocity adjusted for regulatory intervention effects and technology substitution curves. Industry-specific inputs included EMV terminal deployment databases, digital wallet credential sharing agreements, and central bank digital currency pilot scope announcements.
Several conditions sit outside the modeled scope, including unannounced semiconductor foundry allocation decisions, abrupt interchange rate regulatory revisions, and sovereign digital currency launch timelines. Forecasts reflect documented assumptions about wallet interoperability progression and contactless infrastructure penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Korea Real Time Payments Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
Europe Payment Analytics Software Market
Payments
Direct Carrier Billing Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
B2B Payments Market
Payments
China Payments Market
Payments
Belgium Payments Market
Payments
United Kingdom Payment Market
Payments
Bulgaria POS Terminals Market
Payments
Global Utility Billing Software Market
Payments
Norway Mobile Payments Market
Payments
United Arab Emirates Real Time Payments Market
Payments
India Payments Market
Payments
In-Vehicle Payment Services Market