
 Wireless Breast Pump Market | 2026-2036
Wireless Breast Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Breast Pump Market Outlook
Southeast Asian contract manufacturing is reconfiguring supply availability for wearable pump components. Momcozy leverages vertically integrated silicone molding operations to control unit costs. Willow differentiates through proprietary suction algorithms that reduce noise output. Medela AG anchors European quality certification pathways that shape premium positioning.
A wireless breast pump is a battery-powered, hands-free lactation device employing motorized suction through soft silicone breast shields to express milk without tethered tubing or wall outlets. Motor torque, vacuum pressure range measured in millimeters of mercury, and noise decibel ratings determine clinical efficacy and user comfort thresholds. Double electric configurations capture the dominant revenue share as working mothers prioritize expression efficiency during limited break windows. App connectivity segments are expanding fastest as firmware-enabled suction customization and milk volume tracking convert first-time buyers to subscription-anchored ecosystems. Hospital-grade units occupy narrow but defensible margin pools through durable motor assemblies and rental program structures.
FDA 510(k) clearance pathways govern device safety claims and electromagnetic compatibility standards for wireless breast pumps sold in the United States. The EU Medical Device Regulation imposes clinical evidence requirements and post-market surveillance obligations that filter smaller competitors from European distribution. Health Canada and the Therapeutic Goods Administration maintain aligned but distinct approval frameworks that shape staggered launch timelines across North American and Australasian markets. Stakeholders must monitor evolving reimbursement code definitions that determine whether wireless pumps qualify for insurance coverage versus out-of-pocket purchase.
Market Dynamics
Bluetooth-enabled firmware customization is compressing product lifecycles as suction algorithm patents become the primary competitive moat, forcing engineering resources toward app ecosystem development rather than hardware iteration alone.
Growth Catalysts
- PUMP Act enforcement:US workplace lactation accommodation mandates now cover salaried and hourly employees equally, expanding reimbursable device procurement through employer-sponsored health plans.
- Silicone membrane advances:Soft-durometer liquid silicone rubber formulations reduce flange irritation and enable longer expression sessions without tissue trauma.
- Battery energy density gains:Lithium-polymer cell improvements extend cordless operation beyond four full expression cycles per charge.
Market Restraints
- FDA 510(k) pathway costs:Electromagnetic compatibility testing and biocompatibility documentation requirements create six-figure regulatory entry barriers for new market entrants.
- Guangdong component concentration:Micro-motor and flexible PCB sourcing clusters in Shenzhen and Dongguan expose supply continuity to single-region logistics disruptions.
- Hospital-grade rental substitution:Durable medical equipment providers maintain Medicaid-reimbursed pump rental programs that delay wireless device purchase decisions among price-sensitive households.
Strategic Opportunities
- Subscription firmware tiers:Recurring revenue models for personalized suction pattern libraries and lactation consultant telehealth integration remain underdeveloped outside North American markets.
- EU MDR quality certification:Clinical evidence requirements filter smaller competitors from European distribution, creating premium positioning vacuums for compliant manufacturers.
- Telemedicine platform bundling:Direct integration with pediatrician and maternal health apps offers patient acquisition channels distinct from retail pharmacy and e-commerce.
Industry Challenges
- Firmware security validation:HIPAA-aligned encryption standards for milk volume data transmission require specialized health IT compliance expertise scarce among consumer electronics engineering teams.
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for new silicone formulations extend product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Breast Pump Market |
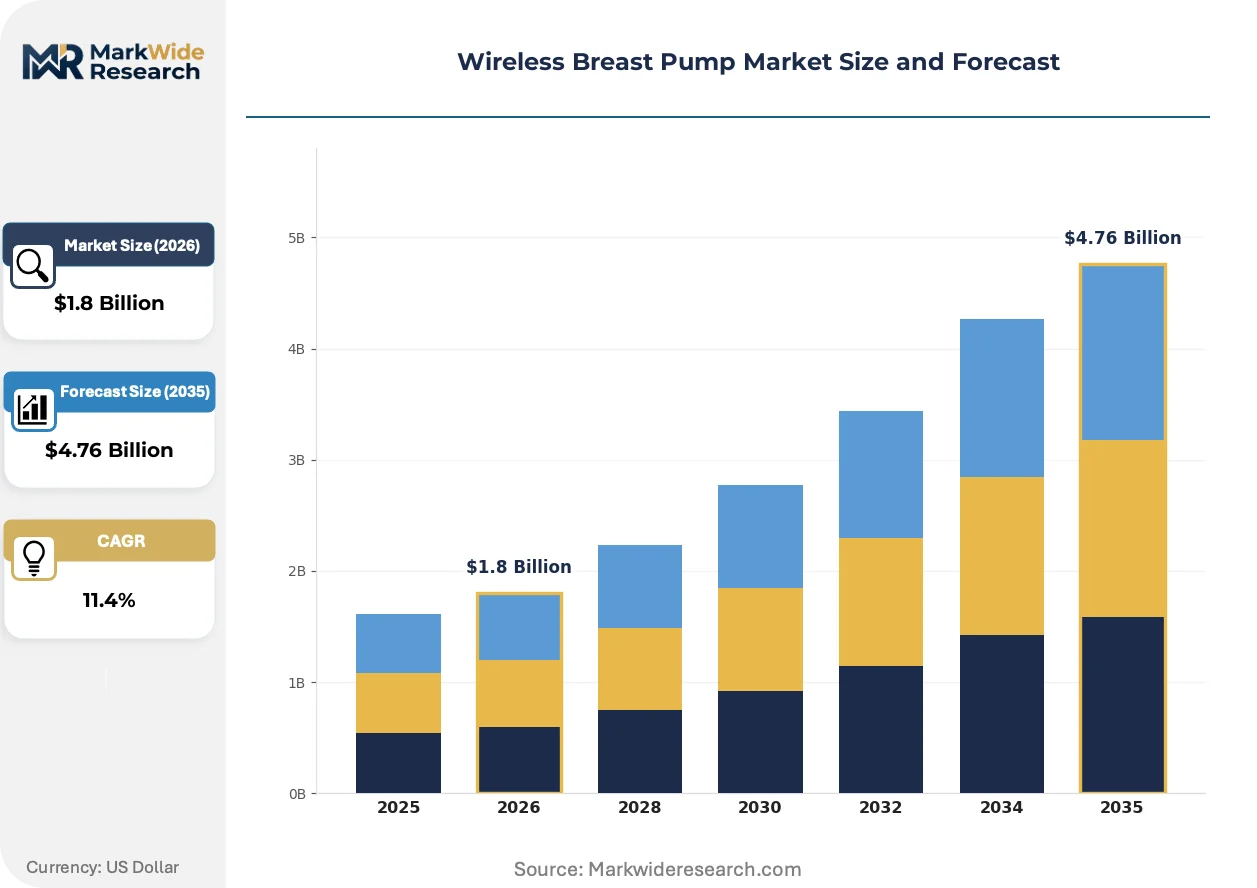
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Electric, Double Electric, Manual, Hospital Grade Technology: Smart Features, App Connectivity, Bluetooth, Battery Operated End User: New Mothers, Lactation Consultants, Hospitals, Health Clinics Distribution Channel: Online Retail, Pharmacies, Baby Stores, Medical Supply |
| Companies Covered | Medela AG, Philips Avent, Momcozy, Willow, Spectra, Lansinoh, Ardo Medical, Pigeon Corporation, Ameda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Breast Pump Market Strategic Shifts
Connected health architectures are redistributing value capture from hardware margins toward software-enabled service revenue, altering how manufacturers prioritize R&D allocation and partnership strategies.
Pressure-sensor arrays embedded in breast shield flanges are digitizing expression pattern optimization. Working mothers with irregular supply volumes adopt these configurations fastest, particularly those navigating return-to-office transitions. Real-time suction adjustment based on milk flow detection is digitizing the transition from standardized vacuum curves toward personalized physiological response models.
EU Medical Device Regulation post-market surveillance obligations are tightening clinical evidence requirements for wearable lactation devices. Manufacturers must now maintain vigilance databases tracking adverse events across all member states. Premium positioning in Germany, France, and the Netherlands now depends on notified body certification depth rather than marketing claims alone.
Employer-sponsored procurement through health benefit administrators is displacing direct-to-consumer e-commerce for working professional segments. Large self-insured employers negotiate volume pricing through benefits platforms, bypassing retail markup structures. This channel migration is most visible in the United States, where the PUMP Act has normalized pump coverage as a standard health plan component.
Wireless Breast Pump Market Segmentation
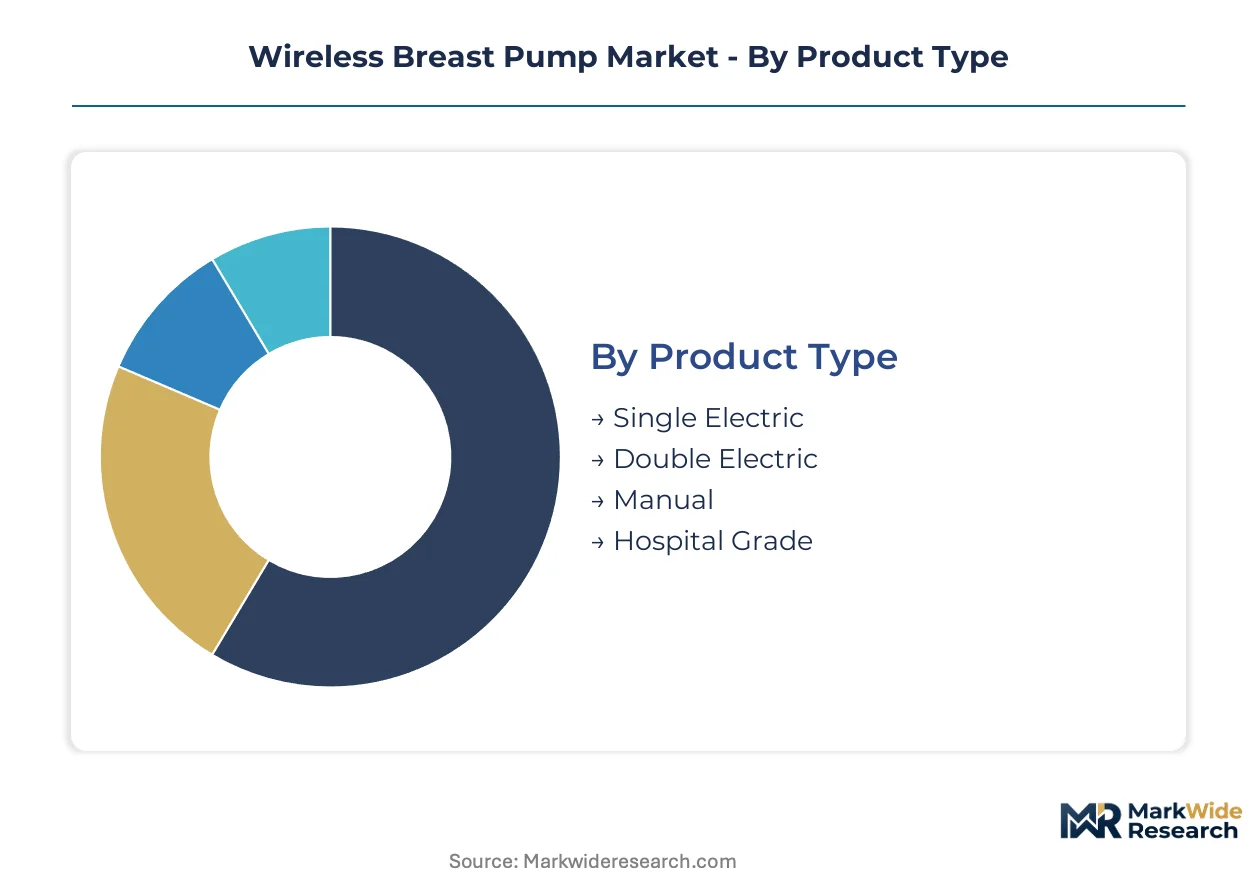
Wireless breast pump segmentation reveals how engineering priorities, reimbursement pathways, and maternal work patterns fragment addressable demand. Each dimension exposes distinct margin structures and competitive entry costs that reshape vendor resource allocation.
Product Type:
Use-case spectrum spans occasional expression at home through intensive clinical-grade extraction protocols.
- Double Electric:Dual-motor configurations synchronize bilateral expression, cutting session duration by half for working mothers navigating federally mandated break windows. Employer-sponsored procurement through US health benefit administrators concentrates demand in this configuration.
- Single Electric:Unilateral motor housings reduce unit cost and device weight for mothers prioritizing portability over throughput. Demand clusters among part-time workers and those with established supply stability.
- Manual:Hand-operated vacuum generation eliminates battery dependency and electromagnetic compatibility certification burdens. Travel segments and emergency backup applications sustain residual demand.
- Hospital Grade:Durable motor assemblies rated for multi-user rental cycles meet Medicaid-reimbursed durable medical equipment specifications. Rental program structures delay purchase conversion among price-sensitive households.
The dominant share belongs to Double Electric, while Hospital Grade is closing the gap fastest through employer procurement normalization.
Technology:
Cost tier separation distinguishes hardware-only devices from firmware-enabled service ecosystems.
- App Connectivity:Cloud-integrated suction pattern libraries and milk volume analytics convert one-time hardware transactions into recurring subscription revenue. Firmware-enabled lactation consultant telehealth integration is expanding most quickly among first-time buyers.
- Smart Features:Pressure-sensor arrays embedded in breast shield flanges enable real-time suction adjustment based on milk flow detection. Return-to-office transitions among US working mothers accelerate adoption of these personalized physiological response models.
- Bluetooth:Short-range wireless protocols enable smartphone-based vacuum customization without full cloud dependency. HIPAA-aligned encryption standards for health data transmission constrain engineering team composition.
- Battery Operated:Lithium-polymer cell integration defines cordless operation thresholds, with energy density gains extending cycles per charge beyond four full expressions.
App Connectivity commands premium positioning, while Smart Features is gaining share fastest through pediatrician referral channel development.
End User:
Customer type fragmentation separates direct maternal purchasers from institutional procurement gatekeepers.
- New Mothers:First-time buyers prioritize noise reduction and discrete wearability for workplace expression. FDA 510(k) clearance signals guide initial purchase decisions.
- Lactation Consultants:Certified professionals influence device recommendations through hospital discharge protocols and private practice consultations. Training program certification requirements shape brand loyalty.
- Hospitals:Neonatal intensive care units and maternity wards specify hospital-grade units for inpatient lactation support. Group purchasing organization contracts consolidate vendor selection.
- Health Clinics:Federally qualified health centers and maternal health clinics distribute subsidized devices through WIC program integration. Reimbursement code alignment determines stocking decisions.
New Mothers represent the largest addressable base, while Hospitals are climbing the fastest through value-based care bundling initiatives.
Distribution Channel:
Supply concentration in Shenzhen and Dongguan manufacturing clusters shapes fulfillment economics across channel types.
- Online Retail:Direct-to-consumer e-commerce platforms capture price-transparent comparison shopping, though employer-sponsored procurement is displacing this channel for professional segments.
- Pharmacies:Retail pharmacy chains leverage insurance adjudication infrastructure for HSA and FSA transaction processing. Shelf space allocation favors established FDA-cleared brands.
- Baby Stores:Specialty retailers emphasize hands-on fitting services and flange sizing expertise. Geographic concentration in suburban markets aligns with new mother residential patterns.
- Medical Supply:Durable medical equipment providers maintain Medicaid-reimbursed rental programs and pump purchase through insurance billing. Documentation requirements filter direct-to-consumer competitors.
Online Retail retains volume leadership, though Medical Supply is expanding most quickly through Medicare Advantage benefit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex underwrites trans-Pacific component flows for North American assembly, while Rotterdam's container terminals anchor European distribution corridors for wearable medical devices.
United States
FDA 510(k) clearance pathways and employer-sponsored health plan coverage through the PUMP Act drive procurement normalization. Working mothers in professional services sectors access wireless pumps through benefits administrators rather than retail channels. The Dallas-Fort Worth metroplex hosts third-party logistics hubs consolidating fulfillment for e-commerce and medical supply distributors.
Germany
EU MDR notified body certification requirements filter non-compliant competitors from premium positioning. Lactation consultant networks influence hospital discharge protocols across Bavaria and North Rhine-Westphalia. Berlin-Brandenburg clusters telemedicine platform developers integrating pump data into maternal health workflows.
China
Domestic demand concentrates in tier-one cities where dual-income professional households prioritize workplace expression solutions. NMPA medical device registration aligns with international quality standards for export-oriented manufacturers. Shenzhen and Dongguan micro-motor and flexible PCB sourcing clusters expose supply continuity to single-region logistics vulnerabilities.
Japan
PMDA pharmaceutical and medical device agency oversight maintains stringent post-market surveillance for wearable lactation devices. METI industrial policy supports precision manufacturing capabilities in Kansai and Chubu regions. Osaka-based component fabricators supply silicone membrane formulations to regional OEM assembly operations.
United Kingdom
MHRA regulatory convergence with EU MDR frameworks shapes staggered product launch timelines post-Brexit. NHS procurement frameworks for maternal health services create institutional demand channels distinct from retail pharmacy. London and Southeast England concentrate health technology venture capital directing R&D investment toward app-connected firmware ecosystems.
Wireless Breast Pump Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying motors, sensors, and membrane materials. The vendor base organizes around three strategic archetypes: vertically integrated silicone processors controlling unit economics, algorithm-focused noise reduction specialists, and quality-certification anchors leveraging European regulatory pathways. Competitive moves concentrate on firmware patent accumulation and telehealth platform bundling rather than hardware specification races.
Among Swiss-anchored quality certification specialists, Medela AG exemplifies the European regulatory pathway archetype. Momcozy represents vertically integrated silicone molding operations with captive supply chain control. Willow occupies a position within the algorithm-intensive noise reduction tier, distinguishing suction pattern intellectual property. These three anchors illustrate how competitive positioning fragments across hardware cost control, software differentiation, and regulatory compliance depth rather than converging on single-dimension dominance.
| Leading Market Players |
|---|
| Medela AG |
| Philips Avent |
| Momcozy |
| Willow |
| Spectra |
| Lansinoh |
| Ardo Medical |
| Pigeon Corporation |
| Ameda |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure between China and the United States dominates cost engineering decisions, compressing margin spreads between FDA-cleared premium units and uncertified economy alternatives while simultaneously forcing assembly relocation toward Southeast Asian contract manufacturers. Component sourcing clusters in Guangdong Province tether pricing power to single-region logistics vulnerabilities, with micro-motor and flexible PCB procurement costs determining tier boundaries.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on FDA 510(k) clearance status and silicone membrane grade. Price differentiation stems from electromagnetic compatibility certification depth and employer-sponsored procurement scale, with health benefit administrator contracts commanding steepest markdowns. Pricing pressure intensifies from Medicaid-reimbursed hospital-grade rental programs delaying purchase conversion among price-sensitive households. New mothers navigating return-to-office transitions exhibit lowest price sensitivity, while WIC program recipients demonstrate highest elasticity.
Supply Chain Analysis
Single-region dependency on Shenzhen and Dongguan manufacturing clusters exposes continuity to logistics disruptions and trade policy volatility. Raw material flows draw from lithium-polymer cell producers in South Korea, liquid silicone rubber formulators in Japan, and precision micro-motor fabricators in Taiwan. Distribution runs through third-party logistics hubs in the Dallas-Fort Worth metroplex for North American fulfillment and Rotterdam container terminals for European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled firmware ecosystems are converting hardware transactions into recurring subscription revenue, with telehealth platform interoperability emerging as the decisive competitive moat.
For Market Incumbents: Harden firmware patent portfolios against algorithm-focused entrants by accumulating suction pattern intellectual property and securing exclusive telemedicine platform integration agreements. Deepen in-house production of liquid silicone rubber membranes to offset component cost volatility from Guangdong suppliers. Prioritize EU MDR notified body certification depth to defend premium positioning vacuums in Germany and France. For New Entrants and Emerging Players: Southeast Asian distribution gaps present the most penetrable white-space, with tier-two cities in Vietnam and Indonesia lacking employer-sponsored procurement infrastructure. Target lactation consultant referral channels in European markets where hospital discharge protocols remain influencer-dominated. Pursue pediatrician app bundling as the lowest-friction go-to-market angle against established retail pharmacy shelf presence. For Investors and Strategic Acquirers: The market sits at a platform-economics inflection phase that favors algorithm-intensive noise reduction specialists with captive suction IP. Long-term viability over the coming decade hinges on firmware-enabled service revenue conversion rather than hardware shipment volume. Watch for FDA 510(k) clearance acceleration timelines as the signal indicating regulatory chokepoint easing.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Patent Accumulation | Suction algorithm IP builds defensible moats against component-cost competitors from Shenzhen clusters. |
| Telemedicine Platform Integration | Direct pediatrician app bundling bypasses retail pharmacy shelf-space allocation barriers. |
| EU MDR Certification Pathway | Notified body depth filters smaller competitors from premium positioning in Germany and France. |
| Subscription Tier Development | Recurring revenue from personalized suction libraries converts one-time buyers into ecosystem-anchored users. |
| Southeast Asian Assembly Relocation | Contract manufacturing in Vietnam and Thailand reduces tariff exposure from US-China trade friction. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with product development executives at wearable medical device manufacturers, lactation consultants, hospital purchasing committee members, and health benefit administrators; and secondary validation against FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement records, and employer-sponsored health plan coverage documents. Bottom-up triangulation of component cost structures and top-down reconciliation of addressable mother populations anchored volume estimates.
Forecast inputs considered product type segmentation across double electric, single electric, manual, and hospital-grade configurations; technology tiers spanning app connectivity, smart features, Bluetooth, and battery-operated variants; and end-user categories including new mothers, lactation consultants, hospitals, and health clinics. CAGRs derived from regression analysis of historical adoption curves correlated with regulatory enforcement timelines and employer coverage expansion patterns across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive firmware patent litigation or accelerated EU MDR compliance investments by mid-cap specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Body Contouring Devices Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Global Microcatheter Market