
 Postmenopausal Vaginal Atrophy Drugs Market | 2026-2036
Postmenopausal Vaginal Atrophy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Postmenopausal Vaginal Atrophy Drugs Market Analysis
Gynecologist workforce shortages in rural health systems is bifurcating patient access between metropolitan specialty clinics and underserved regions. Pfizer Inc. leverages its established estrogen portfolio to sustain formulary dominance across hospital networks. TherapeuticsMD Inc. differentiates through its intravaginal delivery innovations, while Novo Nordisk A/S anchors systemic hormone research pipelines.
Postmenopausal vaginal atrophy drugs comprise pharmaceutical and non-pharmaceutical interventions formulated with estrogen compounds, non-hormonal actives, or emollient bases designed to restore vaginal epithelial integrity and alleviate genitourinary symptoms. These therapies function primarily to address estrogen deficiency-induced mucosal thinning, serving gynecology, urology, and primary care settings where symptom management intersects with long-term pelvic health maintenance. Estrogen therapy occupies the largest revenue pool due to established clinical efficacy and decades of prescriber familiarity, while non-hormonal therapy represents the fastest-expanding segment as breast cancer survivors and hormone-averse patients seek alternatives. Intravaginal delivery commands premium positioning through localized action and reduced systemic exposure, whereas topical formulations compete on accessibility and patient self-administration convenience.
FDA labeling requirements for hormone therapy shape prescriber risk-benefit calculations and directly influence product development priorities across the industry. EMA's vigilance on endocrine-disrupting substance classifications adds compliance complexity for manufacturers seeking European market access. Stakeholders must monitor evolving regulatory posturing on compounded bioidentical alternatives, as enforcement shifts could abruptly reshape competitive boundaries between approved pharmaceuticals and pharmacy-compounded formulations.
Market Dynamics
FDA labeling revisions for hormone therapy are compressing prescriber risk tolerance and redirecting R&D investment toward localized delivery mechanisms that minimize systemic exposure. This regulatory pressure is fragmenting the competitive landscape between established systemic formulations and emerging intravaginal alternatives.
Growth Catalysts
- Aging Demographics:The United States population aged 50-64 is expanding faster than younger cohorts, concentrating symptomatic patient volumes in metropolitan gynecology clinics and driving formulary prioritization for menopause management protocols.
- EMA Endocrine-Disruptor Scrutiny:European regulatory vigilance on environmental classifications is accelerating manufacturer investment in biodegradable excipients and sustainable packaging to preempt market access barriers.
- Intravaginal Delivery Platforms:Polymeric matrix technologies enabling sustained local estrogen release are capturing prescriber preference by reducing dosing frequency and improving adherence curves among hormone-averse patients.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthetic estrogen precursor supply chains cluster in Chinese chemical manufacturing hubs, exposing formulators to geopolitical friction and customs processing volatility.
- Compounded Bioidentical Substitution:Pharmacy-compounded alternatives formulated with estradiol, estriol, and progesterone combinations threaten revenue capture by approved pharmaceuticals through lower cash-pay pricing and direct-to-consumer marketing.
- Black Box Warning Persistence:FDA-mandated cardiovascular and oncogenic risk language on systemic estrogen products continues to suppress initiation rates among primary care physicians managing multimorbid patients.
Strategic Opportunities
- Oncology Survivor Populations:Breast cancer survivors experiencing treatment-induced estrogen deficiency represent an addressable segment for non-hormonal ospemifene and vaginal moisturizers currently underserved by hormone-centric portfolios.
- Telehealth Integration:Direct-to-patient prescription platforms are collapsing traditional gynecology clinic gatekeeping, enabling asynchronous symptom assessment and home delivery of intravaginal therapies.
- IRSA Incentive Alignment:United States value-based care pilots under the Inflation Reduction Act are rewarding preventive pelvic health interventions, creating reimbursement tailwinds for early atrophy treatment versus delayed surgical intervention.
Industry Challenges
- Gynecology Workforce Distribution:Rural health systems in the United States face specialist shortages exceeding 40% of metropolitan density, forcing primary care physicians to manage complex hormone risk stratification without subspecialty backup.
- Clinical Trial Recruitment:FDA-mandated long-term safety databases require decade-scale follow-up, extending development timelines and capital lockup periods for novel non-hormonal mechanisms.
- Formulary Tier Negotiation:Hospital network pharmacy benefit managers are consolidating purchasing power, demanding outcome guarantees that smaller manufacturers lack the claims data infrastructure to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postmenopausal Vaginal Atrophy Drugs Market |
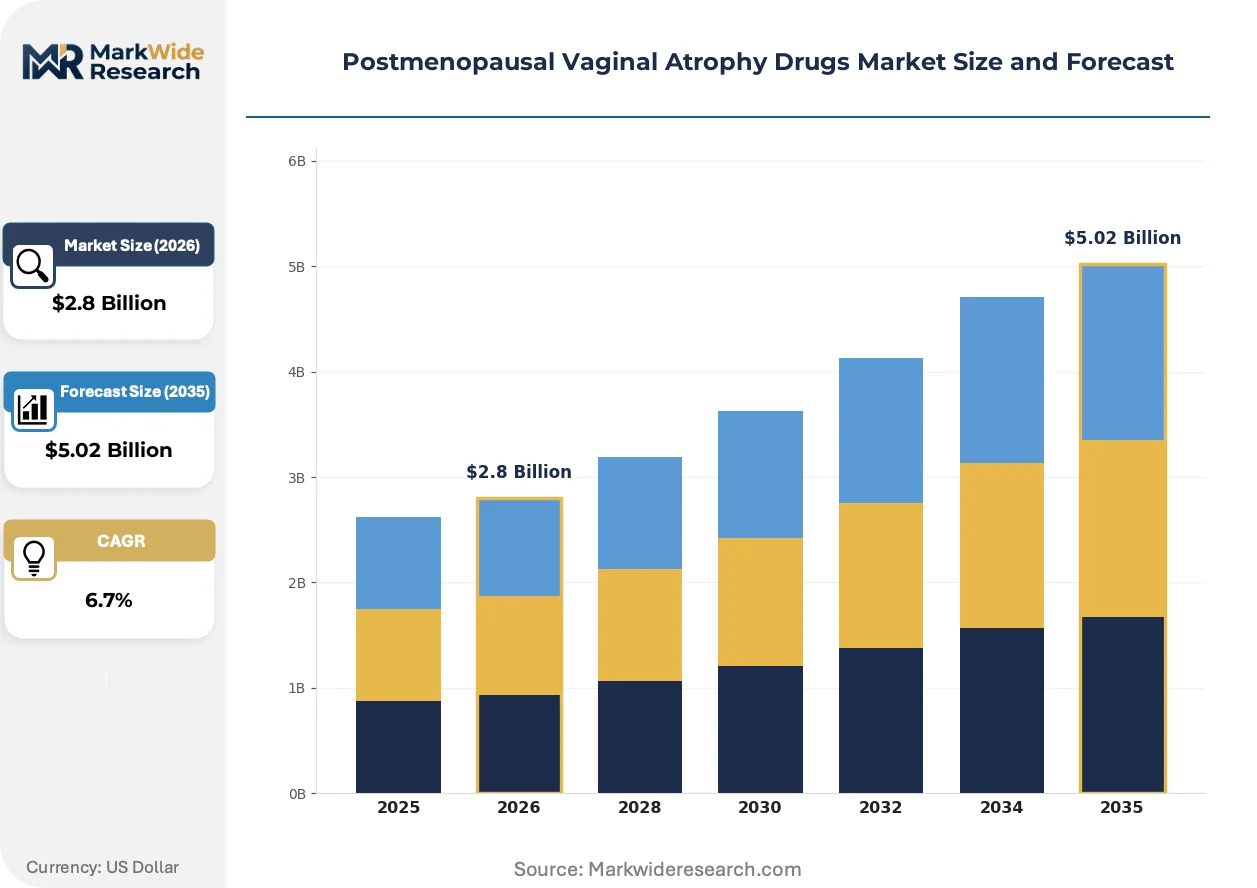
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogen Therapy, Non-Hormonal Therapy, Vaginal Moisturizers, Lubricants Delivery Mode: Topical, Oral, Intravaginal, Systemic End User: Clinics, Hospitals, Pharmacies, Home Care Indication: Vaginal Dryness, Dyspareunia, Urinary Symptoms, Atrophic Vaginitis |
| Companies Covered | Aspen Pharma, Duchesnay USA, Pfizer Inc., TherapeuticsMD Inc., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Endoceutics Inc., Merck & Co., Inc., Novo Nordisk A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postmenopausal Vaginal Atrophy Drugs Market Emerging Trajectories
Delivery mechanism innovation is fragmenting the traditional dominance of oral and transdermal systemic routes, with localized therapies capturing premium positioning through reduced safety signal burden and improved patient autonomy.
Intravaginal ring technologies incorporating silicone-elastomer reservoirs for sustained estradiol release are supplanting conventional cream and tablet formulations among patients prioritizing convenience and dosing discretion. Gynecology clinics in the United States are adopting these devices at accelerating rates, particularly for patients with adherence challenges or cosmetic concerns about visible packaging. The structural consequence is a compression in systemic hormone prescription volumes and a corresponding elevation in localized therapy average revenue per patient.
REACH authorization requirements for endocrine-disrupting substance classifications are compelling European manufacturers to reformulate excipient portfolios and submit enhanced environmental fate data. The industrial consequence is extended registration timelines and elevated compliance expenditure for products seeking EMA marketing authorization renewal. Intravaginal formulations with synthetic progestin components face the most acute reformulation pressure, driving portfolio rationalization toward pure estrogen or non-hormonal alternatives.
Patient-directed research and asynchronous consultation models are displacing traditional physician-gatekeered prescription pathways for vaginal atrophy therapies. Telehealth platforms in the United States are capturing prescription volume through symptom-checker algorithms and direct pharmacy fulfillment, bypassing gynecology clinic scheduling constraints. This channel shift is most visible among employed women aged 45-55 in metropolitan markets, where time scarcity and insurance network flexibility prioritize convenience over established provider relationships.
Postmenopausal Vaginal Atrophy Drugs Market Segmentation
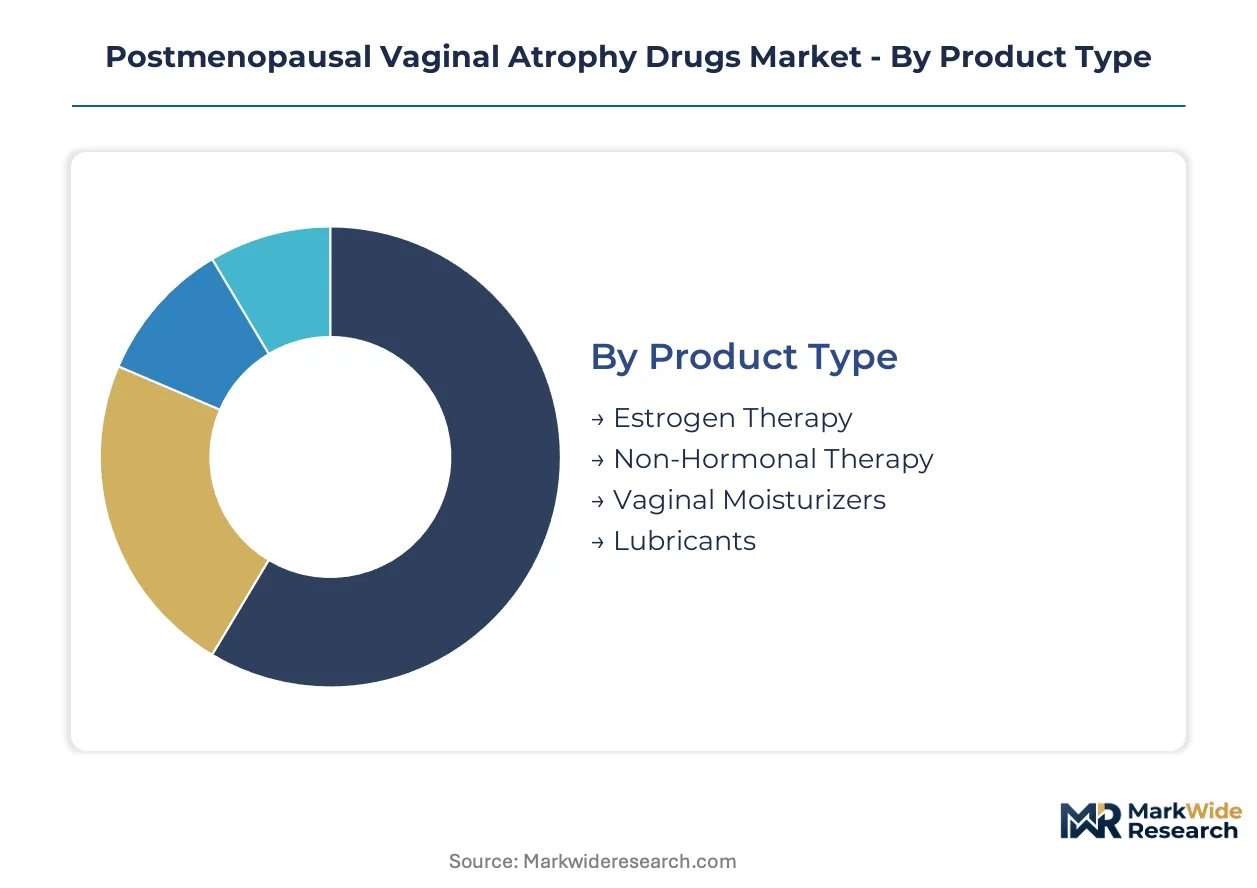
Segmentation in the postmenopausal vaginal atrophy drugs market reveals how prescriber risk tolerance and patient preference fragment across delivery mechanisms and therapeutic classes. Understanding these divisions exposes where compounded bioidentical alternatives exert the strongest substitution pressure on approved pharmaceuticals.
Product Type:
Compounded bioidentical estradiol-estriol combinations exert the strongest substitution pressure on estrogen therapy formulations, while non-hormonal alternatives face lower pharmacy-compounding encroachment due to patent-protected ospemifene mechanisms.
- Estrogen Therapy:Formulations containing estradiol, conjugated estrogens, or esterified estrogens restore vaginal epithelial thickness through nuclear receptor activation. Demand concentrates in metropolitan gynecology clinics across the United States where FDA-labeled systemic and local products maintain formulary preference despite black box warnings.
- Non-Hormonal Therapy:Ospemifene tablets and tissue-selective estrogen complex modulators address atrophy without systemic hormone exposure. Prescription volumes are climbing fastest among breast cancer survivors in oncology-integrated women's health practices where estrogen therapy remains contraindicated.
- Vaginal Moisturizers:Polycarbophil-based and hyaluronic acid formulations provide pH-balanced hydration without pharmacologic activity. These products compete primarily in retail pharmacy and direct-to-consumer channels against cosmetic-grade personal lubricants.
- Lubricants:Water-based and silicone-based preparations reduce friction during intercourse without therapeutic claims. Demand localizes to pharmacy OTC shelves and telehealth subscription platforms targeting peri-menopausal women aged 45-55.
Estrogen therapy anchors the volume base while non-hormonal therapy gains share at the steepest rate.
Delivery Mode:
Cost tier stratification separates premium-positioned intravaginal devices from commodity oral generics, with reimbursement differentials driving hospital formulary decisions.
- Topical:Creams, gels, and emulsions applied to vulvar or vaginal mucosa deliver localized estrogen with minimal systemic absorption. These formulations dominate cash-pay markets where patients prioritize discretion and avoid insurance prior authorization requirements.
- Oral:Systemic estrogen tablets and ospemifene capsules circulate through hepatic first-pass metabolism to achieve therapeutic plasma concentrations. Prescription volumes are compressing fastest in United States managed care networks where FDA cardiovascular warnings elevate liability concerns.
- Intravaginal:Rings, tablets, and inserts release estradiol directly to atrophic tissue with 10-20% systemic bioavailability compared to oral routes. Silicone-elastomer ring technologies from established manufacturers command premium pricing through reduced dosing frequency and improved adherence metrics.
- Systemic:Transdermal patches and oral formulations distribute estrogen throughout the body to address vasomotor symptoms concurrent with genitourinary atrophy. These products face the steepest formulary tier downgrades as prescribers migrate toward localized alternatives.
Intravaginal delivery captures the highest revenue per patient while oral systemic routes contract most rapidly in United States hospital networks.
End User:
Geographic access patterns bifurcate between specialist-intensive metropolitan corridors and primary care-dependent rural health systems.
- Clinics:Gynecology and urogynecology practices conduct pelvic examinations, pH testing, and maturation index assessments to guide therapy selection. These settings concentrate in United States urban markets where workforce density supports complex hormone risk stratification.
- Hospitals:Inpatient and emergency departments manage acute atrophic vaginitis complications including urinary tract infections and severe dyspareunia. Formulary committees in these institutions prioritize single-source intravaginal devices to reduce pharmacy inventory complexity.
- Pharmacies:Retail and specialty dispensaries fulfill prescriptions and counsel on administration technique for self-administered therapies. These channels face margin compression from pharmacy benefit manager reimbursement cuts and 340B pricing distortions.
- Home Care:Long-term care facilities and visiting nurse services manage atrophy in mobility-limited populations. Demand localizes to states with elevated nursing home bed density and Medicaid-funded personal care services.
Clinics generate the highest prescription volumes per site while home care expands most quickly among aging-in-place demographics.
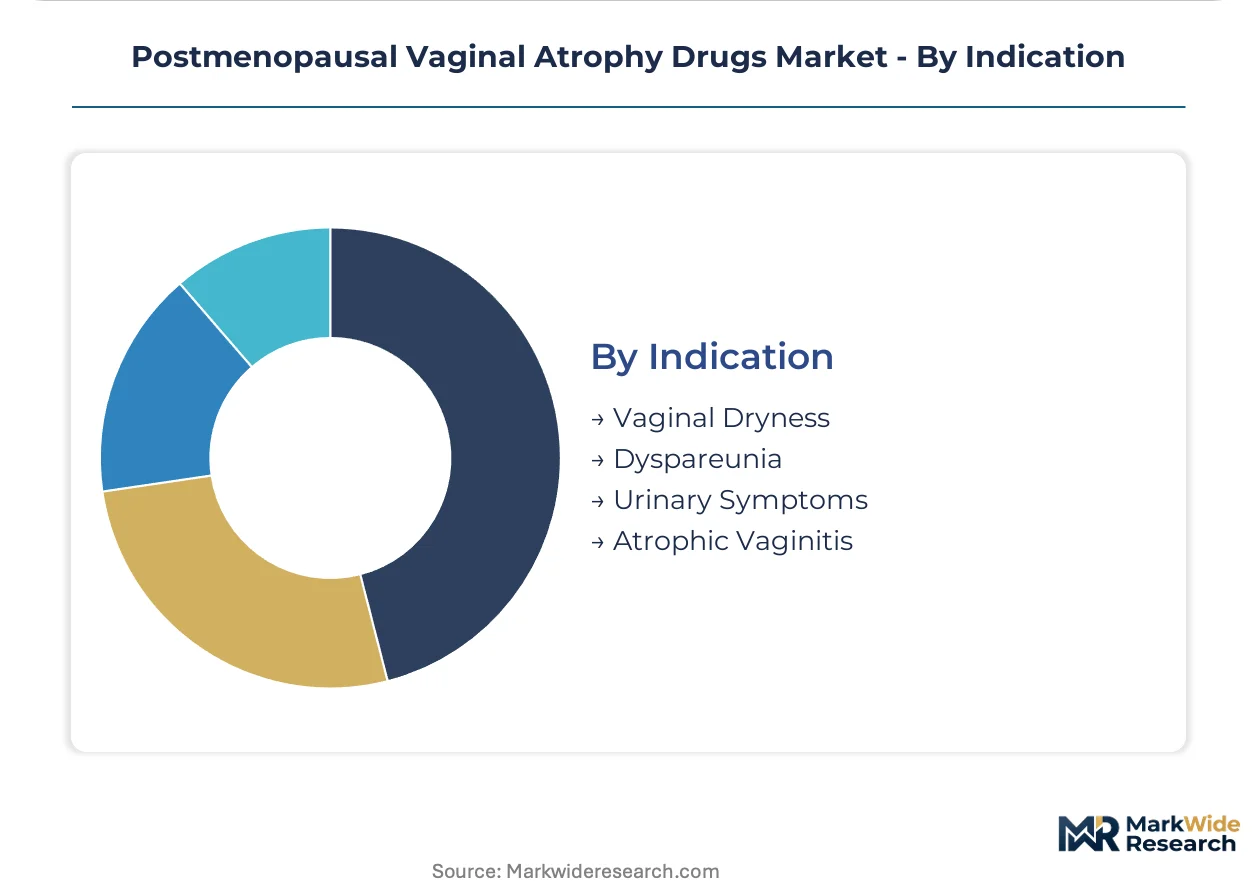
Indication:
Symptom severity and quality-of-life impact stratify patient willingness to pursue prescription therapy versus OTC self-treatment.
- Vaginal Dryness:Mucosal moisture deficiency causing discomfort, itching, and friction-related irritation. This indication drives the largest patient-initiated consultations in United States primary care settings where symptom disclosure rates remain below 50%.
- Dyspareunia:Painful intercourse resulting from epithelial thinning, reduced elasticity, and inadequate lubrication. Prescription therapy penetration is climbing fastest among couples seeking to maintain sexual activity through menopausal transition.
- Urinary Symptoms:Recurrent urinary tract infections, urgency, and dysuria linked to urethral and bladder trigone atrophy. Urology referrals for these complaints are expanding in integrated women's health networks addressing genitourinary syndrome of menopause.
- Atrophic Vaginitis:Inflammatory changes including pallor, friability, and petechiae visible on speculum examination. This diagnostic category requires clinician confirmation, limiting volume to settings with pelvic examination capability.
Vaginal dryness anchors the addressable patient population while dyspareunia drives the fastest conversion from OTC to prescription therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling authority shapes the largest revenue pool for postmenopausal vaginal atrophy therapeutics, while EMA regulatory frameworks and national pricing mechanisms fragment commercial strategies across European markets.
United States
Metropolitan gynecology clinics in Boston, New York, and Los Angeles concentrate symptomatic patient volumes as the 50-64 demographic expands faster than younger cohorts. FDA black box warnings on systemic estrogen continue compressing prescriber risk tolerance and redirecting formulary investment toward localized intravaginal delivery. Texas and Florida health systems are expanding menopause management protocols through telehealth-integrated women's health networks.
Germany
EMA endocrine-disruptor classifications under REACH authorization requirements are compelling manufacturers to reformulate excipient portfolios and submit enhanced environmental fate data. The country's statutory health insurance system maintains tight reimbursement controls on hormone therapy, favoring generic estradiol formulations over premium-priced innovations. Baden-Württemberg and Bavaria host the densest concentrations of specialized urogynecology practices addressing genitourinary syndrome of menopause.
United Kingdom
NHS England menopause pathway guidelines are elevating clinical awareness and reducing underdiagnosis of vaginal atrophy in primary care settings. MHRA vigilance on hormone therapy safety signals aligns with EMA frameworks but permits faster national adaptation of labeling changes. London and the Southeast corridor concentrate private gynecology capacity where cash-pay intravaginal ring prescriptions bypass NHS formulary constraints.
France
ANSM monitoring of transdermal estrogen formulations shapes prescriber preferences toward localized alternatives with reduced systemic exposure profiles. The country's generous reimbursement for menopausal hormone therapy sustains higher per-capita prescription rates than neighboring markets. Île-de-France and Auvergne-Rhône-Alpes anchor pharmaceutical R&D clusters where manufacturers develop next-generation vaginal drug delivery platforms.
Japan
PMDA approval pathways for novel non-hormonal mechanisms extend development timelines, compressing market entry for ospemifene-class alternatives to estrogen therapy. The aging population structure concentrates demand in Kanto and Kansai metropolitan corridors where specialized women's health clinics manage complex multimorbid patients. METI industrial policy incentives are drawing limited domestic manufacturing investment for intravaginal device production.
Postmenopausal Vaginal Atrophy Drugs Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates commanding hospital formulary access through established estrogen portfolios while mid-cap innovators capture niche segments through delivery mechanism differentiation. The competitive terrain fragments across three strategic archetypes: legacy hormone manufacturers defending systemic formulation franchises, intravaginal device specialists building localized therapy positions, and non-hormoral mechanism developers targeting oncology survivor populations. Consolidation pressure manifests through strategic partnerships between device innovators and distribution networks, alongside portfolio diversification moves that add menopause management assets to broader women's health franchises.
Within the integrated pharmaceutical tier, Pfizer Inc. and Novo Nordisk A/S occupy positions that exemplify divergent strategic postures toward systemic versus localized hormone exposure. TherapeuticsMD Inc. anchors the specialist tier as a pure-play intravaginal delivery innovator. These three entities collectively represent the competitive spectrum from established systemic formulation dominance through emerging localized therapy premium positioning.
| Leading Market Players |
|---|
| Aspen Pharma |
| Duchesnay USA |
| Pfizer Inc. |
| TherapeuticsMD Inc. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Endoceutics Inc. |
| Merck & Co., Inc. |
| Novo Nordisk A/S |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between United States hospital networks and intravaginal device manufacturers lock in supply access and price visibility for silicone-elastomer ring technologies, insulating formulary committees from API volatility while compressing margins for non-contracted entrants. This contract structure concentrates purchasing power among integrated delivery networks and fragments pricing power across regional pharmacy benefit managers.
Pricing Analysis
Metropolitan United States corridors command 15-25% premiums over rural health systems for identical intravaginal ring formulations due to gynecology workforce density and prior authorization infrastructure. Three-tier pricing structure across premium silicone-elastomer devices, standard vaginal tablets, and economy oral generics stratifies access by insurance tier and patient cash-pay capacity. Cost compression in the oral systemic segment intensifies because FDA black box warnings elevate liability premiums and suppress prescriber initiation rates. Hospital formulary committees exhibit the highest price sensitivity due to 340B pricing distortions and bundled reimbursement pressures, while cash-pay direct-to-consumer channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Strait of Hormuz transit exposure for petroleum-derived silicone precursors underwrites vulnerability in elastomer ring manufacturing, compelling device specialists to cultivate redundant sourcing strategies. Synthetic estrogen precursor production clusters in China and India, with formulation finishing concentrated in United States and European Union facilities. Active pharmaceutical ingredient supply draws from Chinese chemical manufacturing hubs and Indian contract synthesis operations, creating single-source vulnerability for estradiol hemihydrate and conjugated estrogen intermediates. Distribution runs through wholesale pharmaceutical distributors to hospital pharmacies and specialty mail-order fulfillment centers, with cold-chain requirements limited to select biologic formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across delivery mechanisms and patient risk profiles creates niche expansion opportunities as hormone-averse demographics and oncology survivor populations diverge from traditional estrogen therapy pathways.
For Market Incumbents: Shield systemic formulation franchises by accelerating intravaginal device portfolio expansion and securing exclusive formulary tier placement through outcome guarantee contracts with United States hospital networks. Cultivate backward integration into silicone-elastomer component manufacturing to reduce petroleum precursor exposure and defend margin position against generic ring entrants. Prioritize FDA labeling maintenance investments to preserve prescriber familiarity against compounded bioidentical substitution threats. For New Entrants and Emerging Players: Anchor in non-hormonal mechanism development for breast cancer survivor populations currently underserved by estrogen-centric portfolios, where ospemifene-class alternatives face limited competition and premium reimbursement potential. Target telehealth-integrated prescription platforms as the most penetrable channel, bypassing traditional gynecology clinic gatekeeping through asynchronous symptom assessment algorithms and direct pharmacy fulfillment partnerships. Deploy direct-to-patient marketing emphasizing dosing discretion and convenience to capture employed peri-menopausal women aged 45-55 in metropolitan markets. For Investors and Strategic Acquirers: Capital is best deployed toward intravaginal delivery specialists with differentiated polymeric matrix technologies and established United States formulary access, positioned for sustained premium pricing as localized therapy preference accelerates. Acquisition candidates should demonstrate clinical trial data infrastructure capable of supporting decade-scale FDA safety database requirements and hospital network outcome guarantee negotiations. Monitor EMA REACH authorization enforcement shifts as the critical signal for environmental compliance cost inflection and European market access barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Labeling Maintenance Investment | Preservation of prescriber risk-benefit familiarity against compounded bioidentical encroachment sustains formulary tier position. |
| Silicone-Elastomer Manufacturing Scale-Up | Captive production of ring reservoirs reduces petroleum precursor exposure and secures supply continuity for hospital contracts. |
| Telehealth Platform Partnership | Asynchronous prescription pathways collapse traditional gynecology clinic gatekeeping and expand addressable patient volume. |
| Non-Hormonal Mechanism Clinical Advancement | Ospemifene-class pipeline progression unlocks oncology-integrated women's health practices where estrogen remains contraindicated. |
| REACH Compliance Reformulation Program | Biodegradable excipient transition preempts EMA market access barriers and environmental classification-driven registration delays. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base, triangulated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary database audits. Secondary validation drew from SEC 10-K disclosures, CMS Medicare utilization data, and GPO contract repositories. Bottom-up prescription volume modeling and top-down epidemiological incidence estimates converged through iterative stakeholder feedback.
Sensitivity analysis across patient population growth assumptions, regulatory enforcement scenarios, and reimbursement tier migration probabilities shaped the analytical framework. Segmentation dimensions modeled include therapeutic class, delivery mechanism, end-user setting, and regional regulatory cluster. CAGRs derived from cohort-specific adoption curves and prescriber behavior elasticity parameters, with inputs from aging demographic projections and hormone therapy risk perception indices.
Decision-makers should treat outputs as directional under stable FDA labeling authority and EMA REACH enforcement assumptions; material deviation in compounded bioidentical regulatory posture or silicone precursor supply disruption would warrant model refresh. Practitioners should keep alternative scenarios live as telehealth prescribing regulations and IRA value-based care pilot expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Analgesics Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Prescription Transdermal Patches Market