
 Snap Cap Vials Market | 2026-2036
Snap Cap Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Snap Cap Vials Market Analytics
Germany is tilting toward expanded borosilicate glass capacity to serve biologic packaging demand across Europe. Gerresheimer AG leverages its integrated molding and conversion footprint to control quality from tube to finished vial. Schott AG anchors high-volume supply through its proprietary FIOLAX tubing operations. West Pharmaceutical Services, Inc. competes by pairing snap cap vials with integrated seal and delivery systems.
Snap cap vials are cylindrical containers with friction-fit or snap-on closures, typically manufactured from borosilicate glass or pharmaceutical-grade polymers such as polypropylene and cyclic olefin polymer, designed for secure sample containment and repeated access without threaded manipulation. Their primary purpose spans diagnostic specimen preservation, parenteral drug storage, and analytical chemistry workflows where contamination control and user efficiency matter. Glass vials command premium positioning in biologics and lyophilized formulations where inertness and thermal stability protect sensitive payloads. Plastic variants are capturing volume in point-of-care diagnostics and retail pharmacy dispensing where cost and breakage resistance outweigh extractables concerns. Sample storage applications sit at the center of margin pools, driven by biobank expansion and personalized medicine sample volumes.
The US FDA enforces container closure integrity standards under its 2016 guidance on glass packaging for injectable drugs, while the EU MDR tightens traceability requirements for primary packaging in medical devices. Germany's national pharmaceutical regulator applies additional BfArM scrutiny to leachable profiles from polymeric closures. ISO 8362 governs dimensional interchangeability, shaping procurement specifications across multinational drug makers. Stakeholders must monitor how evolving extractables and leachables testing protocols from USP <1664> and European Pharmacopoeia chapters reshape material qualification timelines and supplier switching costs.
Market Dynamics
Container closure integrity requirements from the US FDA are compressing supplier qualification timelines while biologic drug pipelines expand cold-chain-compatible packaging demand. Glass-to-plastic substitution debates intensify as extractables testing protocols mature.
Growth Catalysts
- Biologic cold-chain expansion:mRNA and cell therapy pipelines require borosilicate glass stability across ultra-low temperature ranges, pulling vial specifications toward premium grades.
- EU MDR traceability mandates:Unique Device Identification requirements for primary packaging accelerate serialized vial procurement across European injectable drug manufacturers.
- German manufacturing density:The Rhine-Main cluster of fill-finish contractors concentrates demand for just-in-time vial supply with documented leachable profiles.
Market Restraints
- Energy-intensive borosilicate melting:Natural gas price volatility in European glassmaking regions compresses margin sustainability for tubing suppliers.
- Single-source tubing concentration:Proprietary FIOLAX and BORO-833 feedstock channels create supply vulnerability when furnace maintenance cycles align.
- Plastic closure leachable ceilings:Cyclic olefin polymer caps face BfArM scrutiny that delays qualification for high-value biologic applications.
Strategic Opportunities
- Indian injectable export hubs:Hyderabad and Ahmedabad clusters seek qualified secondary packaging partners as CDSCO aligns with PIC/S standards.
- Prefilled syringe convergence:Snap cap vial formats adapted for auto-injector cartridge integration capture share from traditional vial-syringe transfer steps.
- Biobank cryogenic protocols:Automated sample retrieval systems favor polymer vials with embedded RFID for -80°C archival workflows.
Industry Challenges
- Extractables chemist scarcity:USP <1664> and European Pharmacopoeia 3.2.6 qualification timelines extend 8-14 months due to limited analytical toxicology capacity.
- Legacy inspection equipment retrofit:Camera-based crack detection systems require revalidation when vial shoulder geometries shift for robotic handling compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snap Cap Vials Market |
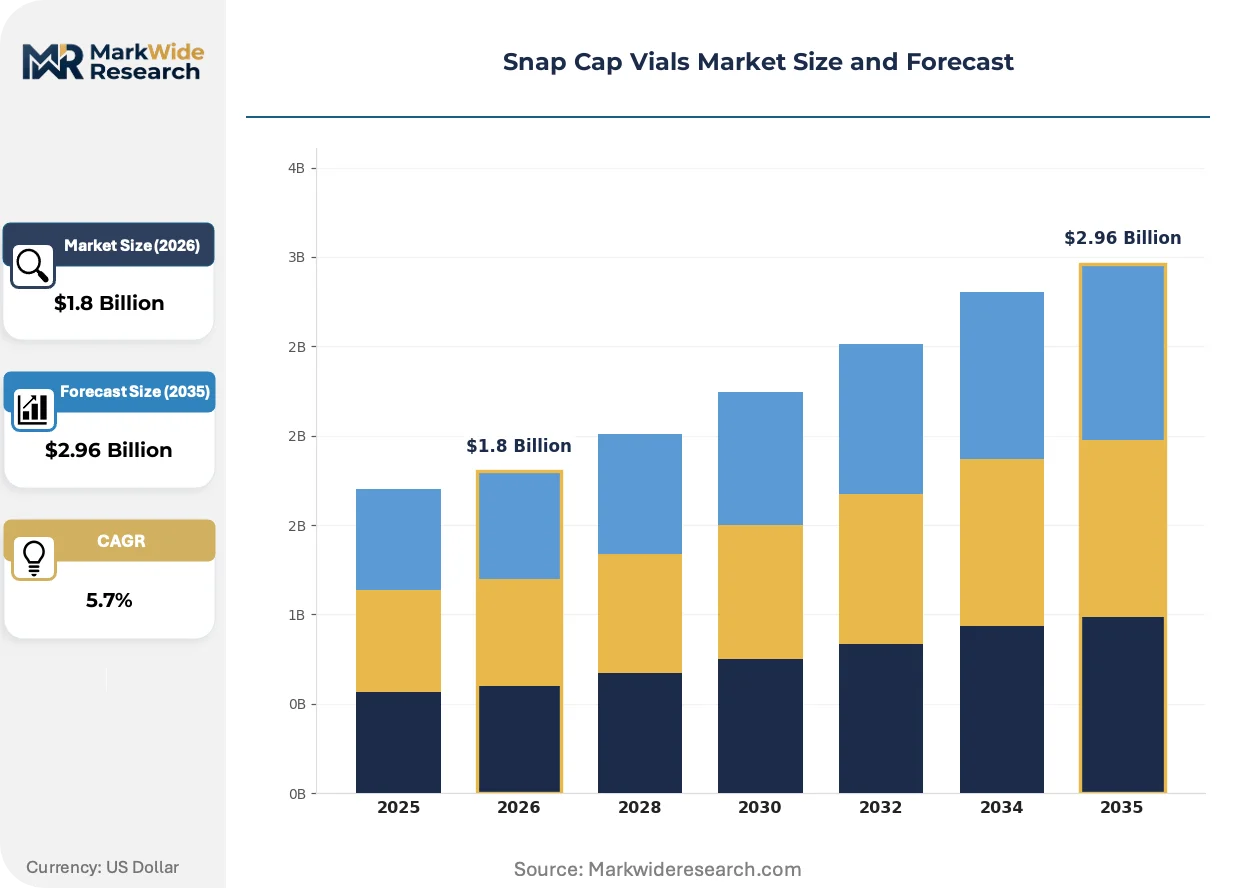
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Sterile, Non-Sterile End User: Pharmaceutical Companies, Laboratories, Research Institutions, Hospitals Application: Sample Storage, Medication Dispensing, Laboratory Testing, Chemical Analysis Packaging Type: Bulk Packaging, Individual Packaging, Custom Packaging, Eco-friendly Packaging |
| Companies Covered | Gerresheimer AG, Schott AG, West Pharmaceutical Services, Inc., Stevanato Group, SGD Pharma, DWK Life Sciences, Corning Incorporated, Nipro Corporation, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snap Cap Vials Market Evolving Landscape
Material science advances and regulatory chemistry requirements are compressing the traditional glass-versus-plastic dichotomy into hybrid specification frameworks. Automation compatibility now shapes vial geometry as much as chemical inertness.
Sterile, ready-to-use (RTU) vial formats are collapsing the conventional sequence of vial washing, depyrogenation, and sterilization that dominated parenteral packaging workflows. Contract fill-finish operators in Germany and Switzerland are adopting RTU glass vials at the fastest clip, compressing line changeover times from hours to minutes while eliminating in-house washer-dryer capital expenditure. This shift is collapsing the historical advantage of vertically integrated pharmaceutical manufacturers who maintained captive glass processing operations.
REACH Annex XVII restrictions on certain phthalate plasticizers are forcing closure compound reformulation across European supply chains. The industrial consequence is a 12-18 month requalification cycle for existing drug-device combinations that relied on legacy elastomer formulations. High-value lyophilized biologics are most affected, with sponsors accelerating halobutyl and Teflon-coated stopper validation to maintain market access.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer-vial supplier relationships in North American hospital systems. Three-tier contracting structures separate premium certified vials for clinical trials from standard catalog items for commercial production. This concentration is most visible in oncology injectable purchasing, where GPOs representing 40% of US infusion center volume now mandate consolidated vial-lead seal-needle system sourcing.
Snap Cap Vials Market Segmentation
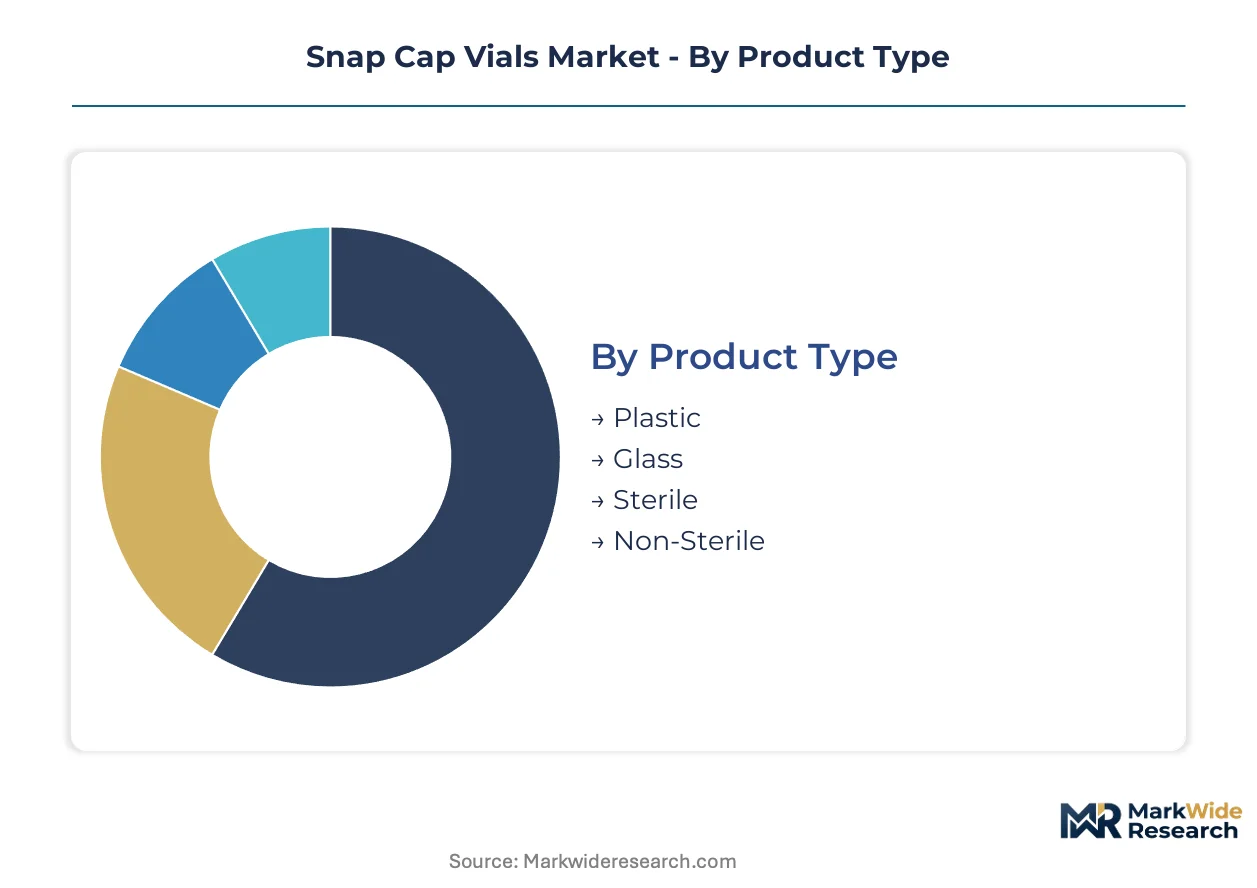
Snap cap vial procurement splits across material purity grades, sterility assurance levels, and end-use workflow requirements. Pharmaceutical manufacturers prioritize container closure integrity certifications while diagnostic laboratories optimize for automation compatibility and cost per sample.
Product Type:
Mature glass formats dominate high-value biologics while polymer variants capture emerging point-of-care and retail pharmacy volumes.
- Plastic:Polypropylene and cyclic olefin polymer vials offer breakage resistance and lower unit economics for high-throughput diagnostic workflows. Demand concentrates in US hospital systems and retail pharmacy chains where cost containment outweighs extractables concerns for non-parenteral applications.
- Glass:Borosilicate formulations deliver thermal stability and chemical inertness required for lyophilized biologics and ultra-low temperature storage. German fill-finish contractors and Swiss biologics manufacturers anchor premium-grade procurement, pulled by EMA stability requirements and cold-chain expansion for mRNA therapies.
- Sterile:Ready-to-use formats eliminate in-house washing and depyrogenation, compressing line changeover times for contract manufacturing organizations.
- Non-Sterile:Bulk formats serve research institutions and analytical chemistry workflows where end-user sterilization protocols remain standard practice.
Glass retains volume leadership in value terms; plastic holds the steepest expansion curve in unit shipments.
End User:
Customer procurement sophistication spans validated pharmaceutical supply chains to decentralized hospital purchasing through group buying organizations.
- Pharmaceutical Companies:Sponsors of injectable biologics mandate documented leachable profiles and container closure integrity data packages. FDA and EMA filing requirements compress supplier qualification timelines to 8-14 months.
- Laboratories:Clinical and research labs prioritize dimensional consistency for automated liquid handling systems. Barcode serialization and RFID embedding are climbing fastest in biobank archival applications.
- Research Institutions:Academic and government labs balance specification flexibility against grant-funded budget constraints.
- Hospitals:Infusion centers and oncology clinics in the US increasingly source through three-tier GPO contracts separating trial-grade from commercial production vials.
Pharmaceutical companies command the premium tier; laboratories represent the volume growth engine.
Application:
Workflow-specific requirements fragment specifications across preservation duration, access frequency, and contamination risk tolerance.
- Sample Storage:Biobank expansion and personalized medicine sample volumes drive demand for cryogenic-compatible formats. Automated retrieval systems favor polymer vials with embedded RFID at minus 80 degrees Celsius.
- Medication Dispensing:Retail pharmacy and hospital outpatient settings require child-resistant closure compatibility and unit-dose traceability.
- Laboratory Testing:Diagnostic specimen preservation demands low-protein-binding surfaces and certified nuclease-free status for molecular applications.
- Chemical Analysis:Chromatography and mass spectrometry workflows specify inert borosilicate with certified low background contamination.
Sample storage captures the widest margin pools; medication dispensing is expanding most quickly in emerging market retail channels.
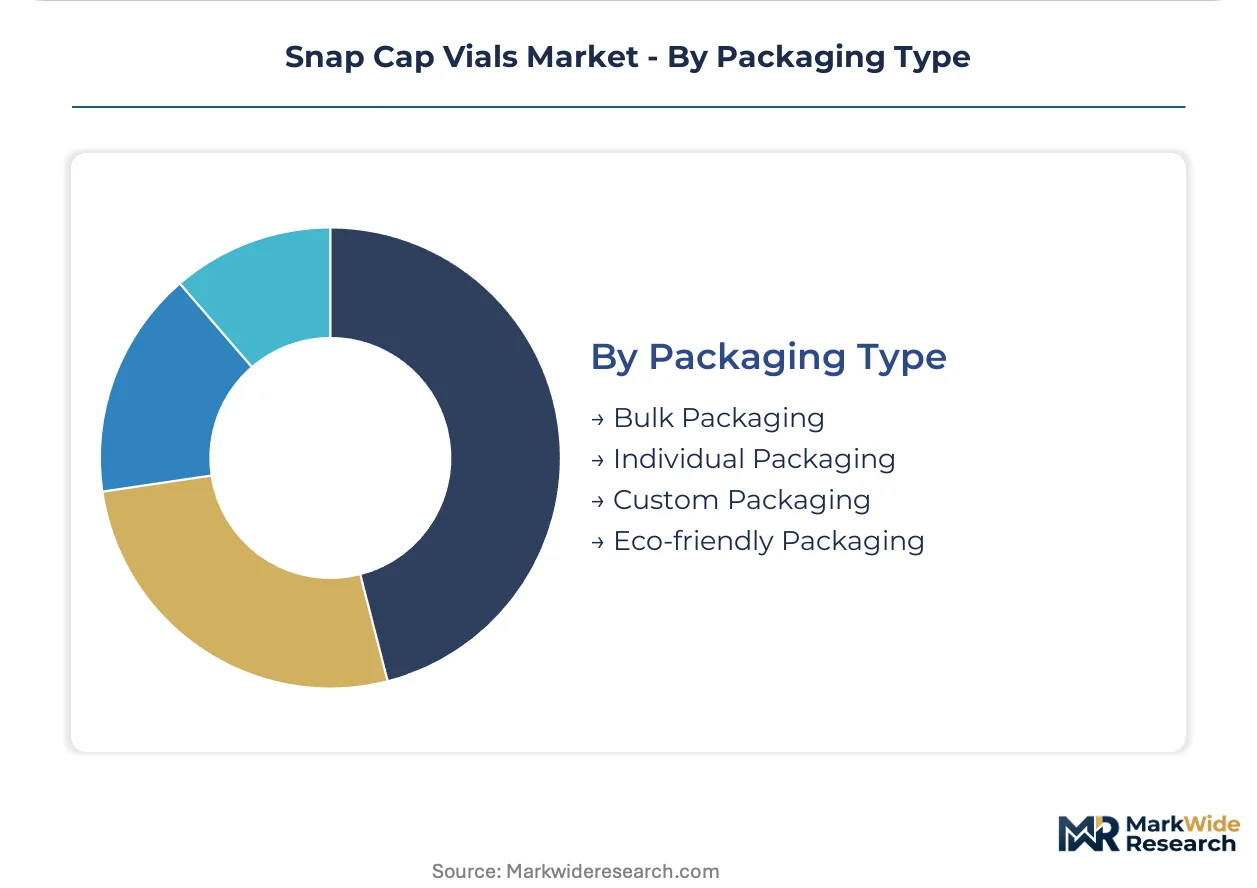
Packaging Type:
Supply chain configuration and sustainability mandates reshape primary packaging decisions alongside sterility assurance requirements.
- Bulk Packaging:Standard for high-volume commercial production where fill-finish operators maintain captive washing and sterilization infrastructure.
- Individual Packaging:Required for clinical trial materials and personalized medicine batches where lot traceability and contamination control are paramount.
- Custom Packaging:Integrated vial-seal-delivery system configurations for auto-injector and wearable device compatibility.
- Eco-friendly Packaging:Recycled content and reduced plastic formats responding to EU Green Deal and REACH Annex XVII pressure on packaging waste.
Bulk packaging retains cost leadership; eco-friendly formats are gaining specification share fastest in European procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics corridor underwrites Europe's dominance in pharmaceutical glass distribution, while direct rail links from Düsseldorf to Basel concentrate borosilicate tubing flows.
United States
FDA container closure integrity guidance is compressing supplier qualification timelines for mRNA vaccine storage formats. The 2016 glass packaging guidance for injectable drugs mandates documented leachable profiles. The Boston-Cambridge biotech cluster anchors premium-grade vial procurement for cell therapy pipelines.
Germany
The Rhine-Main fill-finish contractor density concentrates just-in-time demand for documented leachable profiles. BfArM applies additional scrutiny to polymeric closure leachables beyond EMA baseline requirements. Gerresheimer AG's integrated molding footprint in Essen controls quality from tube conversion to finished vial.
Switzerland
Swissmedic stability requirements for biologics pull specifications toward premium borosilicate grades. The country's pharmaceutical regulator aligns with EMA traceability mandates while maintaining distinct inspection protocols. Basel's Novartis-Roche supplier ecosystem concentrates high-value lyophilized vial demand.
India
Hyderabad and Ahmedabad injectable export hubs seek qualified secondary packaging partners as CDSCO aligns with PIC/S standards. The national pharmaceutical regulator's upgraded GMP inspections are accelerating documentation requirements for primary packaging. Gujarat's Special Economic Zone infrastructure supports temperature-controlled vial distribution to Middle Eastern markets.
China
NMPA's updated pharmacopoeia chapters on extractables testing are extending material qualification timelines for imported drug-device combinations. The Yangtze River Delta pharmaceutical manufacturing belt concentrates domestic fill-finish capacity expansion. Shanghai's free-trade zone logistics infrastructure supports bonded warehousing for multinational vial suppliers.
Snap Cap Vials Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling material feedstock and conversion quality. The supplier base concentrates around three proprietary borosilicate tubing channels that create single-source vulnerability during furnace maintenance cycles. Two strategic archetypes dominate: integrated glass converters with captive tubing supply, and packaging system integrators pairing vials with delivery mechanisms. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing long-term tubing offtake agreements.
Among German-based fabricators, Gerresheimer AG and Schott AG exemplify the integrated converter archetype, each controlling proprietary feedstock channels from melt to finished component. West Pharmaceutical Services, Inc. occupies the system integrator position, representing the packaging-delivery convergence strategy. These three anchors illustrate how material control and system integration define competitive positioning in pharmaceutical primary packaging.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| West Pharmaceutical Services, Inc. |
| Stevanato Group |
| SGD Pharma |
| DWK Life Sciences |
| Corning Incorporated |
| Nipro Corporation |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
The Rhine-Main cluster's furnace capacity dynamics directly translate into downstream pricing power for borosilicate glass converters. Contract fill-finish operators in Germany and Switzerland absorb premium tiering when proprietary FIOLAX tubing channels constrain spot availability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts. Price differentiation rests on certification grade (USP <1664> qualified versus catalog standard) and volume scale (annual offtake commitments above 50 million units unlock base-price indexing). Cost compression in standard-grade plastic vials is intensifying because cyclic olefin polymer resin imports face extended customs clearance timelines. Hospital GPOs represent the most price-sensitive buyer archetype, while Swiss biologics manufacturers exhibit lowest sensitivity due to stability-driven specification lock-in.
Supply Chain Analysis
Tariff exposure between Germany and energy-exporting regions dominates margin risk for borosilicate melters. Supply concentrates in Germany, China, and the United States for finished vial conversion, while proprietary tubing feedstock draws from Schott AG's Mitterteich furnaces and Corning Incorporated's North Carolina operations. Natural gas price volatility in European glassmaking regions creates single-source vulnerability when furnace maintenance cycles align. Distribution runs through direct mill-to-warehouse rail links for German fill-finish contractors, with sea freight dominating transatlantic pharmaceutical company procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized extractables chemist capacity sits at the binding constraint for qualification timelines, with USP <1664> proficiency gaps extending supplier onboarding to 14 months. This scarcity rewards early investment in analytical toxicology partnerships.
For Market Incumbents: Harden container closure integrity data packages against emerging polymer vial competitors by embedding RFID traceability as a standard feature. Secure long-term FIOLAX tubing offtake agreements before furnace maintenance cycles compress spot availability. Vertical integration into halobutyl stopper compounding defends margin position against REACH Annex XVII reformulation delays.
For New Entrants and Emerging Players: Build out cryogenic-compatible polymer vial capacity for biobank archival applications where automated retrieval systems favor embedded RFID formats. Indian injectable export hubs in Hyderabad and Ahmedabad offer the most penetrable geography as CDSCO aligns with PIC/S standards. Partner with German fill-finish contractors on just-in-time delivery protocols to bypass incumbent tubing channel control.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated glass converters with captive borosilicate supply over packaging system integrators dependent on third-party tubing. Long-term viability hinges on energy transition resilience in European furnace operations. Watch for NMPA extractables testing protocol extensions as the inflection signal for China-market qualification cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Tubing Offtake Agreement | Locks in FIOLAX or BORO-833 feedstock ahead of furnace maintenance cycles for German converters. |
| Extractables Chemistry Partnership | Secures scarce USP <1664> analytical capacity to compress 14-month qualification timelines. |
| Ready-to-Use Vial Format Expansion | Eliminates in-house washing capital expenditure for contract manufacturing organizations in Switzerland. |
| RFID-Embedded Polymer Vial Launch | Captures biobank automation demand at minus 80 degrees Celsius archival workflows. |
| Halobutyl Stopper Validation Acceleration | Maintains EMA market access as REACH Annex XVII forces phthalate plasticizer reformulation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork. Pharmaceutical packaging procurement managers, fill-finish operations directors, extractables chemistry laboratory heads, and regulatory affairs specialists at EMA and FDA provided operational validation. Secondary sources encompassed USP <1664> guidance documents, European Pharmacopoeia 3.2.6 chapters, FDA container closure integrity guidance, and SEC filings from listed packaging converters. Bottom-up volume modeling triangulated against top-down pharmaceutical production data.
Calibration against historical borosilicate tubing capacity utilization and pharmaceutical fill-finish expansion announcements anchored the analytical framework. Segmentation dimensions spanned material type (glass versus polymer), sterility assurance level (ready-to-use versus bulk), end-user workflow (pharmaceutical manufacturing versus diagnostic laboratory), and regional regulatory cluster (FDA, EMA, NMPA, CDSCO). CAGRs were derived from installed base depreciation rates and pipeline drug format specifications across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed tubing entrants or accelerated EU carbon border adjustments would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Twist Caps Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Global Aluminum Caps and Closures Market