
 Clic Loc Closure Market | 2026-2036
Clic Loc Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Clic Loc Closure Market Outlook
Modular closure bundling with secondary packaging is expanding buyer choice across pharmaceutical and food-service channels. FlexiLock leverages captive resin compounding to control material consistency across snap and twist closure lines. SealTech anchors its position through dedicated child-resistant design labs serving North American and European drug packagers. ClickSure differentiates via rapid-tooling capabilities that compress custom closure development cycles.
Clic Loc closures are mechanical fastening devices that engage through radial snap-fit or helical twist geometries, typically molded in polypropylene or HDPE with integral tamper-evident bands, designed to secure contents while enabling single-handed dispensing. Their primary commercial purpose spans containment, dose control, and child-safety compliance across liquid and semi-solid product formats. Plastic material formulations dominate unit economics due to injection-molding scalability, though aluminum and composite alternatives occupy premium personal-care and high-barrier pharmaceutical segments where oxygen ingress limits apply. Child-resistant design types command margin premiums as regulatory stringency escalates, while reusable configurations represent an emerging pool as brand owners test refill-commerce models in household and personal-care categories.
FDA 21 CFR Part 170-189 food-contact substance rules and EMA Annex I pharmaceutical packaging guidelines shape material selection and migration-testing burdens for closure suppliers seeking multi-regional market access. ISO 8317 child-resistant packaging standards and EU MDR device-labeling requirements add parallel compliance layers that favor manufacturers with integrated regulatory-affairs functions. Stakeholders must monitor evolving extended-producer-responsibility frameworks in target jurisdictions, as post-consumer recycling mandates will increasingly dictate material specification and design-for-disassembly priorities.
Market Dynamics
Child-resistant packaging mandates from FDA and EMA are compressing development cycles and forcing closure suppliers to integrate dedicated testing labs, reshaping competitive capability requirements across pharmaceutical supply chains.
Growth Catalysts
- FDA 21 CFR Part 170-189 compliance:Food-contact substance rules drive material standardization investments, expanding addressable market for multi-regional suppliers with pre-validated resin formulations.
- Contract packaging services:Third-party packagers in Germany, India, and Brazil are consolidating procurement volumes, creating scale incentives for closure manufacturers with regional molding footprints.
- Tamper-evident band integration:Helical twist geometries with molded tear strips are displacing separate label applications, reducing line complexity for liquid pharmaceutical fillers.
Market Restraints
- Polypropylene price volatility:Propylene feedstock exposure creates margin compression risks for injection molders without captive resin compounding or indexed customer contracts.
- Tooling lead times:Custom cavity fabrication for child-resistant mechanisms requires 12-16 week procurement cycles, constraining rapid response to formulation changes or SKU proliferation.
- Aluminum substitution in oxygen-sensitive segments:High-barrier pharmaceutical applications favor metal closures with induction seals, limiting plastic Clic Loc penetration in biologics packaging.
Strategic Opportunities
- Refill-commerce models:Reusable closure configurations with durable snap-fit geometries are gaining traction in European household and personal-care subscription channels.
- Extended producer responsibility frameworks:EU Green Deal packaging waste directives incentivize mono-material PP designs that simplify post-consumer sorting and mechanical recycling.
- Modular bundling with secondary packaging:Closure-carton integration services create stickier supplier relationships and reduce buyer vendor management overhead.
Industry Challenges
- ISO 8317 certification timelines:Child-resistant testing protocols require 3-6 month validation cycles, delaying product launches and freezing working capital in inventory.
- Migration testing burden:EMA Annex I pharmaceutical guidelines demand extensive extractables studies for each resin batch, straining analytical chemistry capacity at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clic Loc Closure Market |
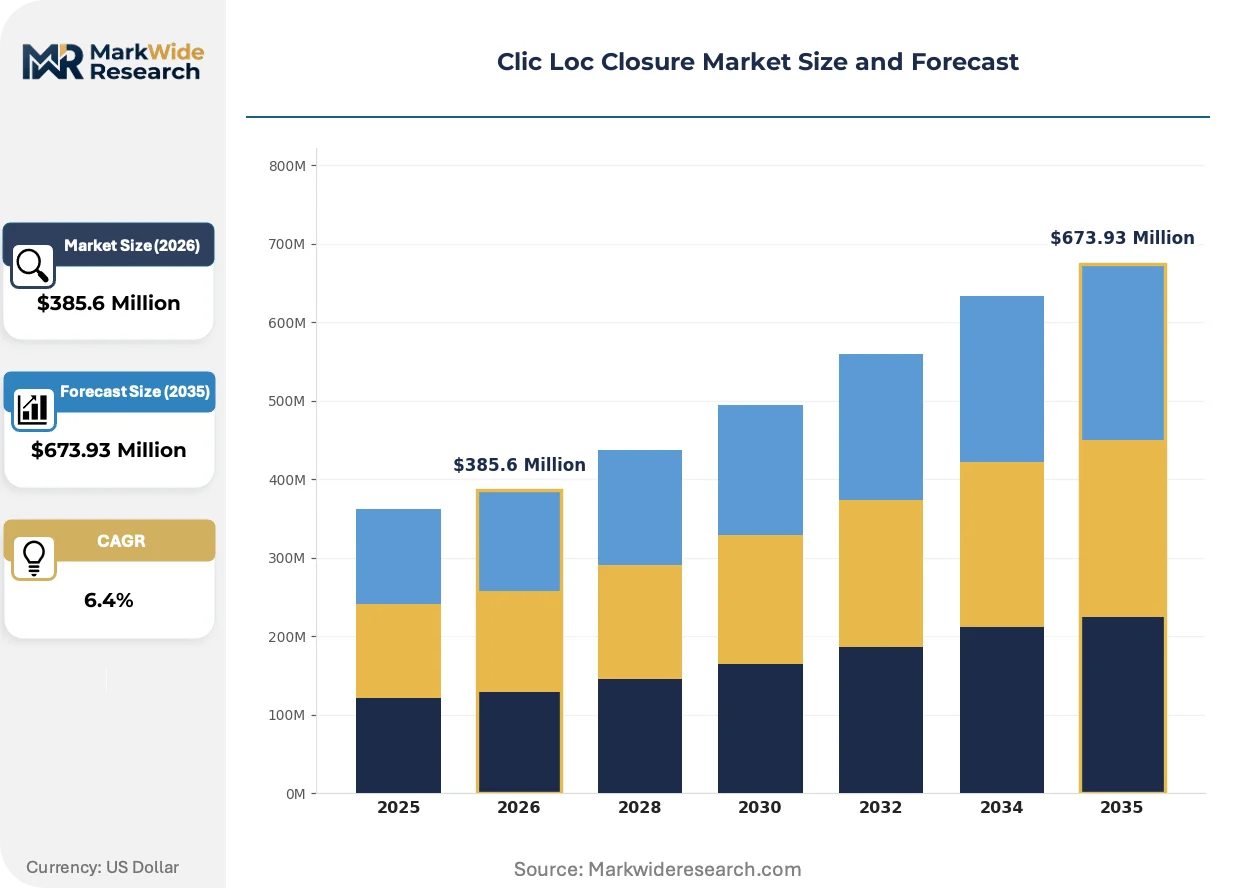
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snap Closures, Twist Closures, Flip Top Closures, Push-Pull Closures Material: Plastic, Aluminum, Glass, Composite End User: Pharmaceutical, Food & Beverage, Personal Care, Household Design Type: Standard, Child-Resistant, Custom, Reusable |
| Companies Covered | FlexiLock, ClickSure, SealTech, ClicFlex, PackShield, SecureLoc, SafeSeal, SecureClick, EcoClic Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clic Loc Closure Market Strategic Shifts
Digital thread technologies and sustainable material platforms are converging to compress product development cycles while reconfiguring supplier qualification criteria across regulated packaging segments.
Biobased polypropylene derived from renewable feedstocks is electrifying material specification conversations among European brand owners with net-zero commitments. Pharmaceutical packagers in Germany and Switzerland are piloting these resins for non-sterile liquid formulations. The technology is electrifying competitive positioning by enabling premium pricing for suppliers with mass-balance certification and ISCC PLUS chain-of-custody documentation.
EU MDR device-labeling requirements are mandating unique device identifiers on primary packaging components, including closures for combination products. This regulatory layer is forcing molders to integrate laser-marking or molded-in datamatrix capabilities into cavity designs. Drug-device manufacturers in the Netherlands and Ireland are prioritizing suppliers with validated serialization-ready tooling.
Direct procurement relationships between closure molders and national pharmaceutical regulators are displacing traditional distributor intermediaries in quality-critical applications. Large generic drug manufacturers in India are establishing technical exchange programs with molder regulatory-affairs teams to accelerate approval timelines. This pattern is most visible in CDSCO-regulated markets where packager self-certification is replacing third-party inspection dependencies.
Clic Loc Closure Market Segmentation
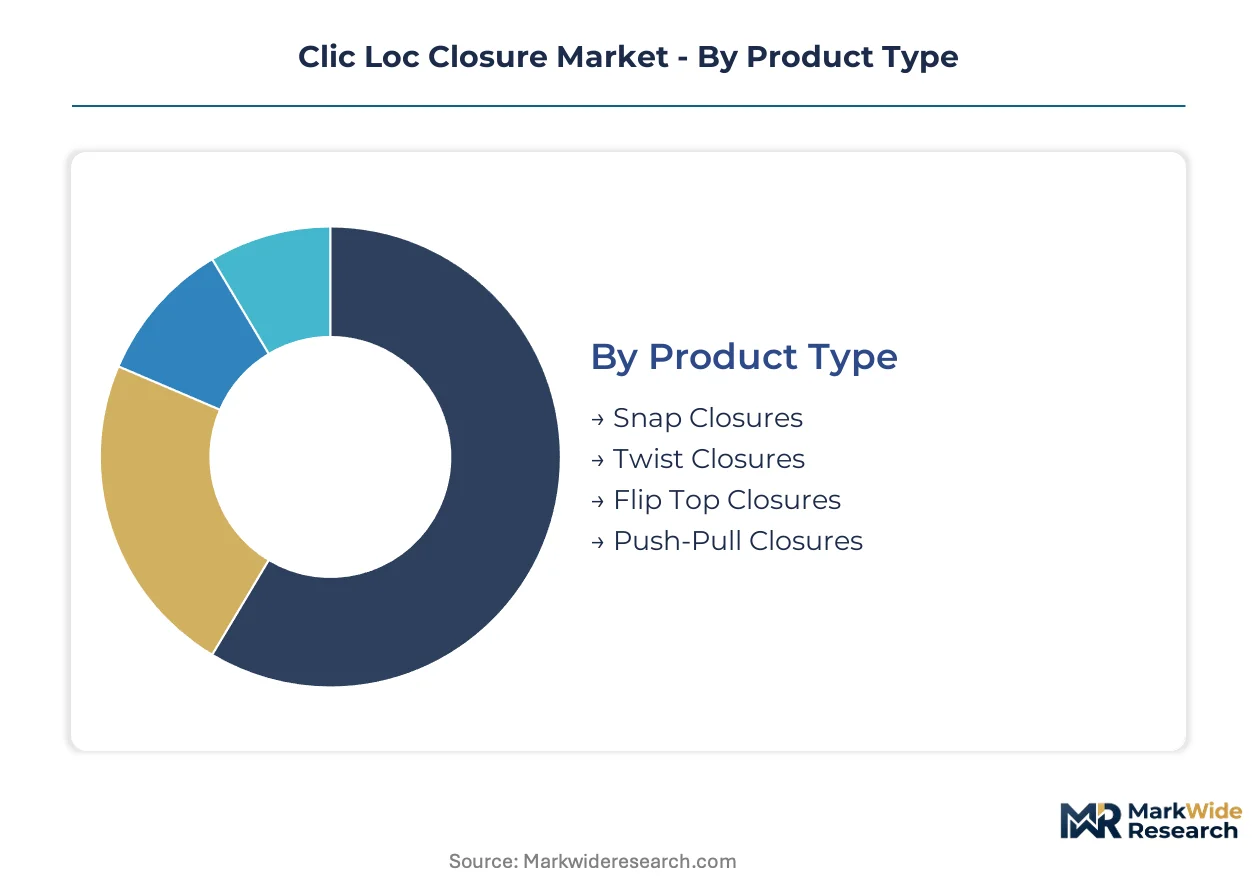
Closure geometry and material selection dictate regulatory compliance pathways and tooling investments across pharmaceutical, food, and personal-care supply chains. Segment boundaries increasingly blur as brand owners demand multi-functional configurations combining child-resistant mechanisms with tamper-evident bands.
Product Type:
Standalone dispensing closures dominate high-volume liquid applications, while embedded snap-fit geometries integrate into secondary packaging systems for subscription commerce models.
- Snap Closures:Radial snap-fit geometries molded in polypropylene enable single-handed dispensing with audible engagement feedback. Pharmaceutical packagers in Germany and India specify these for oral liquid formulations where dosing precision and child-resistant compliance converge. The format absorbs the highest tooling investment volumes due to cavity complexity for multi-component tamper-evident bands.
- Twist Closures:Helical thread engagement with molded tear-strip integration displaces separate label applications in liquid pharmaceutical filling lines. Demand clusters in Brazil where contract packagers consolidate procurement for generic drug manufacturers seeking FDA 21 CFR Part 170-189 pre-validated formats. Continuous-thread variants face margin pressure from propylene feedstock volatility.
- Flip Top Closures:Hinged lid configurations with living hinge geometries serve personal-care and household segments where one-handed access drives consumer preference.
- Push-Pull Closures:Linear actuation mechanisms with dual-position sealing suit sports nutrition and functional beverage applications requiring resealable portability.
Volume placements concentrate in Twist Closures; the faster expansion belongs to Snap Closures.
Material:
Cost tier stratification separates commodity resin formulations from certified barrier materials commanding qualification premiums in regulated pharmaceutical segments.
- Plastic:Polypropylene and HDPE formulations dominate unit economics through injection-molding scalability, with biobased variants gaining traction among European brand owners with ISCC PLUS mass-balance certification. Migration testing burdens under EMA Annex I guidelines strain analytical capacity at mid-tier suppliers.
- Aluminum:Induction-seal compatible metal closures with rolled-thread profiles serve oxygen-sensitive biologics where plastic penetration faces barrier limitations. Swiss and Dutch drug-device manufacturers specify these for high-value parenteral formulations.
- Glass:Borosilicate and soda-lime closure systems pair with pharmaceutical vials requiring inert contact surfaces for sterile applications.
- Composite:Multi-layer structures combining polymer barriers with aluminum interlayers address niche high-performance segments in European personal-care premium channels.
Plastic captures the dominant placement volumes; aluminum climbs the fastest on biologics packaging demand.
End User:
Application-specific compliance requirements fragment procurement specifications, with pharmaceutical and food-service channels imposing divergent validation protocols on shared molding assets.
- Pharmaceutical:FDA and EMA child-resistant mandates compress development cycles, forcing dedicated testing lab investments. CDSCO-regulated manufacturers in India establish direct technical exchanges with molder regulatory-affairs teams to accelerate approval timelines.
- Food & Beverage:FSSAI and FDA food-contact substance rules drive material standardization, with helical twist geometries integrating tear strips to reduce line complexity for liquid fillers.
- Personal Care:Refill-commerce subscription models in European household channels pilot reusable snap-fit configurations with durable engagement geometries.
- Household:Concentrated cleaning formulations demand chemical-resistant polypropylene compounds with enhanced stress-crack resistance.
Pharmaceutical placements lead by value; personal-care gains share fastest on reuse-model adoption.
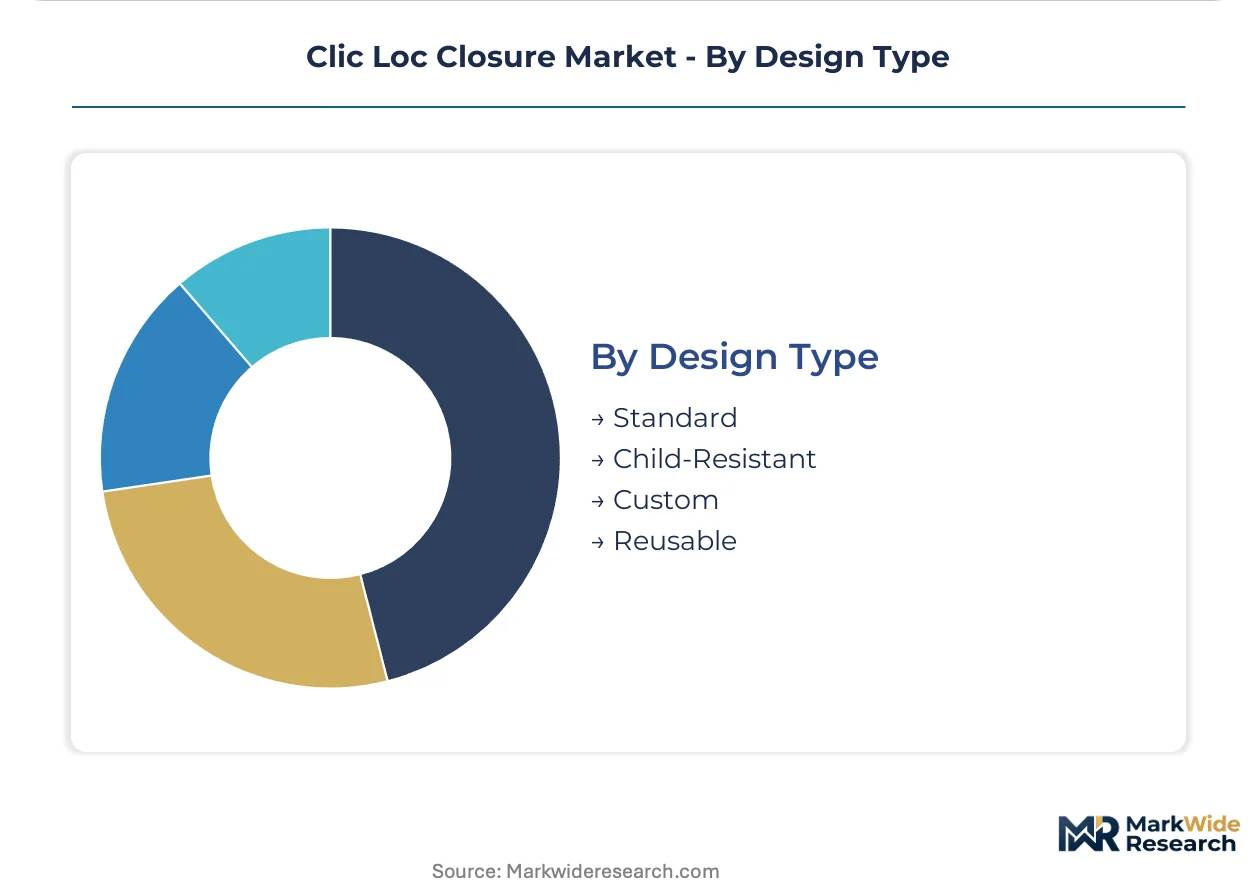
Design Type:
Margin tiering separates certified child-resistant mechanisms from standard formats, with custom development cycles and reusable configurations representing emerging capability investments.
- Standard:Basic snap or twist geometries without specialized safety features serve cost-sensitive food and industrial applications where regulatory burden remains minimal.
- Child-Resistant:ISO 8317-certified mechanisms with dual-action or press-and-turn engagement command margin premiums as FDA and EMA stringency escalates. Three-to-six-month validation cycles freeze working capital and delay product launches.
- Custom:Rapid-tooling capabilities compress development timelines for brand-specific geometries, with ClickSure-type suppliers differentiating on 12-16 week cavity fabrication acceleration.
- Reusable:Durable snap-fit configurations with extended cycle-life specifications enable refill-commerce pilots in European subscription channels, though EU Green Deal packaging waste directives will dictate future material specification priorities.
Child-Resistant designs command the premium tier by value concentration; Reusable formats show the steepest expansion trajectory on circular-economy pilot scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Pharmaceutical Special Economic Zone policy in Hyderabad and Visakhapatnam concentrates contract packaging investment, drawing closure molders toward southern manufacturing corridors with tax-abated tooling facilities.
United States
Generic drug manufacturers in New Jersey and North Carolina consolidate procurement volumes for FDA 21 CFR Part 170-189 pre-validated formats. The FDA's tightening child-resistant packaging enforcement compresses supplier qualification timelines. Philadelphia's contract packaging cluster hosts dedicated technical exchange programs between molders and regulatory-affairs teams.
Germany
Biobased polypropylene adoption accelerates among Baden-Württemberg brand owners with ISCC PLUS mass-balance certification requirements. The EU Green Deal packaging waste directives incentivize mono-material PP designs for post-consumer recycling compliance. Stuttgart's automotive-to-packaging materials crossover suppliers are repurposing compounding capacity for pharmaceutical-grade resins.
India
CDSCO-regulated manufacturers in Maharashtra and Gujarat establish direct procurement relationships with closure molders, displacing traditional distributor intermediaries. The country's national pharmaceutical regulator is streamlining self-certification pathways for packagers with validated quality systems. Hyderabad's Pharmaceutical Special Economic Zone anchors rapid scaling of regional molding footprints.
Brazil
ANVISA-aligned contract packagers in São Paulo and Rio de Janeiro consolidate volumes for generic drug manufacturers seeking export-grade closure formats. Brazil's national health surveillance agency is harmonizing child-resistant testing protocols with FDA benchmarks. The São Paulo metropolitan packaging belt is absorbing dedicated injection-molding capacity for helical twist geometries with integrated tear strips.
Switzerland
High-value parenteral formulation packagers in Basel and Zurich specify aluminum induction-seal closures for oxygen-sensitive biologics. Swissmedic's device-labeling requirements for combination products mandate unique device identifiers on primary packaging components. The Basel pharmaceutical corridor is piloting laser-marking integration into closure cavity designs for serialization-ready tooling.
Clic Loc Closure Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Clic Loc closure supply base, creating tiered capability stratification. The vendor landscape segments into three strategic archetypes: resin-integrated molders with captive compounding, dedicated child-resistant testing labs, and rapid-tooling specialists compressing custom development cycles. Capacity expansion and regulatory-affairs integration represent the dominant competitive moves, as suppliers seek to freeze working capital in validated inventory positions.
Among the named participants, FlexiLock exemplifies resin-integrated positioning through captive compounding control, while SealTech occupies a position within the regulatory-specialist tier with dedicated child-resistant design capabilities. ClickSure anchors the rapid-tooling archetype, representing suppliers that compress custom closure development cycles for brand-specific geometries.
| Leading Market Players |
|---|
| FlexiLock |
| ClickSure |
| SealTech |
| ClicFlex |
| PackShield |
| SecureLoc |
| SafeSeal |
| SecureClick |
| EcoClic Solutions |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR Part 170-189 pre-validation requirements from generic drug manufacturers in New Jersey and North Carolina are forcing closure molders to hold certified resin inventory, compressing working capital and amplifying price premiums for validated stock.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations as twelve-to-sixteen-week cavity fabrication cycles for child-resistant mechanisms create spot-market scarcity for urgent pharmaceutical launches. Three-tier pricing structure across certified child-resistant, standard tamper-evident, and economy non-specialized formats separates margin tiers by validation burden. Cost compression in standard twist closures is intensifying because propylene feedstock volatility transfers directly to spot resin contracts. Contract packagers in Brazil and India exhibit highest price sensitivity due to consolidated procurement volumes, while Swiss biologics manufacturers accept premium aluminum closure pricing for oxygen-barrier assurance.
Supply Chain Analysis
Single-source vulnerability sits with German compounding facilities supplying ISCC PLUS-certified biobased polypropylene to Baden-Württemberg brand owners. Tooling fabrication draws from China, Germany, and Switzerland, while resin supply rests on Saudi and U.S. Gulf Coast propylene production. Tariff exposure on injection-molding equipment from European suppliers threatens capacity expansion timelines for Indian contract packagers. Distribution runs through direct technical exchange programs between molders and CDSCO-regulated manufacturers, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
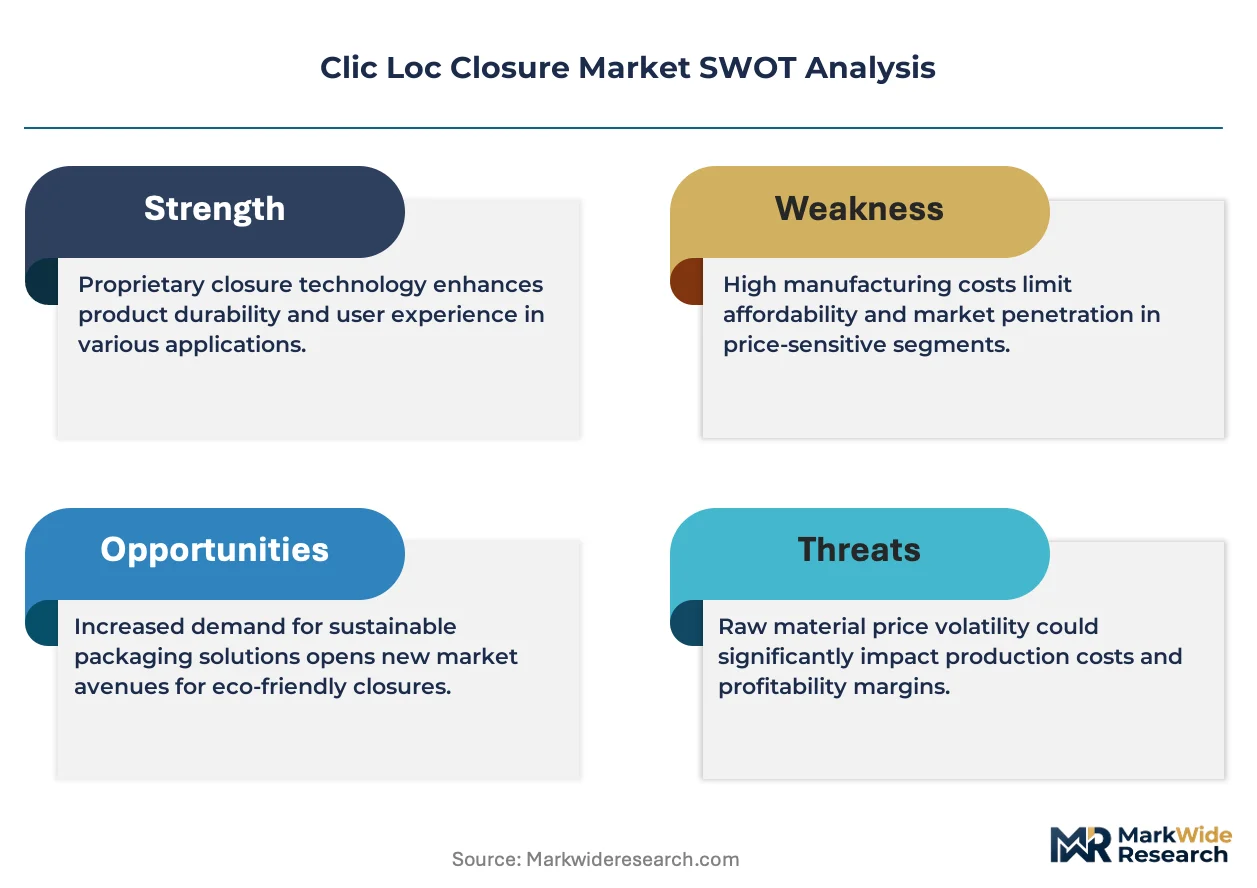
The Clic Loc closure market is becoming a vertical-integration race as suppliers pursue captive resin compounding to insulate margins from propylene volatility and secure material consistency for multi-regional compliance.
For Market Incumbents: Lock in regulatory-affairs integration by embedding dedicated child-resistant testing labs within pharmaceutical customer facilities, mirroring SealTech's North American and European service model. Add compounding capacity in Hyderabad's Pharmaceutical Special Economic Zone to capture tax-abated tooling benefits and proximity to CDSCO-regulated manufacturers consolidating procurement volumes. Defend against aluminum substitution in oxygen-sensitive biologics by developing high-barrier polymer interlayer technologies for premium pharmaceutical segments. For New Entrants and Emerging Players: Enter via reusable closure configurations for European refill-commerce subscription channels, where EU Green Deal packaging waste directives are accelerating mono-material PP specification shifts. Target personal-care subscription services in Germany and Switzerland piloting durable snap-fit geometries with extended cycle-life requirements. Establish rapid-tooling capabilities compressing custom cavity development timelines below incumbent twelve-to-sixteen-week benchmarks, replicating ClickSure's differentiation angle. For Investors and Strategic Acquirers: Re-rating potential sits with resin-integrated molders possessing ISCC PLUS mass-balance certification given biobased polypropylene adoption acceleration among European net-zero-committed brand owners. Long-term viability favors suppliers with validated serialization-ready tooling for EU MDR device-labeling compliance on combination products. Watch for inflection signals in extended producer responsibility framework implementation timelines across target jurisdictions, as post-consumer recycling mandates will reshape material specification priorities and design-for-disassembly investments.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Compounding | Insulates margins from propylene volatility while securing FDA 21 CFR Part 170-189 pre-validated material consistency. |
| Dedicated Child-Resistant Testing Labs | Compresses ISO 8317 certification timelines for pharmaceutical packagers facing tightened FDA enforcement. |
| Biobased Polypropylene Certification | Enables premium positioning among Baden-Württemberg brand owners with ISCC PLUS mass-balance requirements. |
| Serialization-Ready Tooling Investment | Captures EU MDR device-labeling demand from Dutch and Irish drug-device manufacturers requiring laser-marking integration. |
| Regional Molding Footprint Expansion | Aligns with Hyderabad and Visakhapatnam Pharmaceutical Special Economic Zone tax incentives for contract packaging scaling. |
Study Parameters
Document review covered FDA 21 CFR filings, EMA Annex I pharmaceutical packaging guidelines, and ISCC PLUS chain-of-custody documentation, complemented by interviews with closure molder regulatory-affairs directors, pharmaceutical contract packaging procurement leads, and CDSCO technical exchange program managers. Secondary validation drew from customs and trade data, SEC 10-K filings of diversified packaging conglomerates, and EU Green Deal packaging waste directive implementation tracking. Bottom-up and top-down triangulation cross-referenced regional molding capacity investments against consolidated procurement volumes from third-party packagers.
Historical shipment data was cross-referenced against panel input from plant managers at German and Indian injection-molding facilities across the modeling period. Segmentation dimensions modeled include closure geometry type, material formulation tier, end-use regulatory cluster, and regional compliance pathway. CAGRs were derived from regression analysis of validated inventory positions and tooling investment cycles, incorporating biobased resin adoption curves and child-resistant certification queue lengths as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt polypropylene feedstock disruption or accelerated EU extended producer responsibility enforcement. Forecasts reflect assumptions around regulatory harmonization timelines and resin certification adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Vented Caps Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Cap Seals Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
End Cap Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Europe Plastic Caps and Closures Market