
 Latin America Plastic Caps and Closure Market | 2026-2036
Latin America Plastic Caps and Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Plastic Caps and Closure Market Intelligence
Beverage distributor supply chains is reconfiguring across Latin America as large-format retailers consolidate procurement volumes. Silgan Holdings Inc. leverages its Mexico manufacturing footprint to serve carbonated soft drink bottlers throughout Central America. Guala Closures Mexico SA DE CV anchors premium spirits closure demand through specialized tamper-evident designs. Amcor Ltd competes across multiple material platforms, extending its reach into Brazilian pharmaceutical applications.
Plastic caps and closures are injection-molded or compression-molded dispensing and sealing devices, typically manufactured from polypropylene or polyethylene resins with torque specifications measured in inch-pounds, designed to preserve product integrity and enable controlled consumer access. Screw caps dominate volume across Latin American beverage applications due to established capping equipment compatibility and cost-efficient high-speed production. Push-pull caps represent the fastest-growing configuration in personal care and household chemicals, where one-handed dispensing commands premium positioning. Polypropylene leads material selection for hot-fill and carbonated applications, while polyethylene terephthalate closures gain traction where optical clarity and recyclability alignment matter most.
Brazil's ANVISA enforces strict child-resistance and tamper-evidence standards for pharmaceutical closures, while Mexico's environmental regulator advances extended producer responsibility frameworks affecting post-consumer resin quotas. Argentina's national packaging authority maintains evolving migration limit protocols that shape import qualification requirements. Stakeholders must monitor regulatory divergence across Mercosur and Pacific Alliance frameworks when configuring regional product platforms and compliance investments.
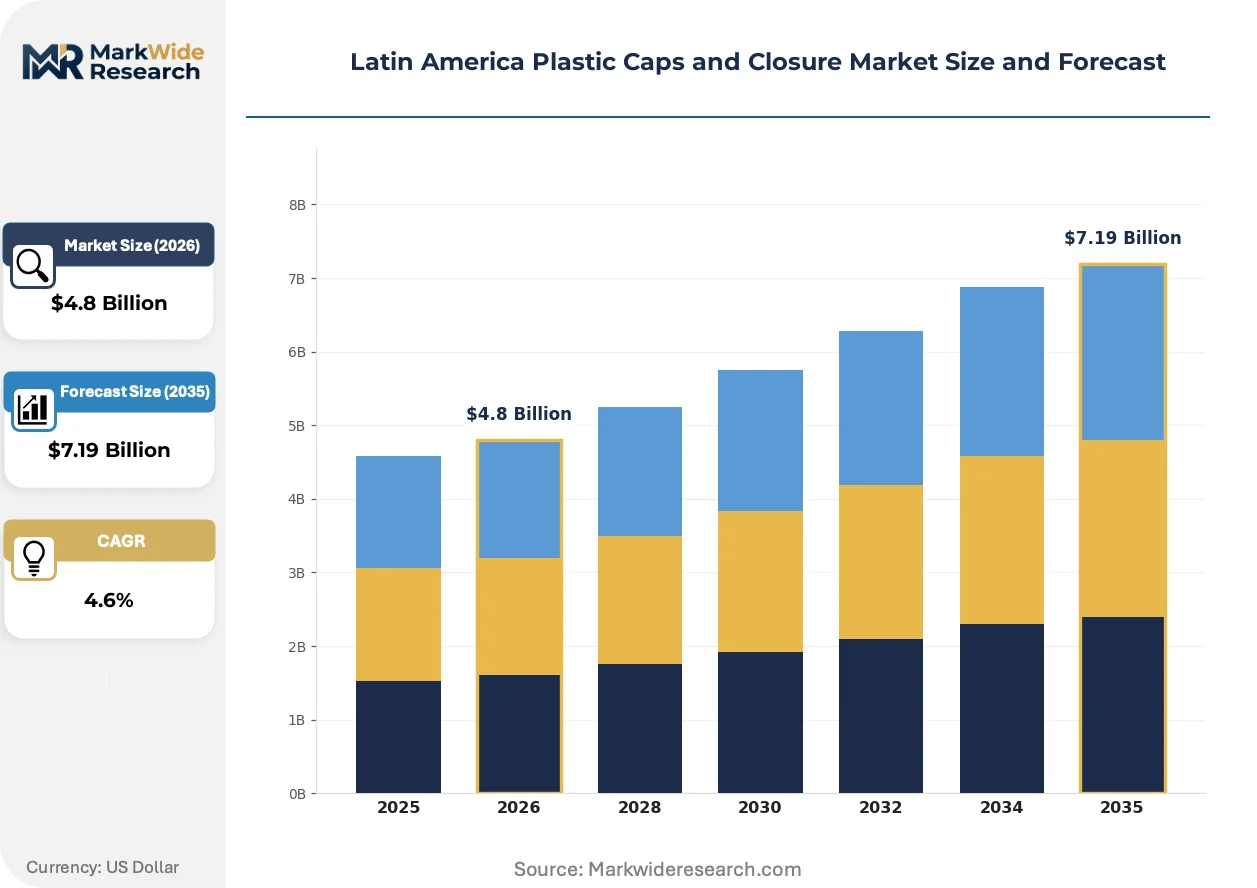
Market Dynamics
Post-consumer recycled content mandates across Brazil, Mexico, and Argentina are forcing resin qualification changes that ripple through tooling investments and supply base selection. Beverage bottlers now specify lightweight polypropylene closures with verified recycled streams, compressing margins for converters lacking integrated recycling partnerships.
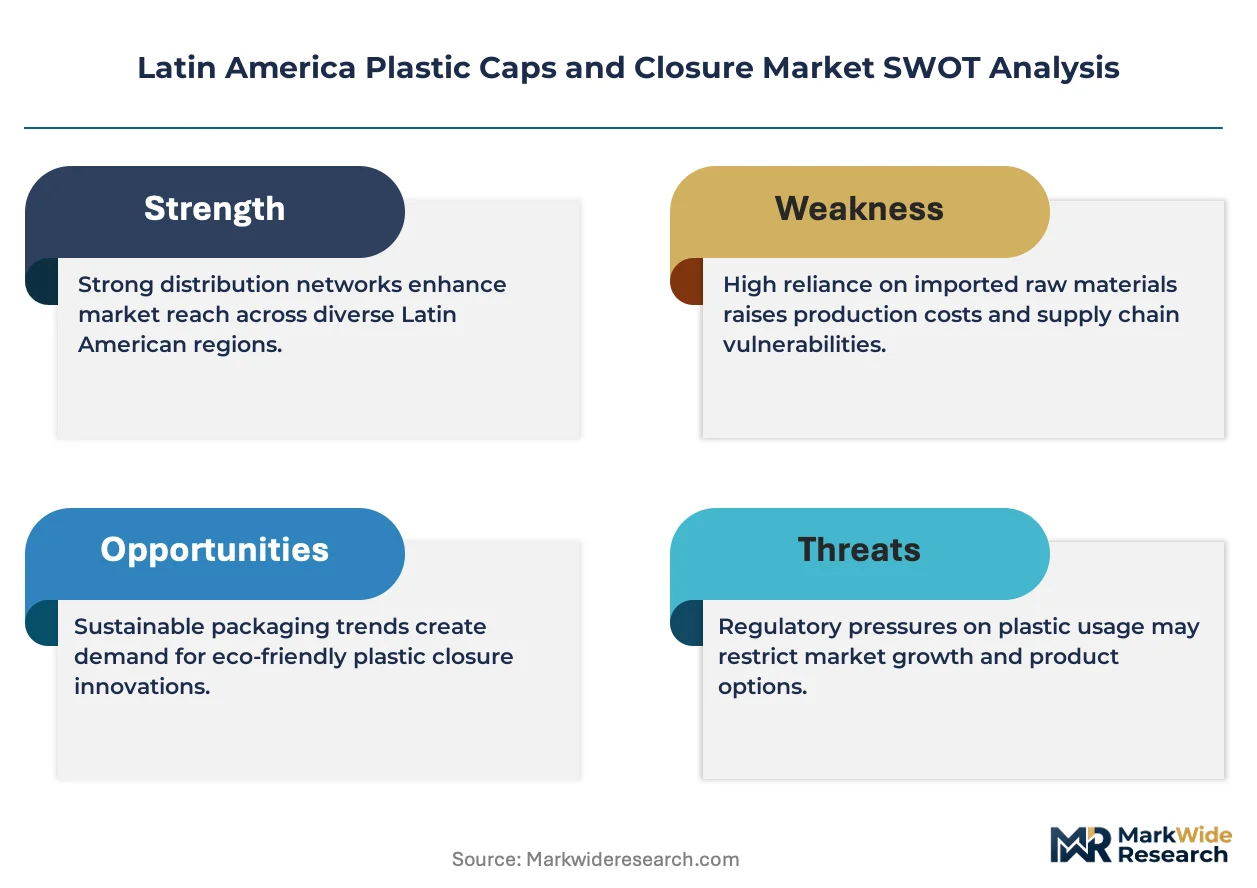
Growth Catalysts
- ANVISA pharmaceutical standards:Brazil's child-resistance and tamper-evidence requirements for medicinal packaging create specialized demand for certified closure designs that command premium positioning.
- Carbonated soft drink bottlers:Mexico's Guadalajara packaging cluster drives volume for high-torque polypropylene screw caps compatible with existing high-speed capping lines.
- Lightweighting technology:Compression-molded closures with reduced wall thickness cut resin consumption by 12-15% per unit while maintaining seal integrity under carbonation pressure.
Market Restraints
- Polypropylene resin volatility:Propylene feedstock price swings tied to regional refinery capacity constrain margin predictability for converters serving price-sensitive beverage segments.
- Tooling concentration:High-cavitation mold fabrication concentrates among São Paulo and Monterrey suppliers, creating lead time vulnerability for new product qualification cycles.
- Migration limit protocols:Argentina's evolving additive approval timelines delay import qualification for European and Asian closure suppliers seeking market entry.
Strategic Opportunities
- Colombian Andean corridor:Underpenetrated personal care manufacturing in Bogotá offers white space for push-pull dispensing caps as local formulators expand household chemical production.
- Extended producer responsibility:Mexico's advancing post-consumer resin quotas create first-mover advantage for converters with verified mechanical recycling partnerships.
- Digital printing convergence:Direct-to-closure decoration technology enables SKU proliferation without label inventory, serving craft spirits brands in Jalisco and São Paulo states.
Industry Challenges
- Hot-fill process engineering:Qualified technicians for linerless polypropylene closure design remain scarce across Brazilian converter operations, extending development timelines.
- Multi-jurisdiction compliance:Divergent Mercosur versus Pacific Alliance testing protocols force redundant certification investments for pan-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Plastic Caps and Closure Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Tops, Screw Caps, Snap Caps, Push-Pull Caps Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyethylene Terephthalate End User: Food & Beverage, Pharmaceutical, Personal Care, Household Chemicals Closure Size: Small, Medium, Large, Extra Large |
| Companies Covered | Silgan Holdings Inc., Albéa Reynosa, Guala Closures Mexico SA DE CV, Bericap, AptarGroup Inc., Amcor Ltd, Crown Holdings Inc., Closure Systems International Inc., Berry Global Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Plastic Caps and Closure Market Strategic Shifts & Innovations
Closure design is pivoting toward material circularity and dispensing convenience, with regulatory pressure and retail consolidation accelerating specification changes faster than equipment replacement cycles.
Compression-molded polypropylene closures with integrated tamper-evident bands are migrating from carbonated beverages into ambient juice and dairy applications. Mexican bottlers in the Guadalajara corridor have adopted these designs for hot-fill lines previously limited to injection-molded alternatives. The shift is compressing demand for separate liner inserts and reducing capping equipment changeover complexity.
Brazil's ANVISA pharmaceutical packaging regulations now mandate child-resistance certification for all new over-the-counter drug introductions. The industrial consequence is a qualification bottleneck at São Paulo testing laboratories, extending product launch timelines by 4-6 months. Pharmaceutical contract packers are responding by pre-qualifying closure designs across multiple resin grades to maintain formulation flexibility.
Large-format retailers in São Paulo and Mexico City are consolidating procurement volumes through direct supplier agreements, displacing traditional distributor intermediaries. Beverage bottlers now negotiate closure specifications at headquarters level rather than through regional purchasing offices. The concentration is most visible among private-label water brands where SKU rationalization favors standardized 28mm neck finishes across multiple bottling partners.
Latin America Plastic Caps and Closure Market Segmentation
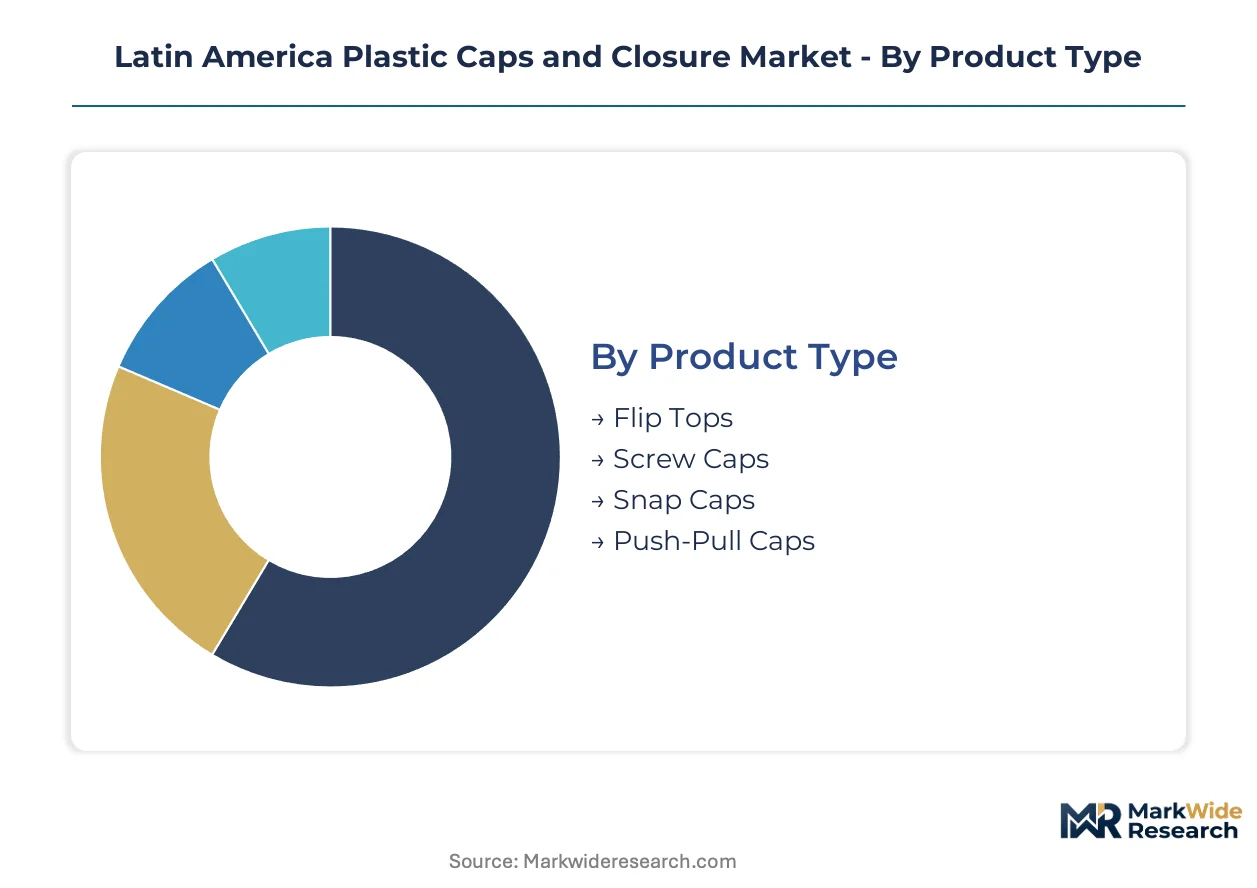
Plastic caps and closures serve distinct functional requirements across Latin American packaging applications. Segment-specific tooling investments and resin qualification protocols create divergent margin profiles for converters serving beverage bottlers versus pharmaceutical contract packers.
Product Type:
After-sales service intensity varies sharply by closure mechanism complexity, with tamper-evident and child-resistant designs demanding specialized technical support.
- Screw Caps:Threaded polypropylene or polyethylene closures with specified torque ranges measured in inch-pounds. Demand concentrates in Brazil's São Paulo industrial corridor where carbonated soft drink bottlers require high-speed capping line compatibility.
- Push-Pull Caps:One-handed dispensing mechanisms with integrated spouts and venting channels. Personal care formulators in Mexico's Guadalajara cluster specify these for shampoo and conditioner bottles, with momentum accelerating as local household chemical production expands.
- Flip Tops:Hinged polypropylene designs with living hinge fatigue resistance specifications. Brazilian pharmaceutical contract packers favor these for over-the-counter liquid medications under ANVISA child-resistance guidelines.
- Snap Caps:Interference-fit closures requiring precise diameter tolerances for seal integrity. Dairy processors in Argentina specify snap-fit designs for ambient milk cartons where cost minimization outweighs dispensing convenience.
Screw caps hold the largest share; momentum sits with push-pull configurations.
Material:
Cost tier stratification separates commodity resin grades from specialized optical and barrier formulations.
- Polypropylene:Semi-crystalline thermoplastic with hot-fill temperature resistance and carbonation pressure tolerance. Beverage bottlers across Mexico specify homopolymer grades for lightweighting initiatives that cut resin consumption.
- Polyethylene:Low-density and linear-low-density grades offering flexibility and stress-crack resistance. Personal care brands in Colombia select polyethylene closures for squeeze tube compatibility.
- Polyethylene Terephthalate:Amorphous polyester with optical clarity matching bottle resin for recyclability alignment. Premium water brands in São Paulo state specify PET closures to satisfy retailer post-consumer recycled content mandates.
- Polyvinyl Chloride:Rigid compound with chemical resistance for aggressive household formulations. Industrial chemical packers in Monterrey retain PVC specifications where cost floors override sustainability positioning.
Polypropylene dominates volume; PET closures are expanding most quickly.
End User:
Application-specific regulatory burdens create divergent qualification timelines and margin structures.
- Food & Beverage:Closure specifications governed by migration limits and organoleptic neutrality requirements. Brazil's ANVISA and Mexico's national food safety authority enforce additive approval protocols that extend import qualification cycles.
- Pharmaceutical:Child-resistance and tamper-evidence certifications mandatory for all new drug introductions. São Paulo testing laboratories face qualification bottlenecks extending product launch timelines.
- Personal Care:Dispensing convenience and aesthetic differentiation drive specification changes. Colombian formulators in Bogotá represent underpenetrated demand for push-pull dispensing innovation.
- Household Chemicals:Chemical compatibility and thread seal integrity prioritize functional performance over material circularity. Argentine packers navigate evolving additive approval timelines from the national packaging authority.
Food and beverage captures the largest share; pharmaceutical commands the steepest expansion trajectory.
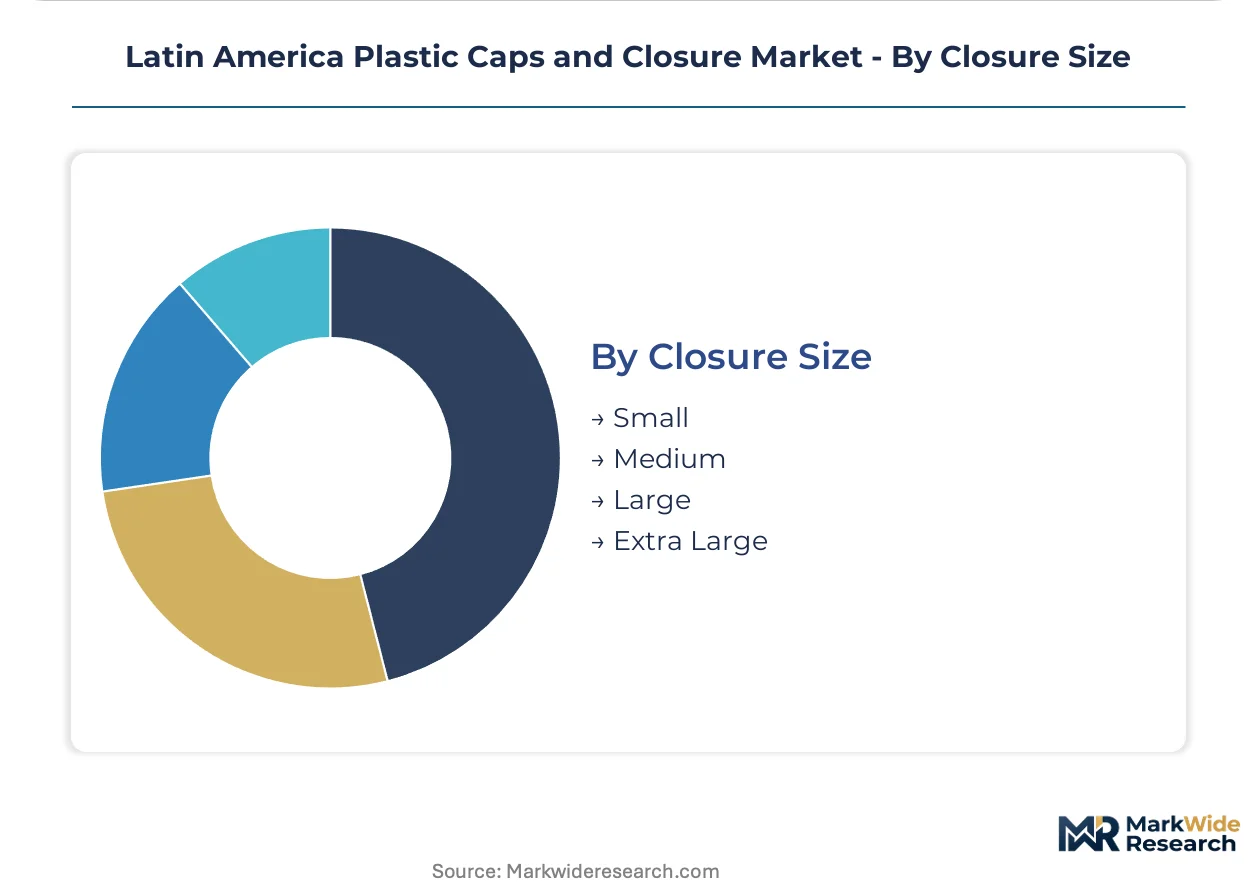
Closure Size:
Volume concentration patterns align with bottling line standardization and retail private-label consolidation.
- Small:Diameters under 28mm for single-serve beverages and travel-size personal care. Convenience store chains in Mexico City specify small closures for on-the-go consumption formats.
- Medium:28-38mm neck finishes dominating carbonated soft drink and water applications. Large-format retailers consolidate procurement around standardized medium closures.
- Large:38-48mm diameters for edible oils, sauces, and industrial chemicals. Brazilian food processors specify large closures for hot-fill aseptic lines.
- Extra Large:Diameters exceeding 48mm for institutional and food-service containers. Limited demand concentrates in São Paulo state's commercial catering supply chain.
Medium closures hold the largest share; small formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands premium positioning for pharmaceutical-grade closures while Mexican beverage bottlers extract volume discounts through consolidated procurement. Argentina's regulatory complexity inflates compliance costs, compressing margins for converters lacking local testing partnerships.
Brazil
ANVISA pharmaceutical standards drive specialized demand for child-resistant and tamper-evident closure designs. São Paulo state's industrial corridor concentrates carbonated soft drink bottling operations requiring high-torque polypropylene screw caps. Compression-molded lightweight closures with integrated tamper bands are displacing injection-molded alternatives in Guarulhos packaging facilities.
Mexico
Guadalajara's packaging cluster anchors volume demand for hot-fill compatible polypropylene closures serving carbonated beverage bottlers. The country's environmental regulator advances extended producer responsibility frameworks mandating verified post-consumer recycled content quotas. Large-format retailers in Mexico City consolidate procurement through direct supplier agreements, eliminating traditional distributor intermediaries.
Argentina
The national packaging authority maintains evolving migration limit protocols that extend import qualification timelines for European and Asian closure suppliers. Buenos Aires pharmaceutical contract packers navigate additive approval bottlenecks when sourcing certified child-resistant designs. Dairy processors in Córdoba specify snap-fit closures for ambient milk cartons where cost minimization outweighs dispensing convenience.
Colombia
Bogotá's underpenetrated personal care manufacturing base offers expansion opportunity for push-pull dispensing caps as local formulators expand household chemical production. The Andean corridor lacks qualified technicians for linerless polypropylene closure design, extending development timelines for converters entering the market. Medellín-based bottlers increasingly specify standardized 28mm neck finishes to align with regional procurement consolidation.
Chile
Santiago's premium water brands specify polyethylene terephthalate closures to satisfy retailer post-consumer recycled content mandates and optical clarity requirements. The country's mining-chemical supply chain generates limited but stable demand for rigid polyvinyl chloride closures in aggressive industrial formulations. Valparaíso port logistics support import-dependent resin qualification for converters serving Pacific Alliance export markets.
Latin America Plastic Caps and Closure Market Key Industry Players
Integrated multinationals and specialized regional converters split the market along beverage-pharmaceutical fault lines. Silgan Holdings Inc. leverages Mexico manufacturing to serve Central American carbonated soft drink bottlers with scale-driven cost structures. Guala Closures Mexico SA DE CV anchors premium spirits demand through specialized tamper-evident design capabilities. Amcor Ltd competes across multiple material platforms, extending reach into Brazilian pharmaceutical applications requiring ANVISA certification. Strategic moves concentrate on lightweighting technology licensing and post-consumer recycled resin partnership formation.
Within the premium-tier vector, Guala Closures Mexico SA DE CV exemplifies specialized tamper-evident expertise for spirits applications. Silgan Holdings Inc. occupies a position representing scale-driven beverage supply across Central America. Amcor Ltd sits within the diversified material platform archetype, spanning polypropylene, polyethylene, and polyethylene terephthalate closure technologies. These three anchors illustrate how geographic proximity to Guadalajara and São Paulo industrial corridors, combined with regulatory pre-qualification investments, determines competitive positioning in a market where ANVISA certification timelines create four-to-six-month entry barriers for unqualified suppliers.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Albéa Reynosa |
| Guala Closures Mexico SA DE CV |
| Bericap |
| AptarGroup Inc. |
| Amcor Ltd |
| Crown Holdings Inc. |
| Closure Systems International Inc. |
| Berry Global Inc. |
| Others |
Cost & Logistics Intelligence
Polypropylene resin volatility tied to regional refinery capacity determines both pricing tier spreads and supply chain configuration across Latin American closure markets. Converters serving price-sensitive beverage segments face compressed margins when propylene feedstock swings coincide with lightweighting mandates that demand new tooling investments.
Pricing Analysis
Customization-premium spreads separate ANVISA-certified pharmaceutical closures from commodity beverage screw caps. Three-tier pricing structure across premium certification-grade, standard volume-scale, and economy unbranded tiers reflects divergent qualification burdens. Cost compression in the economy tier is intensifying as Brazilian bottlers consolidate procurement volumes through direct retailer agreements. Pharmaceutical contract packers show least price sensitivity due to four-to-six-month certification timelines that lock in supplier relationships.
Supply Chain Analysis
Export-control restrictions on high-cavitation mold fabrication technology limit supplier qualification outside São Paulo and Monterrey industrial corridors. Tooling fabrication draws from specialized Brazilian and Mexican machine shops, while resin supply rests on Gulf Coast petrochemical imports and regional refinery output. Single-source vulnerability concentrates in compression-molding equipment where qualified technicians remain scarce. Distribution runs through direct agreements with large-format retailers that displace traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where ANVISA certification timelines create switching costs that entrench pre-qualified suppliers. Regulatory entrenchment rewards early movers who absorbed qualification bottlenecks at São Paulo testing laboratories.
For Market Incumbents: Harden defensive positioning through backward integration into post-consumer recycled resin streams that satisfy Mexico's advancing extended producer responsibility quotas. Lock in channel control by pre-qualifying closure designs across multiple resin grades to maintain pharmaceutical formulation flexibility. Capacity addition in Guadalajara packaging cluster captures volume consolidation among carbonated soft drink bottlers. For New Entrants and Emerging Players: Colombian Andean corridor personal care formulators in Bogotá represent the most penetrable entry point for push-pull dispensing caps where qualified technician scarcity has delayed incumbent deployment. Target verified mechanical recycling partnerships as the go-to-market angle that satisfies retailer post-consumer content mandates without legacy tooling conversion burdens. For Investors and Strategic Acquirers: Mexico's extended producer responsibility framework reshapes the acquisition landscape toward converters with certified recycling partnerships rather than pure volume scale. Long-term viability across the analysis window favors targets with ANVISA pre-qualification and linerless polypropylene design capabilities. Watch for regulatory alignment between Mercosur and Pacific Alliance testing protocols as the signal for pan-regional consolidation feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Recycled Resin Partnership | Verified mechanical recycling streams satisfy Mexico's environmental regulator quotas ahead of compliance deadlines. |
| Lightweighting Technology Licensing | Compression-molded designs with reduced wall thickness cut resin consumption while maintaining seal integrity. |
| Direct-to-Retailer Procurement Agreements | Bypassing distributor intermediaries captures volume consolidation among São Paulo and Mexico City large-format retailers. |
| Digital Printing Convergence Investment | Direct-to-closure decoration enables SKU proliferation without label inventory for craft spirits brands. |
| ANVISA Certification Pre-Qualification | Child-resistance and tamper-evidence certification at São Paulo laboratories creates four-to-six-month entry barriers. |
Research Approach
The analysis maps screw cap, push-pull, flip top, and snap cap configurations, each validated through procurement directors at beverage bottlers, pharmaceutical contract packers, personal care formulators, and household chemical processors. Primary interviews with plant managers at Guadalajara and São Paulo packaging facilities combined with secondary validation from ANVISA regulatory filings, Brazilian customs trade data, and SEC disclosures from listed packaging multinationals. Bottom-up unit volume estimates triangulated against top-down resin consumption figures from regional petrochemical associations.
Assumptions held fixed include ANVISA pharmaceutical standards enforcement intensity and polypropylene resin price volatility bands, while variables tested included post-consumer recycled content mandate acceleration timelines and retailer procurement consolidation rates. Segmentation dimensions modeled encompass closure mechanism type, material grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections that incorporate tooling replacement cycles and qualification timeline bottlenecks. Industry-specific inputs include compression-molding adoption curves and linerless closure technician availability indices.
Practitioners should monitor regulatory divergence between Mercosur and Pacific Alliance testing protocols for early signals of compliance cost inflation. Forecasts reflect assumptions regarding ANVISA certification timeline stability and propylene feedstock price band persistence. Material shifts in extended producer responsibility quota enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
End Cap Market
Caps and Closures
Spray Caps Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Cover Caps Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Foam End Caps Market
Caps and Closures
Canada Plastic Caps and Closures Market