
 Ribbed Phenolic Caps Market | 2026-2036
Ribbed Phenolic Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Ribbed Phenolic Caps Market Analytics
ISO 8317 child-resistant certification is reorganizing competitive standing among phenolic closure suppliers. O.Berk leverages its deep catalog of certified stock closures to sustain pharmaceutical customer relationships across North American distribution channels. Feldman Industries anchors its position through dedicated phenolic molding capacity and precision threading capabilities for small-batch pharmaceutical orders. Berry Global Inc competes at scale with multi-material closure platforms that extend manufacturing reach into complementary polypropylene segments.
Ribbed phenolic caps are thermoset closures molded from phenol-formaldehyde resin, featuring radial ridges that enhance torque grip and mechanical stability during automated capping operations. The material delivers chemical resistance to essential oils, solvents, and alkaline formulations, making these closures standard for oral pharmaceutical bottles, laboratory reagents, and industrial chemical containers. Child-resistant caps command premium positioning due to ISO 8317 testing burdens and patent-protected mechanism designs that limit supplier proliferation. Screw caps dominate volume throughput in pharmaceutical applications where hermetic seal integrity and liner compatibility with desiccant inserts determine specification adherence. Snap-on variants occupy faster-growing niches in diagnostic kit packaging where assembly speed outweighs reseal requirements.
FDA 21 CFR regulations on child-resistant packaging and EMA guidance for tamper-evident closures create dual compliance thresholds that filter regional market access. REACH restrictions on formaldehyde emissions from phenolic resin curing affect European manufacturing cost structures and trigger reformulation investments. Stakeholders must monitor evolving EPA standards for phenol emissions at molding facilities and assess liner material transitions driven by state-level PFAS restrictions.
Market Dynamics
ISO 8317 child-resistant certification requirements are compressing supplier margins while simultaneously filtering market access, creating a bifurcation between certified phenolic closure specialists and commodity thermoset molders unable to absorb testing burdens.
Growth Catalysts
- FDA 21 CFR child-resistant mandates:Oral medication packaging regulations in the United States compel pharmaceutical manufacturers to source certified closures, sustaining premium demand for compliant phenolic caps.
- Generic drug manufacturing expansion:Compounding pharmacy activity and contract manufacturing organizations in North America drive consistent volume throughput for standard screw-cap configurations.
- Thermoset material properties:Phenol-formaldehyde resin delivers chemical resistance to essential oils and alkaline formulations that thermoplastics cannot match, anchoring specification in laboratory reagent applications.
Market Restraints
- Formaldehyde input cost volatility:Petrochemical feedstock fluctuations and energy-intensive curing processes compress molding margins, particularly for small-batch pharmaceutical orders.
- REACH emission controls:European phenol emission limits at thermoset facilities add compliance overhead that disadvantages mid-cap suppliers lacking captive resin synthesis.
- Polypropylene substitution threat:Multi-material closure platforms with integrated child-resistant mechanisms displace pure phenolic caps in high-volume over-the-counter segments.
Strategic Opportunities
- Diagnostic kit packaging expansion:Snap-on phenolic variants address assembly-speed requirements in point-of-care testing kits where reseal functionality is secondary.
- State-level PFAS liner restrictions:California and New York regulations on perfluoroalkyl substances force liner material transitions, creating specification windows for compliant phenolic suppliers.
- Desiccant insert integration:Hermetic seal compatibility with silica gel and molecular sieve inserts opens moisture-sensitive pharmaceutical applications beyond standard oral solids.
Industry Challenges
- ISO 8317 certification timeline compression:Extended testing protocols for child-resistant mechanisms delay new product introductions by 12-18 months, freezing supplier innovation cycles.
- Precision threading skill scarcity:Automated capping line compatibility demands sub-millimeter tolerance control that legacy thermoset molders struggle to maintain without capital-intensive CNC retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ribbed Phenolic Caps Market |
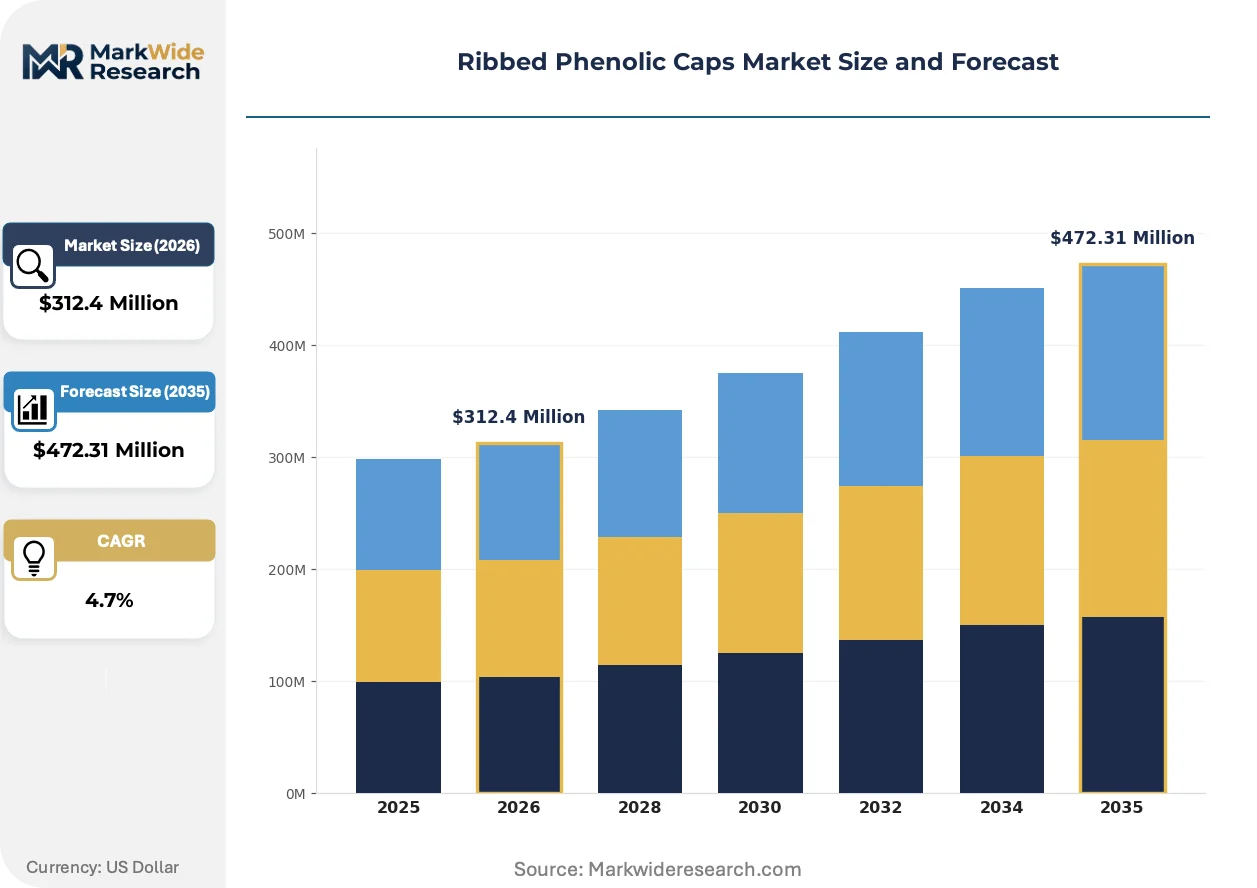
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Caps, Child-Resistant Caps, Snap-On Caps, Screw Caps Material: Phenolic, Polypropylene, Polyethylene, Glass Closure Size: 20mm, 24mm, 28mm, 38mm Application: Pharmaceuticals, Cosmetics, Food & Beverage, Chemicals |
| Companies Covered | O.Berk, Pacific Vial, WB Bottle, Feldman Industries, United Caps, MJS Packaging, Pipeline Packaging, Illing Company, Berry Global Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ribbed Phenolic Caps Market Evolving Landscape
Closure miniaturization and liner material transitions are compressing traditional phenolic cap architectures while regulatory emission controls force manufacturing process reinvention across thermoset supply chains.
Threaded closure geometries are miniaturizing as pharmaceutical bottle neck finishes shrink to 20mm and 24mm standards for pediatric dosing convenience. Generic drug manufacturers in the United States are adopting these reduced-dimension formats at accelerated pace to differentiate shelf presence. This dimensional compression is miniaturizing phenolic resin throughput per unit while demanding tighter torque-tolerance molding capabilities that filter supplier bases.
REACH formaldehyde emission restrictions are compelling European phenolic molders to invest in low-emission curing ovens and resin reformulation. The industrial consequence is a 15-20% capacity cost premium that certified suppliers absorb through pharmaceutical contract premiums while commodity players exit. Small-batch pharmaceutical orders in Germany and France face elongated lead times as compliant capacity concentrates among integrated resin-to-closure manufacturers.
Certification-driven procurement consolidation is compressing buyer-supplier relationships toward sole-source arrangements with ISO 8317-certified molders. Pharmaceutical packaging managers are replacing spot-buying through distribution with direct multi-year contracts that lock capacity and guarantee audit traceability. This behavioral shift is most visible in United States generic drug manufacturing clusters where FDA inspection readiness demands documented closure lineage.
Ribbed Phenolic Caps Market Segmentation
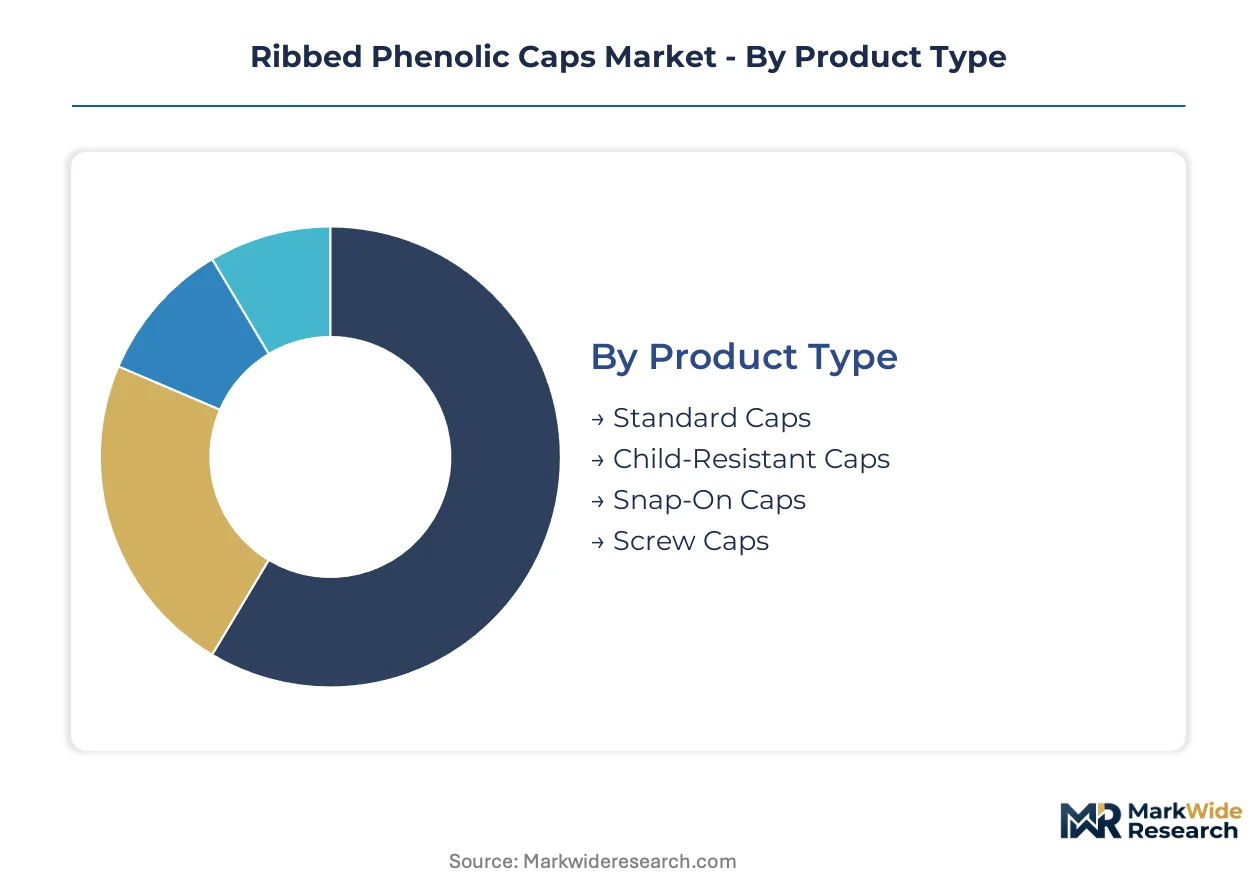
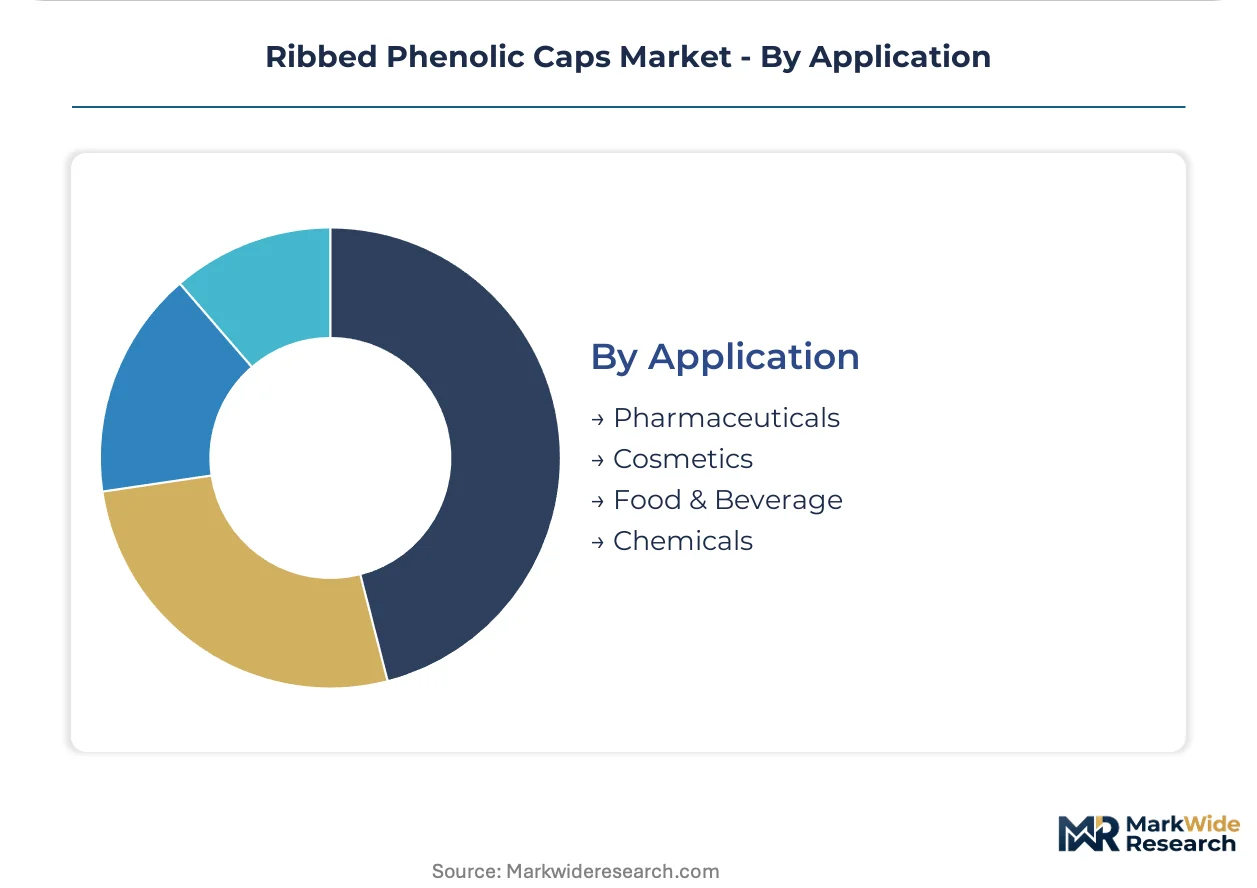
Segmentation in the ribbed phenolic caps market reflects divergent compliance burdens and material substitution pressures that reshape procurement patterns across end-use verticals. Pharmaceutical buyers prioritize ISO 8317-certified configurations while industrial chemical purchasers trade child-resistant premiums for chemical resistance performance.
Product Type:
FDA 21 CFR and EMA child-resistant mandates create tiered compliance obligations that segment pricing power and supplier qualification requirements across closure architectures.
- Child-Resistant Caps:ISO 8317-certified mechanisms with push-and-turn or squeeze-and-turn designs command specification in oral pharmaceutical packaging. FDA enforcement in the United States and EMA guidance in Germany and France sustain premium positioning despite 15-20% cost premiums over standard alternatives.
- Screw Caps:Continuous helical threading delivers hermetic seal integrity for laboratory reagents and moisture-sensitive formulations. Generic drug manufacturers in the United States specify these configurations for standard oral solids where reseal functionality outweighs child-resistant requirements.
- Standard Caps:Non-specialized phenolic closures serve industrial chemical and cosmetic applications where regulatory compliance burdens remain minimal.
- Snap-On Caps:Friction-fit designs enable rapid assembly in diagnostic kit packaging. Point-of-care testing manufacturers in California and Massachusetts adopt these variants where throughput speed dominates reseal considerations.
Screw caps handle the majority of throughput; snap-on caps are expanding most quickly on share.
Material:
Cost tier differentiation separates thermoset heritage formulations from thermoplastic substitutes that erode phenolic dominance in volume-sensitive segments.
- Phenolic:Phenol-formaldehyde thermoset resin delivers chemical resistance to essential oils, solvents, and alkaline formulations that thermoplastics cannot match. REACH formaldehyde emission controls in Europe and EPA phenol standards in the United States concentrate compliant capacity among integrated resin-to-closure manufacturers.
- Polypropylene:Injection-molded thermoplastic closures with integrated child-resistant mechanisms displace phenolic alternatives in high-volume over-the-counter pharmaceutical segments. Multi-material platforms from Berry Global and competitors exploit polypropylene's lower unit cost and faster cycle times.
- Polyethylene:Flexible thermoplastic options serve cost-constrained cosmetic and food applications where chemical resistance demands remain moderate.
- Glass:Specialty closures for high-purity laboratory and diagnostic applications where inertness requirements exclude polymer alternatives.
Phenolic retains specification control in pharmaceutical compliance segments; polypropylene climbs the fastest in over-the-counter volume.
Closure Size:
Dimensional standardization in pharmaceutical bottle neck finishes concentrates demand around pediatric dosing convenience formats.
- 24mm:The dominant pharmaceutical standard for oral solid dosage bottles. Generic drug manufacturers in the United States specify this finish for automated capping line compatibility across high-speed production facilities.
- 20mm:Miniaturized format for pediatric and geriatric dosing convenience. Threaded closure geometries at this dimension demand sub-millimeter tolerance control that filters supplier bases toward precision thermoset molders.
- 28mm:Expanded diameter for liquid formulations and broader mouth access in diagnostic reagent containers.
- 38mm:Large-format closures for industrial chemical drums and laboratory reagent bottles where grip surface area outweighs miniaturization trends.
24mm handles the majority of throughput; 20mm is gaining share fastest as pediatric dosing formats proliferate.
Application:
Customer type concentration determines margin structure, with pharmaceutical procurement consolidating toward sole-source certified suppliers while chemical buyers maintain spot-buying flexibility.
- Pharmaceuticals:Oral medication packaging drives ISO 8317 certification requirements and multi-year direct contracts. FDA inspection readiness in the United States and EMA audit protocols in Europe demand documented closure lineage that compresses buyer-supplier relationships.
- Chemicals:Laboratory reagent and industrial chemical containers prioritize phenolic's chemical resistance over child-resistant functionality. Solvent exposure and alkaline formulation compatibility sustain thermoset specification despite polypropylene substitution elsewhere.
- Cosmetics:Essential oil and fragrance packaging leverages phenolic's inertness, though volume concentration remains below pharmaceutical tiers.
- Food & Beverage:Niche applications in specialty sauce and extract bottles where flavor integrity concerns exclude reactive closure materials.
Pharmaceuticals handles the majority of throughput; chemicals holds the steepest expansion trajectory as laboratory reagent demand climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical packaging managers in the United States, Germany, and Japan drive the majority of certified phenolic closure procurement. Generic drug manufacturers and compounding pharmacies concentrate demand in North American distribution corridors. European REACH compliance and Asian export manufacturing shape regional supplier qualification thresholds.
United States
FDA 21 CFR child-resistant mandates compel generic drug manufacturers to source ISO 8317-certified closures. Compounding pharmacy activity in New Jersey and North Carolina sustains small-batch phenolic orders. The FDA's inspection readiness protocols compress buyer-supplier relationships toward sole-source contracts with documented closure lineage.
Germany
EMA guidance on tamper-evident closures aligns with REACH formaldehyde emission controls to filter supplier bases. Laboratory reagent manufacturers in Baden-Württemberg specify phenolic caps for solvent resistance. The ECHA's industrial emission standards concentrate compliant thermoset capacity among integrated resin-to-closure producers near Ludwigshafen.
Japan
PMDA pharmaceutical packaging regulations and METI industrial standards create dual compliance frameworks for closure suppliers. Diagnostic kit assemblers in the Kanto region adopt snap-on phenolic variants for throughput speed. Osaka-based pharmaceutical contract manufacturers anchor demand for 20mm miniaturized formats.
China
NMPA pharmaceutical packaging standards and export-oriented manufacturing in the Yangtze River Delta shape phenolic closure production. Zhejiang and Jiangsu provinces host thermoset molding clusters serving international pharmaceutical buyers. GB standards for food-contact materials extend phenolic specification into specialty sauce and extract packaging.
India
CDSCO pharmaceutical regulations and contract manufacturing growth in Gujarat and Maharashtra drive phenolic closure adoption. Essential oil exporters in Tamil Nadu leverage phenolic's chemical inertness for fragrance packaging. The country's national pharmaceutical regulator tightens child-resistant packaging requirements for domestic oral medication markets.
Ribbed Phenolic Caps Market Competitive Landscape
Player mix skews toward certified phenolic specialists and diversified multi-material platforms. Market structure concentrates around ISO 8317-certified molders with captive resin synthesis and precision threading capabilities. Two strategic archetypes dominate: integrated resin-to-closure manufacturers absorbing REACH compliance costs, and distribution-anchored suppliers leveraging catalog depth for pharmaceutical relationships. Competitive moves center on certification timeline acceleration and sole-source contract lock-in.
Within the certified specialist tier, O.Berk and Feldman Industries exemplify archetypes of distribution-anchored and manufacturing-anchored positioning respectively. Berry Global Inc occupies a position at the scale-driven end with multi-material closure platforms. These three companies represent the spectrum from catalog-based pharmaceutical relationships through dedicated phenolic molding capacity to diversified polymer manufacturing reach.
| Leading Market Players |
|---|
| O.Berk |
| Pacific Vial |
| WB Bottle |
| Feldman Industries |
| United Caps |
| MJS Packaging |
| Pipeline Packaging |
| Illing Company |
| Berry Global Inc |
| Others |
Value Network & Pricing Analysis
Captive resin synthesis capacity at integrated German and United States facilities anchors price floors for ISO 8317-certified closures, compressing margins for non-integrated molders while elevating premiums for compliant pharmaceutical supply. Scale concentration among phenol-formaldehyde producers with in-house curing operations shapes tiered pricing power across certification grades and volume bands.
Pricing Analysis
Cost-plus contracts with formaldehyde feedstock indexation dominate long-term pharmaceutical agreements, insulating integrated suppliers from petrochemical volatility while exposing spot buyers to margin compression. Price differentiation separates ISO 8317-certified child-resistant mechanisms from standard screw-cap configurations, with certification tier and liner compatibility driving premium spreads. Pricing pressure intensifies in over-the-counter segments as polypropylene multi-material platforms undercut phenolic unit costs. Generic drug manufacturers exhibit highest price sensitivity, while FDA-inspected facilities prioritize audit traceability over per-unit savings.
Supply Chain Analysis
Strait of Malacca transit risk for phenol feedstock from Northeast Asian petrochemical hubs concentrates supply vulnerability among European molders lacking captive resin production. Manufacturing concentrates in Germany, the United States, and China's Zhejiang province, with each node serving distinct regulatory compliance clusters. Raw material dependencies span formaldehyde from methanol cracking, phenol from cumene oxidation, and liner substrates facing state-level PFAS restrictions. Tariff exposure on Chinese-molded closures into North American pharmaceutical channels threatens cost structures for non-integrated distributors. Distribution runs through direct multi-year contracts with generic drug manufacturers and compounding pharmacy networks, replacing spot-buying through industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification audit services and liner material transition consulting are expanding faster than base closure hardware, converting transactional supply relationships into recurring compliance partnerships. This service-attach dynamic repositions supplier value from unit volume to regulatory continuity assurance.
For Market Incumbents: Shield ISO 8317 certification portfolios through accelerated testing protocol investments that freeze competitor entry timelines. Extend backward integration into low-emission phenolic resin synthesis to absorb REACH compliance costs that commodity molders cannot shoulder. Lock sole-source contracts with United States generic drug manufacturers by embedding desiccant insert compatibility and documented closure lineage into multi-year agreements. Polypropylene substitution in over-the-counter segments remains the priority threat requiring differentiated chemical resistance positioning. For New Entrants and Emerging Players: Anchor in diagnostic kit packaging snap-on variants where assembly-speed requirements and lower certification burdens create specification windows. Target California and Massachusetts point-of-care testing manufacturers with PFAS-compliant liner offerings as state restrictions force incumbent material transitions. Pursue white-label manufacturing partnerships with European distributors seeking compliant capacity outside integrated German producers. The most penetrable entry vector runs through small-batch pharmaceutical orders in compounding pharmacy corridors where precision threading capabilities outweigh scale economies. For Investors and Strategic Acquirers: ISO 8317-certified molders with captive resin synthesis and precision CNC threading infrastructure represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance deepening as FDA and EMA audit protocols tighten closure lineage requirements. The inflection signal to monitor is consolidation of pharmaceutical procurement toward sole-source arrangements, compressing spot-buying channels and elevating contract-backed revenue visibility. Avoid commodity thermoset players lacking certification differentiation or emission-compliant curing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 8317 Certification Acceleration | Compresses competitor entry timelines by 12-18 months in child-resistant segments. |
| Backward Integration into Resin Synthesis | Absorbs REACH formaldehyde emission compliance costs that disadvantage non-integrated molders. |
| PFAS-Compliant Liner Development | Captures specification windows in California and New York diagnostic kit packaging channels. |
| Desiccant Insert Integration Partnerships | Expands addressable market into moisture-sensitive pharmaceutical applications beyond oral solids. |
| Precision Threading CNC Retrofit | Enables 20mm miniaturized format production for pediatric dosing convenience trends. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pharmaceutical packaging managers, thermoset molding plant engineers, and regulatory affairs specialists at FDA-registered facilities; and secondary validation through EMA submission databases, EPA emission compliance records, and United States customs trade data. The stakeholder set encompassed procurement directors at generic drug manufacturers, compounding pharmacy operators, and distribution channel partners across North American and European corridors. Bottom-up volume triangulation from molding facility capacity and top-down demand estimation from pharmaceutical packaging consumption were cross-referenced for convergence.
Across the analysis window, the forecasting framework modeled segmentation dimensions including closure type, material grade, neck finish diameter, and end-use vertical with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation of certification-driven procurement consolidation and substitution dynamics between phenolic and polypropylene platforms. Industry-specific inputs incorporated FDA inspection readiness protocols, REACH emission control phase-in schedules, and state-level PFAS restriction timelines.
Material uncertainties — formaldehyde feedstock volatility, ISO 8317 testing protocol revisions, and polypropylene multi-material platform advancement — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement continuity and pharmaceutical outsourcing trends that could shift with macroeconomic conditions. Practitioners should keep alternative scenarios live as EMA audit protocol harmonization and EPA phenol emission standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Overcaps Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Crown Closures Market