
 Global Positive Airway Pressure Market | 2026-2036
Global Positive Airway Pressure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Positive Airway Pressure Market Foresight
Modular device bundling is consolidating buyer choice around integrated mask-tubing-software ecosystems rather than standalone hardware. ResMed Inc. leverages cloud-connected platforms to sustain recurring revenue streams beyond initial device sales. Koninklijke Philips N.V. anchors its position through broad geographic distribution and hospital-grade manufacturing scale. Fisher & Paykel Healthcare Limited differentiates via humidification technology leadership and specialized mask interfaces that reduce skin breakdown incidence.
Positive Airway Pressure denotes mechanical ventilatory support delivering pressurized air through sealed interfaces to maintain pharyngeal patency, typically operating at 4–20 cm H₂O pressure ranges with flow rates calibrated to patient respiratory mechanics. The technology prevents airway collapse during sleep, reduces nocturnal desaturation events, and serves as first-line therapy for moderate-to-severe obstructive sleep apnea. CPAP Machines occupy the mature volume core where reimbursement codes are established and patient compliance protocols are standardized. APAP Devices represent the fastest-expanding product configuration as auto-titrating algorithms reduce manual pressure adjustment burden and improve long-term adherence curves. Home Care Providers channel the dominant end-user flow as remote monitoring capabilities and telehealth integration shift titration and follow-up outside traditional sleep laboratory infrastructure.
FDA 510(k) pathways govern device clearance timelines and predicate selection strategies for US market entry, while the EU MDR transition extends conformity assessment duration for European submissions. ISO 80601-2-70 electrical safety standards and IEC 62304 software lifecycle requirements shape product development roadmaps across all target markets. Stakeholders must monitor reimbursement compression dynamics and patient preference migration toward portable, travel-optimized systems as compliance expectations evolve beyond bedside-bound form factors.
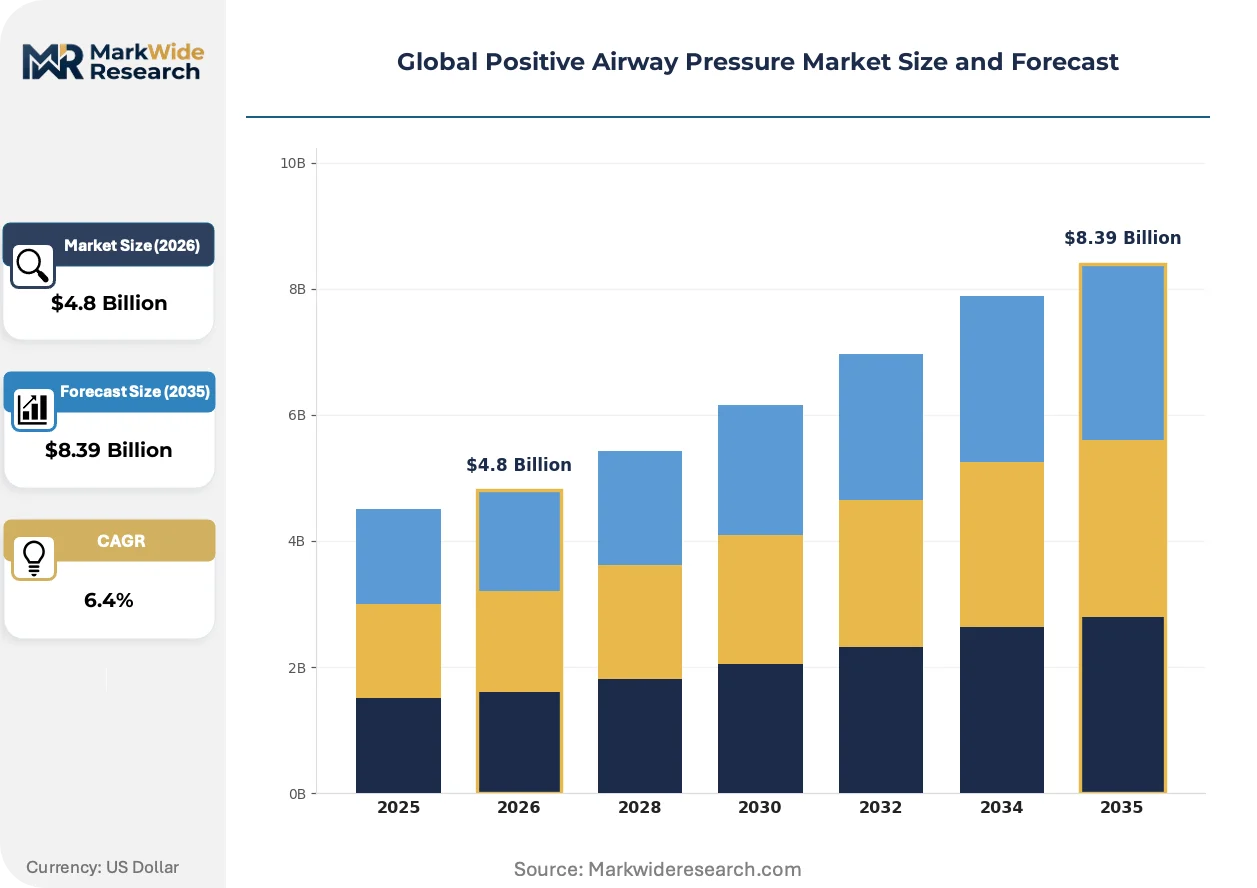
Market Dynamics
Cloud-connected respiratory platforms are restructuring competitive advantage around recurring software revenue rather than one-time device margins, forcing hardware manufacturers to build data infrastructure or cede pricing power to integrated ecosystem providers.
Growth Catalysts
- Remote patient monitoring reimbursement:Medicare coverage expansion for telehealth sleep management removes cost barriers to home-based titration. Sleep laboratories in Germany and Australia now bill for remote APAP adjustments.
- ISO 80601-2-70 electrical safety harmonization:Unified international standards reduce redundant testing costs for multi-market submissions. Device manufacturers achieve faster regulatory convergence across FDA 510(k) and EU MDR pathways.
- Aging respiratory patient populations:Japan's METI projects 40% of adults over 60 will require sleep-disordered breathing intervention by 2030. Home care providers in Osaka and Tokyo are scaling device fleet procurement.
Market Restraints
- Semiconductor component concentration:Flow sensor ASICs and pressure transducers source predominantly from Taiwanese foundries. Single-source dependency creates 14-18 week lead time volatility for device manufacturers.
- CPAP mask silicone supply rigidity:Medical-grade liquid silicone rubber prices fluctuate with petrochemical feedstock costs. Mask producers face margin compression when crude benchmarks spike.
- FDA 510(k) predicate device scarcity:Novel auto-titrating algorithms increasingly lack acceptable predicate comparisons. First-of-kind submissions trigger de novo review pathways extending clearance timelines 8-14 months.
Strategic Opportunities
- Underpenetrated Indian diagnostic infrastructure:CDSCO streamlined Class B medical device registration in 2023. Sleep apnea screening in Mumbai and Bangalore diagnostic chains remains below 15% of estimated prevalence.
- Travel-optimized miniaturization convergence:Lithium-polymer battery density improvements and micro-blower motor integration enable palm-sized CPAP units. Business travelers and airline crew segments represent untapped portable demand.
- EU MDR notified body capacity expansion:Designated body appointments for respiratory devices accelerated in 2024. Manufacturers with MDR-ready technical documentation capture first-mover advantage in European hospital tenders.
Industry Challenges
- Embedded software cybersecurity certification:IEC 62304 lifecycle documentation now requires threat modeling for cloud-connected devices. Engineering teams lack sufficient secure coding expertise to meet FDA premarket submission expectations.
- Legacy data architecture integration:Hospital sleep centers operate on decade-old polysomnography systems. API interoperability gaps force manual data reconciliation between proprietary PAP platforms and electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Positive Airway Pressure Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPAP Machines, BiPAP Devices, APAP Devices, Oxygen Concentrators Therapy Area: Obstructive Sleep Apnea, Central Sleep Apnea, Respiratory Failure, COPD Management End User: Home Care Providers, Sleep Clinics, Rehabilitation Centers, Diagnostic Laboratories Delivery Mode: Auto-Adjusting Pressure, Fixed Pressure Devices, Portable Systems, Stationary Units |
| Companies Covered | ResMed Inc., Koninklijke Philips N.V., Fisher & Paykel Healthcare Limited, Drive DeVilbiss Healthcare, BMC Medical Co., Ltd., Wellell Inc., Somnetics International, Inc., 3B Medical, Inc., Smiths Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Positive Airway Pressure Market Shifts & Advancements
Artificial intelligence inference at the device edge is compressing the gap between diagnostic titration and therapeutic delivery, eliminating the traditional multi-week laboratory-to-bedroom latency that has constrained sleep apnea treatment initiation rates.
Auto-titrating pressure algorithms with embedded respiratory event detection is unifying diagnosis and therapy into single-session workflows. Home medical equipment suppliers in Texas and Florida are deploying these systems for same-day patient onboarding. The technology is compressing specialist referral bottlenecks and shifting revenue capture from sleep physicians to durable medical equipment channels.
EU MDR Article 10 post-market surveillance requirements now mandate systematic vigilance reporting for all Class IIa respiratory devices. Manufacturers must maintain electronic systems for incident traceability across distributed patient populations. The regulation is forcing mid-size device producers to outsource quality management functions or face notified body audit failures.
Patient acquisition through direct-to-consumer channels is displacing traditional sleep specialist referrals in North American markets. ResMed and Philips have established e-commerce platforms with home sleep test bundling. This pattern concentrates most visibly in California and New York, where high-deductible health plans drive price-transparent shopping behavior among commercially insured populations.
Global Positive Airway Pressure Market Segmentation
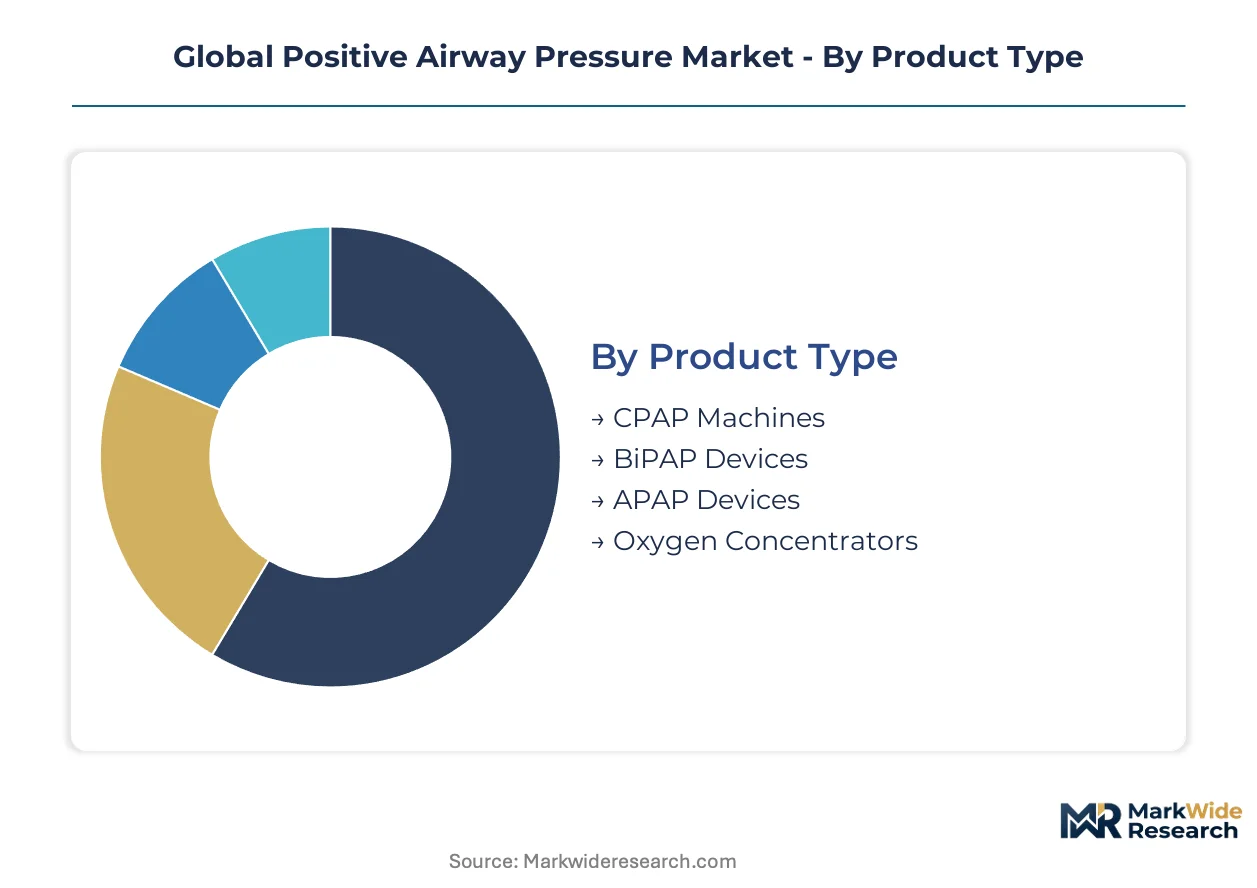
Segmentation in the Positive Airway Pressure market reveals how reimbursement pathways, patient acuity, and care setting infrastructure shape procurement patterns. Device manufacturers must align product configurations with distinct clinical workflows and compliance monitoring requirements across each segment boundary.
Product Type:
Standardization dominates at the volume core while premium tiers concentrate around algorithmic sophistication and connectivity infrastructure.
- CPAP Machines:Fixed-pressure delivery systems operating at clinician-prescribed settings between 4-20 cm H₂O represent the reimbursement-established volume base. Medicare durable medical equipment fee schedules in the United States and Germany's G-BA coverage decisions sustain procurement through home care networks in Florida and Bavaria.
- APAP Devices:Auto-titrating algorithms with breath-by-breath pressure adjustment respond to apnea-hypopnea index variability without manual intervention. Sleep clinics in Texas and New South Wales, Australia are transitioning titration protocols toward these systems to reduce laboratory backlogs and accelerate therapy initiation.
- BiPAP Devices:Bilevel pressure delivery with separate inspiratory and expiratory settings serves central sleep apnea and respiratory failure patients requiring ventilatory support beyond simple airway splinting.
- Oxygen Concentrators:Pressure-swing adsorption systems combining supplemental O₂ with positive airway pressure address nocturnal desaturation in COPD-sleep apnea overlap populations.
Leading the category by volume: CPAP Machines. Growing fastest: APAP Devices.
Therapy Area:
Clinical indication severity determines device specification requirements and reimbursement coding complexity across patient populations.
- Obstructive Sleep Apnea:Pharyngeal collapse during sleep requiring mechanical airway patency maintenance represents the dominant addressable population. Home care providers in California and Ontario, Canada manage the majority of moderate-to-severe cases through remote monitoring platforms that track residual apnea indices and mask leak rates.
- Central Sleep Apnea:Drive failure from chemoreflex instability or opioid-induced respiratory depression demands adaptive servo-ventilation or backup rate capabilities beyond standard CPAP. Tertiary sleep centers in Massachusetts and Tokyo concentrate complex titration for these patients.
- Respiratory Failure:Acute-on-chronic hypercapnic states in obesity hypoventilation syndrome require pressure support with integrated oximetry and transcutaneous CO₂ monitoring.
- COPD Management:Nocturnal non-invasive ventilation reduces hospital readmission risk in chronic bronchitis and emphysema patients with daytime hypercapnia.
Obstructive Sleep Apnea commands the largest patient volume. Central Sleep Apnea shows the steepest expansion trajectory as opioid-associated respiratory depression recognition improves.
End User:
Procurement authority is migrating from institutional sleep laboratories toward distributed home care channels with remote titration capabilities.
- Home Care Providers:Durable medical equipment suppliers with respiratory therapist staffing deliver devices, conduct mask fitting, and manage compliance data transmission to payers. Networks in Ohio and Illinois have achieved scale economies through centralized logistics and telehealth integration.
- Sleep Clinics:Physician-owned diagnostic facilities retain influence over initial prescription decisions and complex titration for multi-morbid patients. Accreditation requirements from the American Academy of Sleep Medicine and equivalent bodies in France and Japan sustain their referral gatekeeper role.
- Rehabilitation Centers:Post-acute facilities manage PAP therapy during recovery from stroke, cardiac surgery, or spinal cord injury where sleep-disordered breathing complicates rehabilitation.
- Diagnostic Laboratories:Independent testing centers conducting home sleep apnea testing generate prescriptions that flow to equipment suppliers, capturing revenue from the diagnostic episode without ongoing therapy management.
Home Care Providers capture the dominant procurement volume. Sleep Clinics maintain the highest per-patient revenue through bundled diagnostic and titration services.
Delivery Mode:
Form factor tradeoffs between clinical precision and lifestyle integration are reshaping patient adherence and replacement cycle timing.
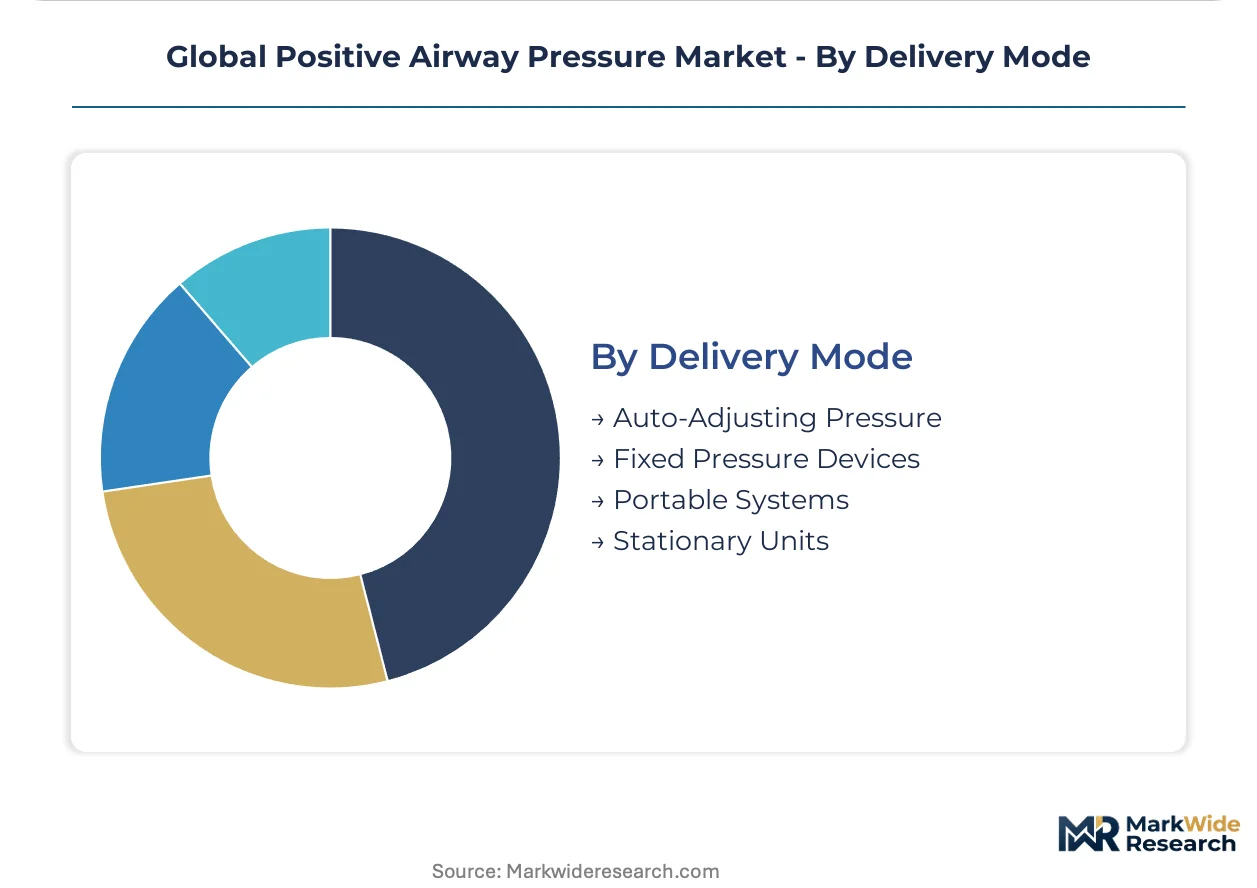
- Auto-Adjusting Pressure:Real-time algorithmic response to flow limitation, snoring, and apnea events eliminates the need for attended polysomnography titration. Patients in high-deductible health plans in Texas and Georgia prefer these systems for their reduced time-to-therapy and elimination of multiple clinic visits.
- Portable Systems:Palm-sized devices with lithium-polymer battery power and micro-blower technology enable therapy continuity during business travel and airline crew rotations. Miniaturization investments from manufacturers target the 15-20% of patients who report travel as a primary compliance barrier.
- Fixed Pressure Devices:Single-setting delivery remains the cost-optimized standard for stable patients with established pressure requirements and consistent body mass.
- Stationary Units:Bedside systems with integrated humidification and cellular connectivity serve the homebound elderly and patients requiring caregiver oversight.
Auto-Adjusting Pressure leads category volume. Portable Systems gain share fastest as battery density improvements and micro-motor integration enable clinical-grade performance at travel-compatible scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in industrial clusters with precision electronics capabilities, while consumption patterns track diagnostic infrastructure expansion and reimbursement stability. The United States absorbs the dominant volume share, though production sourcing spans contract manufacturers across Asia-Pacific electronics corridors.
United States
Medicare durable medical equipment fee schedules sustain home care procurement volumes through networks in Florida and Ohio. FDA 510(k) clearance pathways govern product entry timelines, with predicate device scarcity extending novel algorithm reviews. Sleep clinics in Texas and California are transitioning toward auto-titrating systems to reduce laboratory backlogs.
Germany
G-BA coverage decisions establish reimbursement benchmarks that cascade across European markets, with Bavarian home care providers achieving scale through centralized logistics. EU MDR conformity assessment requirements extend clearance timelines for respiratory devices. Manufacturing concentration in North Rhine-Westphalia supplies hospital-grade systems to tertiary sleep centers.
Japan
METI projections indicate 40% of adults over 60 will require sleep-disordered breathing intervention by 2030, driving fleet procurement by Tokyo and Osaka home care networks. PMDA regulatory harmonization with ISO 80601-2-70 standards accelerates multi-market submission convergence. Kanto region sleep laboratories retain gatekeeper influence over complex titration cases.
India
CDSCO streamlined Class B medical device registration in 2023, reducing entry barriers for international manufacturers. Diagnostic infrastructure in Mumbai and Bangalore remains below 15% of estimated sleep apnea prevalence, creating latent demand. Maharashtra-based diagnostic chains are expanding home sleep test availability to capture undiagnosed populations.
Australia
TGA oversight maintains alignment with IEC 62304 software lifecycle requirements for cloud-connected devices. Medicare reimbursement for remote APAP adjustments enables telehealth sleep management models in New South Wales. Sleep clinics in Sydney and Melbourne are deploying same-day patient onboarding systems to compress specialist referral bottlenecks.
Global Positive Airway Pressure Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the positive airway pressure landscape. Three to five integrated healthcare technology groups anchor the premium tier through cloud-connected platform ecosystems, while mid-scale respiratory specialists concentrate on humidification technology and mask interface differentiation. Competitive positioning hinges on recurring software revenue capture, geographic distribution density, and regulatory submission speed across FDA and EU MDR pathways. M&A activity targets digital health capabilities and telehealth integration assets, while capacity expansion concentrates in Asia-Pacific electronics manufacturing corridors.
Among diversified healthcare conglomerates, Koninklijke Philips N.V. and Smiths Group plc exemplify scale-driven positioning through broad geographic distribution and hospital-grade manufacturing infrastructure. ResMed Inc. and Fisher & Paykel Healthcare Limited occupy the pure-play specialist tier, with the former representing cloud-connected platform integration and the latter exemplifying humidification technology leadership. BMC Medical Co., Ltd. and Wellell Inc. anchor the Asia-Pacific manufacturing corridor, supplying contract production and regional brand development.
| Leading Market Players |
|---|
| ResMed Inc. |
| Koninklijke Philips N.V. |
| Fisher & Paykel Healthcare Limited |
| Drive DeVilbiss Healthcare |
| BMC Medical Co., Ltd. |
| Wellell Inc. |
| Somnetics International, Inc. |
| 3B Medical, Inc. |
| Smiths Group plc |
| Others |
Supply & Pricing Matrix
Medical-grade liquid silicone rubber price volatility cascades through mask production costs into three-tier pricing structure across premium, standard, and economy levels, with petrochemical feedstock spikes compressing margins for producers lacking backward integration into polymer compounding.
Pricing Analysis
Cost-down pressure on economy-tier devices accelerates because Taiwanese foundry concentration for flow sensor ASICs limits supplier choice. Pricing stratifies across premium, standard, and economy tiers based on algorithmic sophistication and FDA 510(k) predicate availability. Medicare reimbursement compression in durable medical equipment channels squeezes home care provider margins most acutely. Large hospital systems exhibit lowest price sensitivity due to bundled service contracts, while independent sleep clinics face acute procurement pressure.
Supply Chain Analysis
Pressure transducer supply rests on Taiwanese specialty semiconductor foundries and German precision sensor manufacturers. Device assembly draws from contract manufacturers in China, Malaysia, and Mexico. Single-source dependency for medical-grade silicone creates vulnerability to petrochemical price cycles. Distribution runs through durable medical equipment networks with respiratory therapist staffing for mask fitting and compliance management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor component concentration in Taiwanese foundries props pricing power for integrated device manufacturers with captive sensor supply, constraining margin recovery for assembly-only competitors.
For Market Incumbents: Anchor cloud-connected platform ecosystems against portable device entrants by deepening software subscription revenue and securing FDA 510(k) predicate libraries. Defend against direct-to-consumer channel displacement by controlling home sleep test bundling workflows. Prioritize notified body relationship investment for EU MDR Article 10 post-market surveillance compliance. For New Entrants and Emerging Players: Enter via travel-optimized miniaturization segments where lithium-polymer density improvements enable palm-sized form factors underserved by bedside-bound incumbents. Target business traveler and airline crew populations in North American and Asia-Pacific corridors. Deploy direct-to-consumer e-commerce with telehealth integration to bypass sleep specialist gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale respiratory specialists with humidification technology differentiation and MDR-ready technical documentation in European manufacturing corridors. Long-term viability hinges on recurring software revenue capture rather than device margin dependency. Watch FDA de novo submission volume as inflection signal for algorithmic innovation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | ResMed's AirView infrastructure demonstrates recurring revenue capture beyond hardware margins. |
| EU MDR Certification Pathway | Notified body capacity expansion in 2024 creates first-mover advantage for hospital tenders. |
| Portable Device Development | Micro-blower motor integration enables therapy continuity for travel-constrained patient segments. |
| Direct-to-Consumer Launch | Home sleep test bundling in California and New York displaces traditional referral channels. |
| Reimbursement Strategy | Medicare telehealth coverage expansion removes cost barriers to remote APAP titration. |
Research Methodology
Independent corroboration across device manufacturer regulatory filings, home care provider procurement databases, and GPO contract records underwrites the qualitative findings. Primary interviews with respiratory therapists, biomedical engineers, hospital purchasing committees, and durable medical equipment logistics directors combined with secondary validation from FDA 510(k) databases, EU MDR notified body registers, and CMS Medicare fee schedules. Bottom-up patient flow modeling and top-down revenue aggregation triangulate volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects. Segmentation dimensions modeled include product type, therapy area, end-user channel, and delivery mode. CAGRs derive from regression against aging demographic projections and diagnostic infrastructure expansion curves. Forecast inputs incorporate reimbursement policy trajectories and semiconductor supply lead time assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA predicate scarcity escalation or Taiwanese foundry disruption. The analysis reflects documented assumptions regarding telehealth reimbursement permanence and EU MDR transition completion. A small set of named triggers warrants ongoing watch: de novo submission backlogs, silicone feedstock price spikes, and notified body audit failure rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Global Pulmonary Surfactant Market