
 Container Washing System Market | 2026-2036
Container Washing System Market Size, Share, and Industry Trends Forecast 2026-2036
Container Washing System Market Analysis
A widening capability gap between automated and manual system providers is unwinding competitive stability in the container washing system sector. Rotajet Systems Ltd. leverages its engineering heritage in high-pressure washing to dominate UK industrial applications. HOBART GmbH anchors its position through integrated in-house production of stainless-steel wash chambers and control systems. Unifortes B.V. specializes in pharmaceutical-grade automated lines that meet EU cGMP validation protocols.
Container washing systems are industrial equipment designed to clean, sanitize, and decontaminate reusable containers through mechanical action, chemical treatment, or thermal processes, typically achieving temperatures exceeding 82 degrees Celsius for sterilization-grade cycles in pharmaceutical settings. These systems serve critical functions in preventing cross-contamination, ensuring regulatory compliance, and extending container lifecycle value across closed-loop supply chains. Automated systems command the dominant share of capital expenditure as food and beverage processors replace manual wash stations to reduce water consumption and labor dependency. Ultrasonic cleaning technology represents the fastest-expanding segment within pharmaceutical end-use, driven by precision demands for parenteral drug container integrity. Fixed installations remain the mature revenue base, though portable units are gaining traction in third-party logistics operations requiring flexible depot configurations.
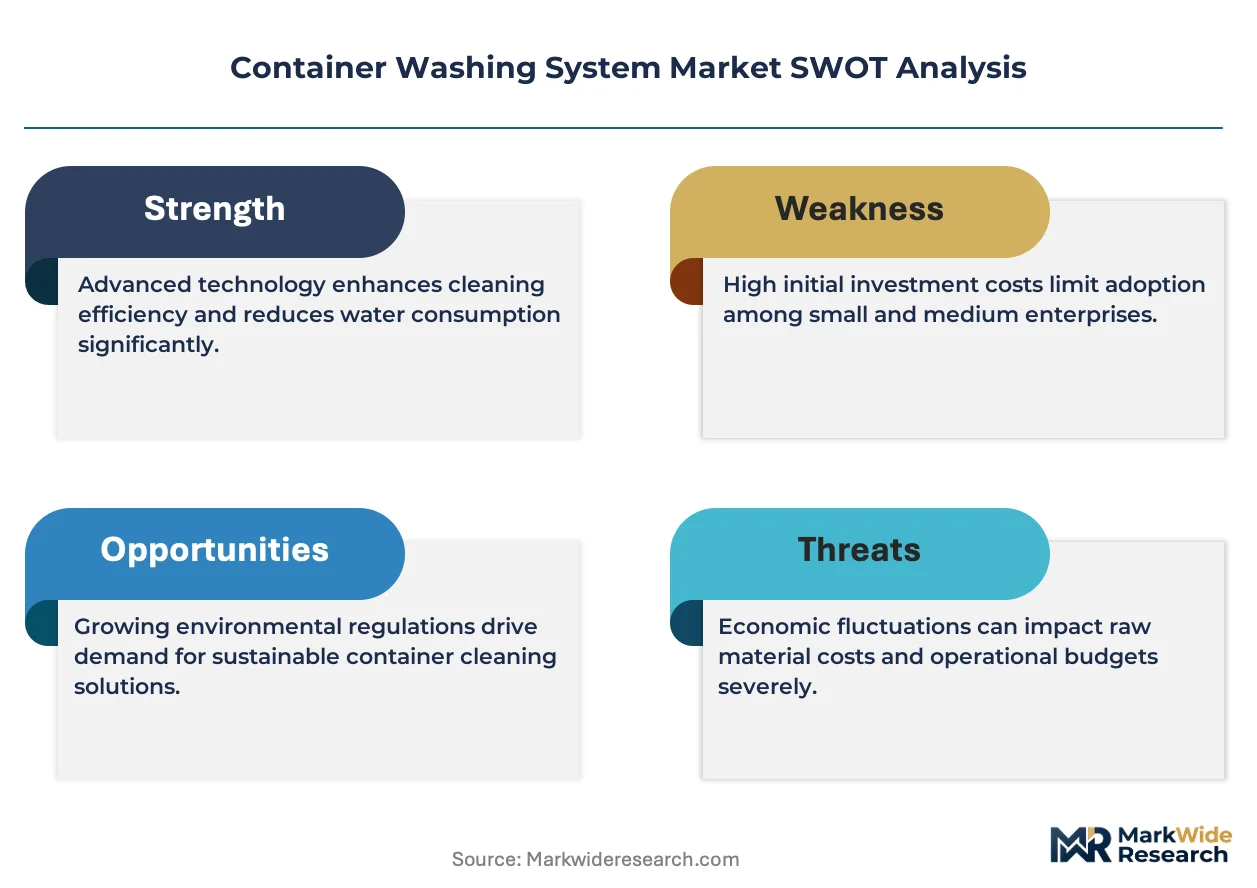
FDA cGMP guidelines, EU MDR traceability requirements, and EPA effluent standards collectively shape equipment specifications, validation documentation burdens, and water treatment subsystem design across all major supply contracts. The EU F-Gas Regulation and REACH chemical restrictions are additionally forcing detergent reformulation and closed-loop solvent recovery integration in European-manufactured systems. Stakeholders must monitor evolving ESG disclosure rules under CSRD and emerging state-level water reuse mandates in California and Texas that could redefine total cost-of-ownership calculations for centralized washing infrastructure investments.
Market Dynamics
Pharmaceutical serialization mandates and EU MDR traceability requirements are forcing container washing infrastructure upgrades across European drug distribution networks, compressing replacement cycles for legacy manual stations.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers must document container wash validation for reusable sterile barriers, expanding automated system procurement.
- Water recovery technology:Closed-loop filtration systems reduce effluent discharge costs for food processors operating under tightening EPA discharge limits.
- German contract packaging consolidation:Multi-site operators are centralizing washing operations into single high-throughput facilities serving pharmaceutical and biotech clusters.
Market Restraints
- Stainless steel supply concentration:Wash chamber fabrication depends on specialized 316L steel grades sourced from limited European mills, creating input cost volatility.
- REACH detergent restrictions:ECHA chemical hazard classifications are forcing reformulation of alkaline cleaning agents, extending qualification timelines.
- Ultrasonic transducer technical limits:Piezoelectric component durability constraints cap cycle throughput for high-volume parenteral container lines.
Strategic Opportunities
- California water reuse mandates:State-level regulations on industrial water recycling create demand for integrated treatment subsystems in third-party logistics depots.
- Biologics cold chain expansion:Temperature-validated washing protocols for cryogenic container reuse represent an emerging application with limited incumbent competition.
- CSRD disclosure requirements:Corporate sustainability reporting obligations incentivize equipment purchases with documented carbon footprint reductions.
Industry Challenges
- cGMP validation documentation:FDA inspection readiness demands extensive IQ/OQ/PQ protocol execution, stretching internal quality engineering capacity.
- Legacy PLC integration:Brownfield pharmaceutical sites require costly control system retrofits to connect new washing lines with existing MES infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Washing System Market |
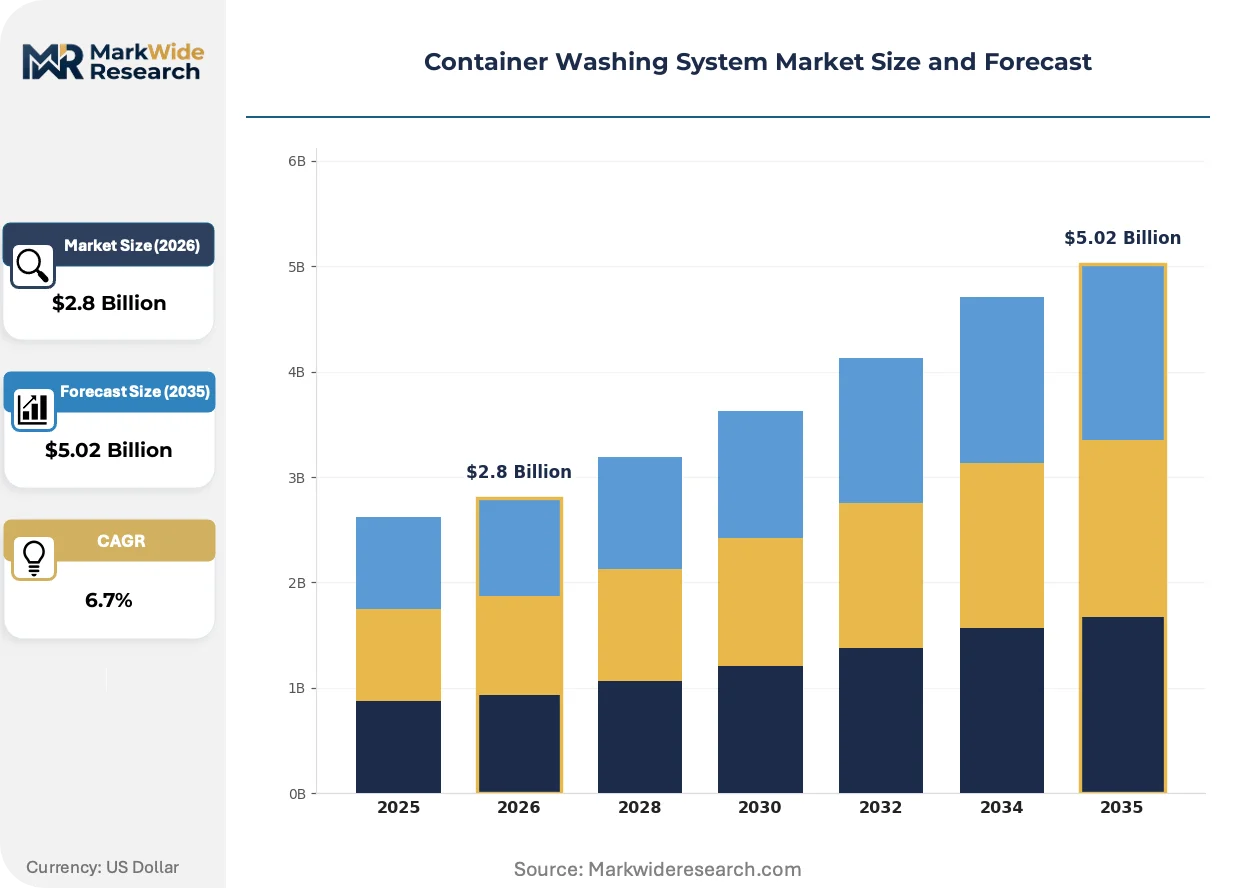
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Mobile Units, Centralized Stations Technology: High-Pressure Washing, Chemical Cleaning, Ultrasonic Cleaning, Steam Cleaning End User: Food and Beverage, Pharmaceutical, Chemical, Logistics Installation: Fixed Systems, Portable Units, In-Line Solutions, Custom Installations |
| Companies Covered | Rotajet Systems Ltd., SRS Engineering Corporation, HOBART GmbH, Unifortes B.V., Feistmantl Cleaning Systems GmbH, NUMAFA, Glatt GmbH, PRI Systems, SF Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Washing System Market Emerging Trajectories
Equipment vendors are converging on modular platform architectures that reduce site-specific engineering while accommodating divergent regulatory validation requirements across pharmaceutical and food end-uses.
Ultrasonic cavitation technology is supplanting high-pressure spray washing in parenteral drug container cleaning. Sterile injectable manufacturers in Switzerland and Germany are retrofitting existing lines with multi-frequency transducer arrays. This transition is compressing margins for traditional spray-nozzle system suppliers dependent on pharmaceutical volume.
EU F-Gas Regulation phase-down schedules are accelerating heat pump integration in thermal washing systems. Equipment builders must redesign steam-based sterilization cycles around lower-global-warming-potential refrigerants. Pharmaceutical-grade installations in the Netherlands and Belgium face the steepest retrofit obligations due to earlier national implementation deadlines.
Third-party logistics operators are unbundling after-sales service contracts from capital equipment purchases. Depot-based container pool managers now procure wash cycles as metered services rather than owning fixed assets. This shift concentrates most visibly in Texas and California, where multi-tenant food distribution hubs favor operational expenditure models over balance-sheet equipment ownership.
Container Washing System Market Segmentation
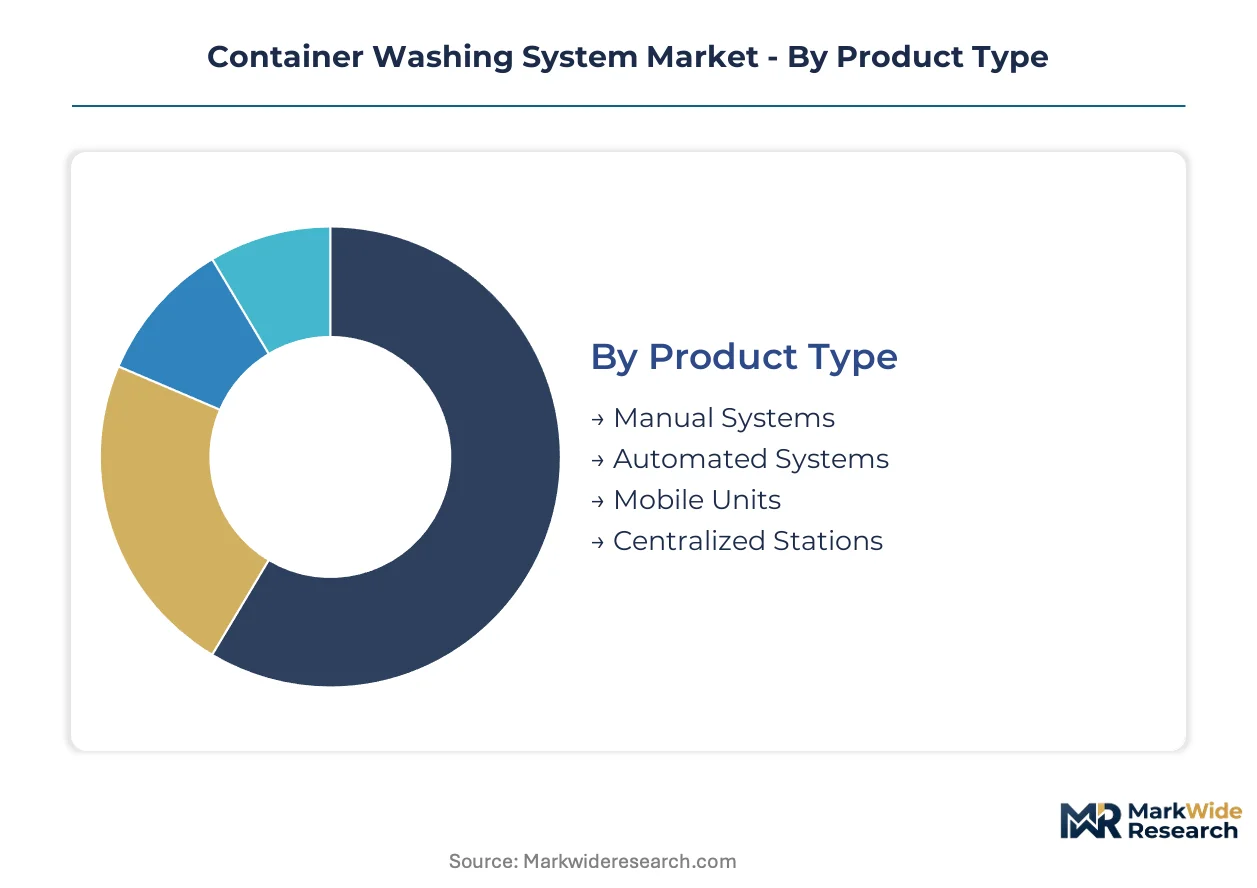
Segmentation in container washing systems determines capital deployment patterns, regulatory compliance pathways, and service model economics across closed-loop supply chains. Equipment specifications diverge sharply between pharmaceutical-grade validation requirements and food-processing throughput priorities. Understanding these divides reveals where technology investments concentrate and margin structures stabilize.
Product Type:
Channel flow splits between capital-intensive fixed installations sold through direct manufacturer relationships and mobile units distributed via equipment leasing networks serving third-party logistics operators.
- Automated Systems:Programmable wash cycles with stainless-steel construction and integrated water recovery subsystems dominate pharmaceutical and large-scale food processing procurement. Demand concentrates in Germany, where contract packaging organizations are consolidating multi-site operations into centralized high-throughput facilities.
- Manual Systems:Operator-dependent wash stations with basic spray wands and single-tank chemical immersion remain prevalent in small-batch chemical handling and legacy food processing plants. Capital constraints in Eastern European manufacturing clusters sustain residual demand despite automation migration.
- Mobile Units:Trailer-mounted or skid-based configurations enable depot-based container pool management without fixed infrastructure commitment.
- Centralized Stations:High-volume integrated facilities serving multiple downstream users through metered wash-cycle contracts.
By volume, Automated Systems lead. By growth pace, Centralized Stations are expanding most quickly.
Technology:
Cost tier stratification separates premium ultrasonic installations from standard high-pressure spray systems, with chemical cleaning occupying a mid-tier position constrained by REACH detergent reformulation costs.
- Ultrasonic Cleaning:Multi-frequency piezoelectric transducer arrays generate cavitation bubbles for precision decontamination of parenteral drug containers and complex geometries. Swiss and German sterile injectable manufacturers are retrofitting existing lines, compressing margins for traditional spray-nozzle suppliers.
- High-Pressure Washing:Mechanical impingement through rotating spray heads and targeted nozzles removes bulk soil from industrial totes and intermediate bulk containers. Food and beverage processors in the UK and Netherlands favor these systems for water efficiency versus manual alternatives.
- Chemical Cleaning:Alkaline or solvent-based detergent cycles with controlled temperature and concentration parameters.
- Steam Cleaning:Thermal sterilization cycles exceeding 82 degrees Celsius for pharmaceutical-grade decontamination.
By installed base, High-Pressure Washing dominates. By revenue expansion, Ultrasonic Cleaning shows the steepest trajectory.
End User:
Application requirements dictate specification divergence, with pharmaceutical mandates demanding IQ/OQ/PQ validation documentation that food and chemical sectors rarely require.
- Pharmaceutical:FDA cGMP and EU MDR compliance drives specification for automated lines with full batch traceability, thermal sterilization capability, and extensive validation documentation. Serialization mandates are compressing replacement cycles for legacy manual stations across European drug distribution networks.
- Food and Beverage:EPA effluent standards and water cost pressures prioritize closed-loop filtration and reduced chemical usage. California and Texas processors face tightening state-level discharge limits that accelerate automated system procurement.
- Chemical:Corrosion-resistant construction and hazardous material handling protocols define procurement criteria.
- Logistics:Flexible depot configurations and operational expenditure models favor portable units and metered service contracts.
By capital deployed, Pharmaceutical leads. By volume growth, Logistics is gaining share fastest.
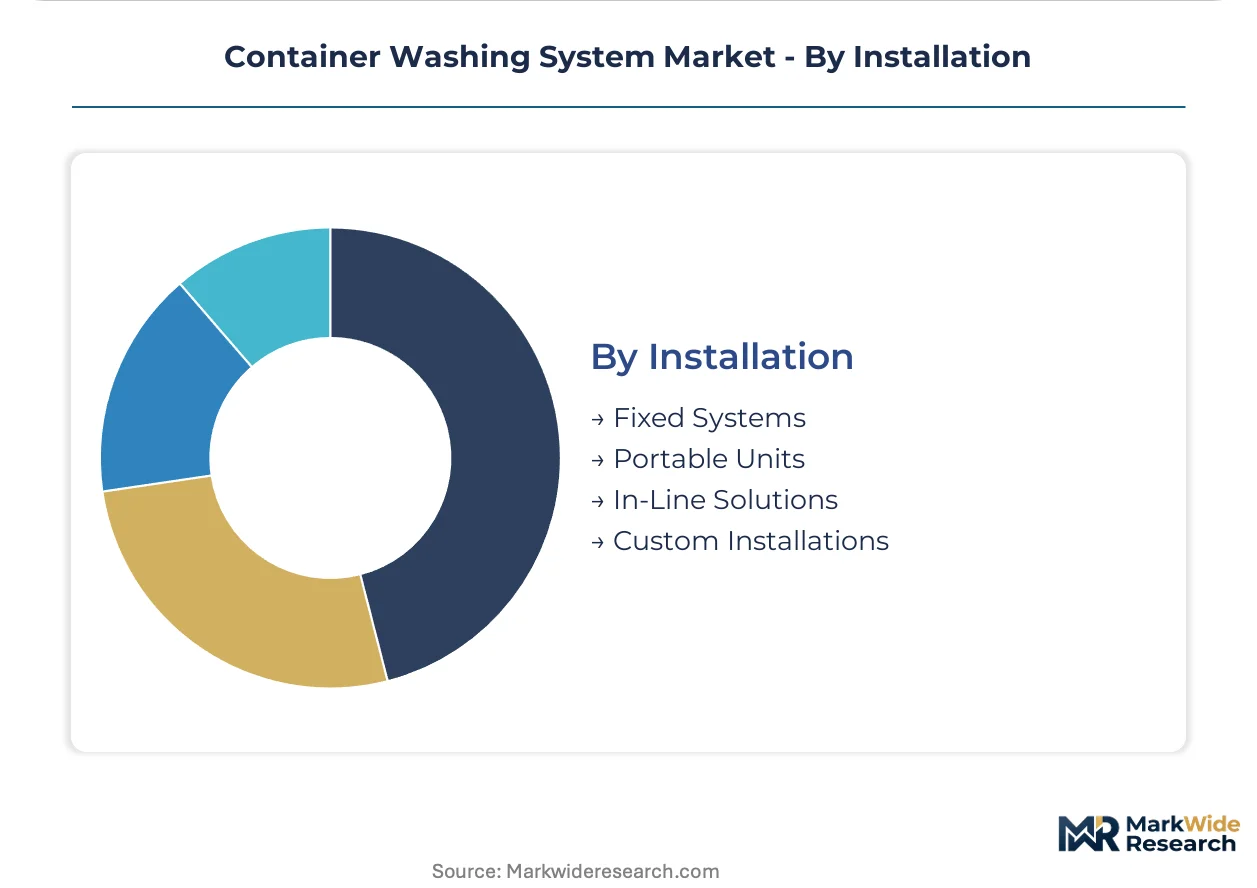
Installation:
Customer type segmentation separates brownfield pharmaceutical sites requiring MES integration from greenfield logistics depots prioritizing rapid deployment flexibility.
- Fixed Systems:Permanent infrastructure with dedicated utility connections, wastewater treatment integration, and validated operating envelopes. Mature revenue base anchored by pharmaceutical manufacturing and large-scale food processing facilities.
- Portable Units:Modular skid-mounted or containerized configurations enabling relocation across third-party logistics depots. Texas and California multi-tenant food distribution hubs favor operational expenditure models over balance-sheet ownership.
- In-Line Solutions:Continuous-flow washing integrated with production or packaging lines.
- Custom Installations:Site-engineered configurations for non-standard container geometries or specialized contamination profiles.
By revenue stability, Fixed Systems anchor the market. By adoption velocity, Portable Units are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between pharmaceutical-heavy European markets and food-processing-led North American deployment, with Asia-Pacific adoption still nascent but accelerating in contract manufacturing clusters.
Germany
Contract packaging organizations are consolidating multi-site washing operations into centralized high-throughput facilities serving pharmaceutical and biotech clusters. The EU MDR traceability mandates compel medical device manufacturers to document container wash validation for reusable sterile barriers. The Rhine-Ruhr and Bavarian industrial corridors host the densest concentration of automated system installations.
United States
Food and beverage processors in California and Texas face tightening EPA effluent standards and state-level water reuse mandates that accelerate automated system procurement. Third-party logistics operators favor operational expenditure models over balance-sheet equipment ownership. The Central Valley agricultural processing belt and Houston-area chemical distribution hubs drive portable unit demand.
Switzerland
Sterile injectable manufacturers are retrofitting existing lines with multi-frequency transducer arrays for precision decontamination of parenteral drug containers. Swissmedic validation protocols exceed baseline EU requirements, extending qualification timelines for new equipment. The Basel pharmaceutical cluster and Zurich industrial district anchor specialized ultrasonic cleaning demand.
Netherlands
Food processors favor high-pressure washing systems for water efficiency versus manual alternatives, with closed-loop filtration reducing effluent discharge costs. The EU F-Gas Regulation phase-down schedules accelerate heat pump integration in thermal washing systems. The Rotterdam port logistics zone and Eindhoven food technology corridor concentrate depot-based container pool management.
United Kingdom
Industrial applications in chemical handling and legacy food processing sustain residual demand for manual wash stations despite automation migration. REACH detergent restrictions force reformulation of alkaline cleaning agents, extending qualification timelines. The Manchester chemical processing belt and Midlands manufacturing corridor represent the primary installation base.
Container Washing System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding pharmaceutical-grade validation capabilities and the latter competing on regional service density and customization speed. The market structure favors players with captive stainless-steel fabrication capacity and in-house control system engineering. Two archetypes dominate: vertically integrated chamber builders and technology-focused cleaning specialists. Competitive moves concentrate on M&A for geographic footprint and strategic partnerships for water treatment subsystem integration.
Among UK-based engineering specialists, Rotajet Systems Ltd. exemplifies the high-pressure washing heritage archetype. German fabricators HOBART GmbH and Glatt GmbH anchor the integrated production tier with captive stainless-steel capabilities. Dutch specialist Unifortes B.V. occupies a position within the pharmaceutical-grade automated line segment, representing the validation-focused archetype that has gained share as EU cGMP protocols tighten.
| Leading Market Players |
|---|
| Rotajet Systems Ltd. |
| SRS Engineering Corporation |
| HOBART GmbH |
| Unifortes B.V. |
| Feistmantl Cleaning Systems GmbH |
| NUMAFA |
| Glatt GmbH |
| PRI Systems |
| SF Engineering |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for 316L stainless steel wash chambers lock in both supply access and price visibility for German and Swiss pharmaceutical equipment builders facing REACH-driven detergent reformulation costs and EU F-Gas thermal system retrofit obligations.
Pricing Analysis
Contract-based long-term offtake dominates capital equipment procurement, with pricing stratifying across FDA-validated premium tiers, standard food-grade installations, and economy manual stations. Price differentiation hinges on cGMP certification level and captive stainless-steel fabrication capacity. Cost compression in the economy tier intensifies because Eastern European buyers prioritize capital constraints over automation migration. Third-party logistics operators show highest price sensitivity due to operational expenditure model preferences, while sterile injectable manufacturers accept premium pricing for Swissmedic-exceeding validation protocols.
Supply Chain Analysis
Strategic stockpiling of specialized 316L steel grades characterizes procurement behavior among integrated chamber builders, contrasting with just-in-time component sourcing for ultrasonic transducer arrays. Manufacturing concentrates in Germany, Switzerland, and the Netherlands, drawing from European mill supply for wash chamber fabrication and Asian sources for piezoelectric components. Single-source vulnerability in 316L steel grades creates input cost volatility. Distribution runs through direct manufacturer relationships for pharmaceutical-grade fixed installations and equipment leasing networks for mobile logistics depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable single-use container systems threaten reusable washing infrastructure investments as biologics manufacturers weigh contamination risk against capital recovery economics.
For Market Incumbents: Fortify validation documentation capabilities against FDA inspection readiness demands while deepening backward integration into stainless-steel chamber fabrication to offset 316L supply concentration. Anchor aftermarket service revenue through metered wash-cycle contracts in Texas and California logistics hubs to defend against portable unit leasing competitors. For New Entrants and Emerging Players: Anchor in cryogenic container washing protocols for biologics cold chain expansion, the most penetrable application with limited incumbent competition. Target California water reuse mandate compliance as a regulatory-driven entry wedge. Pursue partnerships with existing water treatment subsystem specialists rather than greenfield chamber fabrication. For Investors and Strategic Acquirers: Pharmaceutical-grade automated line specialists with captive IQ/OQ/PQ protocol engineering represent the most defensible acquisition profile across the analysis window. Monitor ECHA detergent hazard reclassification velocity as the inflection signal for qualification timeline risk and reformulation cost pass-through capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless-Steel Chamber Fabrication | Captive 316L supply secures margin stability against European mill concentration. |
| Ultrasonic Transducer Array Retrofit Partnerships | Swiss and German sterile injectable demand displaces traditional spray-nozzle incumbents. |
| Metered Wash-Cycle Service Contracts | Texas and California logistics depots shift capital expenditure to operational expenditure models. |
| Heat Pump Thermal System Redesign | EU F-Gas Regulation compliance opens retrofit revenue in Netherlands and Belgium. |
| cGMP Validation Documentation Outsourcing | Pharmaceutical manufacturers stretch internal quality engineering capacity. |
Methodological Framework
Desk research of EU MDR implementation timelines, EPA effluent discharge databases, and ECHA REACH substance classifications preceded structured interviews with pharmaceutical quality engineering directors, food processing plant managers, contract packaging procurement leads, and third-party logistics depot operators. Primary fieldwork combined with secondary validation across FDA cGMP guidance documents, Swissmedic validation protocols, and stainless-steel trade flow data. Bottom-up equipment shipment tracking and top-down capital expenditure surveys were triangulated against regulatory filing analysis.
Variance decomposition across technology type, end-use vertical, installation configuration, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers. Modeled inputs included EU MDR compliance deadline phasing, California water reuse mandate implementation velocity, and ultrasonic transducer durability improvement curves.
Decision-makers should treat outputs as directional under assumptions of sustained EU MDR enforcement and stable 316L steel supply; material deviation would warrant model refresh. Forecasts reflect base-case regulatory trajectory and commodity input stability. Revision becomes warranted when REACH detergent reclassification scope crosses thresholds affecting qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Automatic Liquid Filling Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Hydrapulper Market