
 Recycled Envelopes Market | 2026-2036
Recycled Envelopes Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Envelopes Market Analytics
The gap between premium certified recycled envelopes and commodity-grade alternatives is broadening. WestRock Company leverages its integrated pulp-to-converter footprint to sustain cost discipline across high-volume wallet and catalog formats. Mondi Group anchors its position through specialty kraft paper grades that meet stringent corporate sustainability mandates. EcoEnclose differentiates by serving direct-to-consumer brands with custom-branded window envelopes featuring high post-consumer waste content.
Recycled envelopes are paper-based mailing enclosures manufactured from post-consumer or post-industrial fiber stock, typically containing 30% to 100% recovered content and processed through pulping, sheet forming, die-cutting, and adhesive sealing operations for document protection and distribution. Kraft paper material dominates volume shipments due to structural strength and printability, while white wove grades command margin premiums in corporate and government end-use segments. Side seam construction leads in manufacturing throughput, though window variants are gaining share as transactional mailers require address visibility without secondary labeling.
The EPA guides recovered fiber content standards in the United States, while the EU Green Deal and REACH frameworks restrict chemical additives in adhesives and bleaching agents across European supply chains. Compliance with these overlapping regimes shapes raw material sourcing strategies and converter investment priorities. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustments that will redefine cost structures for cross-border envelope supply.
Market Dynamics
The EU Green Deal's extended producer responsibility frameworks are forcing converters to restructure fiber sourcing and adhesive chemistry across European supply chains. Corporate carbon-neutral packaging mandates are compressing procurement timelines for certified recycled content.
Growth Catalysts
- REACH chemical restrictions:European converters reformulating adhesives and bleaching agents are accelerating demand for compliant specialty kraft grades that satisfy corporate sustainability audits.
- Direct-to-consumer brands:E-commerce merchants requiring custom-branded window envelopes with visible post-consumer waste credentials are expanding order volumes for certified converters.
- German brand procurement:Carbon-neutral packaging mandates from major German retailers are concentrating demand for premium recycled envelope grades with verified chain-of-custody documentation.
Market Restraints
- Recovered fiber cost volatility:Post-consumer waste paper prices fluctuate with municipal collection program funding, squeezing margin predictability for mid-volume converters.
- Integrated pulp-to-converter concentration:North American supply chains dominated by vertically integrated paperboard giants limit independent converter access to competitively priced raw stock.
- Digital document substitution:Electronic billing platforms and PDF distribution are compressing transactional mailer volumes in financial services and utilities.
Strategic Opportunities
- Carbon border adjustment mechanisms:Pending EU carbon border taxes on imported paper products create white space for European converters with verified low-carbon fiber sourcing.
- Pharmaceutical serialization compliance:Track-and-trace mandates requiring tamper-evident mailing enclosures open demand for security-featured recycled envelopes in healthcare distribution.
- Subscription box merchants:Monthly delivery services seeking plastic-free exterior packaging represent an emerging channel for rigid mailer formats with high recycled content.
Industry Challenges
- Fiber sorting and de-inking expertise:Shortages of technicians skilled in optical sorting and contaminant removal constrain capacity expansion at post-consumer waste processing facilities.
- Multi-certification compliance timelines:Simultaneous pursuit of FSC chain-of-custody, EU Ecolabel, and carbon footprint verification extends product qualification cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Envelopes Market |
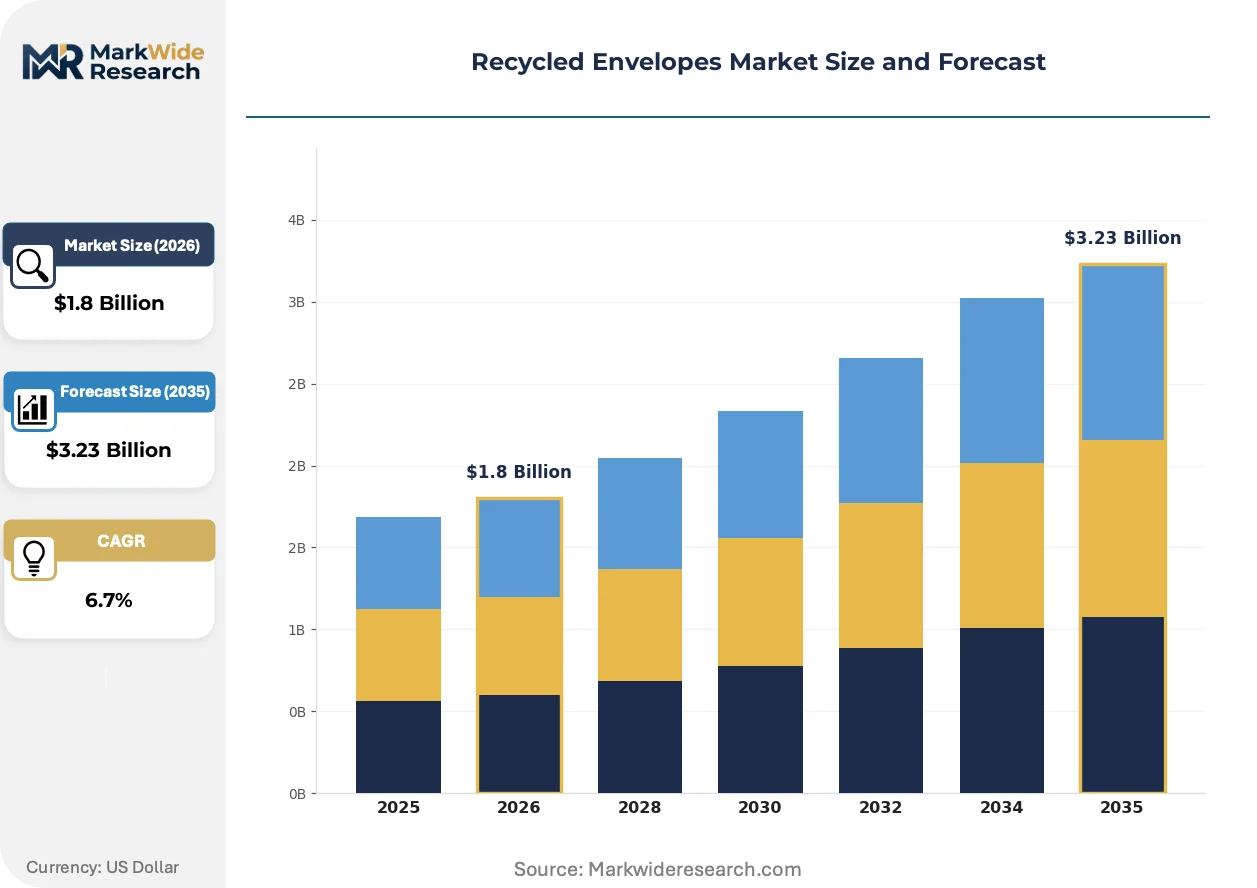
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Side Seam, Wallet, Catalog, Window Material: Kraft Paper, White Wove, Colored Paper, Mixed Material End User: Retail, Education, Government, Corporate Distribution Channel: Online Retailers, Wholesalers, Stationery Stores, Direct Sales |
| Companies Covered | WestRock Company, Bong Group, International Paper Company, Mondi Group, EcoEnclose, Envelopes Ltd., Neenah Inc., Domtar Corporation, Antalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Envelopes Market Evolving Landscape
Water-based barrier coatings are displacing polyethylene linings in window envelopes, enabling full recyclability without separating film from paper. This chemistry shift is converging with brand sustainability commitments to reconfigure converter R&D priorities.
Digital print personalization technology is converging with short-run envelope production, allowing direct-to-consumer brands to customize window placements and branding elements at order quantities below traditional minimums. E-commerce merchants are adopting these capabilities within six-month implementation windows. Variable data printing is compressing the traditional distinction between commodity and specialty envelope tiers.
The EPA's recovered fiber content guidelines are tightening enforcement through third-party auditing requirements, compelling converters to document post-consumer waste percentages with chain-of-custody certificates. Suppliers lacking verified fiber tracking systems face disqualification from federal procurement contracts. Government and corporate mailrooms are demanding enhanced documentation transparency.
Brand sustainability officers are consolidating supplier relationships around converters offering carbon accounting transparency alongside product certification. Single-source envelope procurement with verified lifecycle data is displacing fragmented multi-vendor purchasing in retail and financial services. German and French corporate headquarters are mandating consolidated sustainability reporting from packaging suppliers.
Recycled Envelopes Market Segmentation
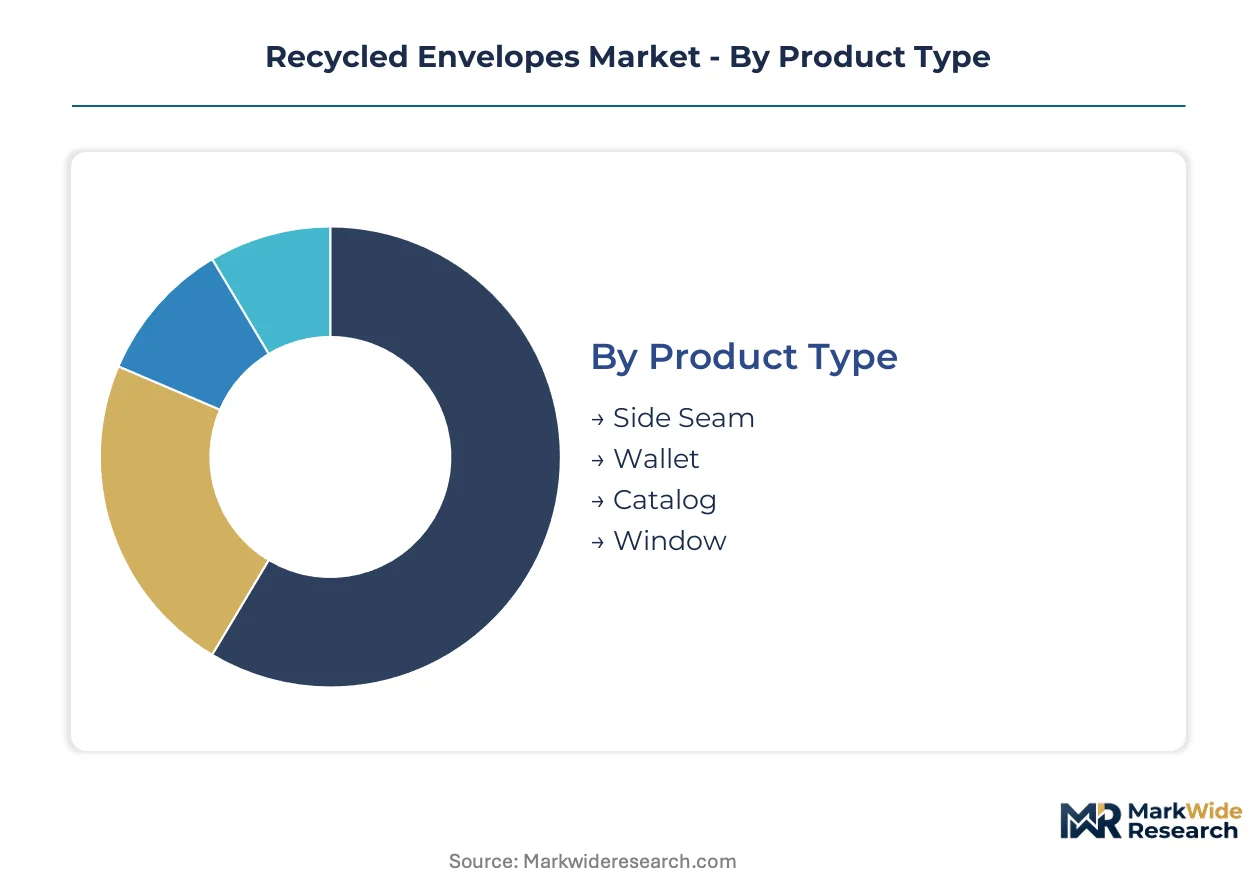
Recycled envelope procurement patterns diverge sharply across product formats and material grades. Corporate sustainability mandates and postal automation requirements reshape which segments capture volume and margin.
Product Type:
Side seam construction dominates high-throughput manufacturing lines, while window variants embed visibility features that eliminate secondary labeling steps.
- Side Seam:Machine-direction fiber alignment delivers tear resistance for high-speed insertion equipment. German financial services mailrooms specify this format for automated statement processing under carbon-neutral procurement rules.
- Window:Die-cut film or cellulose windows enable address visibility without envelope opening. EU Green Deal compliance pressures are accelerating water-based barrier coatings that eliminate polyethylene separation at recycling facilities.
- Wallet:Gusseted expansion panels accommodate bulky document sets. Legal and insurance sectors in France specify this format for contract distribution.
- Catalog:Large-format dimensions with reinforced edges support direct mail weight loads. Retail marketing departments in the United States favor this variant for seasonal promotional drops.
Side seam leads volumes today; window is gaining share fastest.
Material:
Raw stock selection determines printability, structural performance, and certification eligibility for corporate procurement.
- Kraft Paper:Unbleached long-fiber pulp provides tensile strength for heavy-content mailing. German retail brands specify 100% post-consumer waste kraft for carbon-neutral packaging credentials.
- White Wove:Bleached smooth surface supports four-color process printing. Government agencies in France require this grade for official correspondence visibility standards.
- Colored Paper:Pigmented stock differentiates branded communications without additional print passes. Direct-to-consumer subscription services in the United States adopt this for unboxing experience enhancement.
- Mixed Material:Blended fiber streams balance cost and performance for commodity applications. Independent converters source this grade when certified virgin alternatives face supply constraints.
Kraft paper leads volumes today; white wove commands the steepest margin premiums.
End User:
Procurement authority and sustainability mandate intensity vary dramatically across institutional buyer categories.
- Corporate:Centralized purchasing departments negotiate multi-year contracts with verified chain-of-custody documentation. REACH-compliant adhesive specifications dominate RFP requirements in European headquarters.
- Government:Federal procurement rules mandate minimum recovered fiber percentages with third-party auditing. EPA enforcement tightening is disqualifying suppliers lacking verified tracking systems.
- Retail:Brand sustainability officers consolidate vendor relationships around single-source envelope procurement with lifecycle carbon data. Carbon border adjustment anticipation is reshaping sourcing geography.
- Education:Decentralized purchasing across institutional units favors price-competitive commodity grades. Budget pressures limit adoption of premium certified alternatives.
Corporate leads volumes today; retail is expanding most quickly.
Distribution Channel:
Channel selection shapes minimum order quantities, customization access, and sustainability documentation availability.
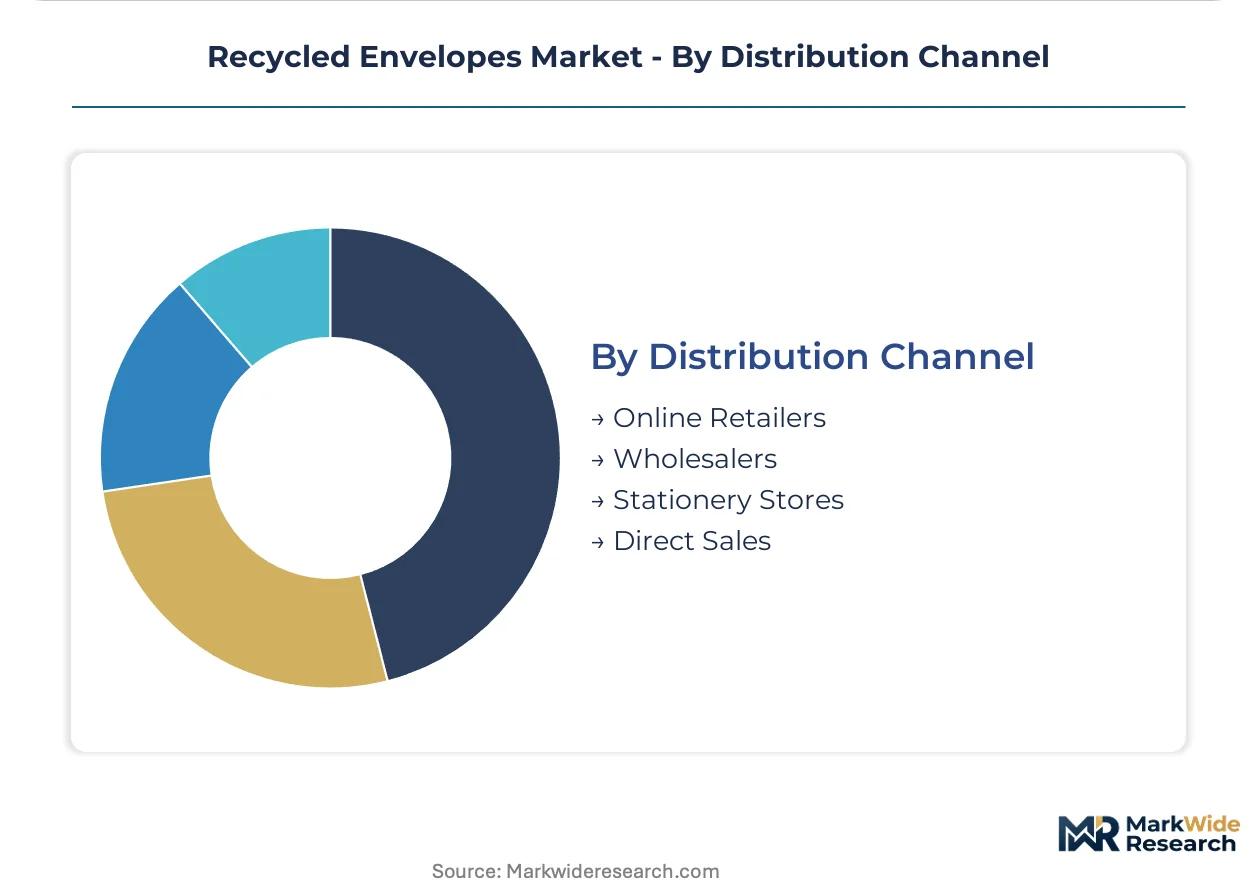
- Direct Sales:Converter-customer relationships enable custom window placement and short-run digital personalization. E-commerce merchants adopt these capabilities within compressed implementation timelines.
- Wholesalers:Inventory aggregation serves mid-volume customers lacking storage infrastructure. German distributors stock REACH-compliant grades for rapid corporate procurement response.
- Online Retailers:Platform-based purchasing suits small-order stationery consumers. Sustainability certification filtering is emerging as a search parameter.
- Stationery Stores:Physical inspection supports tactile quality assessment for premium grades. Urban commercial districts in France maintain this channel for immediate procurement needs.
Direct sales leads volumes today; online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium recycled envelope procurement under carbon-neutral mandates, while the United States sustains volume leadership through federal procurement rules and integrated pulp-to-converter supply chains.
United States
Corporate mailrooms and federal agencies drive certified recycled content procurement. EPA recovered fiber guidelines tighten enforcement through third-party auditing requirements. Chicago and Milwaukee host converter clusters serving financial services transactional mailers.
Germany
Retail brand sustainability officers mandate verified chain-of-custody documentation for carbon-neutral packaging credentials. EU Green Deal extended producer responsibility frameworks restructure adhesive chemistry compliance. The Rhine-Ruhr industrial corridor anchors specialty kraft grade production for premium envelope formats.
France
Government agencies specify white wove grades for official correspondence visibility standards. REACH chemical restrictions accelerate reformulation of compliant adhesives and bleaching agents. Paris and Lyon concentrate legal sector demand for wallet-format contract distribution.
United Kingdom
Direct-to-consumer subscription services adopt custom-branded window envelopes with short-run digital personalization capabilities. CSRD reporting requirements pressure corporate sustainability officers to consolidate supplier relationships. London and Manchester host converter operations serving e-commerce merchant procurement.
China
Export-oriented manufacturers supply mixed-material commodity grades when certified virgin alternatives face supply constraints. Dual carbon goals and MEE environmental inspections reshape fiber sourcing strategies. The Yangtze River Delta cluster processes post-industrial waste streams for envelope-grade pulp production.
Recycled Envelopes Market Competitive Landscape
Top-tier vendors anchor integrated pulp-to-converter operations, while independent specialists occupy custom-branded and short-run digital segments. The market structures around three strategic archetypes: vertically integrated paperboard giants controlling raw stock access, specialty converters serving sustainability-mandated corporate procurement, and agile players targeting direct-to-consumer e-commerce channels. Dominant competitive moves include backward integration into recovered fiber processing and geographic repositioning to preempt EU carbon border adjustment impacts.
Among North American integrated operators, WestRock Company and International Paper Company exemplify scale-driven archetypes with captive pulp supply, while Mondi Group represents European specialty positioning through kraft grade expertise. EcoEnclose occupies the direct-to-consumer tier, anchoring custom-branded window envelope capabilities for e-commerce merchants requiring rapid implementation timelines and visible post-consumer waste credentials.
| Leading Market Players |
|---|
| WestRock Company |
| Bong Group |
| International Paper Company |
| Mondi Group |
| EcoEnclose |
| Envelopes Ltd. |
| Neenah Inc. |
| Domtar Corporation |
| Antalis |
| Others |
Value Network & Pricing Analysis
Old corrugated container price indices cascade through recycled envelope supply chains into three distinct pricing tiers. Post-consumer waste paper volatility compresses margins at mid-volume converters while integrated operators capture cost discipline through captive pulp supply.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for premium certified grades. Pricing stratifies across premium, standard, and economy tiers based on chain-of-custody certification depth and post-consumer waste percentage. Cost compression in commodity grades is intensifying because municipal collection program funding fluctuations feed raw stock volatility. Education sector procurement remains most price-sensitive; corporate sustainability officers accept premium positioning for verified carbon accounting.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor anchor European hub-and-spoke patterns for REACH-compliant adhesive formulations. Supply concentrates in the United States, Germany, and China, with fiber sourcing drawing from post-consumer municipal streams and post-industrial packaging waste. Single-source vulnerability sits with optical sorting equipment suppliers for de-inking operations. Distribution runs through converter-direct relationships for custom formats and wholesale aggregation for standardized grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in recycled envelopes rests on water-based barrier coating adoption and carbon border adjustment positioning. Premium-tier capture through verified low-carbon fiber sourcing justifies the investment thesis.
For Market Incumbents: To counter independent converter encroachment in custom-branded segments, backward integration into recovered fiber processing secures cost predictability. Investment in EU Ecolabel and FSC simultaneous certification compresses competitor qualification timelines. Channel control through direct sales relationships with German retail sustainability officers protects price positioning. For New Entrants and Emerging Players: Digital print personalization technology offers entry into short-run window envelope production for direct-to-consumer subscription merchants. White space concentrates in pharmaceutical serialization compliance for tamper-evident formats. Go-to-market through e-commerce platform partnerships bypasses incumbent wholesale relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty converters holding verified low-carbon fiber sourcing ahead of EU carbon border implementation. Long-term viability favors operators with optical sorting expertise and multi-certification compliance infrastructure. Watch for carbon border adjustment mechanism finalization as inflection signal for geographic repositioning value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Processing | Captive post-consumer waste supply insulates margin from municipal collection funding volatility. |
| Water-Based Barrier Coating R&D Investment | Eliminates polyethylene separation steps, unlocking full recyclability credentials for EU Green Deal compliance. |
| Carbon Footprint Verification Program | Verified lifecycle data satisfies German retailer carbon-neutral packaging mandates and CSRD reporting requirements. |
| Digital Print Personalization Capability | Short-run customization at sub-traditional minimums captures direct-to-consumer merchant demand. |
| Pharmaceutical Serialization Partnership | Track-and-trace compliance opens healthcare distribution channel with security-featured recycled formats. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with envelope converter operations managers, corporate sustainability procurement leads, paper mill fiber sourcing directors, and postal automation equipment specialists combined with secondary validation from EPA recovered fiber guidelines, EU Ecolabel certification databases, REACH substance restriction updates, and customs trade flow records. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map fiber grade availability through converter capacity to end-use demand across product type, material specification, and procurement channel dimensions. CAGRs derive from segment-level growth rate reconciliation against macroeconomic envelope demand drivers. Forecast inputs incorporate EU Green Deal implementation pace, carbon border adjustment mechanism scope, and digital document substitution rates in financial services.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to extended producer responsibility scheme expansion and recovered fiber price volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Refillable Packaging Market