
 Hydrapulper Market | 2026-2036
Hydrapulper Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrapulper Market Foresight
Modular equipment configurations is decoupling capital expenditure from line-wide overhauls in hydrapulper procurement. ANDRITZ leverages its vertical integration into fiberline engineering to bundle hydrapulpers with downstream screening systems. Valmet sustains technology leadership through continuous R&D investment in high-consistency rotor designs. Kadant anchors its competitive position with specialized wear-component aftermarket programs that extend equipment life cycles.
A hydrapulper is a cylindrical or drum-shaped pulping machine that uses mechanical agitation and water injection to disperse fiber raw materials into slurry, typically operating at consistencies ranging from 3% to 18% depending on design type. Batch hydrapulpers dominate installed capacity in legacy mills where production flexibility outweighs throughput optimization, while continuous hydrapulpers are capturing greenfield investments in waste paper processing applications. Thermomechanical pulping technology is displacing conventional chemical routes in packaging-grade installations where yield maximization and reduced effluent loads determine project economics. Enzymatic pulping remains niche but occupies the highest-margin segment as biotech-enabled fiber modification commands premium pricing from specialty paper producers.
EPA effluent limitation guidelines shape wastewater discharge requirements for US-based recycling mills, while REACH and the EU Green Deal establish chemical restriction protocols for pulping additives across European installations. China's MEE enforces increasingly stringent water-intensity benchmarks that filter market access for imported equipment suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as compliance cost asymmetries reshape competitive positioning in cross-border equipment procurement.
Market Dynamics
Circular-economy mandates from the EU Green Deal are compressing discharge timelines for pulping effluent while packaging-grade recycled fiber demand concentrates in specific industrial clusters. This regulatory-demand convergence is restructuring equipment procurement patterns across fiber recovery facilities.
Growth Catalysts
- EU Green Deal circular-economy mandates:Tightening effluent standards in Germany, France, and Italy are forcing packaging-grade mills to upgrade pulping infrastructure ahead of statutory deadlines.
- Post-consumer fiber recovery:Recycling facilities in the Netherlands and Belgium are scaling hydrapulper capacity to process contaminated corrugated feedstock from e-commerce returns.
- High-consistency rotor designs:Continuous pulping technology is capturing greenfield investments where throughput optimization outweighs batch flexibility in waste paper processing.
Market Restraints
- Specialized alloy input costs:Wear-resistant rotor components require nickel-chromium alloys subject to commodity price volatility from Indonesian and Philippine supply sources.
- REACH chemical restriction protocols:Pulping additive formulations face registration burdens that extend qualification timelines for European equipment deployments.
- Mechanical pulping yield ceilings:Thermomechanical routes hit fiber length degradation limits that constrain premium packaging applications regardless of energy efficiency gains.
Strategic Opportunities
- Enzymatic pulping convergence:Biotechnology-enabled fiber modification is opening premium pricing channels with specialty paper producers seeking customized furnish properties.
- Modular equipment configurations:Decoupled capital expenditure models allow brownfield mills to phase hydrapulper upgrades without line-wide shutdowns.
- Aftermarket wear-component programs:Service contracts for rotor refurbishment and screen plate replacement are extending equipment life cycles in high-duty recycling environments.
Industry Challenges
- Rotor balancing skill scarcity:Maintenance technicians with high-speed dynamic balancing expertise for 18% consistency rotors command wage premiums that inflate service costs.
- Legacy DCS integration complexity:Continuous hydrapulper controls must interface with decades-old distributed control systems prevalent in European mills built during the 1990s fiberline expansion wave.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrapulper Market |
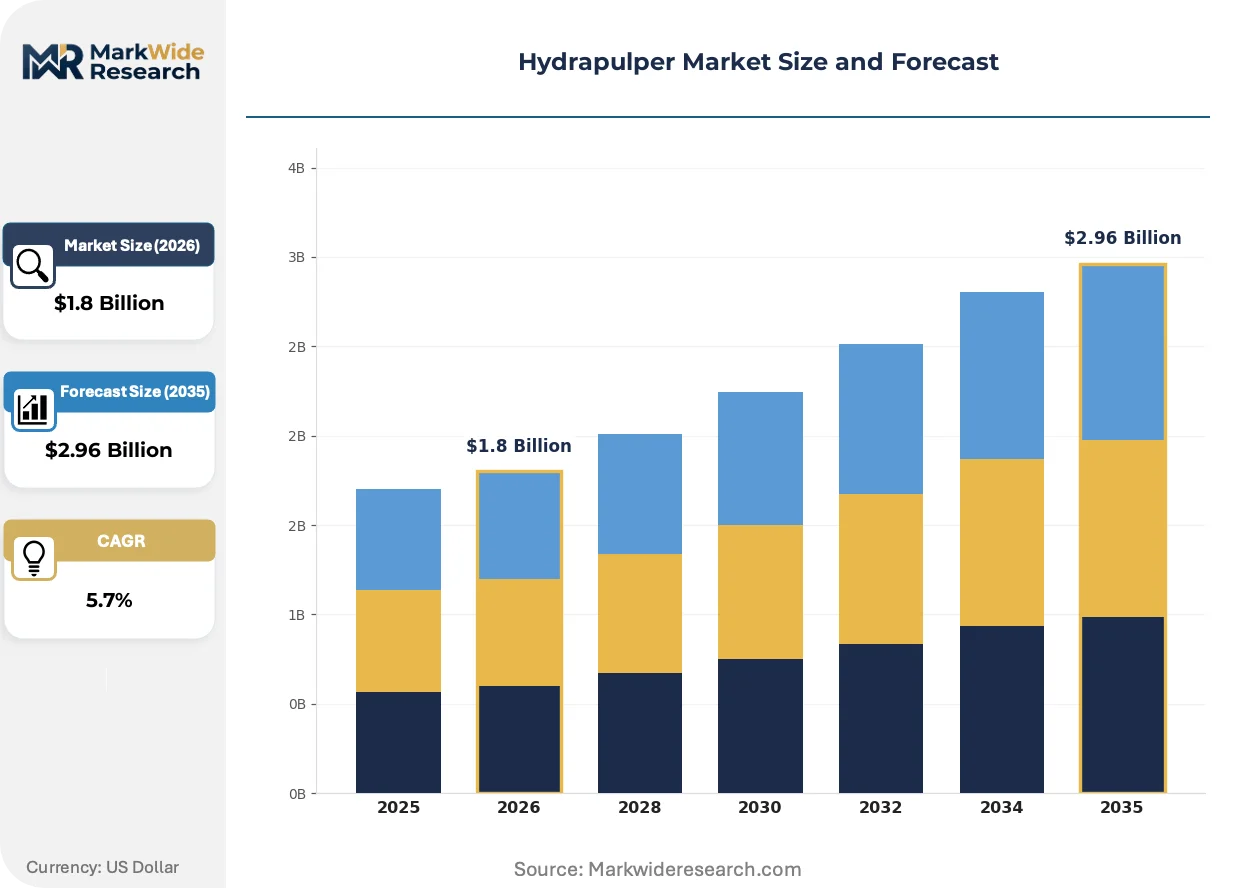
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Hydrapulpers, Continuous Hydrapulpers, Portable Hydrapulpers, High-Consistency Hydrapulpers End User: Pulp and Paper Industry, Recycling Facilities, Waste Management Firms, Food Processing Plants Technology: Mechanical Pulping, Chemical Pulping, Thermomechanical Pulping, Enzymatic Pulping Application: Wood Pulping, Waste Paper Processing, Agricultural Residue Processing, Textile Waste Processing |
| Companies Covered | ANDRITZ, Valmet, Voith, Kadant, Leizhan Machinery, Parason, CNBM International Pulp & Paper, Qinyang City Haiyang Paper Making Machinery, Qinyang Aotian Machinery Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrapulper Market Shifts & Advancements
Digital process control architectures are displacing manual consistency management in hydrapulper operations. Three developments are compressing operational variance and reshaping competitive differentiation in fiber preparation.
Machine vision-based contaminant detection is automating reject stream sorting in continuous pulping lines. OCC recycling facilities in the Rhine-Ruhr industrial cluster are deploying camera arrays that identify wax coatings and adhesive contaminants at 4-meter-per-second belt speeds. This vision infrastructure is automating operator intervention decisions that previously required manual sampling and laboratory verification, compressing response latency from hours to seconds.
REACH authorization requirements for pulping biocides are forcing formulation substitutions across European installations. ECHA's sunset date scheduling for quaternary ammonium compounds is compelling chemical suppliers to requalify enzyme-based alternatives. Packaging-grade mills in Bavaria and Baden-Württemberg are absorbing extended validation timelines as they await biocidal product family approvals under the EU BPR framework.
Performance-based service contracts are displacing time-and-material maintenance arrangements for critical wear components. Fiberline operators in the Amsterdam-Rotterdam-Antwerp corridor are negotiating rotor life guarantees tied to specific furnish mix parameters. This contracting shift transfers operational risk to equipment suppliers while locking in predictable maintenance expenditures for high-volume recycling plants.
Hydrapulper Market Segmentation
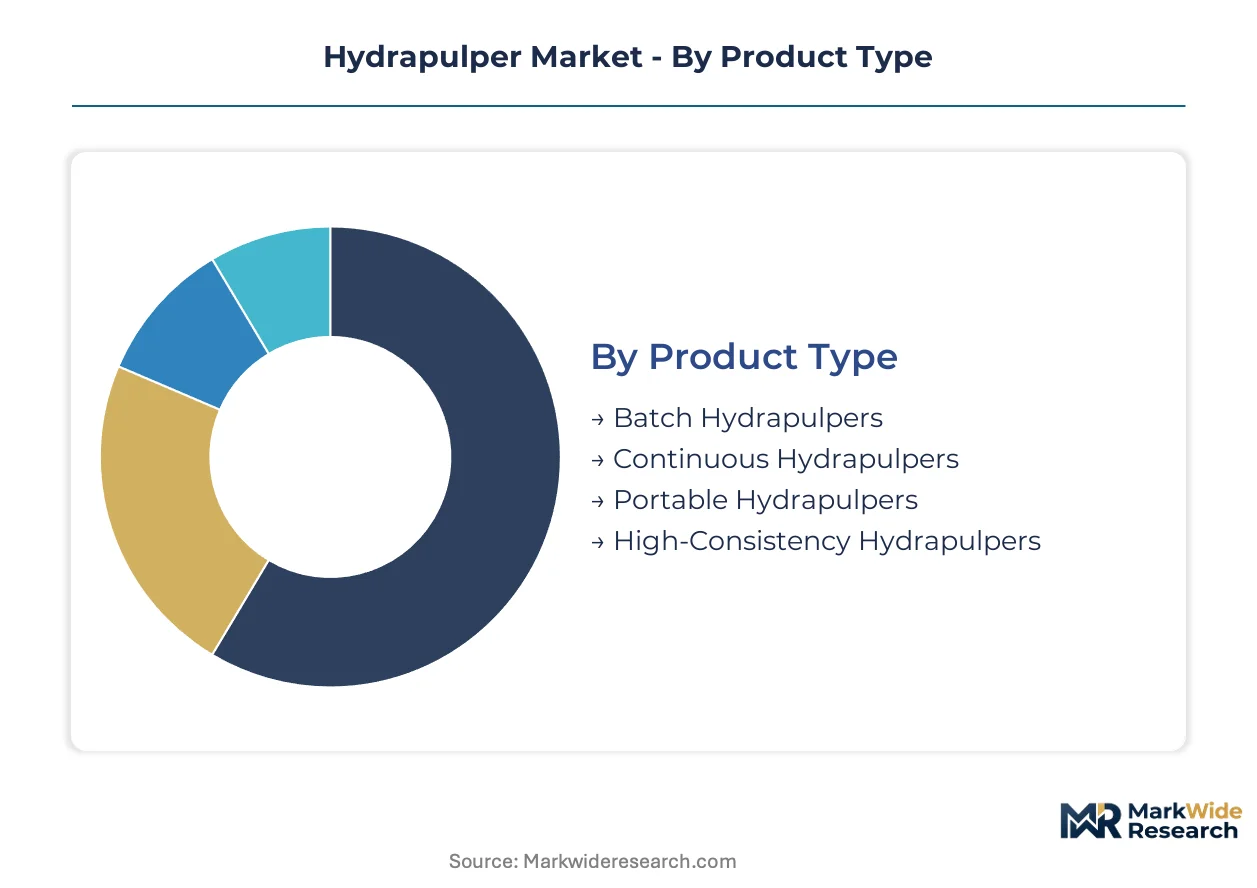
Equipment configuration choices in hydrapulper procurement directly determine capital recovery timelines and operational flexibility. Segmentation reveals where technology investments concentrate across fiber recovery value chains and which end-use specifications command engineering customization.
Product Type:
Supply concentration in rotor manufacturing and wear-component fabrication shapes equipment availability and aftermarket service reach across all four product configurations.
- Batch Hydrapulpers:These cylindrical vessels operate with intermittent loading cycles, accommodating furnish variability through adjustable dwell times. Demand concentrates in legacy European mills in Germany and Italy where production flexibility outweighs throughput optimization for specialty paper grades. The EU Green Deal's discharge timeline compression is forcing selective upgrades rather than full replacement of these installed units.
- Continuous Hydrapulpers:Drum-shaped designs with screw-fed operation achieve steady-state processing at 4-18% consistency ranges. Greenfield investments in Dutch and Belgian recycling facilities favor this technology where e-commerce corrugated returns require high-volume, low-variance fiber preparation. Energy recovery integration from continuous rotor operation is tightening project economics in Rhine-Ruhr industrial cluster deployments.
- Portable Hydrapulpers:Skid-mounted configurations enable temporary capacity augmentation at brownfield sites. Small-scale agricultural residue processors in France deploy these for seasonal campaign operations.
- High-Consistency Hydrapulpers:Specialized rotor geometries handle 15-18% consistency ranges with reduced water demand. Packaging-grade mills in Bavaria specify these for effluent minimization compliance.
Today's leader: Continuous Hydrapulpers. Tomorrow's challenger: High-Consistency Hydrapulpers.
End User:
Cost tier differentiation separates capital-intensive fiberline operators from service-contract-driven waste management intermediaries with divergent equipment procurement cycles.
- Pulp and Paper Industry:Integrated mills specify hydrapulpers as fiberline anchor equipment with 20-year depreciation horizons. German packaging-grade producers in Baden-Württemberg are scaling recycled pulp capacity fastest, driving demand for high-duty rotor designs with extended mean-time-between-failures.
- Recycling Facilities:Standalone operators process post-consumer corrugated and mixed paper streams with contamination-tolerant equipment specifications. Netherlands-based facilities in the Amsterdam-Rotterdam-Antwerp corridor are deploying machine vision-integrated pulping lines for automated contaminant rejection.
- Waste Management Firms:Diversified environmental service companies add fiber recovery as adjacent revenue streams. Italian waste-to-energy operators are retrofitting mechanical sorting plants with hydrapulper modules for secondary fiber extraction.
- Food Processing Plants:Niche applications recover cellulose from agricultural byproducts for packaging substrates. French sugar beet processors deploy specialized pulping for bagasse-derived molded fiber products.
Pulp and Paper Industry commands current procurement volume. Recycling Facilities are expanding most quickly.
Technology:
Application specificity determines technology selection, with yield requirements and effluent constraints filtering viable process routes for each fiber source.
- Thermomechanical Pulping:High-temperature refining of wood chips preserves lignin content while maximizing yield for packaging applications. German linerboard producers favor this route for reduced chemical discharge loads under tightening EU effluent standards.
- Enzymatic Pulping:Biotechnology-enabled fiber modification uses targeted cellulase cocktails for specialty furnish properties. Premium pricing from security paper and currency substrate producers in Switzerland supports highest-margin segment positioning.
- Mechanical Pulping:Stone groundwood and refiner mechanical processes serve newsprint and directory paper grades with lowest capital intensity. Declining graphic paper demand is constraining new investment.
- Chemical Pulping:Kraft and sulfite processes achieve highest fiber strength for tissue and toweling applications. REACH authorization burdens for pulping chemicals are extending European qualification timelines.
Thermomechanical Pulping leads packaging-grade deployment. Enzymatic Pulping offers steepest expansion trajectory in premium segments.
Application:
Customer type fragmentation across virgin fiber, recycled feedstock, and non-wood sources creates divergent equipment specification requirements.
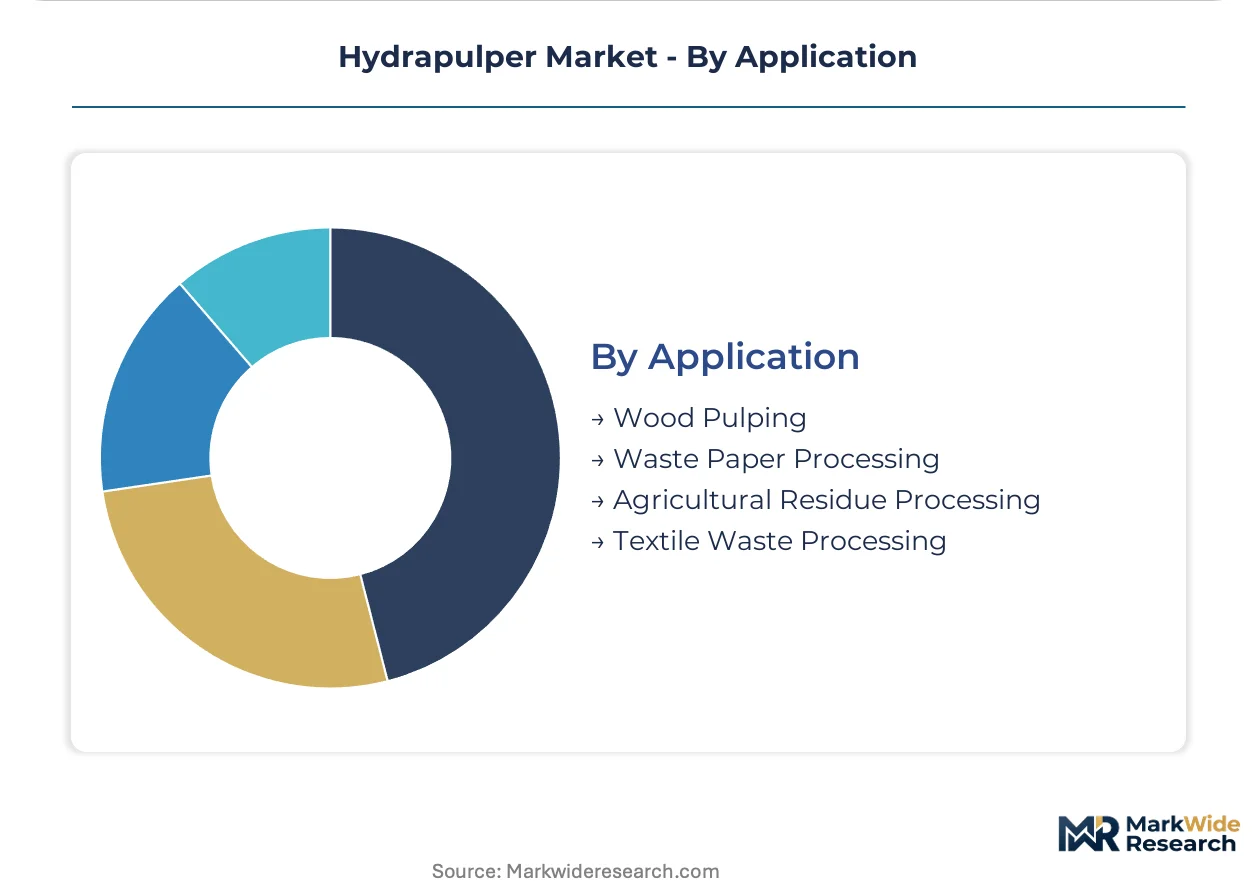
- Waste Paper Processing:Old corrugated containers and mixed office paper dominate feedstock volumes. Contaminant loads from e-commerce adhesive labels and wax coatings are driving rotor wear-component innovation in Belgian and Dutch recycling infrastructure.
- Wood Pulping:Softwood and hardwood species selection determines refining intensity and screen plate aperture specifications. German sawmill-integrated pulp operations in Bavaria are capturing residual chip streams for packaging furnish.
- Agricultural Residue Processing:Wheat straw, rice husks, and corn stalks provide annual fiber sources. French and Italian bioeconomy clusters are piloting dedicated pulping lines for non-wood packaging substrates.
- Textile Waste Processing:Cotton and synthetic blend recovery from post-consumer garments requires specialized defibration. Emerging circular textile initiatives in the Netherlands are testing hydrapulper-based fiber reclamation.
Waste Paper Processing anchors installed capacity. Agricultural Residue Processing is gaining share fastest as non-wood fiber sourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hydrapulper industry traces its modern scaling to post-war European paper machinery development, with German engineering clusters establishing the foundational rotor designs and continuous pulping architectures that dominate contemporary installations.
Germany
Baden-Württemberg and Bavaria host Europe's densest concentration of packaging-grade recycled pulp capacity, with mills scaling high-consistency rotor installations to meet EU Green Deal discharge timelines. The country's Federal Immission Control Act implements BAT conclusions for pulping effluent that exceed baseline EU standards. The Rhine-Ruhr industrial cluster anchors greenfield continuous hydrapulper deployments integrated with energy recovery systems.
United States
EPA effluent limitation guidelines drive wastewater technology upgrades across Great Lakes and Southeast recycling corridors, with mills in Wisconsin and Georgia retrofitting batch units with automated consistency controls. The Inflation Reduction Act's clean manufacturing tax credits accelerate capital deployment in containerboard recycling infrastructure. The Pacific Northwest pulp and paper cluster around Longview, Washington, pilots thermomechanical pulping retrofits for linerboard yield optimization.
China
MEE water-intensity benchmarks filter market access for imported equipment suppliers as domestic mills in Shandong and Guangdong provinces scale waste paper processing capacity. The country's dual carbon goals compress energy consumption allowances for mechanical pulping routes. The Yangtze River Delta paper machinery manufacturing base around Shanghai supplies rotor components to Southeast Asian recycling facilities.
Netherlands
Amsterdam-Rotterdam-Antwerp corridor recycling facilities deploy machine vision-integrated pulping lines for automated contaminant rejection from e-commerce corrugated returns. REACH authorization schedules for pulping biocides extend qualification timelines for enzyme-based additive formulations. Rotterdam's port-adjacent fiber recovery plants process transatlantic OCC streams with contamination-tolerant continuous hydrapulper configurations.
India
BIS certification requirements for imported paper machinery shape equipment procurement patterns as packaging board producers in Gujarat and Maharashtra expand recycled fiber capacity. The country's PLI scheme for paper sector investments accelerates greenfield mill construction with European technology licensing. The Vapi industrial cluster in Gujarat concentrates small-scale hydrapulper installations serving regional corrugated box manufacturers.
Hydrapulper Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and aftermarket service depth, with integrated fiberline engineering groups commanding pricing power over standalone equipment fabricators. The vendor base spans three strategic tiers: full-line pulp and paper technology conglomerates, specialized pulping equipment manufacturers, and regional machinery fabricators serving brownfield replacement cycles. Consolidation pressure concentrates among mid-scale European specialists, while Asian fabricators expand export capacity. Dominant competitive moves include backward integration into wear-component metallurgy and performance-based service contracting that transfers operational risk to suppliers.
Within the full-line engineering tier, ANDRITZ and Valmet exemplify integrated technology positioning that bundles hydrapulpers with downstream screening and refining systems. Kadant occupies a distinct specialist position anchored in aftermarket wear-component programs. Among Asia-Pacific fabricators, Leizhan Machinery and Parason represent regional scale-driven competitive positioning that challenges European incumbents on capital cost metrics for greenfield recycling installations.
| Leading Market Players |
|---|
| ANDRITZ |
| Valmet |
| Voith |
| Kadant |
| Leizhan Machinery |
| Parason |
| CNBM International Pulp & Paper |
| Qinyang City Haiyang Paper Making Machinery |
| Qinyang Aotian Machinery Manufacturing |
| Others |
Supply & Pricing Matrix
EU Green Deal discharge timeline compression is forcing German packaging-grade mills to accelerate rotor replacement cycles, compelling suppliers to hold regional alloy inventories that inflate working capital requirements and compress margin structures for mid-scale fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with premium tiers capturing extended rotor life guarantees and integrated digital control architectures while economy tiers compete on capital cost metrics for brownfield replacement cycles. Price differentiation hinges on certification grade under EU Machinery Directive and volume scale of fiberline deployments. Cost compression in standard-tier batch hydrapulpers is intensifying because Asian fabricators are challenging European incumbents on capital cost metrics. Recycling facilities exhibit highest price sensitivity due to thin margin structures on post-consumer fiber recovery, while integrated pulp and paper mills prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Freight cost differentials between Asian component sources and European assembly sites are widening procurement lead time spreads, with Rotterdam port congestion adding variability to rotor delivery schedules for Rhine-Ruhr industrial cluster deployments. Supply concentrates in Germany for precision rotor machining, China for cast alloy components, and Austria for fiberline engineering integration. Raw material dependencies rest on nickel-chromium alloys from Indonesian and Philippine sources, high-grade bearing steel from Japan, and specialized ceramic coatings from Germany. Single-source vulnerability in nickel-chromium alloy supply creates exposure to commodity price volatility. Distribution runs through OEM direct sales for greenfield projects and specialized aftermarket distributors for wear-component replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH authorization burdens for pulping biocides create compliance cost asymmetries against US EPA frameworks, positioning geographic arbitrage opportunities for suppliers with dual-qualification capabilities.
For Market Incumbents: Anticipate margin compression from Asian capital-cost challengers by deepening captive supply of wear-resistant alloy formulations and anchoring customer relationships through performance-based rotor life guarantees tied to specific furnish parameters. Prioritize certification investment in EU BPR-compliant enzyme-based additive integration to defend positioning against regulatory substitution risks.
For New Entrants and Emerging Players: Small-scale agricultural residue processors in France and Italy represent an underserved buyer archetype with seasonal campaign equipment needs and limited access to flexible financing. Portable skid-mounted configurations for wheat straw and corn stalk pulping offer the most penetrable segment. Pursue equipment-as-a-service go-to-market structures that transfer utilization risk from capital-constrained processors.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized wear-component aftermarket programs that generate recurring revenue streams decoupled from new equipment cycle volatility. Long-term viability hinges on fiber recovery infrastructure buildout momentum rather than virgin pulp capacity expansion. Watch qualification timeline compression for enzyme-based pulping additives under EU BPR as inflection indicator for biotechnology-enabled margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Metallurgy | Captive supply of nickel-chromium formulations insulates margin from Indonesian export volatility. |
| Performance-Based Service Contracting | Rotor life guarantees tied to furnish mix transfer operational risk from recycling facilities. |
| Machine Vision Integration Partnership | Camera array deployment for contaminant detection compresses response latency in Dutch OCC lines. |
| Modular Equipment Configuration | Decoupled capex models enable brownfield upgrades without line-wide shutdowns in legacy mills. |
| Enzymatic Pulping Technology Licensing | Biocatalytic fiber modification commands premium pricing from Swiss security paper producers. |
Research Methodology
Coverage spans Western Europe, North America, and Asia-Pacific, with primary inputs from each region combining structured interviews with fiberline engineering directors, aftermarket service managers at OEMs, procurement leads at recycling facility operators, and plant engineers at packaging-grade mills. Secondary validation draws from EU ECHA authorization databases, EPA effluent limitation guideline filings, customs trade data for paper machinery imports, and SEC disclosures from publicly traded pulp and paper technology conglomerates. Bottom-up equipment shipment tallies and top-down fiberline investment tracking provide triangulation anchors.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include equipment configuration type, end-user industry, pulping technology route, and regional regulatory cluster. CAGRs derive from installed base turnover analysis and greenfield capacity announcement tracking. Industry-specific forecast inputs incorporate EU Green Deal implementation pacing and MEE water-intensity benchmark enforcement trajectories in China.
Underlying measurement precision varies by segment; continuous hydrapulper and high-consistency rotor categories carry tighter precision than portable configurations due to more visible order flow. Forecasts reflect assumptions about regulatory timeline adherence and commodity alloy price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Packaging Racks Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Coding and Marking Equipment Market