
 Laser Coding Equipment Market | 2026-2036
Laser Coding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Coding Equipment Market Insights
Aftermarket service revenue is fragmenting as equipment vendors compete for lifetime value beyond initial hardware sales. TRUMPF sustains premium positioning through captive service networks across European industrial clusters. Videojet Technologies leverages its extensive distributor footprint to control aftermarket parts availability in North America. Han's Laser anchors volume competitiveness through in-house production of fiber laser sources, reducing dependency on external component suppliers.
Laser coding equipment employs focused coherent light to permanently alter surface material through ablation, annealing, or carbonization, typically operating at wavelengths from 1064 nm for fiber systems to 10.6 µm for CO2 platforms. The technology serves primary industrial functions including batch traceability, anti-counterfeiting serialization, and regulatory compliance marking on packaging substrates. Fiber lasers lead product type adoption due to superior efficiency on metal substrates and minimal maintenance requirements, while CO2 lasers retain structural importance for organic materials such as paperboard and glass. Among end user segments, pharmaceuticals commands premium pricing due to stringent validation protocols, whereas food and beverage represents the fastest volume expansion as producers retrofit lines for GS1-compliant traceability.
FDA 21 CFR Part 11 and EU MDR serialization mandates directly expand equipment demand by mandating machine-readable product identifiers across pharmaceutical packaging. REACH and RoHS frameworks constrain consumable material choices, favoring laser systems that eliminate solvent-based inks from production environments. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon reporting requirements, as these frameworks will progressively favor coding technologies with minimal consumable waste streams.
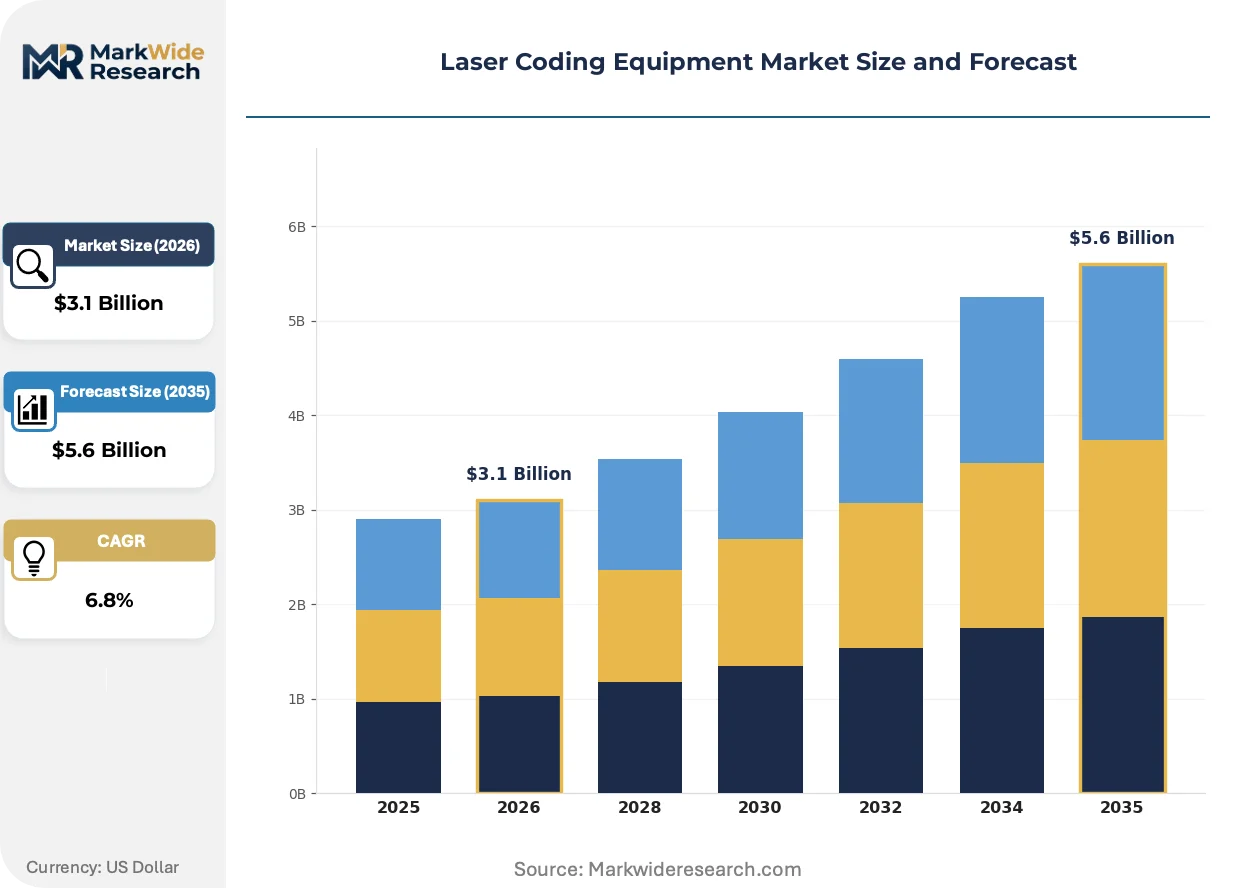
Market Dynamics
Fiber laser systems are compressing replacement cycles for legacy inkjet equipment across pharmaceutical and food packaging lines, driven by EU serialization mandates and China's dual carbon goals eliminating solvent-based consumables.
Growth Catalysts
- EU Falsified Medicines Directive:Pharmaceutical packagers across Germany, Italy, and France must deploy machine-readable serialization by 2025, mandating permanent laser marking on folding cartons and blister foils.
- China's dual carbon framework:Provincial environmental regulators in Jiangsu and Guangdong are restricting volatile organic compound emissions from solvent inks, redirecting food producers toward fiber laser ablation systems.
- Fiber source in-house production:Domestic Chinese manufacturers now produce ytterbium-doped fiber gain modules locally, collapsing lead times and import dependency for coding system integrators.
Market Restraints
- Optical component supply concentration:German and Japanese suppliers control 80% of high-precision scanning galvanometer production, exposing equipment assemblers to 16-week lead time volatility.
- Capital intensity for CO2 platform conversion:Glass tube laser sources require vacuum-sealed manufacturing infrastructure that few Asian contract manufacturers can replicate at scale.
- REACH substance restrictions:ECHA candidate list expansion for SVHCs complicates sourcing of specialized coatings for protective optical windows in high-humidity dairy environments.
Strategic Opportunities
- Indian food traceability infrastructure:FSSAI's mandatory QR code labeling for packaged foods creates first-mover positioning for fiber laser integrators serving Mumbai and Delhi-NCR processing clusters.
- Battery cell serialization:Lithium-ion manufacturers in South Korea and Japan require permanent DMC code marking on aluminum cell housings, opening adjacent demand beyond traditional packaging.
- UV laser convergence with vision systems:355nm solid-state sources combined with inline OCR verification are penetrating cosmetic and medical device marking where thermal damage risks previously blocked adoption.
Industry Challenges
- Multi-wavelength technician scarcity:Servicing hybrid fiber-CO2-UV installations demands optical engineers trained across 1064nm, 10600nm, and 355nm platforms, a skill profile concentrated in Stuttgart and Shenzhen.
- IQ/OQ/PQ validation timelines:Pharmaceutical OEMs require 12-18 month qualification protocols for new laser coding stations, compressing vendor cash conversion cycles.
- MES integration complexity:Legacy packaging lines running proprietary SCADA architectures resist seamless handshake with modern laser controller APIs, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Coding Equipment Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Lasers, CO2 Lasers, Diode Lasers, Solid-State Lasers Technology: Engraving, Marking, Etching, Printing End User: Food & Beverage, Pharmaceuticals, Electronics, Automotive Application: Packaging, Labeling, Product Identification, Traceability |
| Companies Covered | Han's Laser, TRUMPF, Videojet Technologies, Coherent Corp., IPG Photonics, Trotec Laser, RMI Laser, Laserax, FOBA Laser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Coding Equipment Market Trends and Innovations
Ultrafast picosecond sources and AI-driven parameter optimization are redefining mark quality consistency across heterogeneous substrates. Equipment vendors now compete on software-defined flexibility rather than raw optical power specifications.
Picosecond infrared sources operating at 1064nm with pulse durations below 10ps are rendering obsolete nanosecond fiber lasers for high-contrast annealing on stainless steel surgical instruments. German medical device contract manufacturers in Tuttlingen and Freiburg are retrofitting lines at 18-month replacement cycles. The technology is compressing heat-affected zones below 50 microns, eliminating post-mark passivation requirements.
REACH Annex XIV authorization procedures for chromium trioxide in electroplating are redirecting automotive component suppliers toward laser-induced dark marking on bare aluminum engine parts. Tier-1 suppliers in Stuttgart and Wolfsburg are qualifying fiber systems for VIN-equivalent traceability on powertrain castings. The regulation is accelerating substitution away from chemical etching baths in Czech and Polish stamping plants serving German OEMs.
Indian pharmaceutical exporters are consolidating supplier relationships around vendors offering bundled validation documentation and spare part consignment inventory. Mumbai-based generic manufacturers now specify 48-hour technician response SLAs as standard procurement terms. This concentration is visible in the Maharashtra and Gujarat formulation clusters where US FDA warning letter exposure drives preference for single-source equipment accountability.
Laser Coding Equipment Market Segmentation
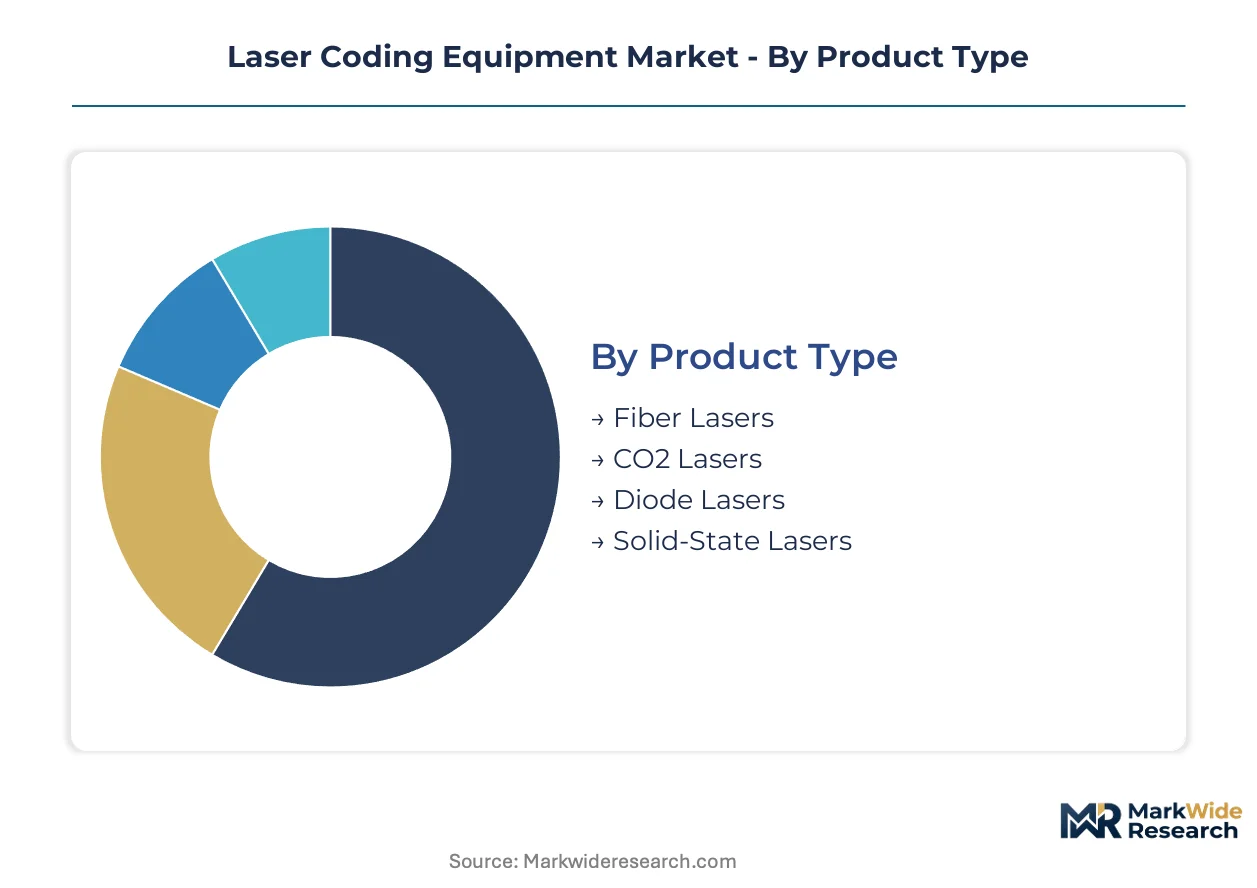
Laser coding equipment segmentation reflects divergent maturity curves across optical technologies and industrial use cases. Equipment buyers select platforms based on substrate compatibility, regulatory validation burden, and total cost of ownership across decade-long service intervals.
Product Type:
Mature fiber and CO2 platforms anchor installed capacity, while diode and solid-state architectures emerge at technology frontiers demanding specialized wavelength performance.
- Fiber Lasers:Ytterbium-doped fiber gain modules generate 1064nm output with wall-plug efficiency exceeding 25%, enabling high-speed ablation on metal and plastic substrates. German pharmaceutical packagers in Stuttgart and Italian food producers in Emilia-Romagna are standardizing on fiber systems to eliminate solvent ink consumables under REACH frameworks.
- CO2 Lasers:Sealed-tube or RF-excited designs at 10.6µm wavelength excel on organic materials including paperboard, glass, and wood. Chinese dairy processors in Inner Mongolia and Heilongjiang retain CO2 dominance for date coding on laminated cartons where fiber absorption remains inefficient.
- Diode Lasers:Direct-emitting semiconductor sources at 808-980nm serve low-power marking on heat-sensitive electronics housings.
- Solid-State Lasers:Nd:YVO4 and vanadate crystals enable frequency-converted UV output at 355nm for medical device marking requiring minimal thermal damage.
Fiber lasers handle the majority of throughput; solid-state UV platforms are gaining share fastest in medical and cosmetic applications.
Technology:
Cost tier stratification separates capital-intensive engraving stations from high-speed printing modules optimized for continuous production economics.
- Engraving:Deep material removal through multi-pass ablation creates tactile, wear-resistant marks on metal tooling and automotive components. Tier-1 suppliers in Wolfsburg specify engraving depth control for powertrain traceability marks surviving 15-year vehicle lifecycles.
- Marking:Surface-level annealing or carbonization produces high-contrast codes without dimensional change. Indian pharmaceutical exporters in Mumbai deploy marking for blister foil serialization meeting US FDA track-and-trace mandates.
- Etching:Chemical-assisted laser processes remove selective material layers on coated metals.
- Printing:Raster-scan deposition mimics inkjet speed with permanent laser-induced marks on flexible packaging films.
Marking commands the largest installed base; printing is climbing fastest as food packagers retrofit lines for GS1-compliant variable data.
End User:
Application-specific margin structures range from pharmaceutical validation premiums to automotive volume pricing disciplined by tier-n supplier consolidation.
- Food & Beverage:Producers retrofit legacy lines for QR-code traceability under FSSAI and EU Food Information to Consumers regulations. Jiangsu and Guangdong provincial environmental offices are accelerating fiber laser adoption by restricting solvent ink emissions.
- Pharmaceuticals:Serialization mandates under EU Falsified Medicines Directive and FDA DSCSA require IQ/OQ/PQ-validated systems with 21 CFR Part 11 electronic records compliance. German generic manufacturers in Baden-Württemberg specify redundant fiber stations to prevent batch rejection.
- Electronics:PCB and component marking demands micron-precision positioning on miniaturized substrates.
- Automotive:Powertrain and battery cell serialization tracks components through multi-tier supply chains.
Food and beverage generates the highest unit volumes; pharmaceuticals captures the steepest expansion trajectory as serialization deadlines approach.
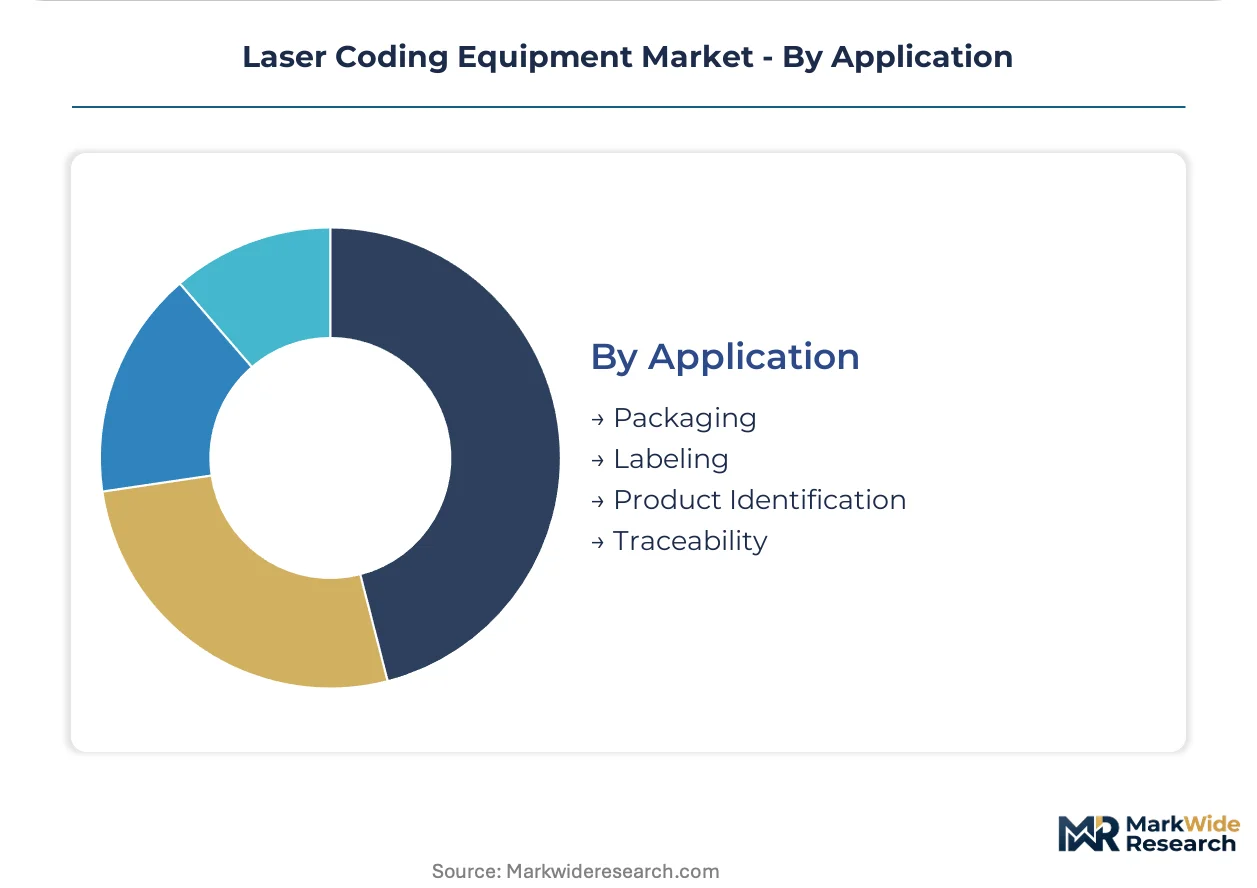
Application:
Customer type differentiation separates OEM-integrated traceability from aftermarket labeling retrofits on legacy packaging infrastructure.
- Packaging:Primary and secondary container marking dominates fiber laser deployment across folding cartons, flexible films, and rigid plastics. French cosmetic houses in Normandy specify packaging-grade systems with vision-verified OCR for luxury export compliance.
- Labeling:Adhesive label stock marking before application enables variable data without direct substrate contact. Japanese electronics assemblers in Osaka prefecture prefer pre-printed laser labels for ESD-sensitive cleanroom environments.
- Product Identification:Direct part marking on bare metal or molded plastic replaces adhesive labels in harsh environments.
- Traceability:End-to-end supply chain tracking integrates laser marks with ERP and MES systems.
Packaging absorbs the dominant share of equipment shipments; traceability is expanding most quickly as battery and medical device sectors adopt permanent marking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. European pharmaceutical packagers prioritize validation-heavy fiber systems for EU serialization mandates, while Chinese food processors drive volume expansion through environmental compliance upgrades. Indian exporters concentrate demand around bundled service contracts with rapid response guarantees.
Germany
Stuttgart and Wolfsburg automotive clusters demand deep-engraving fiber systems for powertrain traceability marks surviving 15-year vehicle lifecycles. REACH Annex XIV authorization procedures for chromium trioxide redirect Tier-1 suppliers from chemical etching toward laser-induced dark marking on bare aluminum engine parts. Baden-Württemberg pharmaceutical generic manufacturers specify redundant fiber stations to prevent batch rejection under EU Falsified Medicines Directive deadlines.
China
Jiangsu and Guangdong provincial environmental offices restrict volatile organic compound emissions from solvent inks, redirecting food producers toward fiber laser ablation systems. Domestic manufacturers now produce ytterbium-doped fiber gain modules locally, collapsing lead times and import dependency for coding system integrators. Inner Mongolia and Heilongjiang dairy processors retain CO2 dominance for date coding on laminated cartons where fiber absorption remains inefficient.
India
FSSAI mandatory QR code labeling for packaged foods creates first-mover positioning for fiber laser integrators serving Mumbai and Delhi-NCR processing clusters. Mumbai-based generic manufacturers specify 48-hour technician response SLAs as standard procurement terms. Maharashtra and Gujarat formulation clusters consolidate supplier relationships around vendors offering bundled validation documentation and spare part consignment inventory.
United States
FDA DSCSA serialization mandates drive pharmaceutical packagers toward IQ/OQ/PQ-validated fiber systems with 21 CFR Part 11 electronic records compliance. Electronics assemblers in California and Texas demand micron-precision positioning for PCB and component marking on miniaturized substrates. Midwest food processors retrofit legacy lines for GS1-compliant variable data as traceability requirements tighten across retail supply chains.
Japan
Osaka prefecture electronics assemblers prefer pre-printed laser labels for ESD-sensitive cleanroom environments, avoiding direct substrate contact. Lithium-ion manufacturers in South Korea and Japan require permanent DMC code marking on aluminum cell housings, opening adjacent demand beyond traditional packaging. METI industrial efficiency guidelines accelerate replacement of solvent-based inkjet systems in automotive component supply chains.
Laser Coding Equipment Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. German and Japanese optical component specialists control high-precision scanning galvanometer production, exposing equipment assemblers to 16-week lead time volatility. Three archetypes dominate: vertically integrated fiber source producers, captive service network operators, and distributor-anchored aftermarket controllers. Competitive moves concentrate on backward integration into ytterbium-doped fiber gain modules and geographic expansion through validation-capable service subsidiaries.
Within the premium-tier service vector, TRUMPF sustains positioning through captive service networks across European industrial clusters. Videojet Technologies leverages its extensive distributor footprint to control aftermarket parts availability in North America. Han's Laser anchors volume competitiveness through in-house production of fiber laser sources, reducing dependency on external component suppliers. These three occupy distinct strategic positions without direct segment overlap.
| Leading Market Players |
|---|
| Han's Laser |
| TRUMPF |
| Videojet Technologies |
| Coherent Corp. |
| IPG Photonics |
| Trotec Laser |
| RMI Laser |
| Laserax |
| FOBA Laser |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese fiber gain module production is compressing equipment margins while simultaneously expanding supplier flexibility for system integrators. This utilization dynamic rewards buyers with pricing leverage on standard platforms while concentrating premium capture among vendors with captive optical component production.
Pricing Analysis
Long-term service contracts dominate pharmaceutical procurement, with packagers bundling hardware, validation documentation, and spare part consignment into multi-year agreements. Price differentiation rests on IQ/OQ/PQ certification tier and geographic proximity of technician networks. Cost compression in standard fiber systems is intensifying because domestic Chinese manufacturers now produce ytterbium-doped sources internally. Food and beverage processors show highest price sensitivity due to thin operating margins, while pharmaceutical OEMs accept premium positioning for regulatory risk mitigation.
Supply Chain Analysis
German and Japanese export-control frameworks on high-precision galvanometer technology constrain component flows to equipment assemblers in Asia. Manufacturing capacity concentrates in Germany, China, and Japan, with German suppliers controlling scanning optics and Chinese producers dominating fiber gain module assembly. Supply chains draw from ytterbium-doped fiber, precision optical coatings, and vacuum-sealed glass tubes. Single-source vulnerability persists for galvanometer subassemblies. Distribution runs through captive service networks in Europe and distributor-anchored parts channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue is expanding faster than hardware shipments as pharmaceutical packagers consolidate around vendors offering bundled validation and rapid-response technician SLAs. This service-attach dynamic repositions competitive advantage toward lifecycle value capture rather than initial equipment margin.
For Market Incumbents: Entrench position by deepening backward integration into ytterbium-doped fiber gain modules and expanding captive technician networks across Maharashtra and Gujarat pharmaceutical clusters. Defend against emerging Chinese system integrators by accelerating IQ/OQ/PQ documentation bundling for FDA-exposed generic manufacturers. Channel control through spare part consignment inventory represents the critical retention lever.
For New Entrants and Emerging Players: Establish a beachhead in Indian food traceability infrastructure by targeting Mumbai and Delhi-NCR processing clusters ahead of FSSAI enforcement acceleration. Penetrate battery cell serialization adjacent demand in South Korean and Japanese lithium-ion manufacturing. A software-defined flexibility positioning—competing on parameter optimization rather than raw optical power—sidesteps incumbent scale advantages in hardware production.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across standard fiber laser platform manufacturing as Chinese domestic sourcing collapses component lead times. Five-to-ten year viability favors vendors with hybrid technology portfolios spanning fiber, CO2, and UV architectures. Acquisition target archetype: regional service specialists with validated pharmaceutical customer relationships and technician density in underserved regulatory clusters. Watch for galvanometer supply disruption as an inflection signal compressing equipment delivery timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Sources | In-house ytterbium-doped module production collapses lead times and import dependency for Chinese system integrators. |
| Validation Documentation Bundling | IQ/OQ/PQ package consolidation addresses FDA-exposed pharmaceutical OEM risk mitigation requirements. |
| Captive Service Network Expansion | Technician density in Stuttgart and Shenzhen industrial clusters supports premium positioning through response-time SLAs. |
| Multi-Wavelength Technology Portfolio | Hybrid fiber-CO2-UV capability captures medical device and cosmetic marking demand beyond packaging. |
| Software-Defined Parameter Optimization | AI-driven mark quality consistency shifts competitive basis from optical power to substrate adaptability. |
Research Methodology
Initial hypotheses were tested against primary input from packaging line engineers, pharmaceutical validation specialists, aftermarket service directors, and optical component procurement leads and refined through secondary validation. Primary fieldwork combined structured interviews with equipment end-users and channel partners across German automotive clusters, Chinese food processing provinces, and Indian pharmaceutical export zones. Secondary sources included FDA 21 CFR Part 11 guidance documents, EMA serialization directive filings, ECHA REACH substance restriction updates, and trade flow data for precision optical components. Bottom-up equipment shipment estimates were triangulated against top-down addressable market calculations.
Demand-supply balance modeling anchored forecast construction across the analysis window. Segmentation dimensions included laser source type, marking technology depth, end-use industry regulatory intensity, and regional compliance deadline clustering. CAGRs were derived from installed base replacement cycle analysis and greenfield line expansion trajectories. Industry-specific inputs incorporated EU Falsified Medicines Directive enforcement timelines and China's dual carbon framework provincial implementation schedules.
Stress conditions across galvanometer supply disruption, REACH substance list expansion, and pharmaceutical validation timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory deadline adherence and component localization trends. Material shifts in EU MDR serialization requirements or German-Japanese export control scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Cannabis Packaging Equipment Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Shrink Wrap Equipment Market