
 Corrugated Equipment Market | 2026-2036
Corrugated Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Equipment Market Intelligence
Recycled linerboard is consolidating demand away from virgin kraft in corrugated equipment procurement. Bobst Group leverages its rotary die cutter portfolio to anchor European packaging automation. BHS Corrugated sustains engineering dominance through in-house production of corrugator rolls and precision flute profiles. Mitsubishi Heavy Industries competes on large-format corrugator scale across Asian manufacturing corridors.
Corrugated equipment encompasses machinery designed to form, cut, score, fold, and glue paperboard into fluted structures, typically operating at speeds exceeding 300 meters per minute on continuous production lines. These systems convert raw linerboard and medium into finished boxes for protective shipping and retail-ready display packaging. Folder gluer systems command the deepest margin pools due to complex adhesive control and inline finishing requirements. Automatic technology segments lead capital deployment as warehouse operators and packing plants pursue throughput consistency with reduced manual intervention. Digital control architectures are displacing programmable logic control in premium installations where real-time flute adjustment and predictive maintenance protocols reduce material waste.
EPA emissions standards and OSHA machine guarding requirements shape equipment design specifications for installations across United States manufacturing facilities. EU REACH compliance and CE marking directives govern chemical adhesive formulations and electrical safety certification for European market access. Stakeholders must weigh regulatory compliance costs against automation efficiency gains when configuring production lines for cross-border contract fulfillment.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-ship cycles below 24 hours. This velocity mandate forces corrugated equipment buyers to prioritize inline finishing and predictive maintenance architectures over standalone batch systems.
Growth Catalysts
- EU Green Deal compliance:Packaging producers in Germany and the Netherlands are retrofitting corrugators with heat recovery systems to meet tightening F-Gas Regulation thresholds on industrial refrigeration emissions.
- Automated packaging lines:Third-party logistics operators across North American distribution corridors are installing folder-gluer systems with robotic palletizing to handle SKU proliferation without proportional labor expansion.
- Precision engineering clusters:Stuttgart and Munich manufacturing corridors sustain concentrated demand for high-speed rotary die cutters capable of micro-flute production for electronics protective packaging.
Market Restraints
- Linerboard cost volatility:OCC (old corrugated containers) price swings in North American spot markets compress equipment ROI calculations for mid-scale independent converters.
- Roll supply concentration:Precision-ground corrugator rolls require specialized foundry capacity concentrated in German and Japanese industrial zones, creating 16-24 week lead time exposure.
- CE marking complexity:Machinery safety directive compliance for adhesive application zones adds 8-12 weeks to European installation timelines versus comparable US deployments.
Strategic Opportunities
- India packaging automation:Domestic e-commerce fulfillment infrastructure remains 60-70% manual, creating whitespace for automatic folder-gluer and inline bundling system penetration.
- Digital control convergence:Real-time flute adjustment algorithms combined with IoT vibration sensing enable predictive roll-change scheduling, reducing linerboard waste by measurable tonnage per shift.
- US IRA manufacturing credits:Domestic production incentives for packaging machinery assembly are attracting European component suppliers to establish Southeast US fabrication facilities.
Industry Challenges
- Mechatronics talent scarcity:Servo control programming for multi-axis folder-gluer synchronization requires skill sets concentrated in automotive automation sectors, not traditional packaging engineering pipelines.
- Legacy PLC integration:Brownfield corrugated plants operating 1990s-era control architectures face prohibitive rewiring costs when upgrading to digital servo systems with real-time diagnostic protocols.
- Adhesive certification timelines:FDA food-contact and EU REACH dual compliance for hot-melt formulations extends new product qualification cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Equipment Market |
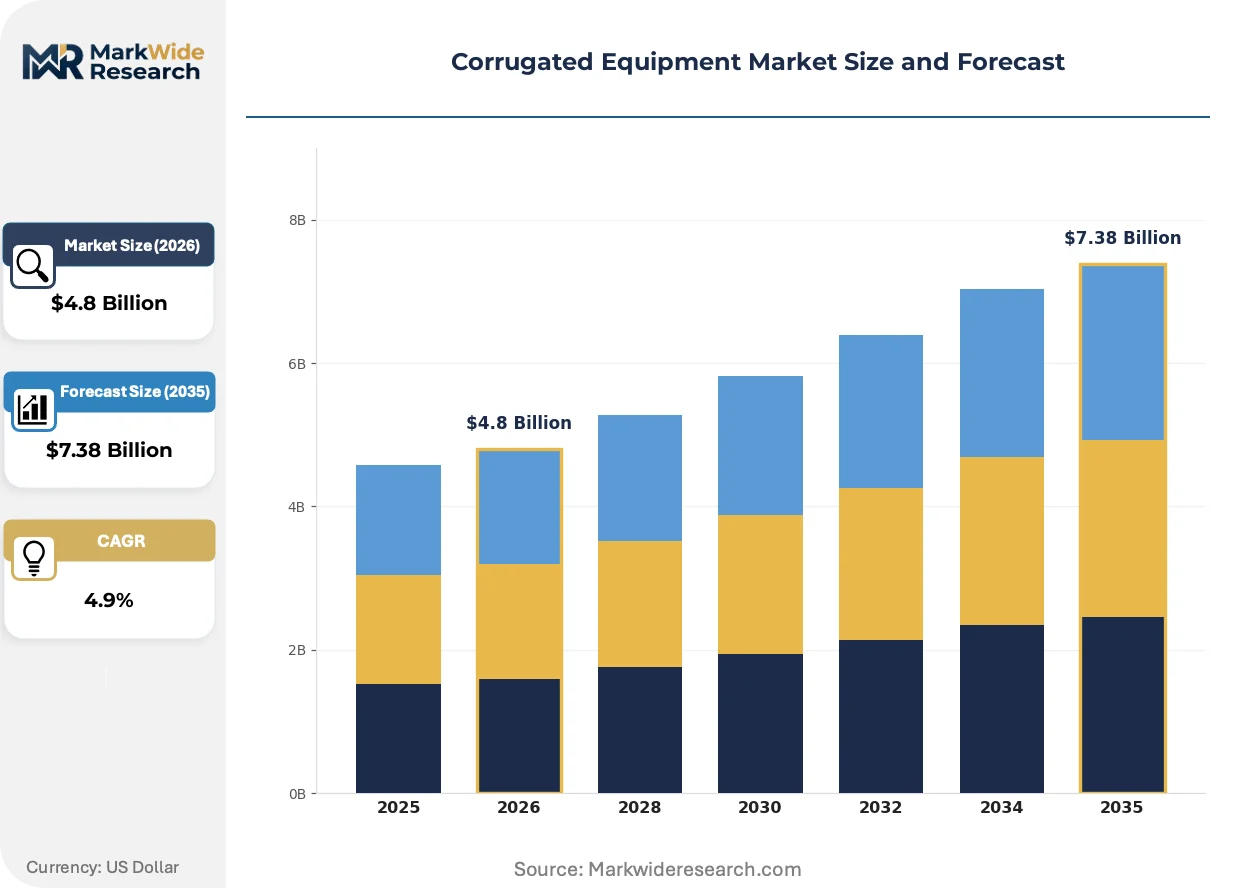
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.38 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Facer, Double Facer, Slitter Scorer, Folder Gluer, Rotary Die Cutter Technology: Automatic, Semi-Automatic, Manual, Digital Control, Programmable Logic Control Application: Packaging, Printing, Labeling, Material Handling, Palletizing End User: Packing Plants, Printing Houses, Warehouse Operators, Box Manufacturers |
| Companies Covered | Bobst Group, BHS Corrugated, Mitsubishi Heavy Industries, Barry-Wehmiller, Heidelberger Druckmaschinen, Fosber Group, Manroland, Sun Automation, Simon Corrugated Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Equipment Market Strategic Shifts & Innovations
Digital servo architectures are displacing mechanical line shafts across premium corrugator installations. This shift enables independent speed zones and real-time flute profile adjustment without stopping production.
Vision-guided robotic pack-out is automating finished case handling at speeds exceeding 40 cases per minute. Amazon and Walmart fulfillment centers in Texas and Pennsylvania are deploying these systems to eliminate manual palletizing bottlenecks during peak seasonal volume. The technology is compressing labor requirements by 70% in greenfield automated lines versus conventional configurations.
EPA emissions standards for industrial adhesive curing are tightening volatile organic compound thresholds in California and Northeast corridor states. Corrugated equipment OEMs are responding with nitrogen-sealed drying zones and catalytic oxidation afterburners that add 12-15% to system capex. Food-contact packaging producers face the steepest compliance burden due to FDA dual jurisdiction over indirect food additives.
Outcome-based maintenance contracts are displacing time-based service agreements among large-format corrugator operators. Packaging converters in the German Ruhr industrial cluster now pay per million square meters produced rather than annual service retainers. This model transfers vibration sensor and thermal imaging infrastructure costs to equipment vendors while guaranteeing 98% uptime thresholds.
Corrugated Equipment Market Segmentation
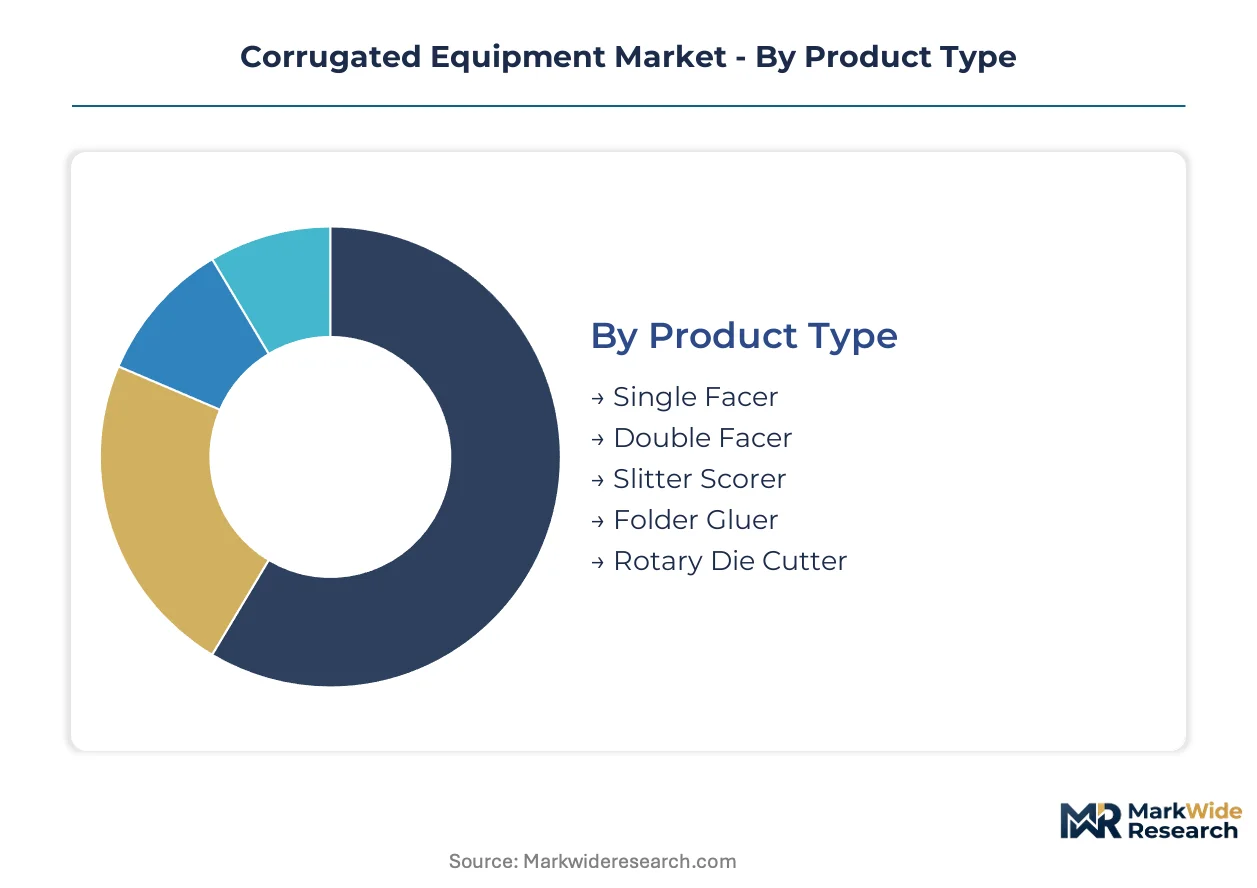
Corrugated equipment procurement decisions cluster around certification requirements, throughput velocity, and integration complexity. Buyers configure production lines by matching technology tiers to end-use regulatory exposure rather than pursuing maximum automation indiscriminately.
Product Type:
CE marking and FDA food-contact compliance burden varies sharply across equipment categories, with adhesive-contact systems facing the steepest qualification timelines.
- Folder Gluer:Complex adhesive control systems with inline finishing modules command the deepest margin pools in corrugated equipment. German automotive parts suppliers and Dutch fresh produce distributors prioritize these systems for 24-hour order-to-ship cycles, accepting 14-18 month hot-melt formulation qualification periods under EU REACH and FDA dual jurisdiction.
- Rotary Die Cutter:Precision-ground cutting cylinders operating at speeds exceeding 300 meters per minute enable micro-flute production for electronics protective packaging. Stuttgart and Munich manufacturing corridors sustain concentrated demand from precision engineering clusters serving consumer electronics OEMs.
- Single Facer:Heat recovery retrofits dominate German and Netherlands procurement to meet F-Gas Regulation thresholds on industrial refrigeration emissions.
- Double Facer:Continuous steam-heated platens bond linerboard to fluted medium at production line speeds.
- Slitter Scorer:Inline precision cutting and creasing modules prepare board for downstream folder-gluer integration.
Leading the category by volume: Folder Gluer. Growing fastest: Rotary Die Cutter.
Technology:
Capital deployment patterns separate brownfield retrofit opportunities from greenfield automation mandates, with control architecture age determining upgrade feasibility.
- Digital Control:Real-time flute adjustment algorithms combined with IoT vibration sensing enable predictive roll-change scheduling. Third-party logistics operators across Texas and Pennsylvania fulfillment corridors deploy these architectures to reduce linerboard waste by measurable tonnage per shift.
- Automatic:Robotic palletizing and vision-guided pack-out systems eliminate manual bottlenecks at speeds exceeding 40 cases per minute. Amazon and Walmart distribution centers achieve 70% labor compression versus conventional configurations during peak seasonal volume.
- Semi-Automatic:Mid-scale independent converters balance throughput gains against OCC price volatility exposure in North American spot markets.
- Manual:India's domestic e-commerce fulfillment infrastructure remains 60-70% manual, creating whitespace for automation penetration.
- Programmable Logic Control:Legacy 1990s-era architectures face prohibitive rewiring costs when upgrading to digital servo systems with real-time diagnostic protocols.
Dominant by installed base: Programmable Logic Control. Expanding most quickly: Digital Control.
Application:
Inline integration requirements separate packaging-automation investments from standalone auxiliary systems in buyer capital allocation.
- Packaging:Protective shipping and retail-ready display conversion commands the largest equipment procurement budgets. E-commerce fulfillment networks compress order-to-ship cycles below 24 hours, forcing prioritization of inline finishing over batch systems.
- Palletizing:Vision-guided robotic pack-out automates finished case handling at greenfield automated lines. Labor requirements compress versus conventional configurations through robotic integration.
- Printing:Flexographic and digital print stations integrate at corrugator infeed for retail-ready graphics.
- Labeling:Inline barcode and RFID application modules support warehouse management system integration.
- Material Handling:Conveyor and divert systems manage WIP flow between corrugator sections.
Highest capital absorption: Packaging. Steepest expansion trajectory: Palletizing.
End User:
Customer scale and contract fulfillment scope determine technology tier selection and maintenance contract structure.
- Warehouse Operators:Outcome-based maintenance contracts displace time-based service agreements among large-format corrugator operators. German Ruhr industrial cluster converters now pay per million square meters produced rather than annual service retainers, transferring vibration sensor infrastructure costs to equipment vendors.
- Box Manufacturers:Precision-ground corrugator rolls require specialized foundry capacity concentrated in German and Japanese industrial zones, creating 16-24 week lead time exposure that shapes procurement planning.
- Packing Plants:SKU proliferation without proportional labor expansion drives folder-gluer system deployment across North American distribution corridors.
- Printing Houses:Graphics-intensive retail packaging demands drive rotary die cutter and inline print integration.
Largest equipment fleet: Box Manufacturers. Fastest contract structure innovation: Warehouse Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corrugated equipment procurement concentrates in economies with dense e-commerce fulfillment networks and precision manufacturing clusters. Germany, the United States, China, Japan, and India collectively absorb the majority of capital deployment for high-speed corrugators and automated folder-gluer systems.
Germany
Stuttgart and Munich engineering corridors sustain concentrated demand for micro-flute rotary die cutters serving electronics OEMs. The F-Gas Regulation drives heat recovery retrofits on industrial refrigeration systems across Ruhr Valley packaging plants. Outcome-based maintenance contracts now dominate, with converters paying per million square meters produced rather than annual service retainers.
United States
Texas and Pennsylvania fulfillment centers deploy vision-guided robotic pack-out systems to eliminate palletizing bottlenecks during peak seasonal volume. EPA emissions standards for adhesive curing tighten volatile organic compound thresholds in California and Northeast corridor states. The Inflation Reduction Act manufacturing credits attract European component suppliers to establish Southeast fabrication facilities.
China
Domestic e-commerce infrastructure expansion drives large-format corrugator installations across Yangtze River Delta manufacturing zones. MIIT energy efficiency standards accelerate digital servo architecture adoption displacing mechanical line shafts. Guangdong and Jiangsu provinces concentrate precision roll grinding capacity serving Asian packaging converters.
Japan
Consumer electronics protective packaging demand sustains orders for high-speed single facers in Nagoya and Osaka industrial belts. METI carbon neutrality roadmaps pressure equipment vendors to develop nitrogen-sealed drying zones reducing thermal emissions. Precision foundry capacity for corrugator rolls remains concentrated in Chubu region industrial zones.
India
Domestic fulfillment infrastructure remains 60-70% manual, creating whitespace for automatic folder-gluer penetration in Maharashtra and Gujarat industrial corridors. BIS machinery safety certification requirements extend installation timelines versus comparable Southeast Asian deployments. Bangalore and Chennai e-commerce hubs drive initial robotic palletizing trials among third-party logistics operators.
Corrugated Equipment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated corrugator lines consolidating around engineering-intensive European and Japanese fabricators while auxiliary systems fragment across regional specialists. The market structures into three tiers: precision engineering houses controlling heat transfer and roll grinding IP, automation integrators bundling robotics with legacy equipment retrofits, and emerging Asian fabricators competing on delivery velocity for standardized configurations. Dominant competitive moves include backward integration into corrugator roll production and geographic licensing partnerships to bypass 16-24 week lead time exposure.
Within the precision engineering tier, Bobst Group and BHS Corrugated exemplify divergent strategic positioning. Bobst anchors European packaging automation through rotary die cutter portfolio depth, while BHS occupies a position sustained by in-house production of corrugator rolls and precision flute profiles. Mitsubishi Heavy Industries represents the scale-driven Asian archetype, competing on large-format corrugator installations across manufacturing corridors where throughput velocity outweighs customization requirements.
| Leading Market Players |
|---|
| Bobst Group |
| BHS Corrugated |
| Mitsubishi Heavy Industries |
| Barry-Wehmiller |
| Heidelberger Druckmaschinen |
| Fosber Group |
| Manroland |
| Sun Automation |
| Simon Corrugated Machinery |
| Others |
Cost & Logistics Intelligence
Third-party logistics operators and e-commerce fulfillment centers concentrate procurement authority for high-speed folder-gluer systems, driving a contract-based pricing model where outcome-based maintenance agreements displace traditional capital expenditure structures. This buyer concentration transfers vibration sensor infrastructure costs to equipment vendors while compressing upfront pricing power for mid-tier fabricators.
Pricing Analysis
High-volume rotary die cutter installations operate on thin per-unit margins while precision folder-gluer systems with inline finishing modules capture deeper margin pools through complex adhesive control IP. Price differentiation hinges on CE marking certification tier and real-time diagnostic capability, with premium digital servo architectures commanding substantial premiums over legacy PLC configurations. Cost compression in standard automatic equipment intensifies as Chinese fabricators expand delivery velocity for standardized corrugator lines. Mid-scale independent converters in North American spot markets exhibit the highest price sensitivity due to OCC volatility exposure, whereas German precision engineering clusters prioritize throughput consistency over acquisition cost.
Supply Chain Analysis
Refurbishment flows for corrugator rolls and precision grinding services create secondary supply channels that extend asset life cycles and buffer against new equipment lead time exposure. Precision-ground roll manufacturing concentrates in Germany and Japan, drawing from specialized foundry capacity and advanced metallurgical formulations. The supply chain rests on bimetallic roll blanks, precision grinding machinery, and heat treatment infrastructure, with single-source vulnerability concentrated in Chubu region industrial zones for critical flute profile components. Distribution runs through direct OEM channels for integrated corrugator lines and regional specialist networks for auxiliary retrofit systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrugated equipment market functions as a cost-of-compliance story where EU F-Gas Regulation thresholds and FDA food-contact adhesive certification create substantial barrier-to-entry moats for players with established regulatory navigation capabilities.
For Market Incumbents: Deploy backward integration into precision roll grinding capacity to neutralize the 16-24 week lead time exposure threatening delivery commitments. Anchor market position through outcome-based maintenance contract proliferation, transferring sensor infrastructure costs to vendor balance sheets while locking in multi-year revenue streams. Counter emerging Asian fabricators by emphasizing CE marking navigation expertise and REACH-compliant hot-melt formulation libraries that compress customer qualification cycles. For New Entrants and Emerging Players: Regional automation integrators in India's Maharashtra and Gujarat corridors represent the most penetrable channel partner type for folder-gluer system penetration where domestic fulfillment infrastructure remains predominantly manual. Target whitespace in robotic palletizing retrofits for brownfield corrugated plants seeking labor compression without full line replacement. Pursue a component-supplier-to-system-integrator trajectory, establishing relationships with European OEMs seeking Southeast US assembly presence under IRA manufacturing credits. For Investors and Strategic Acquirers: The window for entry favors precision engineering houses with captive roll production and established regulatory compliance infrastructure over pure-play automation integrators. Acquisition targets should demonstrate in-house heat transfer IP or precision flute profile capabilities rather than assembly-only positioning. Monitor India BIS machinery safety certification timeline extensions as an early signal of market access friction that will concentrate share among pre-qualified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery Retrofit Deployment | Enables F-Gas Regulation compliance for German and Netherlands packaging producers without full line replacement. |
| Digital Servo Architecture Migration | Displaces mechanical line shafts for real-time flute adjustment and predictive maintenance capability. |
| Backward Integration into Roll Production | Neutralizes supply concentration risk in German and Japanese precision grinding capacity. |
| Outcome-Based Maintenance Contract Expansion | Transforms revenue structure from capital sale to per-million-square-meter service agreements. |
| Southeast US Fabrication Establishment | Captures IRA manufacturing credits while positioning for North American distribution corridor demand. |
Research Approach
Multi-period observation of corrugator installation rates, OEM order backlogs, and regulatory compliance timeline extensions anchored the trend analysis, supplemented by interviews with plant engineers at box manufacturing facilities, procurement leads at third-party logistics operators, aftermarket service heads at equipment vendors, and technical R&D directors at adhesive suppliers. Secondary validation drew from SEC 10-K filings of listed machinery manufacturers, EU ECHA REACH registration databases, US EPA emissions compliance records, and customs trade data for corrugator roll imports. Bottom-up equipment unit economics were triangulated against top-down capital expenditure surveys across the analysis window.
Segment-weighting approaches applied differential growth assumptions across technology tiers, with digital control architectures receiving accelerated penetration rates relative to legacy PLC installed base decay curves. Product type segmentation modeled folder-gluer, rotary die cutter, and corrugator line categories separately, while application segmentation distinguished inline integrated systems from standalone auxiliary equipment. End-user weighting incorporated warehouse operator outcome-based contract adoption trajectories versus traditional box manufacturer procurement patterns. CAGR derivation incorporated named regulatory deadline effects and e-commerce fulfillment velocity mandates as demand shapers.
Caveats apply where EU F-Gas Regulation enforcement intensity or India BIS certification timeline volatility could materially shift the outlook for equipment deployment schedules. Practitioners should monitor OCC price volatility in North American spot markets and precision roll foundry capacity utilization rates for early signals of margin compression or supply constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Global Dispensing Systems Market
Packaging Equipment
Blow Molding Tools Market