
 Refrigerated Display Cases Market | 2026-2036
Refrigerated Display Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Display Cases Market Analysis
Variable-speed compressor technology paired with IoT-enabled temperature monitoring is reconfiguring how refrigerated display cases are engineered and serviced. Hussmann Corporation leverages its North American manufacturing footprint to sustain leadership in vertical cases for supermarket chains. Daikin Industries Ltd. anchors its position through backward integration into compressor technology, while Epta S.p.A. Refrigeration competes on natural refrigerant expertise across European retail networks.
Refrigerated display cases are insulated enclosures with forced-air or static cooling systems designed to maintain precise temperature bands for perishable merchandise visibility and preservation. Units typically employ polyurethane foam insulation, double-glazed low-emissivity glass, and electronic expansion valves to optimize energy draw across ambient retail conditions. Vertical and multi-deck configurations dominate volume due to their floor-space efficiency in high-traffic retail formats, while plug-in cases command margin pools in retrofit and small-format deployments where remote rack systems prove uneconomical. Natural refrigerant technology segments are expanding fastest as regulatory pressure on synthetic hydrofluorocarbons intensifies across major economies.
The EPA Significant New Alternatives Policy program in the United States and the EU F-Gas Regulation collectively shape refrigerant selection, energy labeling requirements, and product certification pathways for manufacturers seeking multi-region market access. Health Canada and Japan's METI enforce parallel efficiency standards that constrain import eligibility and influence R&D allocation across the supplier base. Stakeholders must monitor the pace of national refrigerant phase-down schedules to calibrate production lines and inventory commitments ahead of compliance deadlines.
Market Dynamics
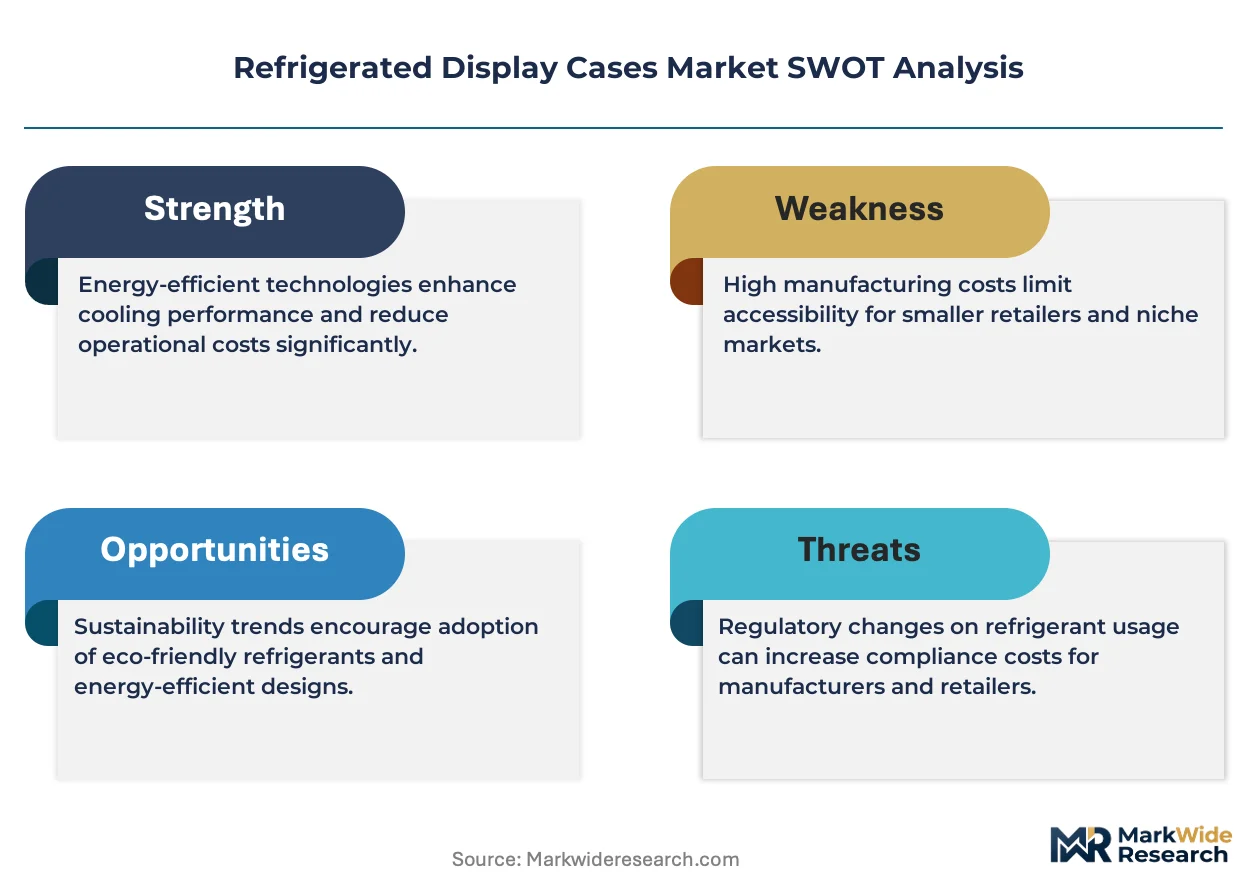
Natural refrigerant mandates are compressing product development cycles as manufacturers retool assembly lines ahead of synthetic hydrofluorocarbon phase-down deadlines. The EU F-Gas Regulation and parallel EPA frameworks are forcing simultaneous compliance across multiple certification pathways.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:Retail chains across Germany, France, and Italy are accelerating case replacement programs to avoid refrigerant quota penalties. This regulatory pressure converts planned maintenance into immediate procurement.
- Convenience store cold-chain expansion:Urban retail formats in Vietnam and Indonesia are deploying plug-in vertical cases to serve dense residential catchments. Secondary city penetration drives volume demand for standardized, rapid-install units.
- Variable-speed compressor technology:Energy consumption reductions of 15-25% versus fixed-speed equivalents are compelling supermarket operators to specify inverter-driven systems in new-build and retrofit programs.
Market Restraints
- Copper and aluminum input volatility:Refrigeration coil and frame manufacturers face margin compression when base metal prices spike, compressing project bid competitiveness.
- Compressor supply concentration:Production of high-efficiency variable-speed units clusters among Japanese and German component specialists, creating allocation risk during demand surges.
- Natural refrigerant charge limits:ISO safety standards constrain ammonia and hydrocarbon quantities in retail-accessible cases, restricting application in compact formats.
Strategic Opportunities
- IoT-enabled predictive maintenance:Sensor-embedded cases allowing remote temperature monitoring and compressor diagnostics are opening recurring revenue streams for OEM service divisions.
- Secondary city modern retail in Indonesia:Provincial capital expansion by domestic and regional grocery chains creates demand for standardized, cost-optimized plug-in cases.
- Heat recovery integration:Capturing condenser waste heat for store space heating or hot water is hybridizing case function with building energy systems in Nordic markets.
Industry Challenges
- Natural refrigerant technician certification:The specialized handling requirements for flammable hydrocarbons and toxic ammonia are constraining qualified installation and service capacity.
- Legacy remote rack integration:Retrofitting distributed case controls into existing centralized refrigeration infrastructure demands custom engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Display Cases Market |
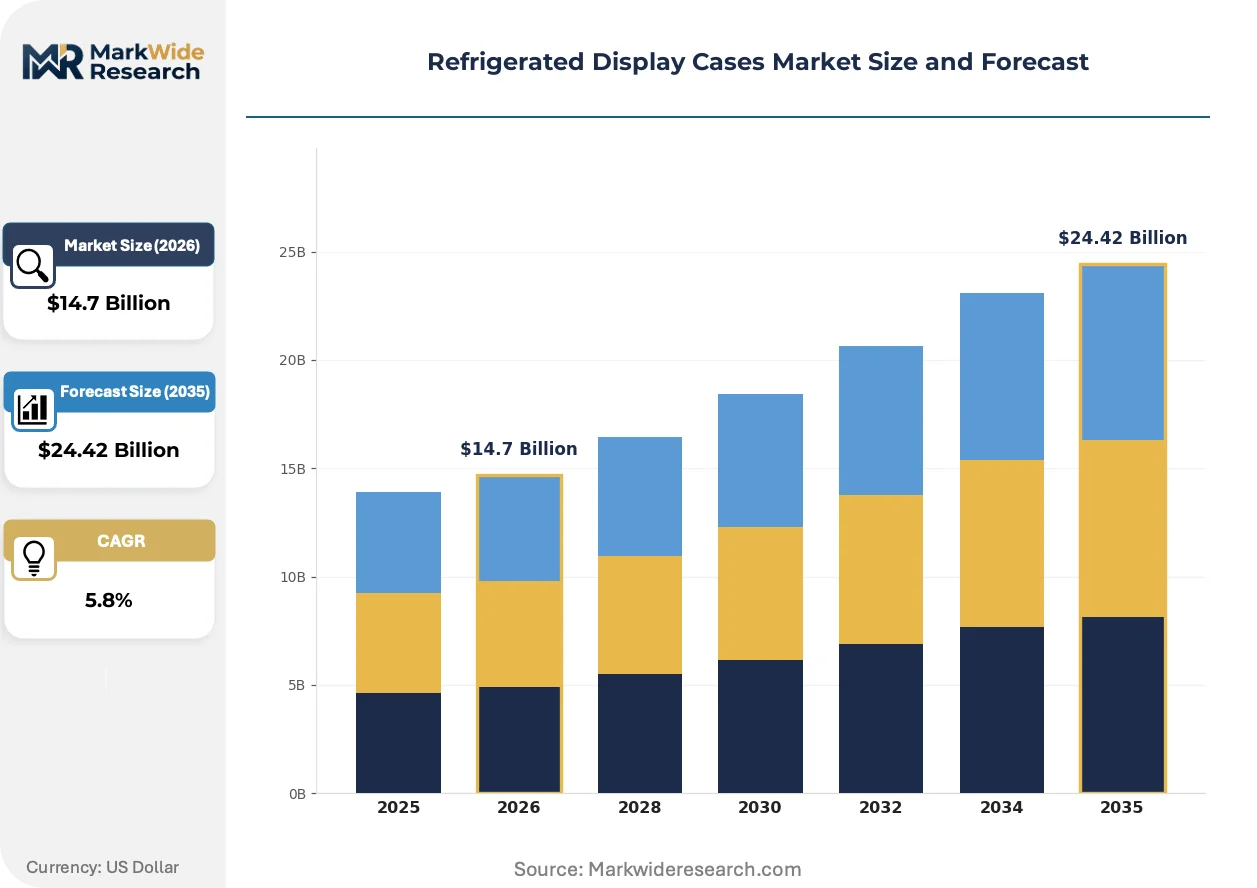
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Plug-in, Multi-deck End User: Supermarkets, Convenience Stores, Restaurants, Cafés Technology: Hydrochlorofluorocarbon, Natural Refrigerants, Ventilated, Static Size: Small, Medium, Large, Custom-built |
| Companies Covered | Hussmann Corporation, Daikin Industries Ltd., Epta S.p.A. Refrigeration, Carrier Corporation, AHT Cooling Systems GmbH, Arneg S.p.A, Hillphoenix Inc., Metalfrio Solutions S.A., Hoshizaki International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Display Cases Market Emerging Trajectories
Refrigerated display case engineering is converging around three vectors: refrigerant chemistry transformation, embedded intelligence deployment, and format flexibility for evolving retail footprints.
CO2 transcritical booster systems are hybridizing with traditional HFC architectures as supermarket operators pilot cascade configurations to manage ambient temperature performance. German and Scandinavian retail chains are specifying these systems in new hypermarket builds, compressing the payback period for full-fleet conversion through energy tariff optimization and heat recovery monetization.
The EPA Significant New Alternatives Policy program is accelerating refrigerant portfolio consolidation among case manufacturers serving North American markets. Acceptable alternatives lists are narrowing faster than product certification cycles, forcing engineering teams to parallel-track multiple refrigerant paths. Remote rack system suppliers face the steepest compliance burden, while plug-in case producers gain flexibility through smaller charge quantities.
Small-format retailers are unbundling case procurement from installation and maintenance contracts, shifting toward equipment-as-a-service models. Convenience store operators in Southeast Asian markets prefer operational expenditure structures that transfer compressor failure risk to OEM service networks. This preference compression is visible in Vietnam, where domestic retail chains now specify multi-year service inclusion in tender specifications.
Refrigerated Display Cases Market Segmentation
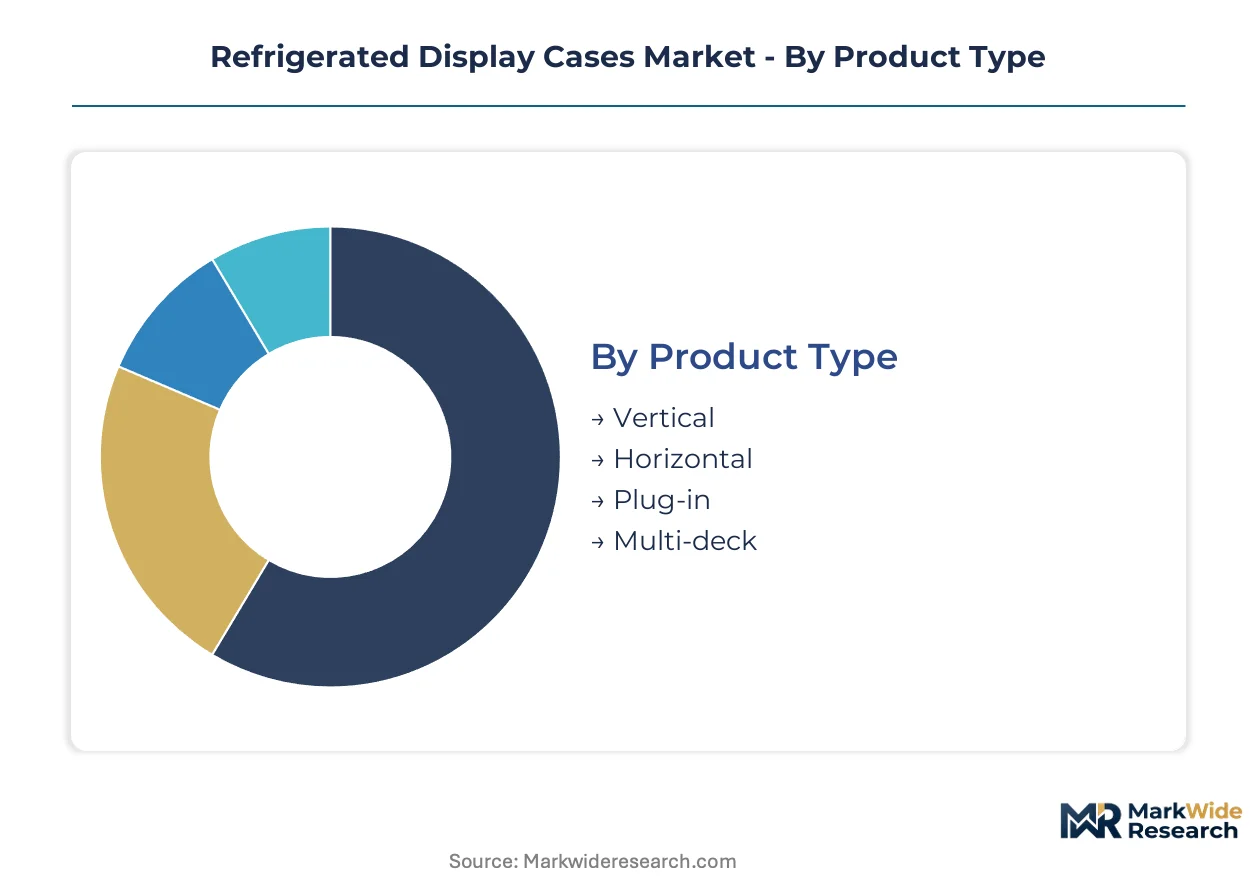
Segmentation in refrigerated display cases determines equipment specification pathways, service contract structures, and refrigerant compliance obligations across retail formats. Procurement cycles vary dramatically by product type and end-use channel, creating distinct margin pools for manufacturers.
Product Type:
Replacement cycles range from 7-10 years for remote rack-connected vertical cases to 3-5 years for plug-in units in high-turnover convenience formats.
- Vertical:Tall, glass-fronted enclosures with forced-air circulation dominate supermarket perimeter installations. German and French retail chains specify these for dairy and beverage merchandising under EU F-Gas Regulation compliance timelines.
- Plug-in:Self-contained refrigeration systems eliminate remote piping infrastructure. Convenience store operators in Vietnam and Indonesia favor rapid-install plug-in vertical cases for secondary city expansion where contractor capacity is limited.
- Horizontal:Chest-style configurations with sliding or lift-up glass lids serve frozen merchandise categories. Ice cream and frozen food specialists in Japan specify these for high-density urban locations.
- Multi-deck:Open-front gravity coil designs maximize product facings per linear meter. Italian supermarket operators deploy these for fresh produce visibility in hypermarket formats.
Vertical cases dominate installed base. Plug-in configurations are where expansion concentrates.
End User:
Channel concentration shapes pricing power and service bundling requirements across the customer base.
- Supermarkets:Large-format operators negotiate fleet-wide refrigerant conversion programs with OEM service commitments. Remote rack systems with centralized controls characterize hypermarket deployments in Germany and France.
- Convenience Stores:Small-footprint retailers prioritize rapid installation and operational expenditure structures. Indonesian domestic chains specify standardized plug-in cases with multi-year service inclusion for provincial capital rollouts.
- Restaurants:Foodservice operators demand under-counter and pass-through configurations for kitchen workflow integration. Health Canada efficiency standards constrain import eligibility for equipment serving Canadian foodservice chains.
- Cafés:Beverage-focused formats drive demand for compact refrigerated merchandisers with glass door visibility. METI efficiency standards in Japan influence specification for premium coffee retail chains.
Supermarkets anchor volume procurement. Convenience stores are climbing the fastest.
Technology:
Regulatory phase-down schedules are compressing technology transition timelines across the supplier base.
- Natural Refrigerants:CO2 transcritical and hydrocarbon systems eliminate synthetic hydrofluorocarbon compliance exposure. Scandinavian retail chains specify these in new hypermarket builds with heat recovery integration.
- Hydrochlorofluorocarbon:Legacy synthetic refrigerants face quota restrictions under EPA Significant New Alternatives Policy frameworks. North American operators accelerate replacement programs ahead of scheduled phase-down milestones.
- Ventilated:Forced-air circulation systems maintain uniform temperature bands across product loadings. High-traffic retail formats in Southeast Asia specify these for tropical ambient conditions.
- Static:Gravity coil cooling reduces air movement and moisture loss for sensitive merchandise. Specialty cheese and charcuterie retailers in France favor these for premium product preservation.
Hydrochlorofluorocarbon retains legacy installed base. Natural refrigerants are gaining share fastest.
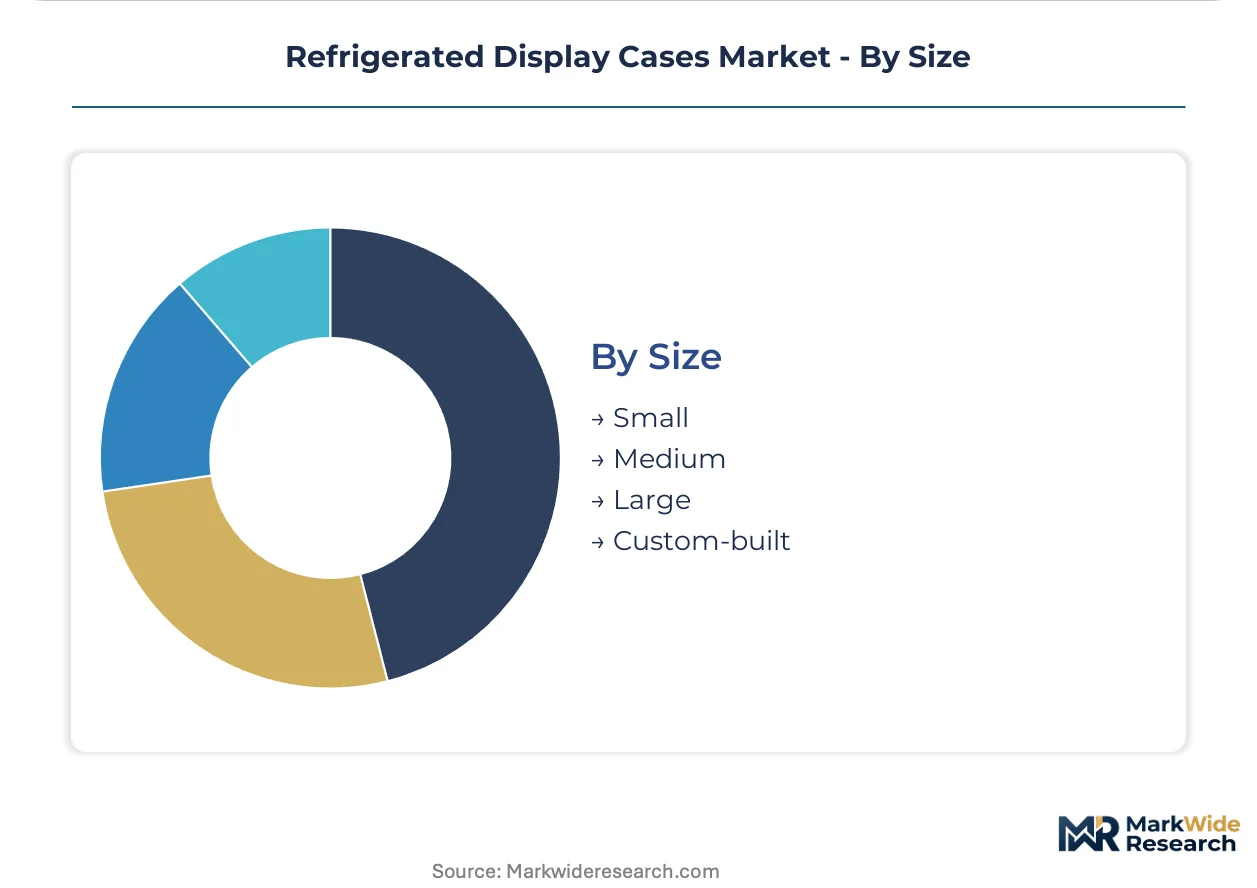
Size:
Format flexibility requirements scale with retail footprint constraints and merchandise category breadth.
- Medium:Standard-width cases balance product capacity with aisle clearance requirements. Supermarket operators in Italy specify these for mainstream dairy and beverage categories.
- Small:Compact under-counter and countertop units serve space-constrained formats. Café operators in Japan deploy these for grab-and-go beverage merchandising.
- Large:Extended-length multi-deck configurations maximize linear merchandising footage. Hypermarket operators in Germany install these for fresh produce and bakery display.
- Custom-built:Bespoke dimensions accommodate architectural constraints or specialty merchandise requirements. High-end food halls in France commission these for curated retail experiences.
Medium cases anchor standardized procurement. Small formats are where application diversity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export transcritical CO2 systems to Scandinavian retail chains, while Chinese component suppliers feed Southeast Asian convenience store rollouts. Trade corridors align refrigerant technology maturity with regional regulatory timelines.
Germany
Hypermarket operators in Bavaria and North Rhine-Westphalia are specifying natural refrigerant cases ahead of EU F-Gas Regulation quota reductions. The country's national environmental regulator enforces accelerated phase-down schedules for synthetic hydrofluorocarbons. Manufacturing clusters around Stuttgart and Frankfurt supply transcritical booster systems to domestic and export markets.
United States
Supermarket chains in California and Texas are retrofitting remote rack installations under EPA Significant New Alternatives Policy frameworks. The EPA maintains acceptable alternatives lists that constrain refrigerant selection for new case procurement. Equipment fabricators in the Midwest serve national retail networks with variable-speed compressor configurations.
Vietnam
Convenience store operators in Ho Chi Minh City and Hanoi are deploying plug-in vertical cases for dense urban catchments. The country's national standards body implements energy labeling requirements adapted from ASEAN harmonized frameworks. Domestic retail chains in provincial capitals specify rapid-install units with multi-year service bundling.
Japan
Premium food retail formats in Tokyo and Osaka are specifying static cooling cases for specialty merchandise preservation. METI enforces efficiency standards that constrain import eligibility and shape domestic manufacturer R&D allocation. Equipment specialists in the Chubu region supply compact under-counter configurations for café and foodservice deployment.
Indonesia
Domestic grocery chains in Jakarta and Surabaya are expanding cold-chain footprints into secondary cities with standardized plug-in cases. The country's national trade ministry oversees import certification for refrigeration equipment serving modern retail formats. Provincial capital rollouts in Central and East Java drive volume demand for cost-optimized vertical configurations.
Refrigerated Display Cases Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement structures. The supplier base clusters around three strategic archetypes: full-system integrators with captive compressor technology, natural refrigerant specialists with European regulatory expertise, and volume fabricators serving emerging market convenience formats. Competitive moves concentrate on backward integration into compressor manufacturing and geographic expansion through distributor network consolidation.
Within the full-system integrator tier, Hussmann Corporation and Daikin Industries Ltd. occupy positions defined by upstream control over critical components. Epta S.p.A. Refrigeration exemplifies the natural refrigerant specialist archetype, with its corporate structure reflecting European market orientation. Among volume-oriented fabricators, Carrier Corporation and AHT Cooling Systems GmbH represent scale-driven positioning for standardized case deployment across diverse retail channels.
| Leading Market Players |
|---|
| Hussmann Corporation |
| Daikin Industries Ltd. |
| Epta S.p.A. Refrigeration |
| Carrier Corporation |
| AHT Cooling Systems GmbH |
| Arneg S.p.A |
| Hillphoenix Inc. |
| Metalfrio Solutions S.A. |
| Hoshizaki International |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit copper and aluminum price volatility directly into coil manufacturing costs, compressing margins for mid-tier fabricators while allowing compressor-integrated OEMs to sustain premium positioning through captive component supply.
Pricing Analysis
Fixed-speed compressor cases, variable-speed inverter systems, and emerging CO2 transcritical configurations occupy distinct price bands. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from Indonesian and Vietnamese convenience store operators demanding operational expenditure models with multi-year service inclusion. Small-format retailers exhibit highest price sensitivity; Scandinavian hypermarket chains demonstrate lowest sensitivity due to heat recovery monetization and energy tariff optimization.
Supply Chain Analysis
Supplier-financing facilities from Japanese and German compressor specialists extend payment terms to 90-120 days for qualified OEMs, compressing working capital cycles for volume fabricators. Manufacturing concentration clusters in China, Germany, and Japan. Production draws from copper refrigeration tubing, aluminum fin stock, and polyurethane foam insulation. Single-source vulnerability in high-efficiency variable-speed compressor allocation creates allocation risk during demand surges. Distribution runs through regional equipment distributors serving supermarket chains and direct OEM relationships with convenience store operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerated display cases are shifting from capital equipment sales toward service-attach revenue models, with IoT-enabled predictive maintenance and multi-year compressor coverage expanding faster than hardware unit growth.
For Market Incumbents: Insulate fleet-wide refrigerant conversion programs from quota penalty exposure by accelerating EU F-Gas Regulation compliance timelines ahead of mandated deadlines. Deepen backward integration into compressor manufacturing to secure allocation priority during demand surges. Channel control through exclusive service networks for natural refrigerant cases defends margin position against emerging volume fabricators.
For New Entrants and Emerging Players: Establish a beachhead in Indonesian provincial capital convenience store rollouts where standardized plug-in case demand outpaces qualified contractor capacity. Target secondary city modern retail expansion with rapid-install vertical configurations and embedded multi-year service bundling. Partner with domestic distributors possessing existing relationships with regional grocery chains to bypass direct OEM sales infrastructure requirements.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down milestones reshape the acquisition landscape toward natural refrigerant specialists with transcritical CO2 deployment expertise. Long-term viability centers on service revenue attachment rates exceeding hardware depreciation cycles. Monitor refrigerant quota auction prices as the inflection indicator for accelerated case replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of variable-speed units secures allocation priority during demand surges for OEMs. |
| IoT Platform Integration | Sensor-embedded cases enable predictive maintenance revenue streams across supermarket fleet deployments. |
| Natural Refrigerant Certification Program | EU F-Gas Regulation compliance positions specialists for accelerated replacement cycles in German and French retail. |
| Geographic Expansion via Distributor Consolidation | Network control in Vietnam and Indonesia captures convenience store rollout demand ahead of competitor entry. |
| Heat Recovery Technology Licensing | Condenser waste heat capture monetizes energy tariffs for Nordic hypermarket operators. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with supermarket procurement directors, convenience store operations managers, compressor manufacturing engineers, and refrigeration contractor service heads; and secondary validation against EPA Significant New Alternatives Policy filings, EU F-Gas Regulation quota auction records, METI efficiency standard disclosures, and ASEAN harmonized energy labeling frameworks. Bottom-up unit shipment modeling and top-down refrigeration equipment spend analysis were triangulated against trade corridor import data.
Forecast inputs included product type segmentation by remote rack versus plug-in configuration, technology segmentation by natural refrigerant versus synthetic hydrofluorocarbon systems, end-user channel segmentation by supermarket versus convenience store versus foodservice, and regional regulatory cluster differentiation. CAGRs were derived from regression analysis across historical replacement cycle data and projected phase-down compliance deadlines. Compressor supply concentration indices and copper price volatility bands were incorporated as sensitivity variables.
Stress conditions across refrigerant quota auction prices, base metal input volatility, and technician certification capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory phase-down adherence and replacement cycle acceleration. Macroeconomic contraction, refrigerant technology breakthroughs, or trade policy disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Laser Coding Equipment Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Automatic Liquid Filling Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Rotary Tray Sealers Market