
 Automatic Liquid Filling Market | 2026-2036
Automatic Liquid Filling Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Liquid Filling Market Outlook
The EU Green Deal and F-Gas Regulation is pivoting beverage bottlers toward electric and vacuum-based filling technologies that eliminate compressed air dependency. Krones AG leverages its Swabian manufacturing footprint to dominate high-speed rotary filler exports. Syntegon Technology GmbH sustains pharmaceutical-grade aseptic filling leadership through isolator-integrated systems. Tetra Pak International S.A. competes in carton-aseptic formats with in-house production of filling valves and sterilization modules.
Automatic liquid filling equipment dispenses measured volumes of free-flowing or viscous liquids into containers at speeds from 50 to 120,000 units per hour, using gravity, pressure, vacuum, or piston mechanisms with fill accuracy typically within plus or minus 0.5 percent. Inline fillers serve craft beverage and regional dairy operations where batch flexibility outweighs maximum throughput. Continuous rotary systems capture margin pools in carbonated soft drink and bottled water plants where uptime economics favor dedicated high-speed lines. Pneumatic technology retains installed base dominance in emerging market chemical packaging, though electric actuation gains share in pharmaceutical cleanrooms demanding particle-free operation.
FDA 21 CFR Part 11 and EU MDR shape validation documentation and electronic record requirements for pharmaceutical filling installations, while EPA effluent guidelines constrain CIP chemical discharge in US food plants. ISO 9001 and 3-A Sanitary Standards govern equipment qualification protocols across dairy and beverage applications. Stakeholders must weigh total cost of ownership against regulatory compliance burden when selecting between European precision engineering and Asian cost-optimized alternatives.
Market Dynamics
Electric servo actuation is consolidating control architectures across pharmaceutical and beverage filling lines, compressing pneumatic system margins while forcing requalification of legacy installations against FDA 21 CFR Part 11 and EU MDR traceability mandates.
Growth Catalysts
- EU F-Gas Regulation phase-down:Beverage bottlers in Germany and Italy are retrofitting compressed-air-dependent rotary fillers with vacuum-based electric systems to eliminate fluorinated gas leakage risks and avoid carbon border adjustments.
- ASEAN pharmaceutical manufacturing expansion:Contract development and manufacturing organizations in Singapore and Thailand are installing isolator-integrated aseptic filling lines to supply biologics for export to FDA and EMA jurisdictions.
- High-viscosity product diversification:Personal care and nutraceutical brands are specifying piston-driven fillers with heated product paths to handle CBD tinctures, collagen shots, and plant-based creamers that defeat standard gravity mechanisms.
Market Restraints
- Precision component supply concentration:German and Swiss linear actuator and servo motor suppliers command 60-90 day lead times, constraining capacity expansion for rotary filler OEMs outside the EU supply radius.
- Stainless steel alloy volatility:Grade 316L and 304 price swings directly impact CIP-skid and filler frame manufacturing economics, compressing margins on mid-speed equipment contracts with fixed pricing clauses.
- Cleanroom infrastructure bottleneck:Pharmaceutical-grade isolator and restricted access barrier system installation requires specialized HVAC and monitoring contractors, extending project timelines beyond equipment delivery schedules.
Strategic Opportunities
- India PLI scheme for medical devices:Domestic filler assembly operations can capture 5-20% incentive-linked benefits by localizing production for syringe and vial filling systems serving the country's expanding vaccine and insulin manufacturing base.
- Bag-in-box and pouch format migration:Wine, edible oil, and industrial chemical producers are shifting from rigid containers to flexible formats, creating demand for web-fed aseptic filling systems with integrated spout insertion and induction sealing.
- Digital twin and predictive maintenance convergence:Equipment OEMs bundling virtual commissioning tools with subscription-based remote monitoring can shift revenue from capital sales to recurring service streams, particularly in North American craft beverage segments.
Industry Challenges
- Mechatronics technician scarcity:The intersection of PLC programming, servo tuning, and hygienic mechanical design requires hybrid skill sets that vocational training systems in most manufacturing economies have not yet scaled to produce.
- Legacy system integration friction:Brownfield pharmaceutical plants running 1990s-era SCADA architectures face multi-year validation timelines when retrofitting isolator-integrated fillers, delaying ROI realization and freezing capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Liquid Filling Market |
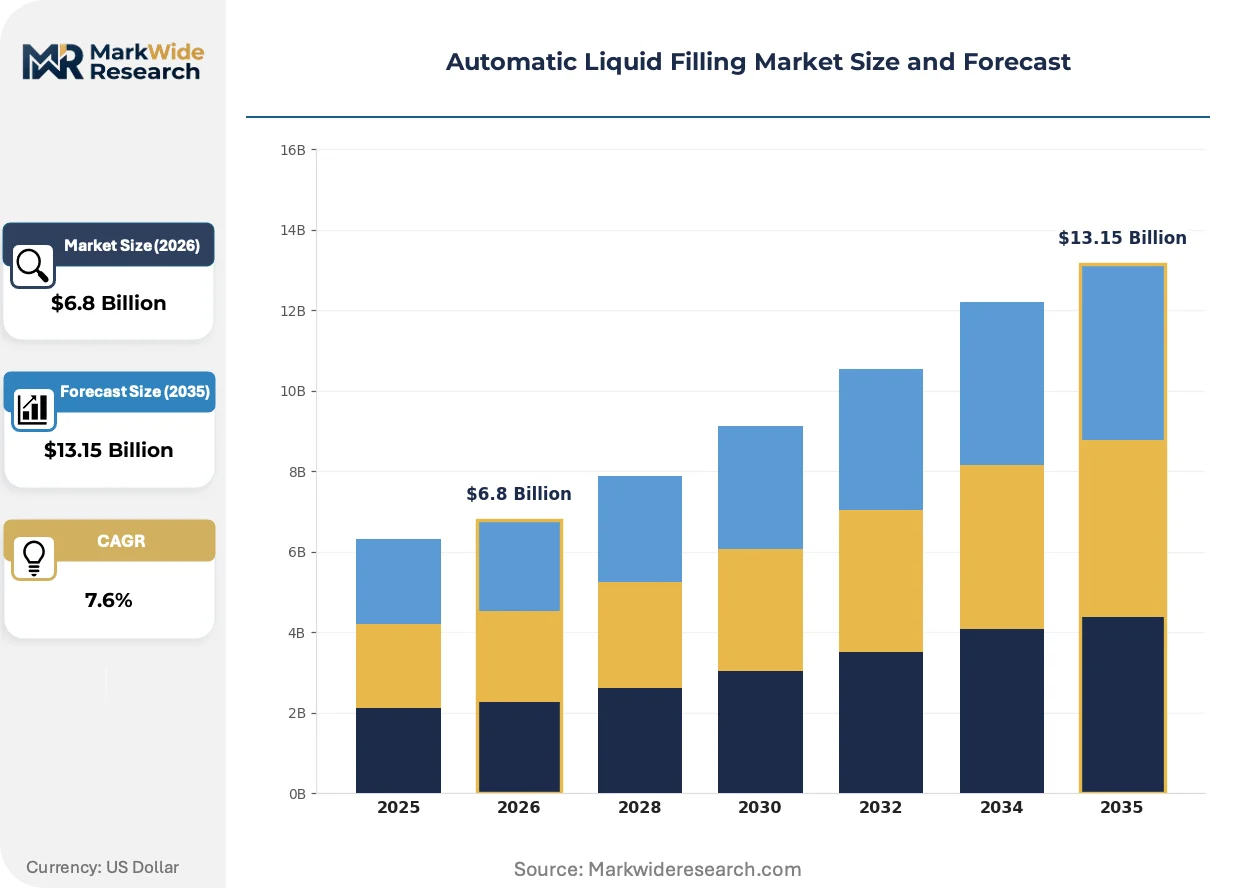
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Alone Filler, Inline Filler, Continuous Filler, Semi-Automatic Filler End User: Food and Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Pneumatic, Mechanical, Electric, Vacuum Container Type: Bottles, Pouches, Cans, Jars |
| Companies Covered | Krones AG, Tetra Pak International S.A., Syntegon Technology GmbH, ProMach Inc., GEA Group AG, KHS GmbH, Bosch Packaging Technology, Coesia S.p.A., JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Liquid Filling Market Strategic Shifts
Machine learning-based vision inspection and single-use fluid path technologies are compressing changeover times and contamination risk profiles across aseptic filling operations, while regulatory digitization mandates force reconciliation of paper-based legacy protocols with electronic batch records.
Servo-electric filling valves with integrated load cells and real-time feedback loops are consolidating position control architectures that previously required separate pneumatic cylinders, mechanical cams, and external checkweigh stations. Pharmaceutical cleanroom operators in Switzerland and Germany are specifying these systems to eliminate compressed air particle generation and reduce maintenance intervals. The technology is consolidating supplier tiers by collapsing motion control, weighing, and reject handling into single-source mechatronic modules that displace multi-vendor integration complexity.
FDA 21 CFR Part 11 and EU Annex 11 electronic record integrity requirements are mandating audit trails, electronic signatures, and data integrity controls that legacy PLC-based filling lines cannot satisfy without complete control system replacement. Pharmaceutical manufacturers in Ireland and Denmark are prioritizing equipment with pre-validated software packages to compress qualification timelines. The policy shift is accelerating obsolescence of mechanically actuated fillers without Ethernet-connected controllers, particularly in sterile injectables production where regulatory inspection intensity has intensified.
Contract packaging organizations are unbundling equipment ownership from operational responsibility, preferring throughput-based service agreements where OEMs retain asset ownership and guarantee line efficiency metrics. This model is displacing traditional capital purchase and in-house maintenance structures in North American craft spirits and regional dairy segments. The shift is most visible in California and New York state, where beverage startups lack balance sheet capacity for seven-figure rotary filler investments but require pharmaceutical-grade changeover flexibility for seasonal SKU proliferation.
Automatic Liquid Filling Market Segmentation
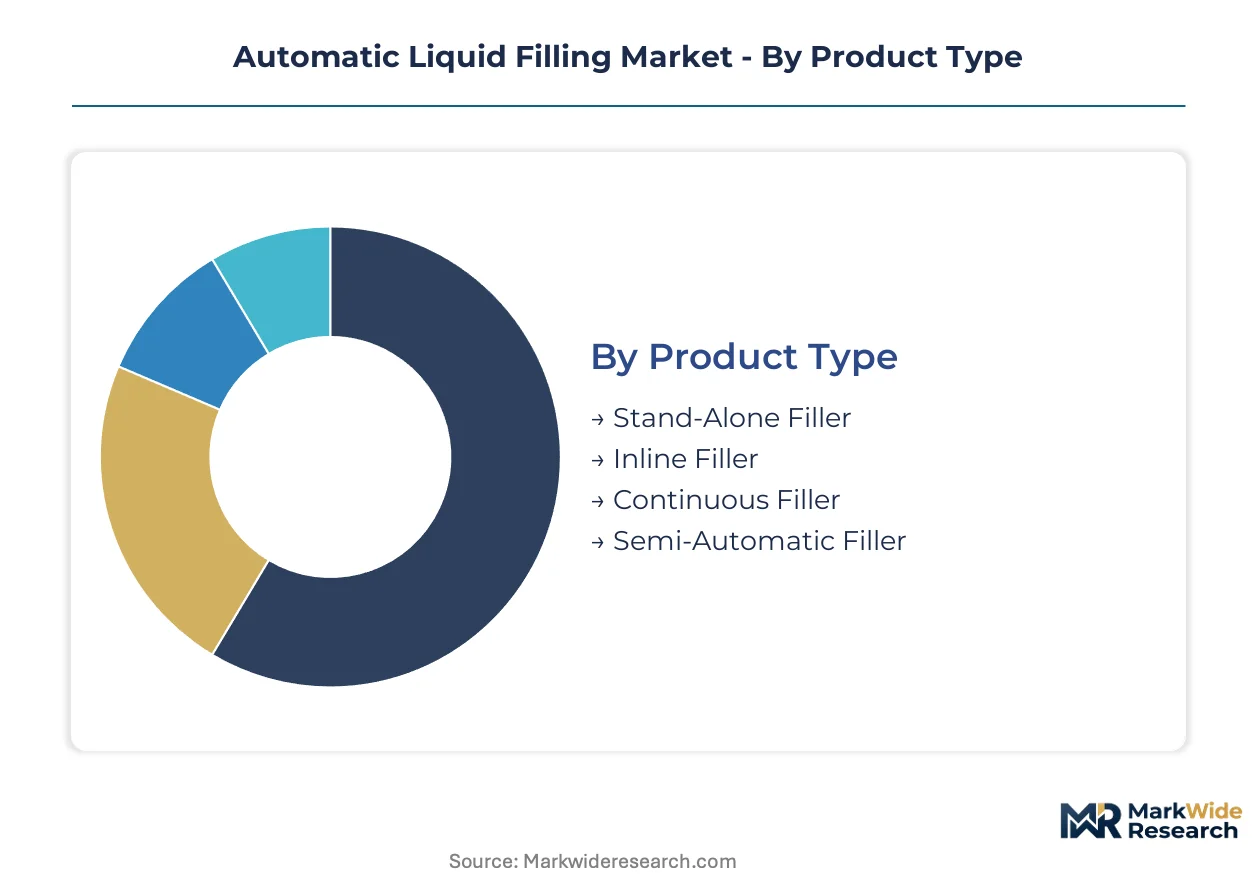
Segmentation in automatic liquid filling reveals how equipment specifications diverge across regulatory environments, viscosity ranges, and cleanroom requirements. Manufacturers configure product portfolios around these axes to defend margin pools in pharmaceutical aseptic systems versus commodity beverage lines.
Product Type:
Integration depth separates standalone units deployed in contract packaging operations from embedded systems integrated into turnkey bottling lines.
- Stand-Alone Filler:Self-contained units with independent control cabinets and HMI interfaces serve regional dairies and craft distilleries requiring batch flexibility. Demand concentrates in California and New York state beverage startups lacking capital for full line integration.
- Inline Filler:Modular stations arranged in linear configurations accommodate frequent changeovers between SKUs. German craft brewers specify these systems for seasonal wheat beer rotations where throughput requirements stay below 15,000 bottles per hour.
- Continuous Filler:Rotary systems with 60-120 valve configurations dominate carbonated soft drink and bottled water plants. These units embed directly into high-speed lines where uptime economics justify dedicated infrastructure.
- Semi-Automatic Filler:Operator-assisted systems bridge manual and fully automatic operation for pilot-scale pharmaceutical batches. CDMOs in Singapore deploy these for clinical trial material production prior to commercial scale-up.
Continuous fillers lead volumes today; semi-automatic systems are gaining share fastest in emerging biologics manufacturing.
End User:
Regulatory stringency and contamination risk tolerance create distinct equipment specifications across customer verticals.
- Food and Beverage:Gravity and pressure fillers with 3-A Sanitary Standards compliance handle milk, juices, and carbonated drinks. German bottlers retrofit vacuum-based electric systems to meet EU F-Gas Regulation phase-down mandates.
- Pharmaceuticals:Isolator-integrated aseptic fillers with restricted access barrier systems serve sterile injectables and biologics. FDA 21 CFR Part 11 and EU MDR traceability requirements force electronic batch record integration.
- Cosmetics:Piston-driven fillers with heated product paths manage high-viscosity creams and serums. Personal care brands in France specify these for CBD tinctures and collagen shots.
- Chemicals:Corrosion-resistant pneumatic systems with explosion-proof ratings package solvents and agricultural formulations. Emerging market producers retain this technology despite electric actuation gains elsewhere.
Food and beverage dominates installed base; pharmaceuticals exhibits the steepest expansion trajectory.
Technology:
Actuation mechanisms differentiate particle generation profiles, maintenance intervals, and energy consumption footprints.
- Pneumatic:Compressed air-driven cylinders and valves retain cost advantages in chemical packaging and legacy beverage installations. EPA effluent guidelines and EU F-Gas Regulation are compressing this technology's addressable market.
- Mechanical:Cam-driven and linkage-based systems offer simplicity for low-speed gravity filling. These units persist in regional dairy operations where electronic complexity introduces unwarranted failure modes.
- Electric:Servo motors with integrated load cells and real-time feedback loops eliminate compressed air particle generation. Swiss and German pharmaceutical cleanrooms specify these for isolator-integrated lines.
- Vacuum:Negative pressure filling mechanisms handle foam-prone products and enable precise level control. Beverage bottlers in Italy adopt these systems to eliminate fluorinated gas leakage risks.
Pneumatic systems retain legacy dominance; electric actuation is climbing the fastest in sterile manufacturing environments.
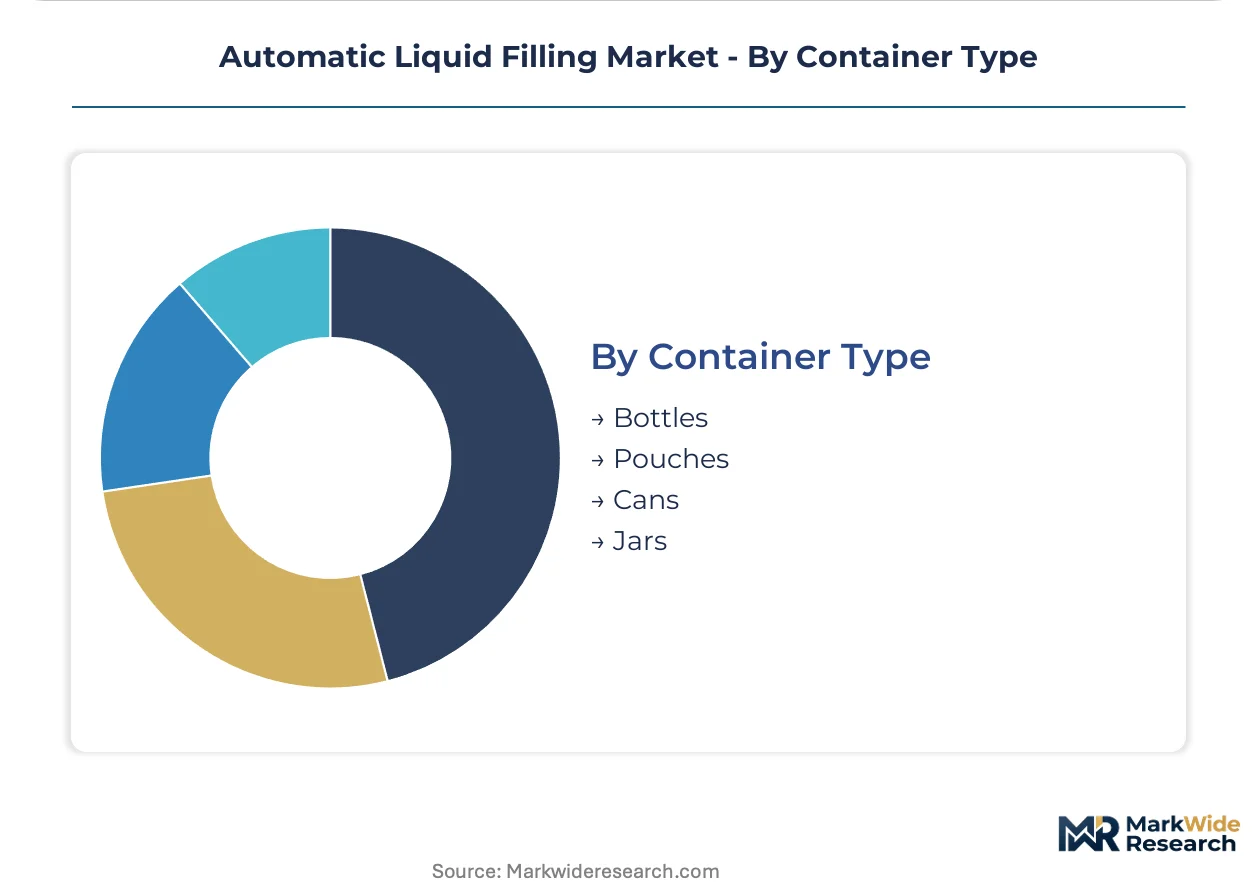
Container Type:
Format rigidity versus flexibility determines sealing technology, sterilization method, and downstream packaging integration.
- Bottles:Rigid PET, glass, and HDPE containers with threaded or crimp closures dominate beverage and pharmaceutical volumes. Rotary fillers with neck-handling starwheels achieve 120,000 units per hour in German mineral water plants.
- Pouches:Flexible film formats with spout insertion and induction sealing gain share in wine, edible oil, and industrial chemicals. Web-fed aseptic systems integrate forming, filling, and sealing in single operations.
- Cans:Aluminum two-piece and three-piece containers require counter-pressure fillers for carbonated products. Craft brewers in Denmark specify these for export-ready canned beer portfolios.
- Jars:Wide-mouth glass and plastic containers accommodate viscous foods, cosmetics, and nutraceuticals. Piston fillers with heated nozzles prevent product solidification during dispensing.
Bottles command current volume leadership; pouches are expanding most quickly in sustainable packaging transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered high-speed rotary filler engineering during the post-war beverage industrialization, establishing precision manufacturing clusters that now supply pharmaceutical and food packaging lines worldwide. This historical foundation shapes current demand patterns across major equipment-consuming economies.
Germany
Swabian engineering clusters around Stuttgart and Ulm anchor precision servo actuator production for pharmaceutical isolator systems. The EU F-Gas Regulation accelerates retrofit demand among Bavarian mineral water bottlers replacing pneumatic rotary fillers with vacuum-based electric alternatives. Krones AG maintains export dominance from its Neutraubling headquarters.
United States
Craft spirits proliferation in California and New York drives demand for semi-automatic and inline fillers with rapid changeover capability. FDA 21 CFR Part 11 compliance requirements constrain brownfield pharmaceutical plants in New Jersey and North Carolina to extended validation timelines. Contract packaging organizations in Illinois are piloting throughput-based service agreements.
India
Domestic vaccine and insulin manufacturing expansion concentrates demand in Maharashtra and Gujarat for syringe and vial filling systems. The PLI scheme for medical devices offers 5-20% incentive-linked benefits for localized filler assembly operations. CDSCO regulatory alignment with FDA standards enables export-oriented production from Pune and Ahmedabad clusters.
China
Beverage bottling capacity expansion in Guangdong and Zhejiang provinces sustains demand for high-speed continuous rotary systems. NMPA pharmaceutical manufacturing standards are tightening aseptic filling requirements for biologics production in Shanghai and Suzhou. Domestic OEMs are capturing mid-speed equipment segments from European suppliers.
Switzerland
Pharmaceutical cleanroom operations in Basel and Zurich specify electric servo filling valves with integrated load cells for sterile injectables production. Swissmedic regulatory intensity drives pre-validated software package requirements that compress equipment qualification timelines. Precision component suppliers in the Swiss-German border region command extended lead times for linear actuator deliveries.
Automatic Liquid Filling Market Competitive Environment
Premium-margin players sit above commodity-margin players across precision engineering depth and regulatory compliance capability. The vendor base organizes into three tiers: Swiss-German precision specialists commanding pharmaceutical cleanroom specifications, diversified European engineering conglomerates spanning beverage and pharma segments, and Asian cost-optimized fabricators capturing emerging market chemical packaging. Consolidation pressure is intensifying through strategic partnerships between component suppliers and system integrators, alongside geographic expansion into ASEAN pharmaceutical manufacturing corridors.
Among German-based precision engineering groups, Krones AG and Syntegon Technology GmbH exemplify the pharmaceutical-beverage dual-track archetype, while Tetra Pak International S.A. occupies a distinct position in carton-aseptic format integration. Krones leverages its Swabian manufacturing footprint for high-speed rotary filler exports. Syntegon sustains leadership in isolator-integrated aseptic systems through precision servo technology. Tetra Pak competes through captive production of filling valves and sterilization modules for liquid food cartons.
| Leading Market Players |
|---|
| Krones AG |
| Tetra Pak International S.A. |
| Syntegon Technology GmbH |
| ProMach Inc. |
| GEA Group AG |
| KHS GmbH |
| Bosch Packaging Technology |
| Coesia S.p.A. |
| JBT Corporation |
| Others |
Value Chain & Pricing Dynamics
Grade 316L stainless steel alloy volatility propagates through filler frame and CIP-skid manufacturing economics, compressing margins on mid-speed equipment contracts with fixed pricing clauses while forcing OEMs to stratify offerings across certification-grade tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolator-integrated pharmaceutical systems from beverage rotary fillers and emerging-market chemical packaging units. Price differentiation rests on FDA 21 CFR Part 11 validation status and servo-electric actuation precision. Cost compression in standard-tier beverage equipment is intensifying because domestic OEMs in China capture mid-speed segments. Craft distilleries in California exhibit highest price sensitivity; Swiss pharmaceutical cleanrooms show lowest.
Supply Chain Analysis
Refurbishment flows for legacy pneumatic rotary fillers create secondary parts markets in Germany and Italy, extending equipment lifecycles while dampening new-build demand. Geographic supply concentration centers on Germany, Switzerland, and China for servo motors, linear actuators, and stainless steel fabrication respectively. Raw material dependencies draw from Swedish specialty steel mills, Taiwanese precision electronics, and Chinese rare-earth magnet processors. Single-source vulnerability in German linear actuator supply creates bottlenecks. Distribution runs through OEM direct sales for pharmaceutical systems and regional distributor networks for beverage equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic liquid filling market functions as a regulatory compounder where EU F-Gas Regulation phase-down mandates and FDA electronic record requirements continuously upgrade installed bases.
For Market Incumbents: Deepen captive supply of servo actuator modules to offset 60-90 day lead time vulnerabilities from Swiss-German component suppliers. Expand validation-service bundling to capture brownfield pharmaceutical retrofit cycles. Electric drive substitution for pneumatic systems represents the primary threat vector; counter through pre-validated software packages that compress qualification timelines. For New Entrants and Emerging Players: Regional dairy cooperatives in India and ASEAN contract packaging organizations represent underserved buyer archetypes with unmet demand for flexible inline fillers. White-space concentration appears in bag-in-box aseptic systems for wine and edible oil producers shifting from rigid containers. Pursue throughput-based service agreement models rather than capital sales to penetrate balance-sheet-constrained craft beverage startups. For Investors and Strategic Acquirers: Consolidation pressure builds where precision component supply bottlenecks intersect with pharmaceutical-grade certification requirements. Long-term viability favors OEMs with in-house servo motor and isolator integration capabilities. Acquisition target archetype: mid-tier European filler manufacturers with established FDA master files but underutilized capacity. Monitor NMPA regulatory tightening in Chinese biologics manufacturing as inflection indicator for aseptic system demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Actuator Production | Reduces dependency on German-Swiss suppliers and compresses lead times for pharmaceutical OEMs. |
| Isolator-Integrated System Certification | Enables access to sterile injectables manufacturing in Basel and Zurich pharmaceutical clusters. |
| Throughput-Based Service Agreement Model | Aligns revenue with craft beverage startup cash flow constraints in California and New York. |
| Digital Twin Virtual Commissioning Platform | Shifts revenue to recurring service streams for North American contract packaging organizations. |
| India PLI Localization Partnership | Captures 5-20% incentive-linked benefits for syringe and vial filling system assembly. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with pharmaceutical manufacturing engineers, beverage plant managers, CDMO procurement leads, and aftermarket service directors combined with secondary validation from FDA 510(k) filings, EMA inspection reports, EU F-Gas Regulation implementation databases, and trade flow data from German mechanical engineering associations. Cross-referencing equipment shipment records against capacity expansion announcements enables triangulation.
Historical trendline analysis of rotary filler installations and aseptic line deployments establishes baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, actuation technology, and container format alongside regional regulatory cluster intensity. CAGRs derive from weighted average of bottom-up demand build and top-down macro constraint analysis. Forecast inputs incorporate stainless steel price indices and pharmaceutical cleanroom construction permits.
Underlying measurement precision varies by segment; pharmaceutical aseptic systems carry tighter precision than commodity beverage equipment due to regulatory filing transparency. Forecasts assume continued EU F-Gas Regulation enforcement and FDA data integrity mandate expansion. Practitioners should monitor CDSCO regulatory alignment progress and Chinese NMPA biologics manufacturing standard tightening for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Retail Press Dispenser Pump Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Basket Granulator Extruder Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Global Reverse Vending Machine Market