
 Contact Center Software Market | 2026-2036
Contact Center Software Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Center Software Market Intelligence
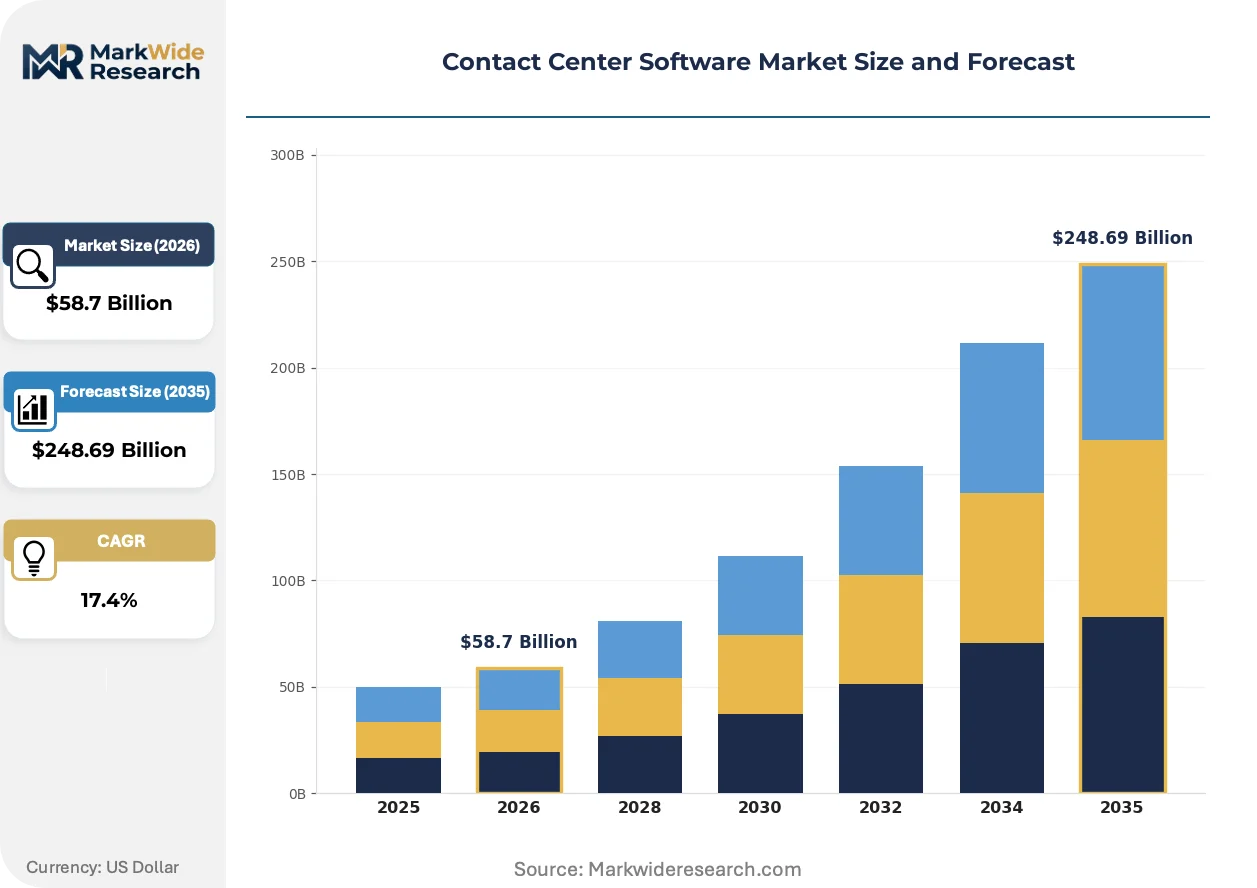
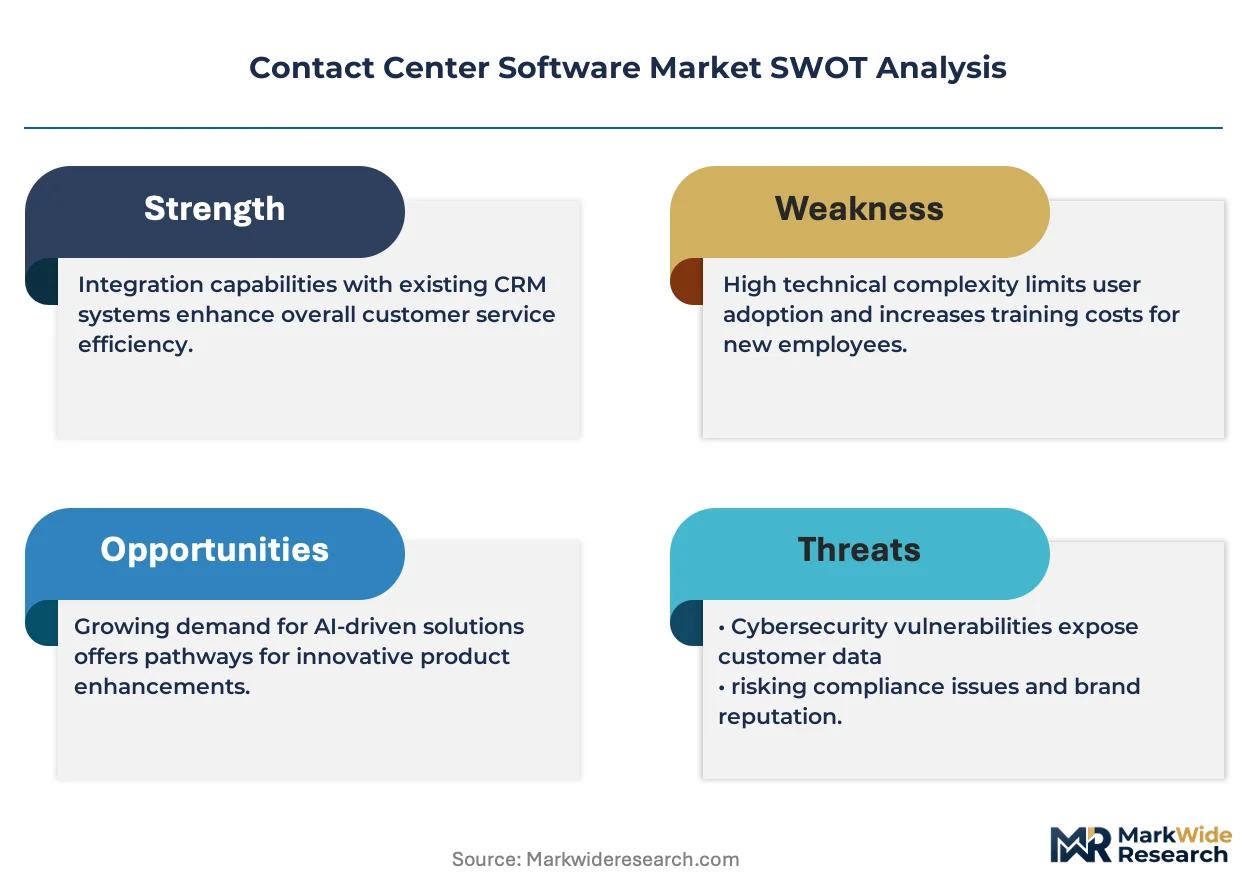
Multi-source vendor strategies is hardening across enterprise procurement of contact center platforms. NICE Ltd. anchors its position through advanced analytics specialization in workforce optimization. Five9, Inc. competes aggressively on cloud-native architecture for mid-market transitions. Cisco Systems, Inc. sustains channel dominance through hybrid deployment flexibility for regulated industries.
Contact center software encompasses integrated applications managing customer interactions across voice, digital, and self-service channels, typically requiring sub-200-millisecond latency for real-time engagement and API connectivity to CRM systems. Its primary purpose is orchestrating inbound and outbound communications while optimizing agent productivity and customer satisfaction metrics. Cloud-based deployment leads expansion as enterprises abandon legacy PBX infrastructure for elastic capacity scaling. Interactive Voice Response systems retain mature margin pools in banking and telecom, while Workforce Management solutions capture fastest-growing demand as remote agent models proliferate.
The FCC enforces TCPA restrictions on automated dialing and prerecorded messaging that directly constrain dialer system design and operational workflows. GDPR in Europe mandates explicit consent for customer data processing across recorded interactions and analytics storage, elevating compliance costs for multi-tenant platforms. ISO 27001 certification has become a baseline procurement filter for healthcare and financial services buyers evaluating vendor security posture. Stakeholders must weigh sovereignty requirements against cloud scalability when architecting cross-border deployment strategies.
Market Dynamics
Cloud-native migration is compressing deployment cycles from months to weeks, forcing incumbent vendors to re-architect legacy platforms or cede mid-market share to elastic SaaS providers.
Growth Catalysts
- AI-powered conversation intelligence:Natural language processing engines now transcribe and analyze 100% of voice interactions in real time, enabling automated quality assurance that reduces supervisor overhead by half.
- GCPR-mandated consent frameworks:European data protection rules compel enterprises to upgrade recording and analytics infrastructure, creating replacement demand for non-compliant legacy systems.
- India's digital infrastructure maturation:Enterprise-grade data center capacity and fiber penetration in Mumbai, Bangalore, and Hyderabad enable cloud contact center migration at scale for domestic BPO operations.
Market Restraints
- TCPA dialer restrictions:FCC enforcement of automated dialing limitations constrains outbound campaign volume and forces expensive compliance re-engineering of predictive dialer algorithms.
- Specialized AI engineering scarcity:Machine learning talent for conversational AI development concentrates in San Francisco, Seattle, and Tel Aviv, inflating implementation costs for vendors without captive R&D clusters.
- Legacy PBX sunk-cost entrenchment:Financial services and healthcare incumbents face seven-figure write-downs for on-premise hardware retirement, delaying cloud migration decisions.
Strategic Opportunities
- Agentic AI workflow automation:Autonomous agents handling tier-one inquiries without human escalation are converging with CRM data layers to unlock fully automated resolution paths.
- Southeast Asian BPO expansion:Philippines and Vietnam regulatory frameworks now permit 100% foreign ownership of IT-enabled services, attracting platform vendor direct investment.
- ISO 27001 certification arbitrage:Healthcare and financial services procurement mandates create premium pricing power for vendors achieving information security management certification ahead of competitors.
Industry Challenges
- Real-time latency engineering:Sub-200-millisecond voice packet delivery requires edge computing infrastructure investments that strain vendor capex allocation across dispersed geographic markets.
- API ecosystem fragmentation:CRM, ticketing, and workforce management systems maintain incompatible data schemas, forcing expensive custom integration development for each enterprise deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Center Software Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $248.69 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solution: Dialer Systems, Interactive Voice Response, Workforce Management, Customer Relationship Management End User: Retail, Healthcare, BFSI, Telecommunications Service Type: Technical Support, Training, Consulting, Maintenance |
| Companies Covered | Genesys Telecommunications Laboratories, Inc., NICE Ltd., Five9, Inc., Cisco Systems, Inc., Twilio, Inc., Mitel Networks Corporation, Amazon Web Services, Inc., Talkdesk, Inc., 8x8, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Center Software Market Strategic Shifts & Innovations
Generative AI is collapsing the cost curve for conversational automation, compressing the economic viability threshold for human-only service models while elevating platform differentiation toward orchestration capabilities rather than channel coverage.
Large language models for contact center applications are converging with proprietary interaction data lakes to produce domain-specific fine-tuned engines. Banking and telecommunications buyers are deploying these systems for complex dispute resolution workflows previously requiring senior agent expertise. This convergence is compressing vendor moats from feature breadth to data network effects.
The EU AI Act's risk classification framework imposes documentation and human oversight mandates on high-risk AI systems including biometric identification and emotion recognition in customer interactions. Vendors must now maintain technical files and conformity assessments for deployment in European markets. Financial services buyers in Frankfurt, Paris, and Amsterdam are prioritizing suppliers with established EU AI Act compliance roadmaps.
Subscription-based consumption models are displacing perpetual license arrangements across enterprise procurement. Mid-market buyers in particular are unbundling implementation services from platform fees, pressuring vendor professional services margins. This shift is most pronounced in United States technology and retail verticals where CFO scrutiny of SaaS spend has intensified.
Contact Center Software Market Segmentation
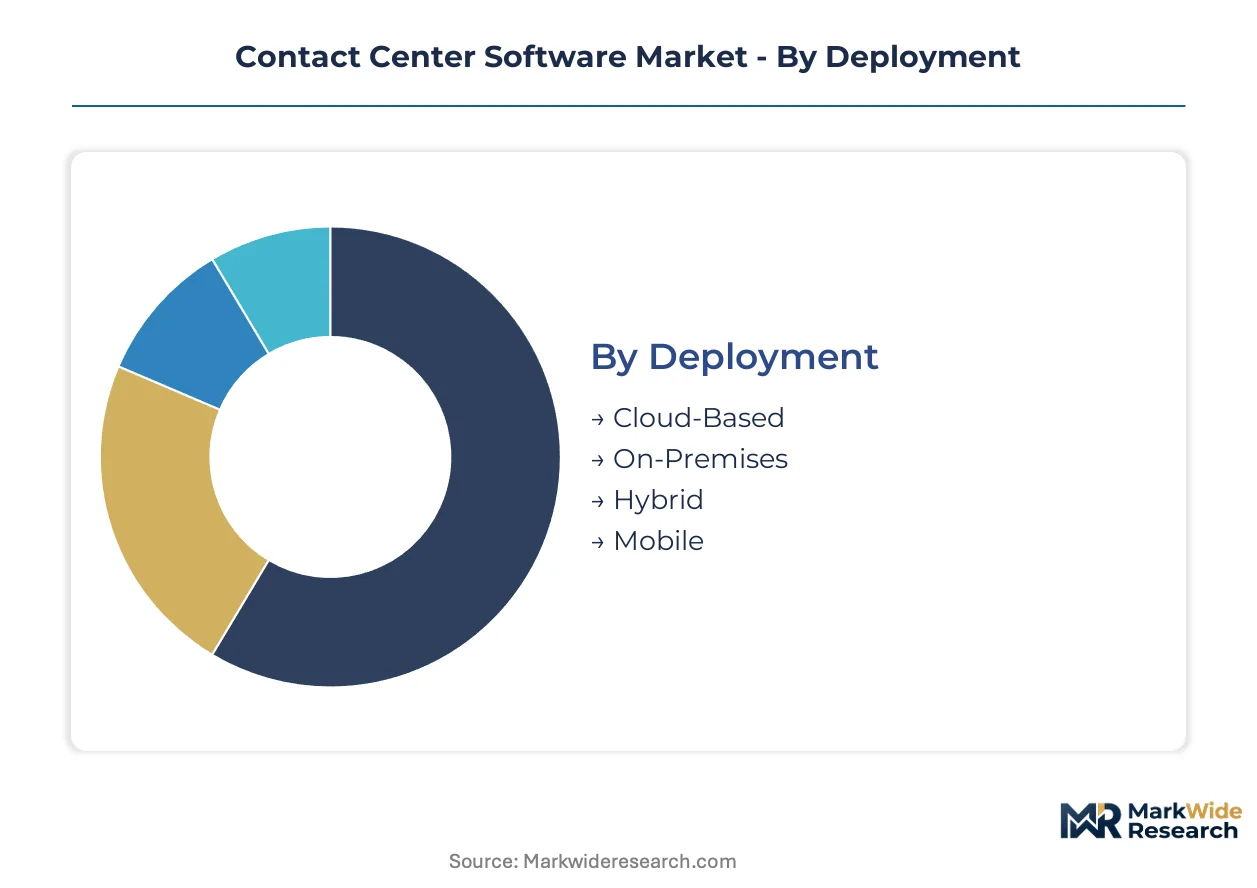
Contact center software segmentation reveals divergent investment profiles across deployment architectures and solution types. Procurement patterns cluster around regulatory tolerance for cloud migration and the technical debt accumulated in legacy voice infrastructure.
Deployment:
Capital intensity varies sharply across deployment modes, with on-premises installations demanding substantial upfront hardware expenditure while cloud alternatives shift costs to recurring operational budgets.
- Cloud-Based:Multi-tenant SaaS architectures eliminate data center capital expenditure and enable elastic capacity scaling. Financial services buyers in Frankfurt and Singapore are migrating here to satisfy GDPR and Monetary Authority of Singapore data sovereignty requirements while avoiding seven-figure PBX write-downs.
- On-Premises:Dedicated hardware deployments retain dedicated customer bases in defense contracting and classified government operations where air-gapped networks are mandatory. Healthcare systems in the United States maintain these installations to satisfy HIPAA audit trail requirements without third-party data exposure.
- Hybrid:Split architectures preserve sensitive interaction data on local infrastructure while pushing routine traffic to cloud elasticity. This configuration dominates telecommunications carriers managing legacy PSTN interconnection obligations alongside digital channel expansion.
- Mobile:Smartphone-native agent applications extend workforce management to field service and gig-economy customer support models. Demand concentrates in logistics and last-mile delivery verticals across India and Brazil.
Cloud-Based absorbs the bulk of installed capacity; Mobile is expanding most quickly.
Solution:
Solution type determines integration complexity and the depth of professional services revenue vendors can capture per engagement.
- Dialer Systems:Predictive and power dialer algorithms automate outbound campaign pacing. FCC TCPA enforcement in the United States constrains algorithm design, forcing compliance re-engineering that elevates implementation costs for vendors serving American debt collection and political campaign verticals.
- Interactive Voice Response:Touch-tone and speech-recognition self-service menus deflect routine inquiries from live agents. Banking institutions in Spain and Italy deploy these for balance inquiries and payment scheduling, capturing mature margin pools despite limited differentiation between competing platforms.
- Workforce Management:Scheduling, forecasting, and adherence monitoring tools optimize agent utilization across remote and hybrid work models. This segment is climbing the fastest as BPO operations in the Philippines and Vietnam scale distributed agent populations.
- Customer Relationship Management:Native or integrated CRM functionality unifies interaction history with sales pipeline data. Retail and e-commerce buyers prioritize these solutions for omnichannel cart recovery and loyalty program management.
Interactive Voice Response retains the largest installed base; Workforce Management is gaining share fastest.
End User:
End-user verticals impose distinct compliance burdens and channel-mix requirements that shape vendor specialization strategies.
- BFSI:Banking and financial services demand biometric authentication, PCI-DSS compliant payment processing, and audit-grade interaction recording. Institutions in Switzerland and Luxembourg select platforms with Swiss FINMA and CSSF alignment for private wealth management operations.
- Healthcare:HIPAA-covered entities require Business Associate Agreements, encrypted data transmission, and granular access controls. Hospital systems in the United States and National Health Service trusts in the United Kingdom drive replacement cycles here.
- Telecommunications:Carriers manage massive inbound volumes for billing disputes, service outages, and technical troubleshooting. Tier-1 operators in Germany and Japan prioritize platforms with native network fault ticketing integration.
- Retail:Seasonal demand spikes and omnichannel return processing define requirements. Direct-to-consumer brands in the United States and fashion retailers in France deploy these solutions for Black Friday and holiday surge capacity.
BFSI commands the deepest per-seat spending; Retail is scaling fastest.
Service Type:
Service attachment rates determine lifetime customer value and the sustainability of vendor margin structures beyond initial license or subscription revenue.
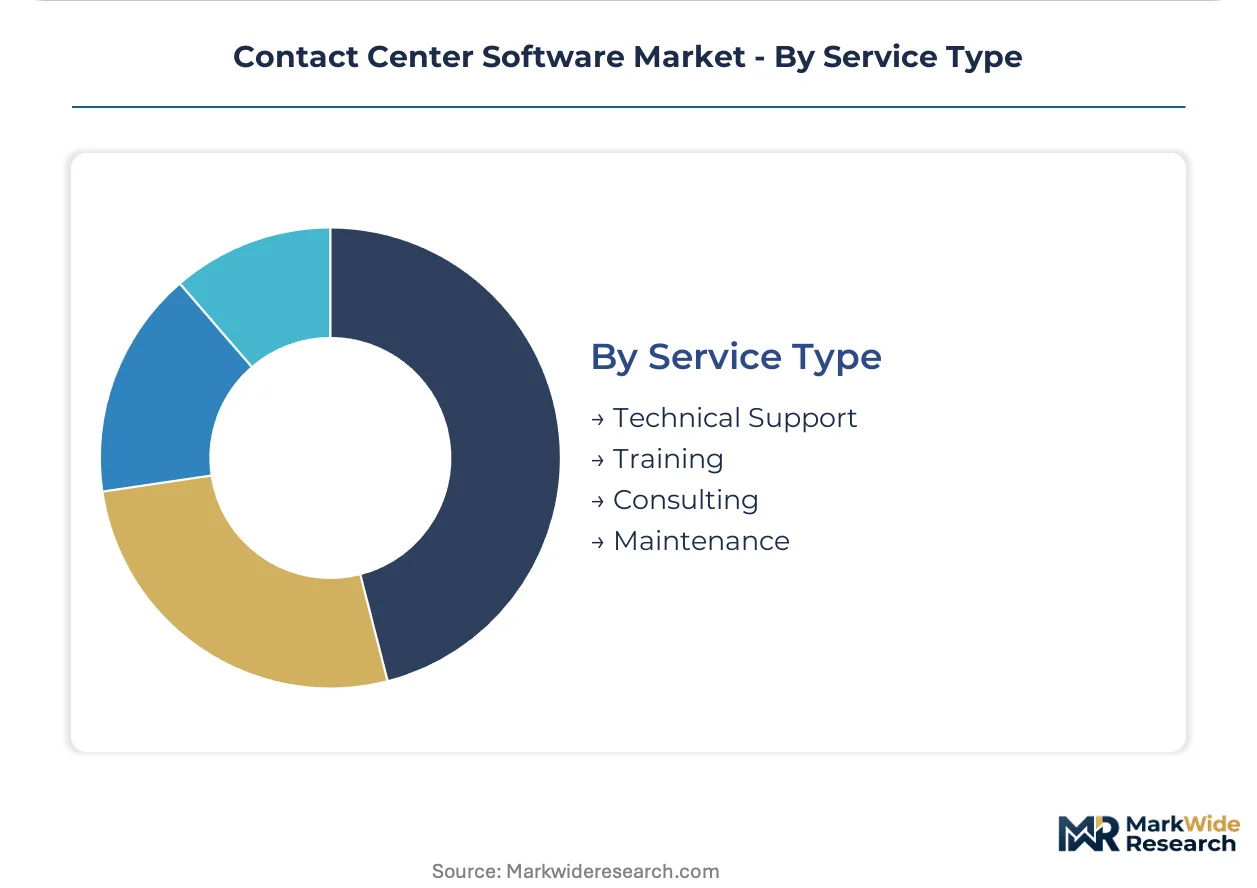
- Consulting:Workflow design, change management, and ROI measurement services accompany complex enterprise transformations. These engagements concentrate in regulated industries undergoing cloud migration in the United Kingdom and Australia.
- Technical Support:Tiered response commitments and dedicated account management ensure platform uptime. Manufacturing and industrial buyers in Germany and Japan prioritize vendors with local-language engineering support.
- Training:Administrator certification and agent onboarding programs accelerate time-to-value. BPO operators in South Africa and Egypt consume these services heavily for workforce ramp-up.
- Maintenance:Patch management, version upgrades, and security hotfix delivery preserve operational continuity. On-premises deployments in government and defense sectors generate sticky recurring revenue here.
Technical Support generates the largest service revenue pool; Consulting is expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital concentration anchors cloud-native platform development, while enterprise adoption clusters around financial centers with stringent data sovereignty requirements.
United States
Banking consolidation in Charlotte and fintech proliferation in San Francisco drive platform demand for omnichannel authentication. FCC TCPA enforcement constrains predictive dialer deployment, elevating compliance engineering costs for vendors serving debt collection verticals. Dallas-Fort Worth hosts expanding BPO operations migrating from legacy PBX to elastic cloud architectures.
Germany
Automotive OEM customer service digitization and industrial equipment aftermarket support create demand for multilingual workforce management tools. EU AI Act documentation requirements impose conformity assessment burdens on emotion recognition and biometric authentication features. Frankfurt's financial services cluster prioritizes platforms with Bundesbank-aligned audit trails and GDPR Article 44 transfer mechanism compliance.
India
Domestic BPO scaling and e-commerce customer service expansion fuel cloud contact center migration. TRAI's cloud services framework and data localization guidance shape vendor infrastructure deployment decisions. Mumbai, Bangalore, and Hyderabad concentrate enterprise-grade data center capacity enabling real-time voice processing for banking and telecommunications clients.
United Kingdom
Insurance sector claims automation and retail banking digital transformation sustain replacement demand for legacy systems. FCA consumer duty rules mandate interaction recording and outcome monitoring that elevate analytics platform requirements. London's fintech corridor drives API-first architecture adoption for embedded finance customer support.
Japan
Telecommunications carrier legacy infrastructure modernization and aging population service accessibility requirements shape solution specifications. METI's AI governance guidelines influence procurement criteria for conversational automation in financial services. Tokyo and Osaka metropolitan areas concentrate enterprise deployment of hybrid architectures preserving on-premises sensitive data handling.
Contact Center Software Market Key Industry Players
Strategic partnerships dominate the current landscape as incumbents accelerate cloud-native re-architecture. The vendor base stratifies across three tiers: established enterprise platforms with hybrid deployment heritage, pure-play SaaS specialists capturing mid-market transitions, and hyperscale cloud providers integrating contact center functionality into broader service suites. Competitive intensity concentrates on AI-powered conversation intelligence capabilities and API ecosystem breadth. M&A activity and technology licensing arrangements represent the primary vectors for capability acquisition and geographic expansion.
Within the established platform tier, NICE Ltd. and Cisco Systems, Inc. occupy positions defined by workforce optimization depth and hybrid infrastructure flexibility respectively. Five9, Inc. exemplifies the cloud-native specialist archetype competing on elastic deployment speed. These three entities represent divergent strategic bets on enterprise migration timelines and regulatory tolerance for multi-tenant architectures.
| Leading Market Players |
|---|
| Genesys Telecommunications Laboratories, Inc. |
| NICE Ltd. |
| Five9, Inc. |
| Cisco Systems, Inc. |
| Twilio, Inc. |
| Mitel Networks Corporation |
| Amazon Web Services, Inc. |
| Talkdesk, Inc. |
| 8x8, Inc. |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure compute costs cascade through subscription tiers, with hyperscaler data center capacity in Mumbai and Frankfurt anchoring price floors for enterprise deployments while unbundled implementation services compress margins for mid-market SaaS providers.
Pricing Analysis
Warranty and technical support bundling separates premium vendor tiers from economy alternatives, with ISO 27001-certified platforms commanding sustained price premiums in healthcare and BFSI procurement. Pricing stratifies across premium, standard, and economy tiers based on AI feature depth and compliance certification level. Cost compression in the mid-market is intensifying because CFO scrutiny of SaaS spend has unbundled professional services from platform fees. Retail and e-commerce buyers exhibit highest price sensitivity, while Swiss private wealth management operations tolerate premium pricing for FINMA-aligned audit capabilities.
Supply Chain Analysis
Refurbishment and legacy PBX migration flows create secondary equipment markets that extend hardware lifecycles and delay full cloud transitions for cost-constrained buyers. Software development concentrates in the United States, India, and Israel, with conversational AI engineering talent clustering in San Francisco, Bangalore, and Tel Aviv. Platform architecture rests on GPU compute from NVIDIA and AMD, API gateway infrastructure from hyperscalers, and telecommunications interconnection agreements with carriers. Single-source vulnerability in specialized AI chip supply threatens capacity scaling for real-time transcription workloads. Distribution runs through direct enterprise sales, systems integrator partnerships, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architectures are displacing legacy on-premise PBX installations, with agentic AI automation converging with CRM data layers to unlock fully automated resolution paths previously requiring human escalation.
For Market Incumbents: Anticipate margin compression from pure-play SaaS specialists by accelerating hybrid-to-cloud re-architecture and embedding workforce optimization analytics deeper into core platforms. Defensive consolidation through acquisition of conversational AI specialists in Tel Aviv and Bangalore addresses machine learning talent scarcity. ISO 27001 certification investment preserves pricing power in healthcare procurement.
For New Entrants and Emerging Players: Systems integrator partnerships offer the fastest path to enterprise referenceability without direct sales infrastructure buildout. Southeast Asian BPO expansion in Vietnam and the Philippines presents the most penetrable geography, with 100% foreign ownership frameworks enabling direct platform investment. Target mid-market retail and logistics verticals with smartphone-native agent applications for field service deployment.
For Investors and Strategic Acquirers: EU AI Act conformity assessment completion is the leading indicator that European market access risk has been de-risked for acquisition targets. Long-term viability hinges on data network effects from proprietary interaction lakes rather than feature breadth. Monitor Bundesbank-aligned audit trail capabilities as the signal for German financial services readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CRM data layers with conversational AI for automated resolution paths in banking disputes. |
| Geographic Expansion | Captures Philippines and Vietnam BPO scaling with regulatory-compliant multi-tenant infrastructure. |
| Acquisition of Specialist Firm | Addresses machine learning engineering scarcity through Tel Aviv and Bangalore talent clusters. |
| Strategic Partnership | Accelerates enterprise referenceability via systems integrator channel relationships. |
| Product Launch | Deploys agentic AI workflow automation for tier-one inquiry handling without human escalation. |
Research Approach
Multi-period observation of cloud migration velocity, AI feature adoption curves, and compliance certification timelines anchored the trend analysis, supplemented by interviews with contact center operations directors, IT procurement officers, BPO managing directors, and workforce optimization specialists. Primary fieldwork combined with secondary validation from SEC filings of publicly traded vendors, TRAI cloud services framework documentation, EU AI Act implementation guidance, and hyperscaler capex disclosures. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segment-weighting applied deployment architecture, solution type, end-user vertical, and regional regulatory cluster as primary dimensions. CAGRs derived from elasticity-adjusted adoption curves incorporating legacy PBX replacement cycles and cloud-native greenfield expansion. Forecast inputs included FCC TCPA enforcement intensity, GDPR Article 44 transfer mechanism adoption, and ISO 27001 certification penetration rates across healthcare and financial services buyers.
Caveats apply where FCC regulatory reinterpretation, EU AI Act risk classification expansion, or hyperscaler data center capacity constraints could materially shift the outlook. Practitioners should monitor agentic AI resolution accuracy metrics and biometric authentication consent framework litigation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
US Customer Relationship Management Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market