
 Valve Interlocks Market | 2026-2036
Valve Interlocks Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Interlocks Market Insights
Buyer concentration among multinational oil and gas operators is realigning procurement standards toward integrated safety system packages. Smith Flow Control Ltd leverages its trapped-key specialization to sustain long-term contracts with North Sea and Gulf Coast petrochemical complexes. Emerson Electric Co. anchors its position through embedded interlock logic within distributed control system architectures, while Schneider Electric SE competes by extending electrical interlock portfolios into IoT-enabled safety platforms.
Valve interlocks are mechanical or electromechanical safety devices that enforce predetermined valve operating sequences through keyed or coded locking mechanisms, typically constructed from stainless steel or brass housings with corrosion-resistant internal cams and pins. Their primary industrial purpose is preventing hazardous process events such as cross-contamination, pressure buildup, or unintended chemical release by physically blocking incorrect valve positions until prerequisite conditions are satisfied. Mechanical interlocks still occupy the largest installed base across legacy oil and gas infrastructure, though smart interlocks are displacing traditional systems in greenfield chemical processing plants where digital safety integrity level verification is mandated. The application split reveals oil and gas as the dominant revenue pool, while water and wastewater utilities represent the fastest structural expansion as municipal infrastructure resilience programs accelerate sequential valve automation.
OSHA process safety management requirements and ISO 14119 machinery safety standards directly shape product certification pathways and installation protocols for valve interlock manufacturers seeking North American and European market access. The EPA's Risk Management Program amendments and the EU Machinery Directive's updated conformity assessment procedures are tightening documentation burdens for interlock system integrators. Stakeholders must monitor evolving cybersecurity annexes to functional safety standards, as smart interlock adoption introduces network-accessible attack surfaces previously absent in purely mechanical designs.
Market Dynamics
OSHA process safety mandates and ISO 14119 machinery guarding standards are compressing certification timelines and forcing interlock manufacturers to embed digital safety integrity verification into mechanical designs. This regulatory convergence is restructuring competitive advantage around integrated safety system architecture rather than standalone hardware.
Growth Catalysts
- Petrochemical cluster expansion:Gulf Coast and North Sea operators are mandating trapped-key interlock sequences for refinery turnarounds and new unit commissioning, locking in long-term procurement contracts.
- EPA Risk Management Program amendments:Updated documentation requirements for chemical process facilities are accelerating replacement of legacy manual valve lockout systems with automated sequential interlocks.
- Smart interlock digitization:IoT-enabled safety platforms with real-time position monitoring are capturing greenfield chemical plant specifications where digital safety integrity level verification is now standard.
Market Restraints
- Stainless steel input volatility:Corrosion-resistant housing materials face price swings tied to nickel and chromium supply disruptions from Indonesian and Russian export channels.
- Mechanical interlock installed base inertia:Decades of legacy trapped-key systems in North American oil and gas infrastructure create switching friction against electromechanical upgrades.
- EU Machinery Directive conformity costs:Updated assessment procedures impose documentation burdens that disproportionately burden mid-tier system integrators without dedicated compliance teams.
Strategic Opportunities
- Municipal water infrastructure resilience:Sequential valve automation programs in German and Chinese utility networks represent underpenetrated demand for electromechanical interlock retrofits.
- Cybersecurity-integrated safety platforms:Convergence of IEC 62443 industrial cybersecurity standards with functional safety protocols opens specification channels in critical infrastructure.
- Performance-based maintenance contracts:Service unbundling from hardware sales creates recurring revenue streams as operators outsource interlock calibration and key management.
Industry Challenges
- SIL certification timeline compression:Third-party safety integrity level verification for smart interlocks now stretches 14-18 months, delaying project commissioning and straining manufacturer engineering capacity.
- Legacy DCS integration complexity:Electromechanical interlocks must interface with decades-old distributed control system architectures from Emerson, Honeywell, and Yokogawa, requiring custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Interlocks Market |
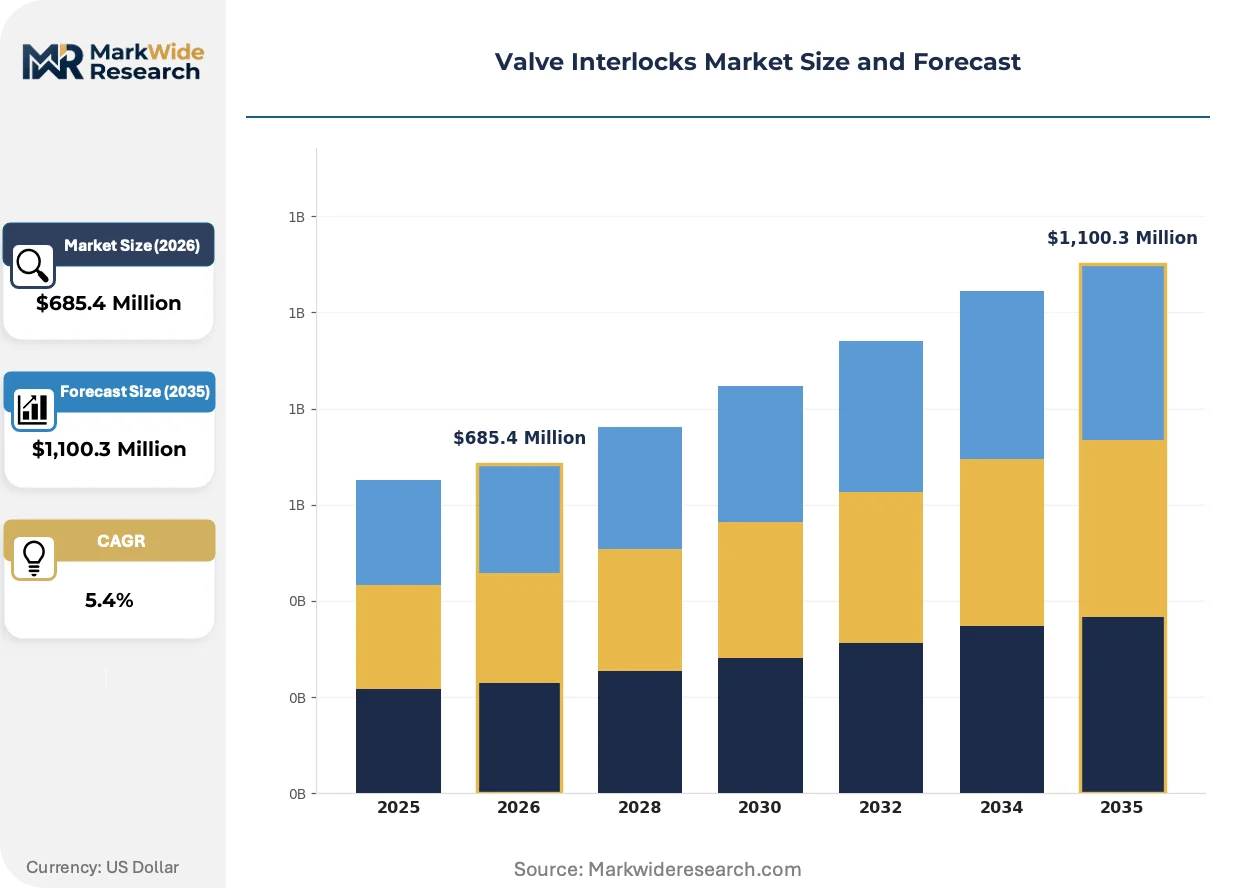
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,100.3 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Interlocks, Electrical Interlocks, Pneumatic Interlocks, Hydraulic Interlocks Application: Oil & Gas, Water & Wastewater, Power Generation, Chemical Processing End User: Utilities, Industrial Plants, Marine, Manufacturing Technology: Smart Interlocks, Manual Interlocks, Automated Solutions, Traditional Systems |
| Companies Covered | Smith Flow Control Ltd, Alcatraz Interlocks BV, Emerson Electric Co., Kirk Key Interlock Company LLC, Sofis BV, Schneider Electric SE, Velan Inc., Habonim Industrial Valves & Actuators Ltd., Castell Safety International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Interlocks Market Trends and Innovations
Digital safety architecture is rewriting how valve interlocks are specified, procured, and maintained across process industries. Three convergent developments are compressing the traditional mechanical-electromechanical boundary and elevating cybersecurity to a core design parameter.
Wireless position sensing with battery-free energy harvesting is rewriting interlock deployment economics in remote pipeline stations and offshore platforms. Shell and BP are piloting these systems in North Sea installations where hardwired power runs prove cost-prohibitive. The technology is rewriting the capital-expense threshold for sequential safety coverage, extending interlock protection to previously uneconomic valve clusters.
REACH substance restrictions and RoHS hazardous material limits are forcing brass housing suppliers to reformulate alloys and eliminate lead-bearing components. European valve interlock manufacturers face 18-month material recertification cycles to maintain CE marking validity. German chemical processors are responding by consolidating procurement around suppliers with pre-validated green material portfolios.
Integrated safety system procurement is displacing standalone interlock purchasing as major operators bundle valve interlocks with DCS, ESD, and fire-and-gas detection under single-source contracts. This pattern concentrates specification influence with Emerson, Schneider, and Yokogawa system integrators. The shift is most visible in Middle Eastern petrochemical greenfield projects where lump-sum turnkey contracts dominate.
Valve Interlocks Market Segmentation
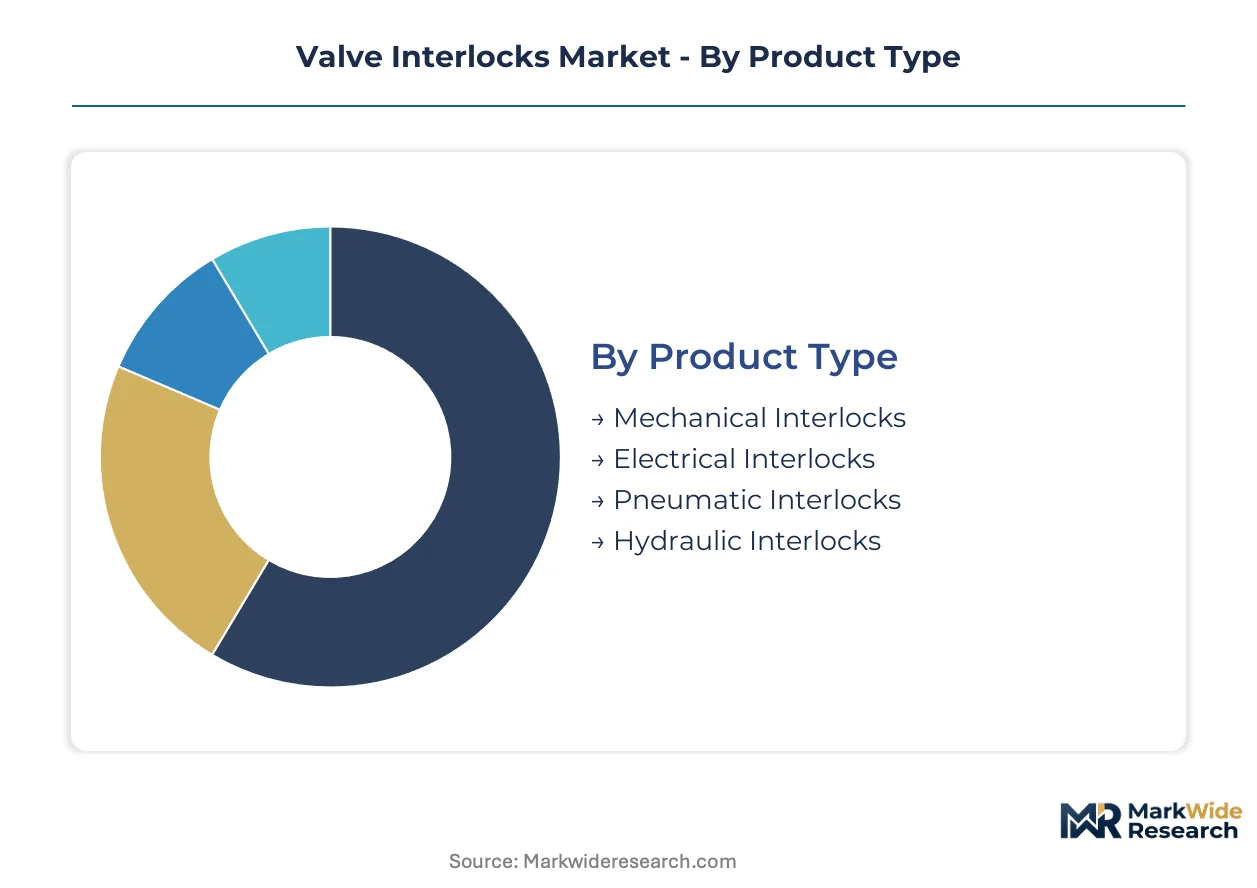
Valve interlock segmentation reveals divergent procurement patterns across mechanical, electromechanical, and digitally integrated safety architectures. Buyers select interlock categories based on legacy infrastructure compatibility, safety integrity level requirements, and total cost of ownership across 20-30 year asset lifecycles.
Product Type:
Cost tier differentiation separates buyers pursuing lowest capital expenditure from those prioritizing lifecycle safety verification.
- Mechanical Interlocks:Trapped-key mechanisms constructed from stainless steel or brass housings with corrosion-resistant internal cams deliver fail-safe physical blocking without electrical dependencies. Gulf Coast and North Sea petrochemical operators specify these for refinery turnarounds where explosion-proof ratings are mandatory and power infrastructure is unreliable.
- Electrical Interlocks:Solenoid-actuated locking bolts integrated with distributed control system architectures enable remote position monitoring and automated safety sequences. Greenfield chemical processing plants in Germany and China are specifying these where digital safety integrity level verification is contractually required.
- Pneumatic Interlocks:Air-actuated locking mechanisms suit high-vibration environments in offshore platforms where electrical spark hazards are prohibited.
- Hydraulic Interlocks:Fluid-pressure locking systems serve heavy-duty valve applications in power generation turbine isolation sequences.
Mechanical interlocks lead volumes today; electrical interlocks are gaining share fastest.
Application:
Volume concentration tracks capital expenditure cycles in process industries with the most stringent sequential safety mandates.
- Oil & Gas:Upstream, midstream, and downstream operations deploy trapped-key and electromechanical sequences to prevent cross-contamination, pressure buildup, and unintended chemical release during unit commissioning and emergency shutdowns. OSHA process safety management requirements and EPA Risk Management Program amendments are accelerating replacement of manual lockout systems across Texas and Louisiana refining corridors.
- Water & Wastewater:Municipal sequential valve automation programs are expanding fastest in German and Chinese utility networks where infrastructure resilience funding targets flood prevention and contamination isolation. Electromechanical retrofits are displacing manual operations in treatment plant upgrade cycles.
- Power Generation:Turbine isolation and steam system interlocks protect combined-cycle and nuclear facilities from thermal excursion events.
- Chemical Processing:Batch reactor sequencing and hazardous material transfer operations demand SIL-certified interlock architectures.
Oil and gas commands the largest revenue pool; water and wastewater represents the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, from centralized utility specifications to fragmented industrial maintenance budgets.
- Utilities:Municipal water authorities and electric power generators issue long-term framework agreements for sequential valve automation, prioritizing cybersecurity-integrated platforms and performance-based maintenance contracts over standalone hardware purchases.
- Industrial Plants:Petrochemical, pharmaceutical, and food processing facilities specify interlocks as components of integrated safety system procurement bundling DCS, ESD, and fire-and-gas detection under single-source contracts.
- Marine:Offshore platform operators and LNG carriers require explosion-proof mechanical interlocks with marine-grade corrosion resistance.
- Manufacturing:Discrete manufacturing applies machinery guarding interlocks under ISO 14119 standards for press safety and robotic cell access control.
Industrial plants dominate current procurement volumes; utilities are expanding most quickly.
Technology:
Maturity gradient separates legacy installed base preservation from greenfield digital safety architecture adoption.
- Smart Interlocks:IoT-enabled platforms with real-time position monitoring, wireless energy-harvesting sensors, and IEC 62443 cybersecurity compliance are capturing specifications in Middle Eastern petrochemical greenfield projects and North Sea offshore pilots where hardwired power runs prove cost-prohibitive.
- Manual Interlocks:Purely mechanical trapped-key systems without electrical components maintain dominance in legacy North American oil and gas infrastructure where switching friction against electromechanical upgrades is pronounced.
- Automated Solutions:Programmable electromechanical sequences with DCS integration serve chemical plants requiring dynamic safety logic.
- Traditional Systems:Conventional keyed locks without sequence enforcement persist in low-criticality manufacturing applications.
Manual interlocks retain the largest installed base; smart interlocks are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal utilities outpace Chinese petrochemical clusters in sequential valve automation procurement velocity, while Gulf Coast operators sustain the largest trapped-key interlock installed base worldwide.
United States
OSHA process safety management enforcement and EPA Risk Management Program amendments drive replacement of manual lockout systems across Texas and Louisiana refining corridors. Gulf Coast petrochemical operators mandate trapped-key sequences for refinery turnarounds, locking in long-term procurement contracts with interlock specialists.
Germany
Municipal water infrastructure resilience programs target flood prevention and contamination isolation through electromechanical retrofits. REACH substance restrictions and RoHS hazardous material limits force brass housing suppliers into 18-month material recertification cycles, consolidating procurement around suppliers with pre-validated green material portfolios.
China
Petrochemical cluster investments and utility infrastructure upgrades accelerate demand for smart interlock systems with digital safety integrity level verification. Yangtze River Delta chemical processors specify IoT-enabled safety platforms where hardwired power runs prove cost-prohibitive.
Saudi Arabia
Middle Eastern petrochemical greenfield projects favor lump-sum turnkey contracts bundling valve interlocks with distributed control systems. NEOM Northwest development and Eastern Province refining expansions create specification channels for cybersecurity-integrated safety platforms.
United Kingdom
North Sea offshore operators pilot wireless position sensing with battery-free energy harvesting in remote pipeline stations. Shell and BP deployments extend sequential safety coverage to previously uneconomic valve clusters where hardwired infrastructure is unavailable.
Valve Interlocks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across mechanical, electromechanical, and smart interlock categories. The vendor base organizes into three tiers: integrated safety system providers, trapped-key specialists, and regional fabrication houses. Market structure rewards players with pre-certified SIL architectures and established relationships with multinational oil and gas operators. Dominant competitive moves include strategic partnerships with distributed control system integrators and portfolio diversification into IoT-enabled safety platforms.
Among trapped-key specialists, Smith Flow Control Ltd and Kirk Key Interlock Company LLC exemplify the focused pure-play archetype, while Emerson Electric Co. anchors the integrated safety system tier through embedded interlock logic within control architectures. Schneider Electric SE occupies a position spanning both electrical interlock portfolios and IoT-enabled safety platform extension.
| Leading Market Players |
|---|
| Smith Flow Control Ltd |
| Alcatraz Interlocks BV |
| Emerson Electric Co. |
| Kirk Key Interlock Company LLC |
| Sofis BV |
| Schneider Electric SE |
| Velan Inc. |
| Habonim Industrial Valves & Actuators Ltd. |
| Castell Safety International Ltd |
| Others |
Pricing and Supply Chain Analysis
OSHA process safety management mandates and EPA Risk Management Program amendments are forcing North American oil and gas operators toward SIL-certified electromechanical systems, compelling suppliers to absorb certification costs while brass housing manufacturers navigate REACH substance restrictions that extend material recertification cycles.
Pricing Analysis
Capacity additions in China and Germany are reshaping price floors for electromechanical interlock modules as local manufacturers achieve scale economies in sensor-integrated housing production. Three-tier pricing structure across premium SIL-certified, standard electromechanical, and economy mechanical tiers separates buyers by safety integrity verification requirements. Cost compression in the premium tier is intensifying because Schneider and Emerson are bundling interlock logic into DCS contracts at reduced standalone margins. Municipal water utilities exhibit the highest price sensitivity due to fragmented procurement budgets, while Middle Eastern petrochemical greenfield projects show the lowest sensitivity under lump-sum turnkey structures.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia's NEOM development and China's Yangtze River Delta chemical corridor are reshaping sourcing patterns toward local stainless steel fabricators and sensor assembly operations. Manufacturing concentrates in China, Germany, and the United States, with corrosion-resistant housing production drawing from nickel and chromium supply channels anchored in Indonesian and Russian export nodes. Single-source vulnerability in nickel supply creates exposure to export disruption events. Distribution runs through authorized system integrators and DCS channel partners rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in valve interlocks rests on the shift from standalone hardware sales toward recurring performance-based maintenance contracts, where service unbundling captures value from calibration and key management outsourcing.
For Market Incumbents: Hedge against smart interlock commoditization by deepening captive supply of wireless position sensing modules and pre-certifying green brass alloys ahead of RoHS enforcement waves. Trapped-key specialists must defend against integrated safety system bundling by embedding interlock logic into third-party DCS architectures through protocol gateway partnerships. For New Entrants and Emerging Players: The price-point gap between premium SIL-certified systems and economy mechanical interlocks creates entry space for mid-tier electromechanical retrofits targeting German municipal water utilities. Focus specification capture on sequential valve automation programs in underpenetrated Chinese utility networks where infrastructure resilience funding accelerates. Lead with cybersecurity-integrated platforms as the go-to-market differentiator against legacy mechanical installed base. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play trapped-key specialists holding North Sea and Gulf Coast long-term service contracts that generate recurring calibration revenue. Five-to-ten year viability favors vendors with pre-certified SIL architectures and established multinational oil and gas operator relationships. Monitor IEC 62443 cybersecurity annex adoption rates as the inflection signal for smart interlock specification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures margin from wireless position sensing modules specified in North Sea offshore pilots. |
| Green Material Portfolio Pre-certification | Secures CE marking continuity ahead of REACH substance restriction enforcement on brass housings. |
| Performance-based Maintenance Contract Expansion | Converts hardware sales into recurring revenue streams from key management and calibration outsourcing. |
| Cybersecurity-integrated Safety Platform Launch | Opens specification channels in Saudi NEOM and Middle Eastern petrochemical greenfield projects. |
| Strategic Partnership with DCS Integrators | Embeds interlock logic within Emerson and Yokogawa control architectures against standalone competitors. |
Research Methodology
Direct dialogue with plant engineers at Gulf Coast petrochemical complexes, maintenance directors at German municipal water utilities, procurement leads at North Sea offshore operators, and safety system integrators supplied qualitative grounding for demand patterns. Secondary validation drew from OSHA enforcement records, EPA Risk Management Program filings, ISO 14119 certification databases, and customs trade data on stainless steel valve component imports. Bottom-up segment sizing triangulated against top-down industry expenditure estimates across mechanical, electromechanical, and smart interlock categories.
Output projections span the analysis window across product type, application, end user, and technology segmentation dimensions with regional disaggregation. CAGRs derived from fitted growth curves incorporating petrochemical capital expenditure cycles, utility infrastructure upgrade timelines, and regulatory compliance deadline clustering. Forecast inputs included nickel price volatility indices, SIL certification queue lengths, and DCS replacement cycles at major oil and gas operators.
Caveats apply where nickel supply disruptions, cybersecurity standard revision timelines, or mechanical-to-electromechanical switching friction could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Harmonic Dampers Market
Valves
Pressure Reducing Valve Market
Valves
Valve Remote Control System Market
Valves
Global Stainless Steel Control Valves Market
Valves
Actuators and Valves Market
Valves
Middle East and Africa Machined Seals Market
Valves
North America Irrigation Valves Market
Valves
Global Flow Control Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Sand Control System Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Dense Phase Vessels Market
Valves
North America Valves Market
Valves
Isolator Valves Market