
 Construction Risk Assessment Software Market | 2026-2036
Construction Risk Assessment Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Risk Assessment Software Market Insights
ISO 45001 certification is reorganizing competitive standing in construction risk assessment software, as enterprise buyers now require occupational health and safety management validation from vendors. Procore Technologies leverages its cloud-native project management heritage to anchor risk modules within existing contractor workflows. Autodesk competes through BIM-integrated hazard visualization that extends its design-to-construction data thread. Bentley Systems specializes in infrastructure-scale risk modeling for transportation and energy megaprojects, dominating segments where geospatial precision governs safety outcomes.
Construction risk assessment software encompasses digital platforms that ingest site telemetry, worker location data, and environmental sensors to calculate probability-weighted safety scores and trigger automated compliance alerts. These systems integrate machine learning classifiers trained on incident databases to flag near-miss patterns before injury events occur. Cloud-based deployment leads the market by absorbing capital constraints from mid-sized contractors who lack server infrastructure. Hazard identification solutions within the solution type category capture the fastest growth as computer vision and wearable sensor feeds enable real-time anomaly detection. Regulatory reporting use cases sit at the mature margin pool, where established workflows and audit trail requirements resist platform switching.
OSHA mandates in the United States, the EU AI Act's risk classification framework for automated decision systems, and ISO 31000 enterprise risk management standards collectively shape product roadmaps and vendor qualification criteria. The EU AI Act specifically constrains how European construction firms deploy algorithmic severity scoring, forcing transparency disclosures that increase implementation complexity. Stakeholders must monitor how emerging building safety codes in jurisdictions with post-Grenfell regulatory tightening will mandate predictive risk analytics as a condition of occupancy permitting.
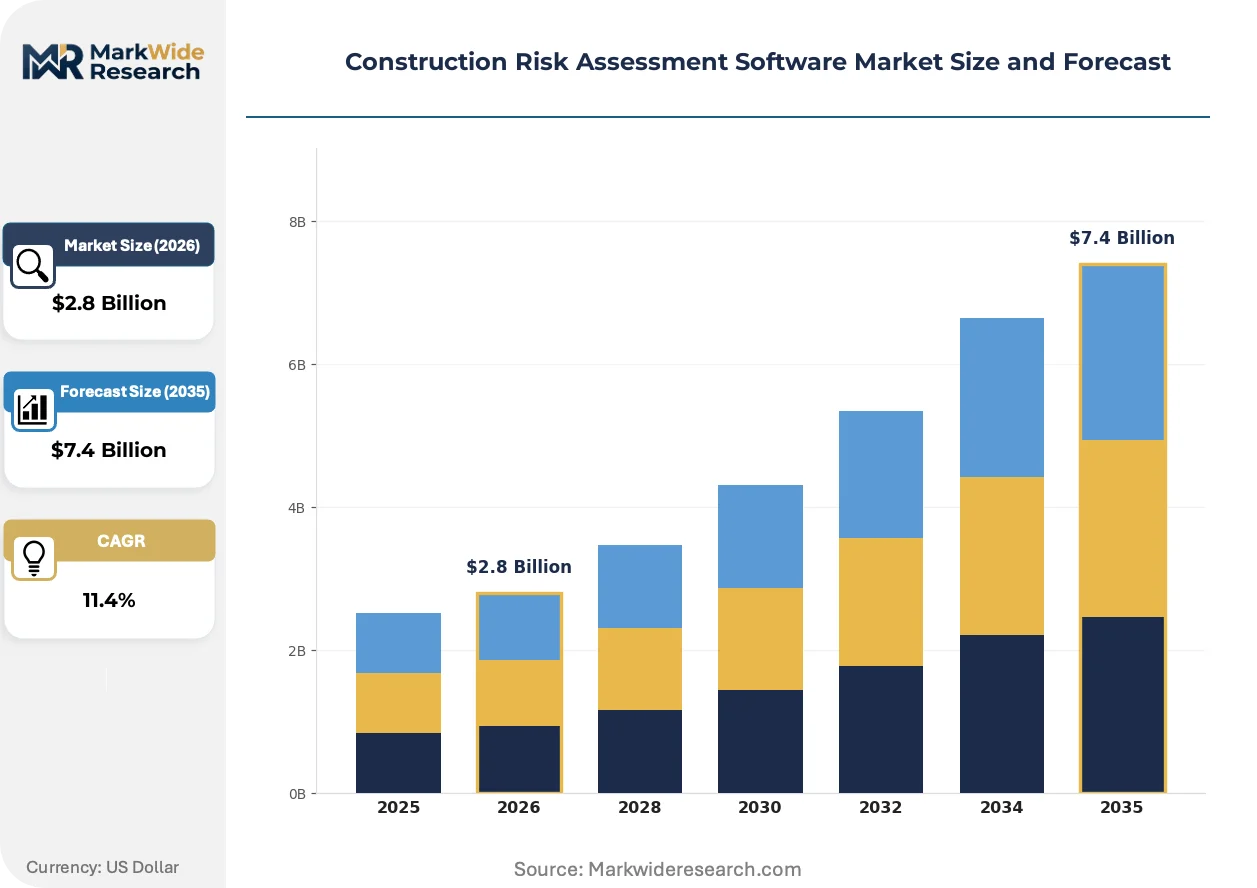
Market Dynamics
Cloud-native architecture is compressing deployment timelines for construction risk platforms, while OSHA recordkeeping mandates and ISO 45001 certification requirements force mid-sized contractors toward subscription-based compliance tools.
Growth Catalysts
- Federal infrastructure spending:United States appropriations for transportation and energy megaprojects mandate digital safety documentation, pulling general contractors toward integrated risk modules.
- Wearable sensor proliferation:Biometric hardhats and location-aware vests feed real-time worker proximity data into hazard scoring algorithms, accelerating near-miss detection.
- ISO 45001 certification:Enterprise procurement departments now require occupational health and safety management validation from software vendors, filtering vendor pools.
Market Restraints
- Data interoperability friction:Proprietary BIM formats and fragmented sensor protocols force costly middleware development for system integration.
- Specialized talent scarcity:Construction technologists with dual competency in safety engineering and machine learning deployment command premium compensation, constraining vendor scaling.
- EU AI Act algorithmic transparency:Automated severity scoring systems in European jurisdictions face mandatory explainability disclosures, increasing implementation complexity.
Strategic Opportunities
- India infrastructure buildout:National highway and urban metro expansion under BIS construction codes creates first-mover advantage for cloud-based hazard platforms.
- Computer vision convergence:Edge-deployed video analytics paired with drone photogrammetry enables autonomous site surveillance without dedicated sensor infrastructure.
- Insurance-linked pricing models:Usage-based premiums tied to real-time risk scores align vendor revenue with client safety outcomes.
Industry Challenges
- Legacy ERP integration:On-premise project management systems at established contractors resist API connectivity, extending sales cycles.
- Workforce digital literacy gaps:Field supervisors require sustained training on dashboard interpretation and alert response protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Risk Assessment Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Edge-based Solution Type: Hazard Identification, Risk Quantification, Compliance Management, Safety Training Use Case: Project Planning, Site Monitoring, Incident Investigation, Regulatory Reporting End User: General Contractors, Architects, Safety Consultants, Insurance Firms |
| Companies Covered | Procore Technologies, Autodesk, Oracle, Trimble, Bentley Systems, SafetyCulture, HammerTech Global, Novade Solutions, SiteDocs Safety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Risk Assessment Software Market Trends and Innovations
Construction risk assessment software is pivoting from retrospective incident logging toward predictive intervention systems, with three developmental vectors reshaping competitive requirements.
Edge computing architectures for site-level inference is bifurcating the vendor landscape. Real-time processing of video and sensor streams without cloud round-trips enables sub-second hazard alerts for heavy machinery collision avoidance. Tier-one contractors with dedicated IT infrastructure deploy on-premise nodes, while mid-market buyers rely on vendor-managed edge-as-a-service subscriptions.
OSHA's proposed heat illness prevention standard is accelerating investment in environmental monitoring stacks. The rule would mandate rest-break algorithms triggered by wet-bulb globe temperature thresholds, forcing software vendors to integrate meteorological APIs and physiological modeling. United States-based commercial developers are pre-emptively procuring platforms with built-in heat stress modules.
Subscription pricing for compliance documentation is displacing perpetual license structures. General contractors now expect monthly fees covering automatic regulatory update deployment and audit-ready report generation. This shift concentrates vendor attention on retention metrics and customer success functions rather than upfront implementation revenue.
Construction Risk Assessment Software Market Segmentation
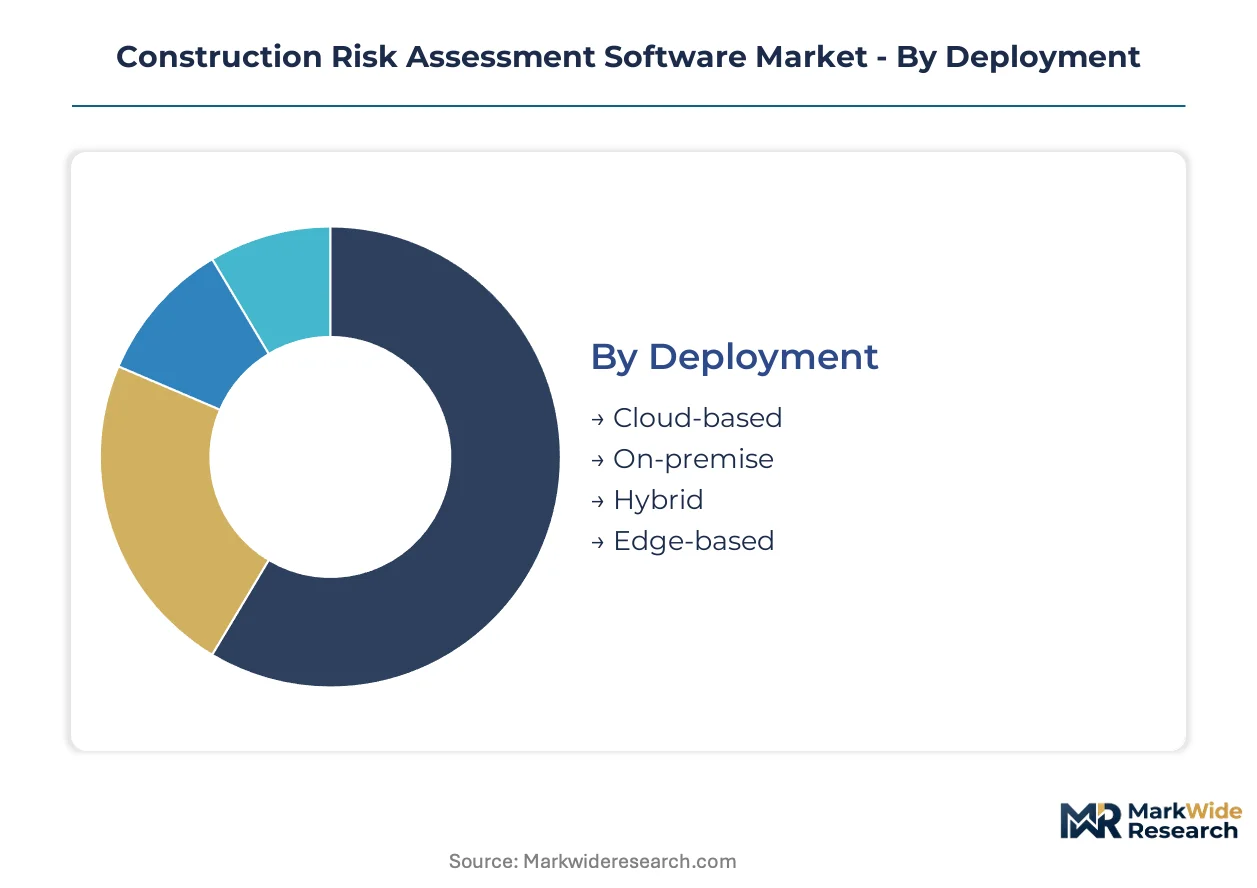
Construction risk assessment software segments by deployment architecture, solution capability, operational use case, and professional end user. Each dimension governs distinct procurement patterns, integration requirements, and margin structures across contractor workflows.
Deployment:
Channel mix varies sharply by deployment mode: cloud-based platforms flow through vendor direct sales and construction technology distributors, while on-premise and edge-based systems rely on systems integrators and specialized safety equipment dealers.
- Cloud-based:Multi-tenant SaaS architectures with API-first design enable rapid provisioning for mid-sized contractors lacking server infrastructure. Demand concentrates among United States commercial developers where federal infrastructure documentation mandates require scalable subscription models.
- On-premise:Single-tenant installations with dedicated hardware satisfy data sovereignty requirements at defense and critical infrastructure contractors. European energy megaprojects under EU AI Act algorithmic transparency rules favor this deployment for audit trail control.
- Hybrid:Split architectures process sensitive worker biometric data locally while pushing anonymized analytics to cloud dashboards. Safety consultants serving cross-border clients deploy hybrid stacks to navigate fragmented privacy regimes.
- Edge-based:Site-level inference nodes process video and sensor streams without latency-heavy cloud round-trips. Tier-one United States contractors with dedicated IT infrastructure source edge hardware through industrial automation channels.
Cloud-based platforms dominate installed base. Edge-based deployment is where expansion concentrates.
Solution Type:
Cost tier stratification separates premium hazard identification modules from standardized compliance tools, with pricing scaling by sensor integration depth and machine learning sophistication.
- Hazard Identification:Computer vision classifiers and wearable sensor fusion detect near-miss patterns in real time. United States general contractors procuring under OSHA recordkeeping mandates drive fastest segment expansion.
- Risk Quantification:Probability-weighted severity scoring algorithms aggregate historical incident databases with project-specific variables. Insurance firms in London and New York use these tools to adjust contractor premiums dynamically.
- Compliance Management:Automated regulatory update pipelines and audit-ready documentation generators serve mature procurement workflows. Architects in Germany and France source these modules for ISO 45001 certification maintenance.
- Safety Training:Virtual reality hazard simulations and microlearning platforms target workforce digital literacy gaps. India's national highway expansion under BIS construction codes is pulling demand for localized training content.
Compliance Management anchors recurring revenue streams. Hazard Identification is climbing the fastest.
Use Case:
Application maturity governs vendor positioning: project planning and regulatory reporting sit at established margin pools, while site monitoring commands premium pricing for real-time infrastructure.
- Project Planning:Pre-construction risk registers and subcontractor safety qualification workflows integrate with BIM and ERP systems. United States commercial real estate developers deploy these tools during design-phase contractor selection.
- Site Monitoring:Continuous telemetry ingestion from environmental sensors, worker wearables, and equipment telematics enables intervention before injury events. Heavy machinery collision avoidance in Australian mining and United States energy construction drives specialized demand.
- Incident Investigation:Root cause analysis modules with timeline reconstruction and witness interview digitization serve post-event documentation requirements. Safety consultants in Canada and the United Kingdom procure these for litigation defense preparation.
- Regulatory Reporting:Pre-formatted submission generators for OSHA, HSE, and jurisdiction-specific regulators resist platform switching due to audit trail requirements. Established United States general contractors treat these as sunk-cost infrastructure.
Regulatory Reporting locks in retention-heavy accounts. Site Monitoring is gaining share fastest.
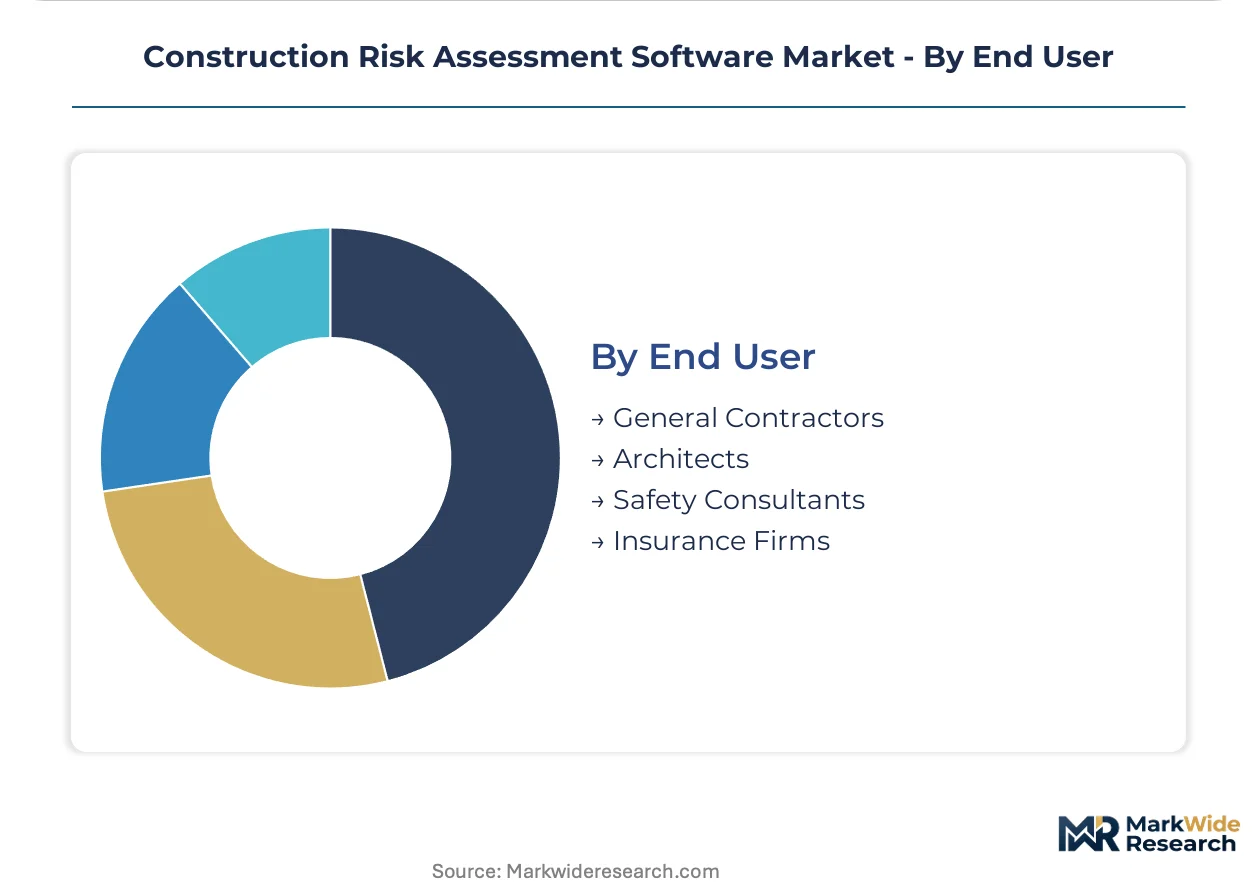
End User:
Customer type determines sales cycle length and integration complexity: general contractors drive volume, while insurance firms and safety consultants shape product roadmaps through outcome-based contracting.
- General Contractors:Primary procurement decision-makers with project-budget authority over safety technology spend. United States federal infrastructure contractors under Davis-Bacon compliance requirements represent concentrated demand.
- Architects:Design-phase influencers specifying risk assessment requirements in contractor RFPs. United Kingdom practices responding to post-Grenfell building safety reforms are embedding predictive analytics clauses in documentation.
- Safety Consultants:Independent advisors recommending platform selections to multiple contractor clients. Australian and Canadian consultants leverage cross-client benchmarking to negotiate vendor discounts.
- Insurance Firms:Risk carriers and brokers deploying software to monitor insured contractor portfolios. Lloyd's of London syndicates and United States excess liability underwriters are piloting real-time score-based pricing models.
General Contractors dominate transaction volume. Insurance Firms represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure appropriations and contractor liability standards are redrawing procurement maps for construction risk assessment platforms. National safety regulations now function as market gatekeepers, determining which vendors qualify for project bids.
United States
Commercial real estate developers and federal infrastructure contractors drive software investment through Davis-Bacon compliance requirements and OSHA recordkeeping mandates. The Department of Transportation mandates digital safety documentation for transportation megaprojects. Texas and California energy construction clusters deploy edge-based hazard detection for heavy machinery collision avoidance.
Germany
Industrial construction and energy infrastructure projects prioritize ISO 45001-certified platforms for occupational health management validation. The EU AI Act constrains algorithmic severity scoring systems with mandatory transparency disclosures. Bavaria and North Rhine-Westphalia manufacturing corridors source compliance management modules for audit-ready documentation.
United Kingdom
Post-Grenfell building safety reforms embed predictive analytics requirements in contractor RFPs issued by London architectural practices. The Health and Safety Executive maintains stringent incident reporting standards that resist platform switching. Southeast England commercial development clusters procure hazard identification solutions with computer vision capabilities.
India
National highway expansion and urban metro buildouts under BIS construction codes create first-mover opportunities for cloud-based platforms. The Bureau of Indian Standards mandates safety documentation protocols that favor subscription-based compliance tools. Maharashtra and Gujarat infrastructure corridors deploy localized safety training modules for workforce digital literacy programs.
Australia
Mining and heavy construction operations drive demand for real-time site monitoring with wearable sensor integration. State-level work health and safety regulators enforce incident investigation documentation standards. Western Australia and Queensland resource extraction clusters invest in edge computing architectures for sub-second hazard alerts.
Construction Risk Assessment Software Market Competitive Landscape
Player mix skews toward established construction technology platforms with cloud-native heritage and project management integration capabilities. Market structure concentrates around vendors with existing contractor workflow penetration rather than pure-play safety specialists. Two strategic archetypes dominate: BIM-integrated design-to-construction platforms and infrastructure-scale geospatial modeling specialists. Competitive moves center on API ecosystem expansion and outcome-based insurance partnerships.
Within the cloud-native platform tier, Procore Technologies and Autodesk exemplify vendors leveraging existing contractor relationships to anchor risk modules within operational workflows. Bentley Systems occupies a specialized position serving transportation and energy megaprojects where geospatial precision governs safety outcomes. Oracle represents the enterprise software archetype extending ERP infrastructure into compliance documentation and regulatory reporting functions.
| Leading Market Players |
|---|
| Procore Technologies |
| Autodesk |
| Oracle |
| Trimble |
| Bentley Systems |
| SafetyCulture |
| HammerTech Global |
| Novade Solutions |
| SiteDocs Safety |
| Others |
Pricing and Supply Chain Analysis
Platform scale economies in cloud-native SaaS architectures compress marginal delivery costs for vendors serving mid-sized contractor segments, concentrating pricing power among established players with existing workflow integration while forcing pure-play specialists toward niche premium positioning or acquisition exits.
Pricing Analysis
Certification level (ISO 45001/OSHA compliance-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels anchors subscription fees to sensor integration depth and machine learning sophistication. Cost compression in the mid-market tier is intensifying because general contractors now expect bundled regulatory update deployment and audit-ready reporting without module surcharges. Federal infrastructure contractors under Davis-Bacon requirements demonstrate lowest price sensitivity due to compliance documentation mandates, while India's emerging contractor base drives standard-tier volume with heavy discounting.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-based platform delivery, with vendor-managed infrastructure eliminating client-side hardware inventory needs. Software development capacity concentrates in the United States, Ireland, and India, with machine learning engineering talent commanding premium compensation in all three markets. The supply chain draws from specialized sensor hardware manufacturers in Taiwan and Germany for biometric hardhats and location-aware vests. Single-source vulnerability in edge-computing chipsets sourced from Taiwan presents structural risk for real-time hazard alert systems. Distribution runs through vendor direct sales teams and construction technology distributors, with systems integrators handling on-premise deployments at defense and critical infrastructure contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction risk assessment software sits in early-cycle expansion as federal infrastructure spending and ISO 45001 procurement mandates accelerate first-time adoption among mid-tier contractors previously reliant on manual documentation.
For Market Incumbents: Shield installed base retention by embedding risk modules deeper within existing project management workflows before competitors achieve API parity. Prioritize backward integration into sensor hardware partnerships to control data pipeline quality and reduce third-party dependency exposure. Defensive certification investment in EU AI Act algorithmic transparency compliance preserves European market access against regulatory fragmentation. For New Entrants and Emerging Players: Lead with computer vision-native hazard identification targeting India's national highway expansion under BIS construction codes, where localized safety training content gaps create first-mover advantage. White-space opportunity concentrates in edge-as-a-service subscriptions for tier-one contractors seeking sub-second collision avoidance without captive IT infrastructure. Go-to-market leverage through safety consultant channel partnerships accelerates cross-client benchmarking credibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with embedded compliance documentation workflows, suggesting superior cash-flow quality relative to perpetual-license legacy vendors. Long-term viability favors vendors with infrastructure-scale risk modeling capabilities serving transportation and energy megaprojects where geospatial precision governs safety outcomes. Acquisition target archetype: computer vision specialists with drone photogrammetry integration and established contractor pilot programs. Signal to watch: insurance-linked pricing model adoption rates among Lloyd's of London syndicates and United States excess liability underwriters.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding risk modules within existing BIM and ERP workflows reduces vendor switching and extends contract duration. |
| Acquisition of Specialist Firm | Computer vision and edge-computing acquisitions fill capability gaps for real-time hazard detection without greenfield development. |
| Strategic Partnership | Insurance carrier alliances enable usage-based premium pricing tied to platform-generated safety scores. |
| Product Launch | Heat stress modules with OSHA-compliant rest-break algorithms capture pre-emptive procurement ahead of final rule issuance. |
| Geographic Expansion | India infrastructure buildout under BIS codes creates first-mover positioning before domestic competitors consolidate. |
Research Methodology
Initial hypotheses were tested against primary input from construction technology procurement officers, safety directors at general contractors, platform engineers at cloud-native vendors, and insurance risk modelers, then refined through secondary validation against OSHA regulatory filings, ISO certification databases, federal infrastructure appropriations records, and construction industry trade association expenditure surveys. Bottom-up triangulation across deployment mode, solution capability, and end-user segments was cross-checked against top-down market sizing from vendor revenue disclosures and channel partner volume estimates.
Variance decomposition across the projection horizon isolates growth contributions from regulatory mandate acceleration, sensor hardware cost curves, and contractor digital literacy improvement. Segmentation dimensions modeled include deployment architecture, solution type, operational use case, and professional end user, with additional cross-cutting analysis by project scale tier and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to early-adopter penetration patterns and late-majority constraint factors. Industry-specific forecast inputs incorporate federal infrastructure spending authorization trajectories and EU AI Act implementation timelines.
Underlying assumptions cover OSHA rule finalization schedules, ISO 45001 certification penetration rates, and cloud infrastructure cost curves, with deviation risk concentrated in algorithmic transparency compliance costs in European jurisdictions and workforce training timeline slippage. Revision becomes warranted when federal infrastructure appropriation levels or contractor liability insurance premium structures cross thresholds that alter platform ROI calculations for mid-market buyers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
India Construction Market
Construction and Engineering
Sand Washing Machine Market
Construction and Engineering
Dredging Market
Construction and Engineering
Risers Market
Construction and Engineering
Blanking Machine Market
Construction and Engineering
Global Elevator Market
Construction and Engineering
Industrial Maintenance Products Market
Construction and Engineering
Italy HVAC Market
Construction and Engineering
Italy Ceramic Tiles Market
Construction and Engineering
CNC Lathe Machine Market
Construction and Engineering
North America Ceramic Tiles Market
Construction and Engineering
Vertical Baling Press Market
Construction and Engineering
Truck Loader Crane Market
Construction and Engineering
Wood Milling Machine Market
Construction and Engineering
Saudi Arabia Transportation Infrastructure Construction Market
Construction and Engineering
North and Latin America Weatherization Services Market