
 Blanking Machine Market | 2026-2036
Blanking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Blanking Machine Market Analysis
Aftermarket service revenue is fragmenting across the installed base as OEMs compete for long-term maintenance contracts. TRUMPF Group leverages its laser-integrated service architecture to capture recurring revenue from European automotive stampers. Schuler anchors high-tonnage mechanical press aftermarket programs through its global spare-parts logistics network. AMADA competes on retrofit CNC upgrades that extend legacy hydraulic blanking machine lifecycles.
A blanking machine is a metal-forming press that shears flat sheet or coil stock into predetermined shapes using hardened punch-and-die sets operating at forces from 30 to 3,000+ metric tons. Servo blanking machines now dominate new capital expenditure in automotive stamping for their programmable slide motion and 30% energy reduction over conventional mechanical drives. Hydraulic blanking machines retain share in heavy-gauge metal fabrication where variable stroke control accommodates thick-plate aerospace alloys. CNC technology leads programmable blanking installations as tier-one suppliers eliminate manual setup times.
OSHA lockout/tagout standards and EPA metalworking fluid emissions rules shape North American machine specifications and facility compliance costs. EU machinery directives under CE marking and F-Gas Regulation refrigerant constraints on hydraulic cooling systems drive European OEM design priorities. Stakeholders must weigh servo-electric capital premiums against decade-long energy savings as electricity tariffs diverge across manufacturing regions.
Market Dynamics
Servo-electric drive architecture is compressing the installed base of mechanical blanking lines as automotive stampers reconfigure capital allocation around programmable slide motion and energy benchmarking mandates.
Growth Catalysts
- EU Green Deal carbon benchmarks:German automotive OEMs are retrofitting stamping facilities with servo-electric blanking lines to meet binding emissions reduction targets for Scope 2 industrial electricity consumption.
- China's Yangtze River Delta cluster:Precision metal stamping corridors in Shanghai, Suzhou, and Ningbo concentrate demand for high-speed CNC blanking machines serving electric vehicle battery enclosure production.
- METI energy-efficiency directives:Japanese metal formers are accelerating capital replacement cycles to comply with mandatory factory energy audits and equipment efficiency standards.
Market Restraints
- Copper and rare-earth magnet cost volatility:Servo motor supply chains face input price swings that compress OEM margin structures on long-lead capital equipment contracts.
- Hydraulic cooling system refrigerant constraints:EU F-Gas Regulation phase-down schedules are forcing premature obsolescence of legacy hydraulic blanking machine cooling architectures.
- Mechanical press substitution threat:High-speed progressive die systems are capturing thin-gauge automotive stamping applications that previously required dedicated blanking lines.
Strategic Opportunities
- India's PLI scheme for automotive manufacturing:Tier-one suppliers are establishing greenfield stamping facilities eligible for production-linked incentives covering advanced servo press installations.
- Laser-blanking convergence:Fiber laser integration with mechanical blanking architectures enables near-net-shape production of high-strength aluminum alloys for EV body-in-white applications.
- Aftermarket service unbundling:Independent maintenance providers are capturing long-term service contracts from legacy equipment installed bases as OEMs prioritize new machine sales.
Industry Challenges
- Servo drive commissioning expertise scarcity:Field engineering talent capable of programming programmable slide motion profiles remains concentrated among European and Japanese OEM technical service teams.
- Legacy hydraulic system integration complexity:Retrofit CNC controls onto existing mechanical press architectures require custom mechanical linkages that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blanking Machine Market |
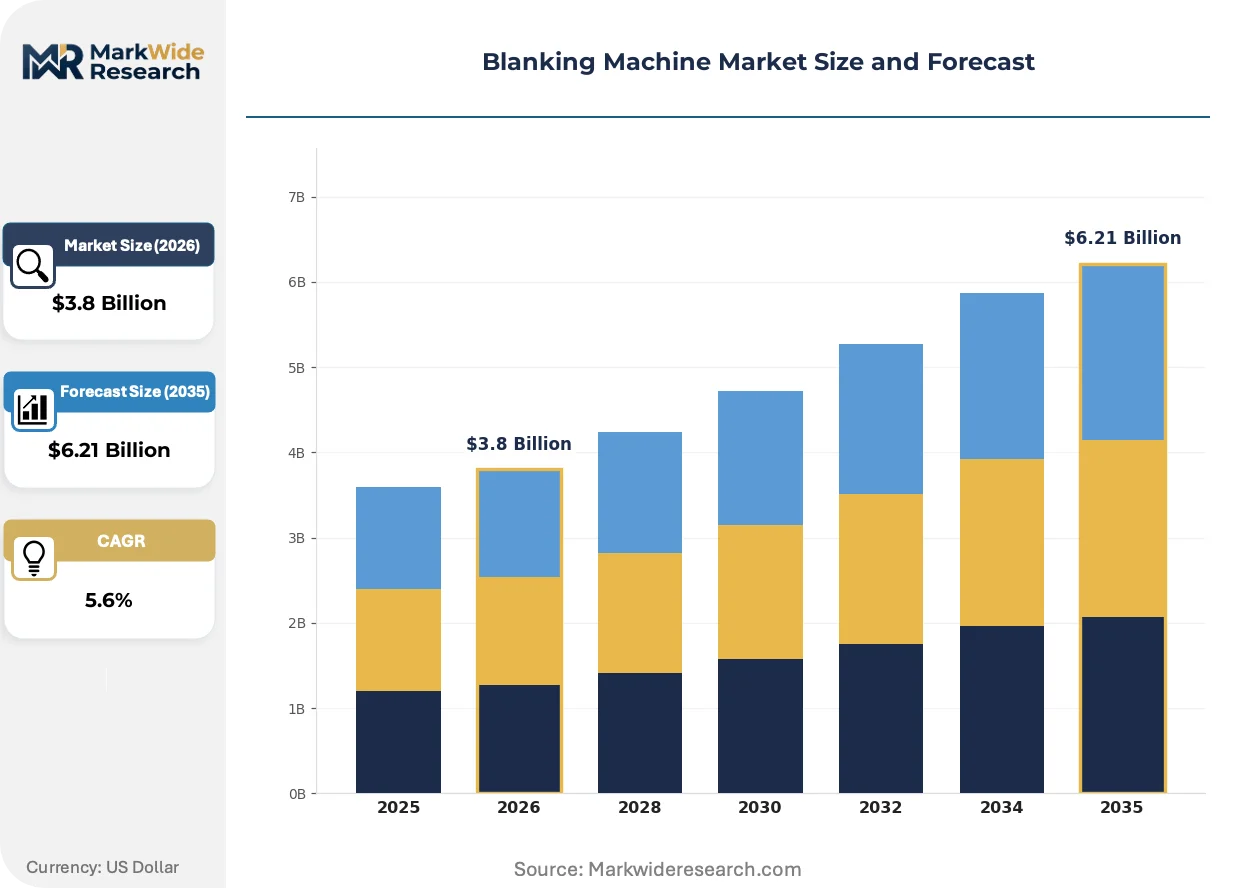
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Blanking Machines, Mechanical Blanking Machines, Pneumatic Blanking Machines, Servo Blanking Machines End User: Automotive, Aerospace, Electronics, Heavy Machinery Technology: CAM, CNC, Manual, Programmable Application: Metal Fabrication, Stamping, Assembly, Prototyping |
| Companies Covered | TRUMPF Group, Ueshima Seisakusho, AMADA, AUTOPRINT, Torontech Inc, Schuler, Sakamoto Zoki, Jinan Junao CNC Equipment, Komatsu Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blanking Machine Market Emerging Trajectories
Programmable motion control and closed-loop force monitoring are redefining blanking machine specifications as stampers prioritize part quality consistency over raw throughput metrics.
Direct-drive servo motor technology is migrating from niche high-precision applications to mainstream automotive blanking lines. Tier-one suppliers in Germany and Japan are specifying servo-electric architectures for new press shop investments. The technology is migrating from mechanical flywheel drives by eliminating energy storage inertia and enabling stroke-specific force profiling.
EPA metalworking fluid emissions rules are tightening permissible volatile organic compound thresholds for stamping lubricant mist collection systems. North American facility operators must install upgraded ventilation and filtration infrastructure to maintain operating permits. Automotive stamping plants in Michigan and Ohio are retrofitting blanking lines with enclosed die enclosures and centralized fluid recovery systems.
Buyer procurement patterns are compressing equipment evaluation cycles as automotive platform launches accelerate. Tier-one metal stampers are consolidating supplier relationships around full-line press system integrators capable of delivering turnkey servo blanking cells. This concentration is most visible in China's Yangtze River Delta, where battery enclosure manufacturers are awarding multi-press contracts to single-source OEMs with localized service capabilities.
Blanking Machine Market Segmentation
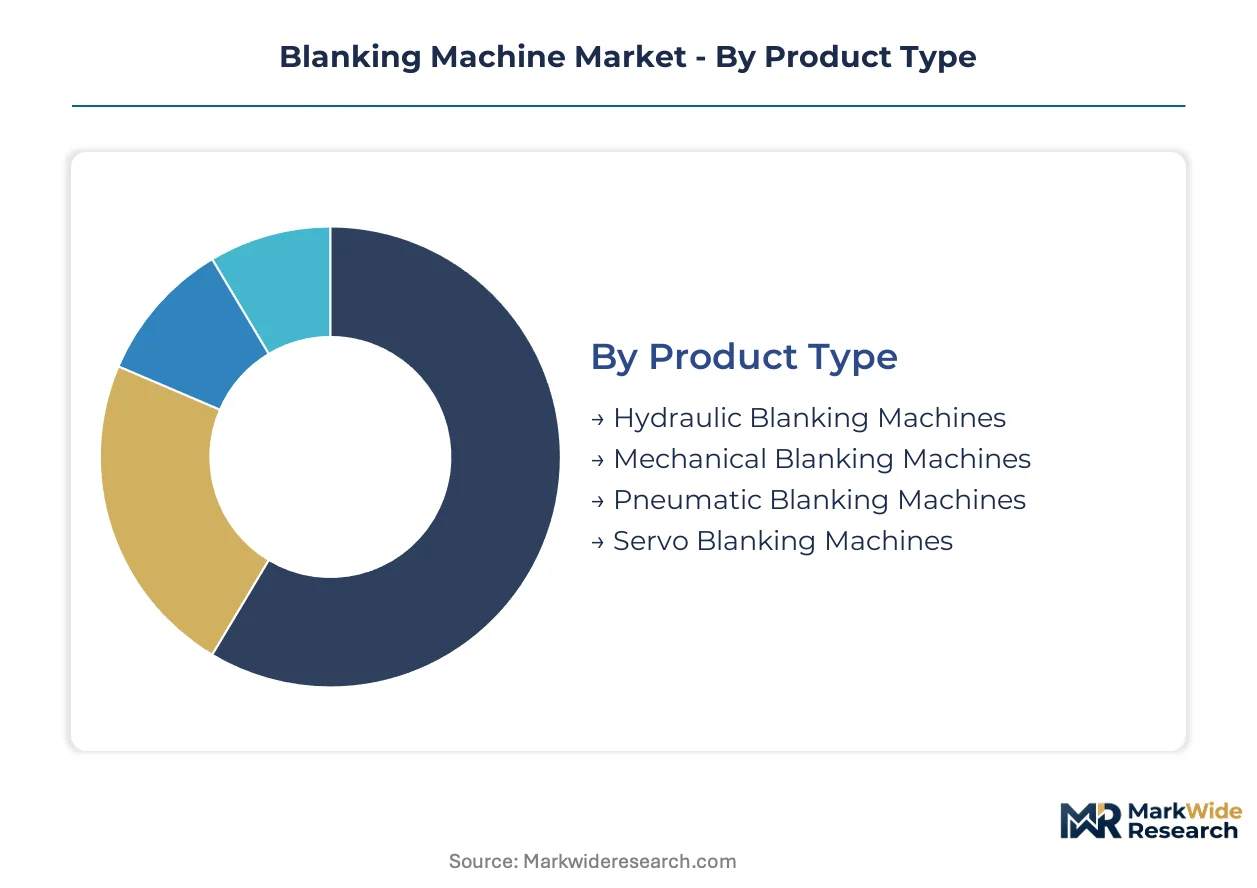
Blanking machine procurement patterns diverge sharply across technology tiers and end-use requirements. Servo-electric architectures command premium capital allocations in automotive stamping, while hydraulic systems retain installed-base dominance in heavy-gauge fabrication. Understanding these segment boundaries clarifies where OEMs compete for new machine sales versus aftermarket service capture.
Product Type:
Cost tier determines capital expenditure patterns and energy benchmarking compliance trajectories across installed-base renewal cycles.
- Servo Blanking Machines:Direct-drive servo motors eliminate flywheel inertia and enable stroke-specific force profiling with programmable slide motion. German automotive OEMs specify these architectures for new press shop investments to meet EU Green Deal carbon benchmarks for Scope 2 electricity consumption.
- Hydraulic Blanking Machines:Variable stroke control accommodates thick-plate aerospace alloys through Pascal pressure multiplication. EU F-Gas Regulation refrigerant constraints on cooling systems are forcing premature obsolescence of legacy hydraulic architectures across European metal formers.
- Mechanical Blanking Machines:Conventional flywheel drives retain share in high-volume thin-gauge stamping where fixed stroke rates optimize cycle economics.
- Pneumatic Blanking Machines:Compressed-air actuation serves low-tonnage prototyping and light-gauge electronics stamping with minimal capital outlay.
Servo-electric systems command the established base in automotive tier-one supplier facilities. The steepest expansion runs through servo architectures displacing mechanical flywheel drives.
End User:
Application-specific tolerance requirements and production volumes shape machine specification priorities across vertical demand clusters.
- Automotive:Battery enclosure production in China's Yangtze River Delta concentrates demand for high-speed CNC blanking machines with closed-loop force monitoring. Tier-one suppliers award multi-press contracts to single-source OEMs with localized service capabilities.
- Electronics:Miniaturized connector and shield stamping requires sub-millimeter die clearance control and rapid tool changeover protocols.
- Aerospace:Heavy-gauge titanium and aluminum alloys for structural components demand hydraulic variable-stroke control with thermal compensation.
- Heavy Machinery:Thick-plate structural steel fabrication tolerates lower precision tolerances in favor of raw tonnage capacity and durability.
Automotive commands the established base through platform launch acceleration and EV body-in-white restructuring. The steepest expansion runs through electronics as connector miniaturization intensifies precision requirements.
Technology:
Control architecture maturity determines setup automation levels and integration complexity with upstream coil handling systems.
- CNC:Computer numerical control eliminates manual setup times through stored die programs and automated slide positioning. China's precision metal stamping corridors specify CNC for electric vehicle battery enclosure production.
- Programmable:Servo-driven programmable motion enables stroke-specific velocity profiling for high-strength aluminum forming.
- CAM:Mechanical cam-driven sequences retain cost advantage in fixed-operation high-volume stamping with minimal product changeover.
- Manual:Hand-fed operation persists in prototype shops and specialty fabrication with batch sizes below economic automation thresholds.
CNC commands the established base through tier-one supplier consolidation around full-line system integrators. The steepest expansion runs through programmable architectures as servo drive commissioning expertise concentrates among European and Japanese OEM technical service teams.
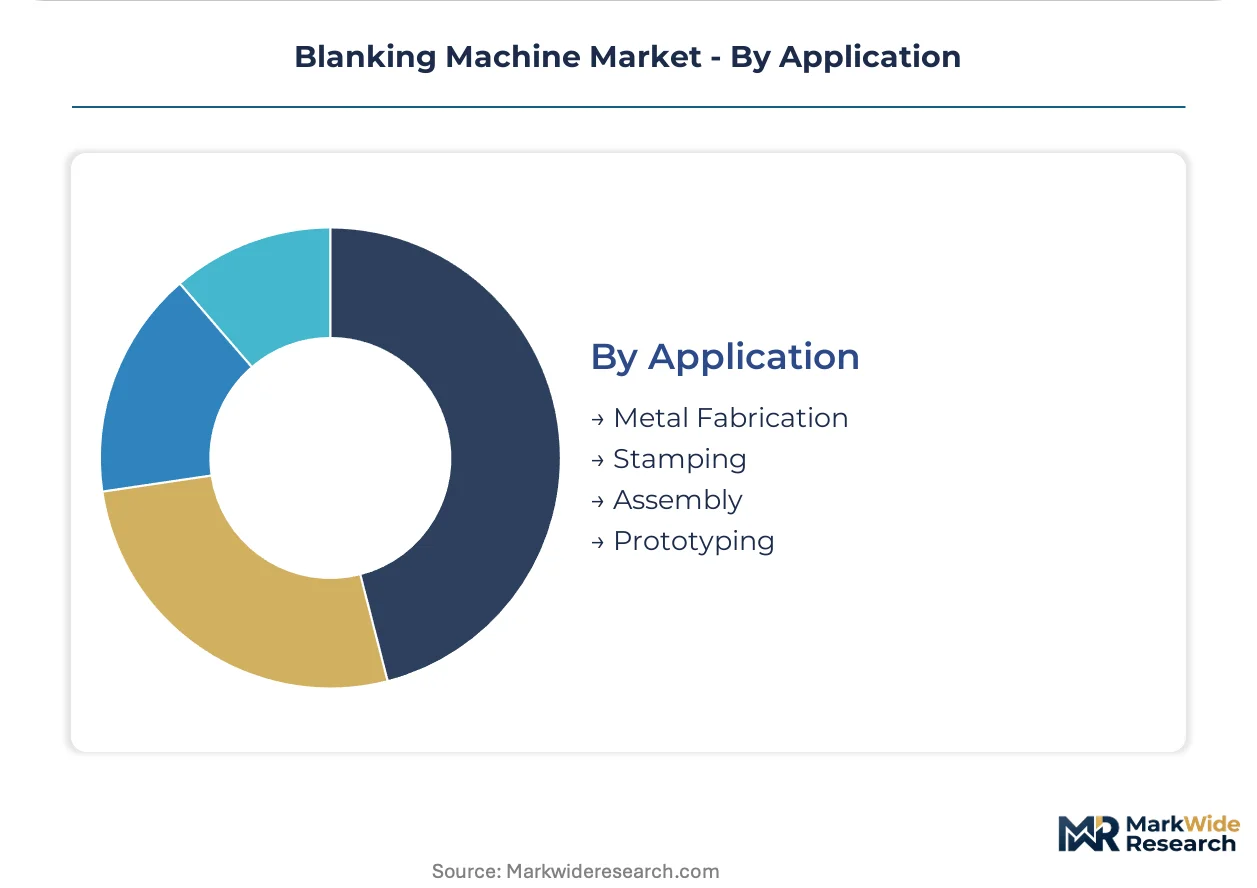
Application:
Process stage integration determines throughput metrics versus quality consistency trade-offs in production line configuration.
- Stamping:High-speed blanking into predetermined shapes using hardened punch-and-die sets operating at forces from 30 to 3,000+ metric tons. METI energy-efficiency directives in Japan accelerate capital replacement cycles for stamping equipment.
- Metal Fabrication:Job-shop flexibility for variable batch sizes and custom geometries with rapid die changeover systems.
- Assembly:Integration with robotic part handling and downstream welding cells in turnkey press line configurations.
- Prototyping:Short-run validation of die designs before hard tooling commitment with minimized setup overhead.
Stamping commands the established base through automotive platform volume concentration. The steepest expansion runs through metal fabrication as India's PLI scheme for automotive manufacturing incentivizes greenfield stamping facility establishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity, prioritizing servo-electric precision for regulatory compliance. Chinese manufacturers in the Yangtze River Delta cluster demonstrate moderate elasticity, trading capital premiums for localized service networks. Indian procurement shows highest sensitivity, where PLI scheme subsidies offset upfront equipment costs.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive servo-electric blanking line procurement for EU Green Deal Scope 2 compliance. ECHA REACH restrictions on metalworking fluid formulations elevate enclosed die enclosure specifications. The Baden-Württemberg precision metal stamping corridor concentrates battery enclosure production investments from tier-one suppliers.
Japan
METI energy-efficiency directives compress capital replacement cycles for mechanical press fleets in Toyota City and Yokohama. JIS standards on industrial equipment efficiency ratings mandate factory energy audit compliance. The Chubu region around Nagoya anchors high-speed CNC blanking demand for electric vehicle motor core laminations.
China
Dual carbon goals from MEE accelerate servo press adoption in Shanghai and Suzhou precision stamping corridors. GB standards on industrial electricity consumption benchmarking constrain facility expansion permits. The Yangtze River Delta cluster concentrates battery enclosure manufacturing for domestic EV OEMs.
United States
OSHA lockout/tagout enforcement elevates safety system specifications in Michigan and Ohio automotive stamping plants. EPA metalworking fluid emissions rules mandate upgraded ventilation infrastructure for operating permit renewal. The Southeast manufacturing belt attracts greenfield servo press investments from battery enclosure suppliers.
India
PLI scheme production-linked incentives cover advanced servo press installations for automotive tier-one suppliers in Pune and Chennai. BIS certification requirements for industrial machinery imports extend equipment qualification timelines. The Gujarat industrial corridor hosts greenfield stamping facilities targeting export-oriented component production.
Blanking Machine Market Vendor Landscape
Capability concentration sits with European and Japanese OEMs possessing servo drive commissioning expertise; scale advantage sits with diversified industrial conglomerates serving multiple metal forming segments. The vendor base stratifies into three tiers: full-line system integrators delivering turnkey press cells, specialized servo technology developers, and regional fabricators competing on retrofit CNC upgrades. Consolidation pressures favor players with localized service architectures in China's Yangtze River Delta. Dominant competitive moves include strategic partnerships for laser-blanking convergence and geographic expansion through joint ventures in India's PLI-eligible zones.
Among German-based full-line integrators, Schuler occupies a position exemplifying high-tonnage mechanical press aftermarket capture through spare-parts logistics networks. TRUMPF Group represents the laser-integrated service architecture archetype, anchoring recurring revenue streams from European automotive stampers. Japanese specialists AMADA and Komatsu Industries Corporation sit within the precision servo technology tier, where programmable slide motion expertise concentrates among technical service teams.
| Leading Market Players |
|---|
| TRUMPF Group |
| Ueshima Seisakusho |
| AMADA |
| AUTOPRINT |
| Torontech Inc |
| Schuler |
| Sakamoto Zoki |
| Jinan Junao CNC Equipment |
| Komatsu Industries Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta industrial cluster concentrates servo-electric blanking machine capacity for China's electric vehicle battery enclosure manufacturers, concentrating pricing power among full-line system integrators with localized service architectures. OEM procurement teams in this corridor negotiate multi-press contracts where after-sales service bundling commands premium capital allocations over standalone equipment sales.
Pricing Analysis
Aftermarket service contracts drive lifetime value capture across the installed base as OEMs compete for long-term maintenance revenue. Three-tier pricing structure across premium servo-electric architectures, standard mechanical retrofits, and economy hydraulic legacy systems reflects certification grade and localized service availability. Pricing pressure stems from copper and rare-earth magnet cost volatility compressing margin structures on long-lead capital equipment. Tier-one automotive suppliers in Germany and Japan exhibit lowest price elasticity, prioritizing programmable slide motion precision, while Indian PLI-scheme beneficiaries demonstrate highest sensitivity where subsidies offset upfront equipment costs.
Supply Chain Analysis
Copper winding feedstock and rare-earth permanent magnet supply chains draw from China, Japan, and Germany, concentrating upstream dependencies for servo motor manufacturing. Critical inputs include precision-machined die sets, CNC control systems, and hydraulic cooling system components. Single-source vulnerability in rare-earth magnet processing creates exposure to export restriction shocks from dominant suppliers. Distribution runs through direct OEM sales teams for large automotive tier-one accounts and regional distributor networks serving job-shop metal fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment in EU Green Deal carbon benchmarking and METI energy-efficiency directives creates switching costs for automotive stampers locked into approved OEM service networks.
For Market Incumbents: Insulate installed-base positions by deepening spare-parts logistics networks in China's Yangtze River Delta and capturing retrofit CNC upgrade contracts for legacy hydraulic architectures. Threats from high-speed progressive die substitution in thin-gauge automotive applications require countering through laser-blanking convergence investments. Vertical integration into servo drive commissioning expertise pools defends against independent maintenance provider encroachment.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-eligible greenfield stamping facilities where production-linked incentives reduce effective capital barriers for tier-one supplier procurement teams. The aftermarket service unbundling trend creates white-space for independent maintenance providers targeting legacy mechanical press fleets in North America. Go-to-market positioning around rapid servo drive commissioning capabilities addresses the field engineering talent scarcity constraining European and Japanese OEM expansion timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-line system integrators with localized service capabilities in high-growth EV battery enclosure corridors. Long-term viability rests on recurring revenue streams from multi-decade equipment lifecycles rather than cyclical new machine sales. Acquisition targets should demonstrate captive spare-parts logistics networks and programmable motion control IP. The signal to watch is accelerating consolidation around single-source OEM relationships in China's precision metal stamping corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Architecture Migration | Enables EU Green Deal Scope 2 compliance for German automotive OEM stamping facilities. |
| Aftermarket Service Network Expansion | Captures recurring revenue from legacy installed bases as OEMs prioritize new machine sales. |
| Laser-Blanking Technology Convergence | Facilitates near-net-shape production of high-strength aluminum alloys for EV body-in-white applications. |
| Localized Manufacturing Footprint | Reduces qualification timelines for BIS certification requirements in India's PLI scheme zones. |
| Retrofit CNC Control Integration | Extends legacy hydraulic machine lifecycles while addressing EPA metalworking fluid emissions rules. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with plant engineers, aftermarket service heads, OEM procurement teams, and Tier 1 supplier stamping directors; and secondary validation through customs trade data, SEC equipment manufacturer filings, METI factory energy audit disclosures, and EU ETS industrial emissions registries. Bottom-up equipment shipment tallies by technology tier and top-down industrial capital expenditure surveys were triangulated to anchor market sizing.
Forecast inputs span servo-electric versus hydraulic versus mechanical technology mix, automotive platform launch cadence by OEM, and regional electricity tariff trajectories affecting energy benchmarking compliance economics. Segmentation modeling covers product architecture, end-use vertical, control technology maturity, and process stage integration. CAGRs were derived from installed-base renewal cycle analysis and regulatory mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, rare-earth commodity indices, or automotive production volumes would shift the trajectory. Forecasts reflect documented assumptions regarding EU F-Gas Regulation phase-down schedules and China dual carbon goal enforcement intensity. Cross-checking against IHS Markit vehicle production databases and national industrial energy consumption statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rotary Dryers Market
Construction Equipment
Sawmill Machinery Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Mini Excavators Market
Construction Equipment
Mobile Light Tower Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Static Crane Market