
 Power Generator for Military Market | 2026-2036
Power Generator for Military Market Size, Share, and Industry Trends Forecast 2026-2036
Power Generator for Military Market Outlook
Market Context
EPA Tier 4 Final emissions compliance is broadening the cost-of-entry calculus for diesel generator suppliers serving military contracts. Caterpillar Inc. leverages its integrated engine-electronics architecture to navigate certification complexity without external component reliance. Cummins Inc. sustains competitive position through captive production of aftertreatment systems that reduce field failure rates in austere environments. Rolls-Royce Holdings plc anchors its military portfolio on aero-derivative gas turbine expertise that commands premium positioning for naval and expeditionary power applications.
Technical Definition and Segment Structure
A power generator for military is an engineered electromechanical system designed to convert chemical or kinetic energy into regulated electrical output under extreme environmental conditions, typically operating across temperature ranges from negative 50 to positive 125 degrees Celsius and meeting MIL-STD-810 shock and vibration thresholds. Its primary purpose is to deliver assured power for command centers, weapon systems, medical facilities, and communications arrays where grid connectivity is absent or compromised. Diesel generators retain dominant installed base share across fixed military installations, though hybrid generators incorporating battery storage and photovoltaic input represent the fastest-expanding procurement category as forces reduce liquid fuel logistics burdens. Portable installations command attention from special operations and rapid response units, while fixed and mobile configurations serve enduring base infrastructure and maneuver brigades respectively.
Regulatory Framework and Outlook
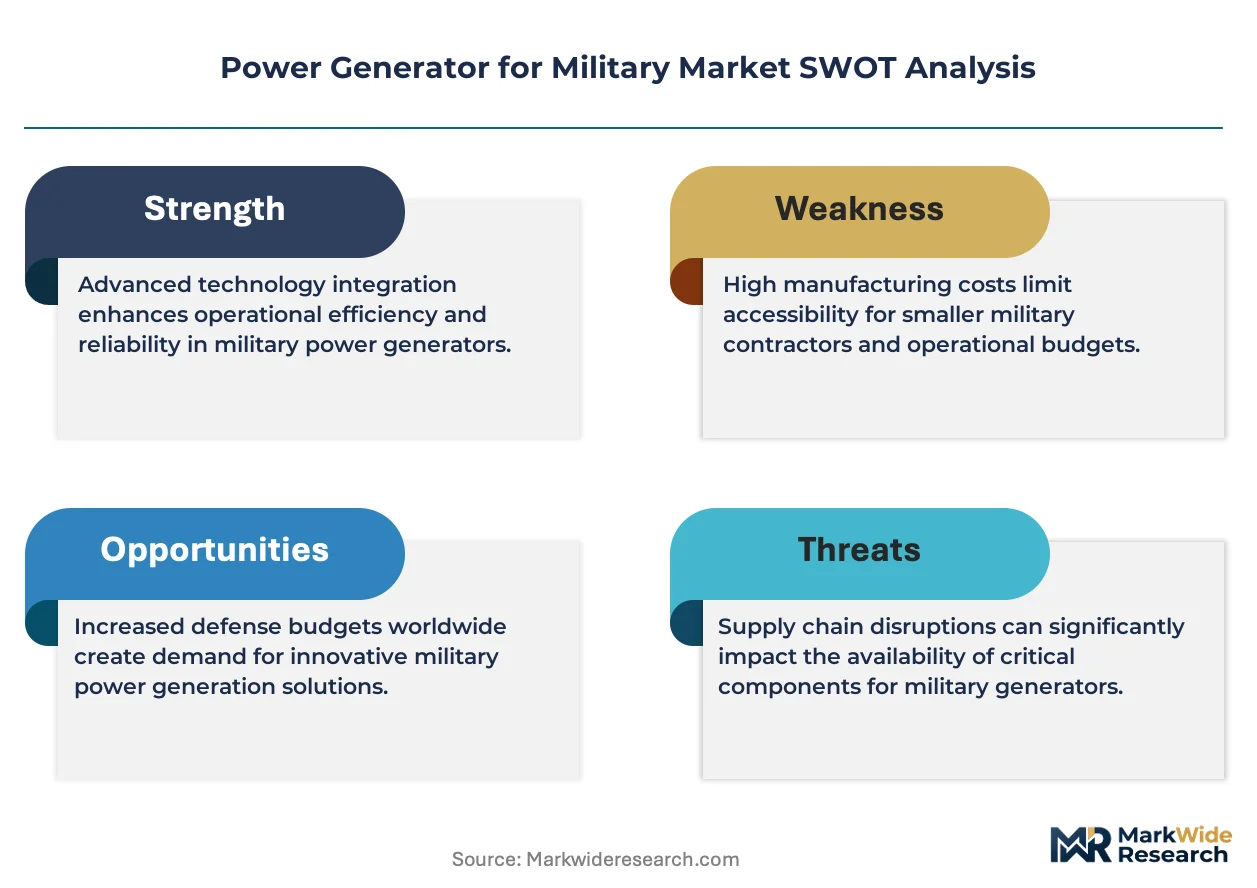
The US EPA, the EU F-Gas Regulation, and NATO standardization agreements collectively shape product design mandates, emissions thresholds, and cross-border interoperability requirements that determine market access for military power equipment. The EU Green Deal's defense procurement implications are pressing European suppliers toward lower-carbon generator architectures even in tactical applications. Stakeholders must monitor how emerging battlefield electrification requirements for directed energy weapons and unmanned systems reshape capacity specifications and duty cycle expectations across all generator categories.
Market Dynamics
The US Department of Defense's tactical microgrid mandate is forcing generator architectures toward hybrid diesel-battery configurations that reduce fuel logistics exposure while maintaining blackout-proof power assurance for expeditionary operations.
Growth Catalysts
- EPA Tier 4 Final compliance pressure:Emissions thresholds for diesel prime movers are accelerating aftertreatment system upgrades across military generator fleets, creating replacement demand for legacy non-compliant units.
- Expeditionary base electrification:Contingency response budgets in the United States are funding deployable power systems that operate independently of host-nation grid infrastructure during rapid force projection missions.
- Directed energy weapons proliferation:Pulsed-power requirements for laser and microwave armaments are reshaping generator capacity specifications toward megawatt-class mobile platforms with specialized duty cycles.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet dependencies for high-efficiency generator rotors create exposure to processing bottlenecks concentrated in single-source jurisdictions.
- Steel alloy price volatility:Lamination-grade electrical steel and rotor forging materials face input cost swings that compress fixed-price contract margins for long-lead military procurements.
- EU F-Gas Regulation friction:Fluorinated gas restrictions on high-voltage switchgear cooling systems complicate export certification for European defense contractors seeking NATO interoperability contracts.
Strategic Opportunities
- Australian northern territory basing:Rotational force agreements between Washington and Canberra are driving demand for tropicalized generator systems at expanded air-ground training complexes.
- Photovoltaic-diesel hybrid convergence:Solar array integration with tactical generators offers fuel reduction pathways for extended duration missions without compromising silent-watch capabilities.
- US Inflation Reduction Act domestic content:Clean energy manufacturing incentives are creating onshore assembly opportunities for battery-integrated military power systems previously sourced from overseas.
Industry Challenges
- MIL-STD-810H certification timelines:Shock and vibration qualification protocols for extreme temperature operation extend product development cycles and delay fielding schedules.
- Legacy 400Hz aircraft ground power integration:Harmonizing new generator architectures with existing airfield support equipment requires costly interface engineering and interoperability testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Generator for Military Market |
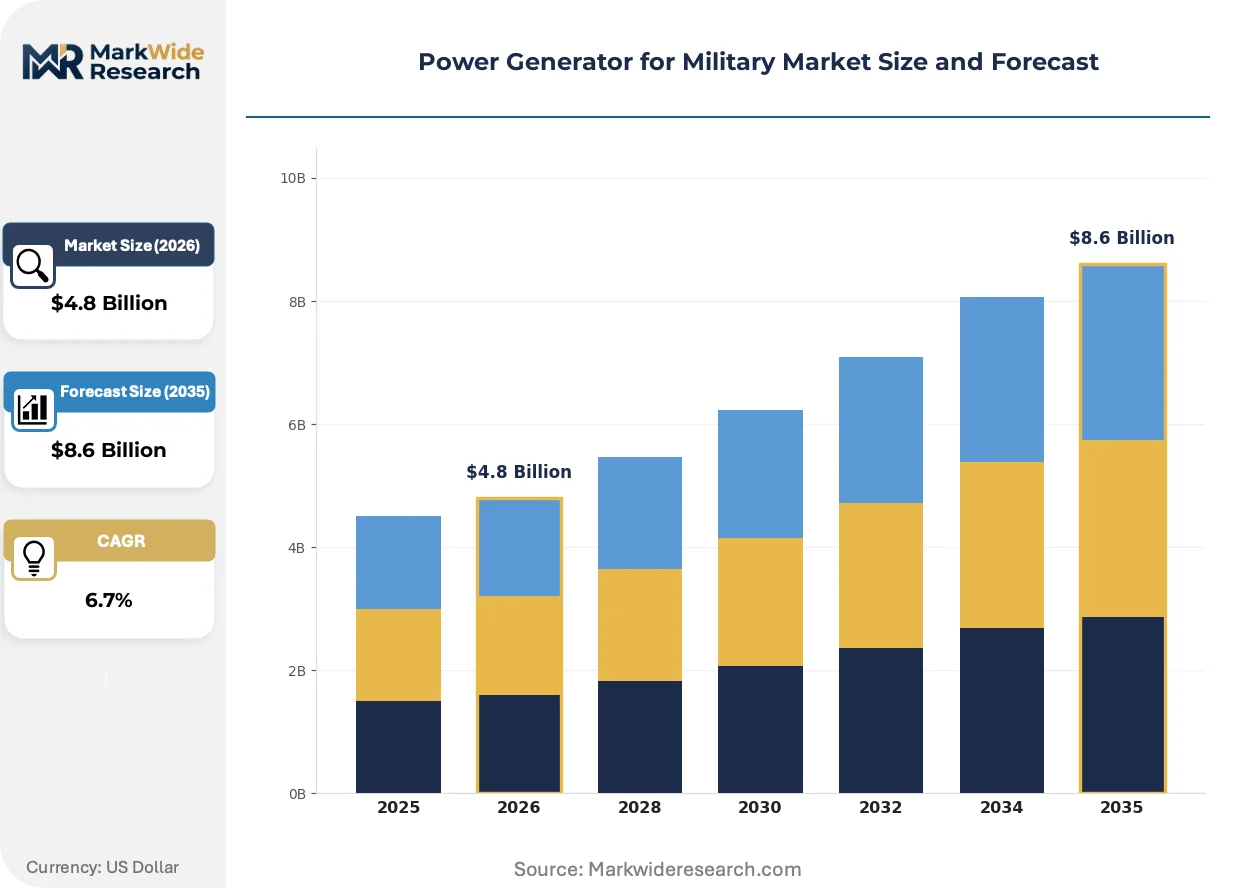
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Diesel Generator, Solar Generator, Hybrid Generator, Fuel Cell Generator Capacity: 10 kW, 25 kW, 50 kW, 100 kW Installation: Portable, Fixed, Mobile, Stationary End User: Military Bases, Field Operations, Naval Operations, Air Force Support |
| Companies Covered | Caterpillar Inc., Cummins Inc., Rolls-Royce Holdings plc, Kohler Co., HIMOINSA, Generac Power Systems, Atlas Copco, Kirloskar Oil Engines Ltd., Volvo Penta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Generator for Military Market Strategic Shifts
Tactical power generation is fragmenting from centralized bulk supply toward distributed node architectures that prioritize survivability and reduced signature over raw output capacity. This shift is compressing traditional generator sizing conventions and elevating control system sophistication.
Containerized battery energy storage systems paired with small-footprint diesel prime movers are decentralizing power distribution at forward operating bases. Marine expeditionary units are adopting these configurations for island-hopping campaigns where liquid fuel resupply faces contested logistics. The technology is decentralizing commanders' reliance on single-point generator farms that present high-value targeting signatures.
EU Green Deal defense procurement guidelines are mandating lifecycle carbon assessments for military equipment acquisitions. European defense ministries are embedding these requirements into tender specifications ahead of NATO standardization. French and German land forces are responding with hybrid generator pilot programs that demonstrate operational viability while satisfying Brussels sustainability criteria.
Program-of-record contracting is fragmenting into multiple-award indefinite-delivery vehicles that accelerate technology refresh cycles. The US Army's tactical power program exemplifies this shift, with special operations units now accessing developmental systems through rapid prototyping pathways. Poland and Romania represent the most visible European adopters of this accelerated acquisition model for border defense infrastructure.
Power Generator for Military Market Segmentation
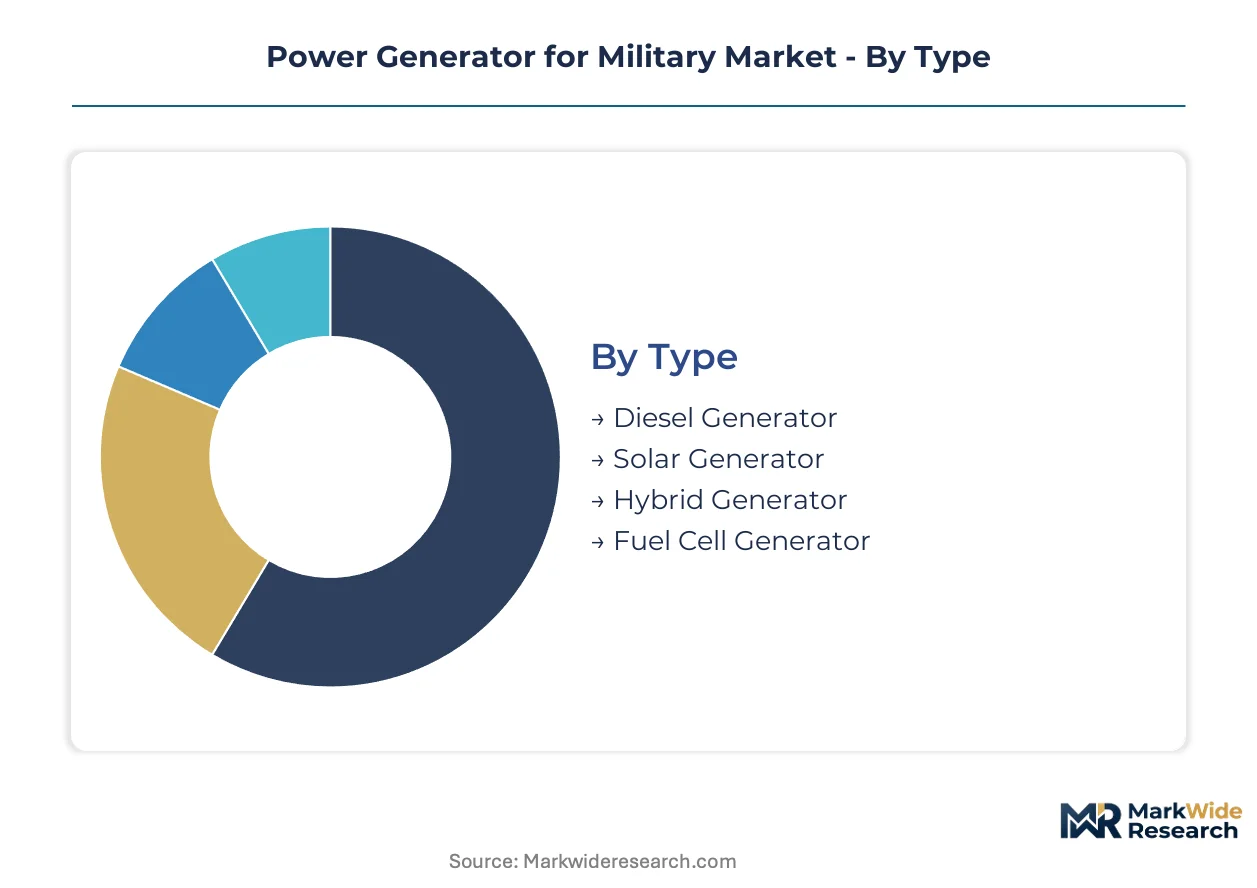
Military power generation procurement splits across four distinct axes that determine equipment specifications, logistics requirements, and contract award criteria. Each segmentation layer reflects divergent capital commitments, operational tempos, and regulatory exposure that shape supplier positioning and buyer decision frameworks.
Type:
Capital-intensity varies dramatically across prime mover technologies, with fuel cell architectures demanding the highest upfront engineering investment while diesel platforms leverage mature manufacturing scale.
- Diesel Generator:Compression-ignition prime movers with integrated aftertreatment systems dominate fixed installations and heavy maneuver formations. The US Army's contingency response budgets sustain replacement cycles for legacy non-EPA Tier 4 Final fleets at CONUS and OCONUS bases.
- Hybrid Generator:Diesel-battery architectures with photovoltaic input capability are gaining procurement traction as expeditionary forces prioritize fuel logistics reduction. Marine expeditionary units in the Pacific are piloting these configurations for island-hopping campaigns with contested resupply lines.
- Solar Generator:Deployable photovoltaic arrays with integrated inverters serve silent-watch applications and forward observation posts where acoustic signature control is paramount.
- Fuel Cell Generator:Proton-exchange membrane systems with hydrogen or methanol reformers offer zero-emission operation for enclosed spaces and signature-sensitive missions.
Most installed capacity flows through Diesel Generator. Expansion is steepest in Hybrid Generator.
Capacity:
Power output tiers align with mission duration, equipment load profiles, and transportability constraints that differentiate tactical from operational-level energy requirements.
- 10 kW:Man-portable or light-vehicle-towable units power squad-level communications and medical stabilization points. Special operations forces in the United States drive procurement for rapid infiltration missions.
- 25 kW:Trailer-mounted systems support platoon command posts and small radar installations with moderate duty cycles. Australian northern territory basing agreements are expanding tropicalized orders for rotational training infrastructure.
- 50 kW:Skid-mounted or vehicle-integrated platforms serve company-level operations centers and counter-UAS systems. Polish border defense modernization programs are accelerating fixed-site deployments.
- 100 kW:Containerized or heavy-truck-mounted generators anchor battalion headquarters and expeditionary base clusters. Directed energy weapons testing is reshaping duty cycle specifications for this tier.
Volume concentrates at 25 kW and 50 kW for general-purpose field deployment. Procurement velocity is climbing fastest at 100 kW as pulsed-power weapon integration advances.
Installation:
Physical configuration determines mobility class, setup time, and vulnerability profile against kinetic and electronic targeting.
- Portable:Disaggregated man-pack or hand-cart systems under 500 pounds enable special operations detachments and forward air controllers to establish power independence within minutes of landing zone clearance.
- Mobile:Vehicle-integrated or towed platforms accompany maneuver brigades during offensive operations and reposition within hours to avoid counter-battery fire.
- Fixed:Permanent or semi-permanent installations at enduring bases feature hardened enclosures and grid-intertie capability for peacetime utility cost management.
- Stationary:Containerized or shelterized systems designed for rapid emplacement but not frequent relocation serve intermediate-duration deployments and humanitarian assistance missions.
Fixed installations carry the largest cumulative megawatt footprint. Mobile configurations are gaining share as distributed tactical microgrids replace centralized generator farms.
End User:
Service branch and operational context dictate environmental qualification levels, interoperability requirements, and fuel standardization priorities.
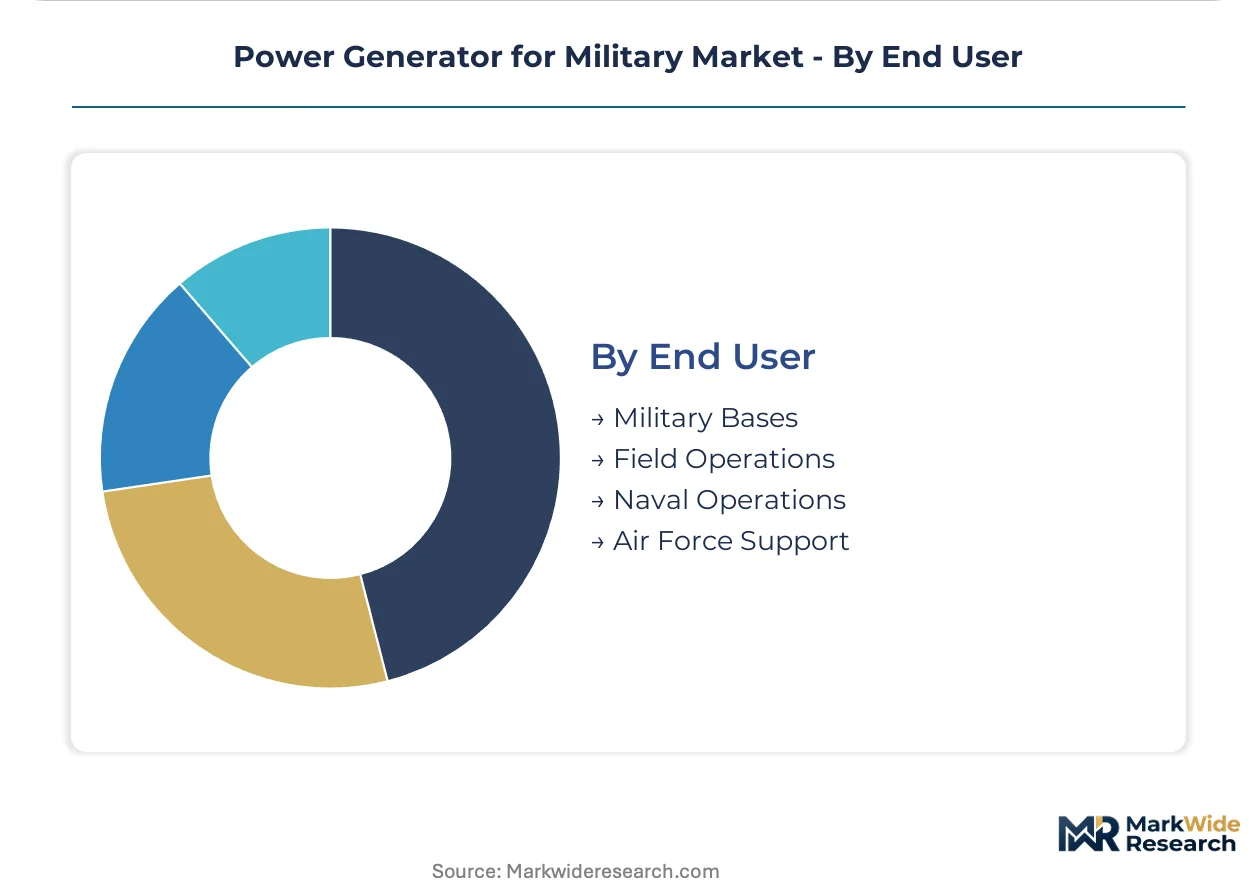
- Field Operations:Expeditionary ground forces require rapid-deployment power systems with MIL-STD-810H shock and vibration certification for austere terrain. US Indo-Pacific Command contingency planning is expanding tropicalized and cold-weather procurement.
- Military Bases:Enduring installations prioritize efficiency, emissions compliance, and grid resilience through hybrid microgrids. EPA Tier 4 Final mandates are accelerating replacement demand at CONUS facilities.
- Naval Operations:Shipboard and expeditionary maritime units demand salt-fog corrosion resistance, compact footprints, and electromagnetic compatibility with combat systems. Amphibious ready groups specify containerized battery-diesel hybrids for shore power.
- Air Force Support:Flightline ground power and airbase infrastructure require 400Hz output compatibility and rapid spool-up for aircraft engine starting. Legacy 400Hz integration constraints complicate new generator fielding.
Field Operations absorb the highest unit volume for deployable systems. Naval Operations are expanding most quickly as distributed maritime operations and island defense concepts mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Military power generator manufacturing traces its industrial lineage to World War II-era engine foundries in the United States, where Caterpillar and Cummins first scaled diesel-electric systems for armored vehicle and base power applications. This heritage established the technical standards and supply chain infrastructure that continue to dominate global procurement patterns.
United States
Pentagon contingency response budgets and EPA Tier 4 Final compliance mandates drive replacement cycles for legacy generator fleets at CONUS and OCONUS installations. The Department of Defense's tactical microgrid initiative is reshaping specifications toward hybrid diesel-battery architectures. Industrial concentration clusters around Peoria, Illinois, and Columbus, Indiana, where integrated engine-electronics manufacturing sustains prime contractor ecosystems.
Germany
Bundeswehr expeditionary commitments and NATO interoperability requirements sustain demand for containerized power systems compatible with allied force integration. The EU Green Deal's defense procurement implications are pressing the Ministry of Defence toward lifecycle carbon assessments in tender specifications. Bavaria-based defense contractors are piloting hybrid generator programs to satisfy Brussels sustainability criteria while maintaining field reliability.
United Kingdom
Royal Navy distributed maritime operations and island defense concepts are accelerating procurement of salt-fog-resistant containerized systems for amphibious ready groups. Ministry of Defence procurement guidelines emphasize electromagnetic compatibility with combat systems integration. Industrial activity concentrates in Bristol and the Midlands, where aero-derivative gas turbine expertise anchors naval power generation supply chains.
Australia
Rotational force agreements with Washington are driving tropicalized generator demand at expanded Northern Territory air-ground training complexes. The country's national defense procurement regulator is embedding resilience requirements into contingency infrastructure specifications. Darwin and Townsville host the primary concentration of depot-level maintenance capacity for Indo-Pacific expeditionary power systems.
Poland
Border defense modernization programs are accelerating fixed-site deployments of 50 kW-class skid-mounted generators for counter-UAS and surveillance infrastructure. NATO standardization agreements shape cross-border interoperability requirements for equipment acquisitions. Industrial clusters in Warsaw and the Silesian region are developing rapid-prototyping pathways for accelerated acquisition models.
Power Generator for Military Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive engine manufacturing and integrated aftertreatment capabilities. Market concentration reflects high barriers to EPA Tier 4 Final certification and MIL-STD-810H qualification protocols that extend product development cycles. Three archetypes dominate: integrated prime mover manufacturers, specialist generator set assemblers, and aero-derivative turbine specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for hybrid architecture transitions.
Among integrated engine-electronics manufacturers, Caterpillar Inc., Cummins Inc., and Rolls-Royce Holdings plc occupy positions that exemplify divergent technical specializations. Caterpillar represents the construction-industrial conglomerate archetype with heritage manufacturing scale. Cummins sits within the dedicated engine manufacturer tier emphasizing captive aftertreatment production. Rolls-Royce anchors the aero-derivative specialist position leveraging gas turbine expertise for premium naval and expeditionary applications.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Rolls-Royce Holdings plc |
| Kohler Co. |
| HIMOINSA |
| Generac Power Systems |
| Atlas Copco |
| Kirloskar Oil Engines Ltd. |
| Volvo Penta |
| Others |
Value Chain & Pricing Dynamics
Hybrid diesel-battery architecture adoption is compressing cost structures for traditional prime mover suppliers while concentrating procurement leverage among integrated engine-electronics manufacturers with captive aftertreatment capabilities. EPA Tier 4 Final compliance investments and rare earth magnet dependencies are forcing tier-2 assemblers toward margin compression or exit.
Pricing Analysis
Turnkey installation contracts versus bare-unit procurement splits the pricing landscape, with bundled service agreements commanding premiums for expeditionary field support. Three-tier pricing structure across premium, standard, and economy levels reflects MIL-STD-810H certification grade, EPA compliance tier, and after-sales logistics coverage. Cost compression in standard-tier diesel platforms is intensifying because steel alloy and electrical steel lamination input volatility squeezes fixed-price military contract margins. Special operations units exhibit lowest price sensitivity due to mission-critical reliability requirements, while base infrastructure procurement shows highest sensitivity to lifecycle cost optimization.
Supply Chain Analysis
Skilled technician availability constraints in Peoria, Illinois, and Columbus, Indiana, are tightening production scheduling flexibility for integrated engine manufacturers serving Pentagon program-of-record contracts. Manufacturing gravity centers on the United States, Germany, and the United Kingdom, with each jurisdiction anchoring distinct prime mover specializations. Lamination-grade electrical steel, rare earth permanent magnets, and high-temperature alloys feed from concentrated mining and processing nodes. Single-source vulnerability in permanent magnet supply chains creates exposure to export restriction shocks. Distribution runs through defense prime contractors and authorized depot maintenance networks rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as expeditionary electrification mandates drive predictable replacement cycles for legacy generator fleets across NATO force structures.
For Market Incumbents: Deepen captive production of aftertreatment systems and battery integration modules to defend against specialist hybrid-architecture entrants. Secure EPA Tier 4 Final certification pipelines early to lock out tier-2 competitors lacking compliance engineering scale. Prioritize workforce retention in Peoria and Columbus manufacturing clusters where technician scarcity threatens production velocity. For New Entrants and Emerging Players: Enter via photovoltaic-diesel hybrid subsystems for Marine expeditionary unit island-hopping campaigns, where fuel logistics reduction mandates create white-space demand absent from established prime mover portfolios. Target Australian northern territory basing infrastructure for tropicalized generator deployments under Washington-Canberra rotational force agreements. Pursue rapid prototyping pathways through US Army special operations indefinite-delivery vehicles to bypass traditional program-of-record barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among specialist generator set assemblers lacking integrated engine manufacturing, as margin compression from steel alloy volatility and certification cost inflation erodes standalone viability. Long-term viability favors diversified industrial conglomerates with backward integration into aftertreatment and battery storage. Watch directed energy weapons pulsed-power specification releases as inflection signal for megawatt-class mobile platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aftertreatment Systems | Caterpillar and Cummins reduce field failure exposure through captive selective catalytic reduction manufacturing. |
| Hybrid Architecture Pilot Programs | French and German land forces demonstrate operational viability under EU Green Deal procurement guidelines. |
| Rapid Prototyping Pathway Access | Poland and Romania accelerate acquisition timelines through multiple-award indefinite-delivery contracting vehicles. |
| Tropicalized Generator Certification | Australian northern territory basing agreements expand demand for humidity and salt-fog resistant systems. |
| Containerized Battery Energy Storage Deployment | Amphibious ready groups adopt shore power configurations reducing liquid fuel resupply vulnerability. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, generator set engineering directors, military depot maintenance supervisors, and prime contractor program managers with secondary validation. Defense budget justification documents, EPA certification filings, NATO standardization agreements, and customs trade data anchored supply-side assessment. Bottom-up unit shipment modeling and top-down defense expenditure allocation triangulated market sizing.
Segment-weighting across type, capacity, installation, and end-user dimensions shaped analytical framework construction over the projection horizon. Diesel generator, hybrid generator, solar generator, and fuel cell generator categories received distinct growth trajectory modeling. CAGRs derived from replacement cycle analysis, contingency response budget allocation patterns, and directed energy weapons integration timelines. Pulsed-power duty cycle specifications and MIL-STD-810H qualification protocol durations informed capacity-tier penetration assumptions.
Inputs from Pentagon program-of-record announcements and EU defense procurement tender databases were available through the study window; gaps in classified expeditionary capability requirements introduce uncertainty bands around special operations segment projections. Forecasts reflect documented assumptions regarding EPA compliance phase-in schedules and NATO interoperability standardization timelines. Material deviation in rare earth export restrictions or directed energy weapons fielding acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Saudi Arabia Diesel Generator Market
Generators
Commercial Generator Market
Generators
Silent Generator Market
Generators
North America Generator Sets Market
Generators
Asia-Pacific Generator Sets Market
Generators
Middle East and Africa Gas Generator Market
Generators
Construction Portable Generators Market
Generators
Asia-Pacific Portable Generator Market
Generators
Generator Belt Market
Generators
Containerized Solar Generators Market
Generators
Residential Gas Generator Market
Generators
Residential Generators Market
Generators
Global Portable Generator Market
Generators
Europe Gas Generator Market
Generators
South America Gas Generator Market
Generators
Europe Diesel Generator Market