
 Telecom Site Management Software Market | 2026-2036
Telecom Site Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Site Management Software Market Insights
The telecom site management software market is recalibrating around a widening gap between premium orchestration suites and commodity monitoring tools. IBM leverages its hybrid cloud architecture to anchor enterprise-grade deployments for multinational network operators. Sitetracker specializes in project-centric workflows that dominate North American tower rollout cycles. Cisco Systems extends its networking heritage into edge-aware site management platforms that compete on real-time telemetry integration.
Telecom site management software encompasses applications that monitor, maintain, and optimize physical telecommunications infrastructure including cell towers, data centers, and remote equipment shelters through centralized dashboards, automated alerting protocols, and energy consumption analytics. Cloud-based deployment leads solution adoption as network operators pursue elastic scaling across geographically dispersed sites, while energy management commands premium pricing due to diesel generator fuel tracking and renewable hybrid integration requirements. Asset tracking functions are maturing fastest in mature markets whereas fault management retains higher margin pools in emerging infrastructure buildouts.
FCC Part 15 equipment authorization rules and OSHA tower climbing safety standards shape product certification requirements and field service module design in the United States, while India's TRAI infrastructure sharing guidelines and CEA telecom energy norms drive localization of compliance monitoring features. Tower companies and managed service providers must evaluate vendor roadmaps against evolving multi-jurisdiction regulatory portfolios rather than single-market compliance snapshots.
Market Dynamics
The telecom site management software market is fracturing between cloud-native orchestration platforms and legacy on-premise installations as tower operators consolidate vendor relationships to reduce integration overhead across multi-tenant infrastructure portfolios.
Growth Catalysts
- 5G Spectrum Obligations:FCC buildout deadlines in the United States are forcing tower companies to accelerate software procurement for site densification tracking and compliance documentation.
- India Broadband Targets:Government-mandated rural connectivity goals under BharatNet are intensifying vendor competition for tower management contracts in underserved districts.
- Hybrid Cloud Architectures:Network operators are migrating distributed asset monitoring to elastic cloud environments that scale with site portfolio expansion without proportional infrastructure investment.
Market Restraints
- Integration Complexity:Legacy SCADA systems at established tower sites require expensive middleware development to interface with modern API-driven management platforms.
- Specialized Talent Scarcity:Field engineering teams with combined expertise in RF engineering and software configuration command premium wages that compress deployment margins.
- Data Sovereignty Requirements:India's data localization mandates under pending digital privacy frameworks are forcing vendors to establish in-country cloud infrastructure, raising operational costs.
Strategic Opportunities
- Energy Management Modules:Diesel-to-solar hybrid transitions at remote cell towers are creating demand for predictive analytics that optimize battery cycling and generator runtime.
- AI-Driven Predictive Maintenance:Machine learning models trained on equipment telemetry are enabling shift from scheduled maintenance to condition-based intervention, reducing site visits.
- Small Cell Overlay Management:Urban 5G densification is expanding addressable market beyond macro towers to street furniture and building-mounted infrastructure requiring centralized coordination.
Industry Challenges
- Multi-Vendor Interoperability:Tower operators managing equipment from disparate OEMs face protocol fragmentation that complicates unified dashboard deployment.
- Cybersecurity Certification Delays:NIST framework compliance and SOC 2 attestation timelines are extending sales cycles for vendors targeting enterprise operator procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Site Management Software Market |
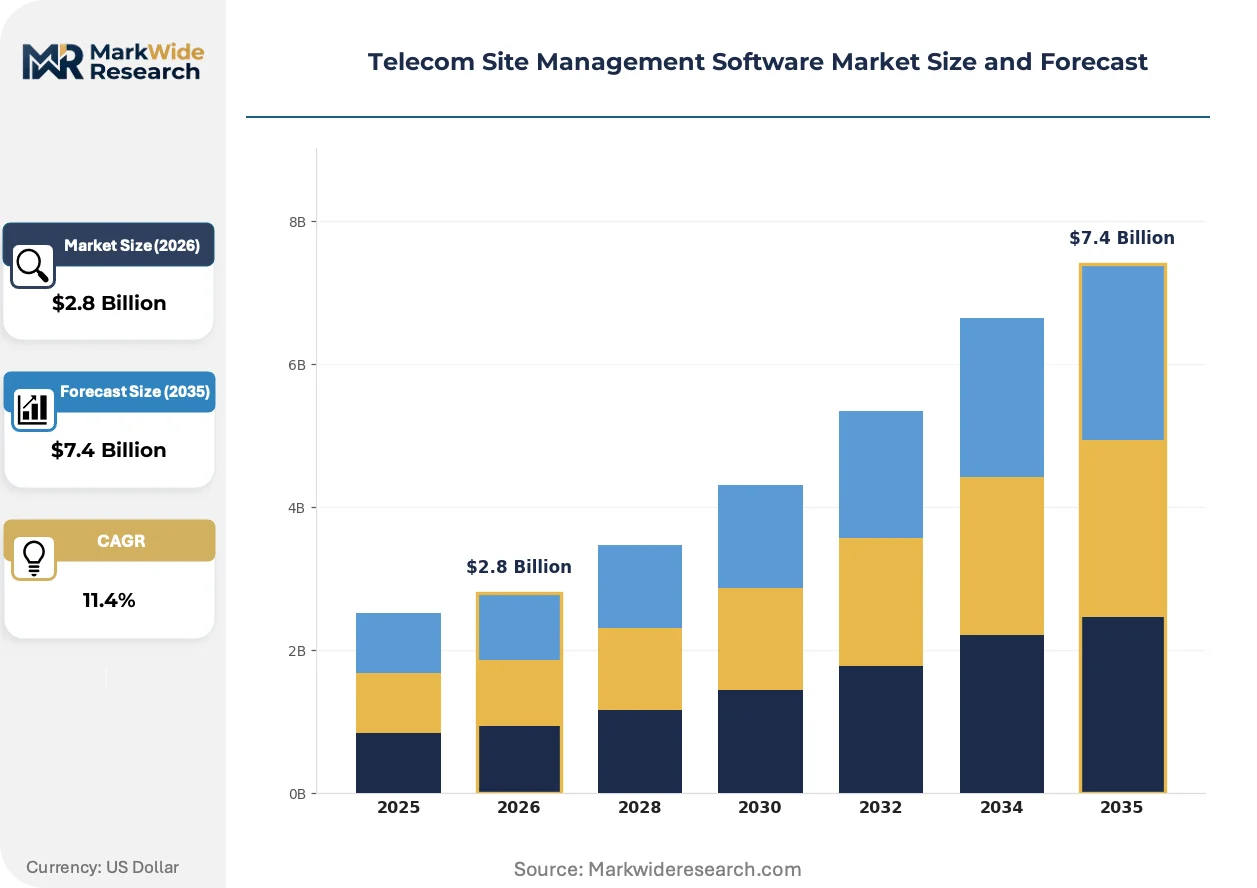
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Network Optimization, Asset Tracking, Fault Management, Energy Management Use Case: Site Inventory Management, Maintenance Scheduling, Compliance Monitoring, Performance Analytics End User: Network Operators, Managed Service Providers, Infrastructure Vendors, Tower Companies |
| Companies Covered | Accruent, Sitetracker, Tarantula, Asentria, IBM, Cisco Systems, Nokia, Hewlett Packard Enterprise, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Site Management Software Market Trends and Innovations
Software architecture decisions are increasingly dictated by edge computing requirements as real-time processing demands outpace centralized cloud latency tolerance for critical infrastructure monitoring.
Digital twin modeling is converging with live sensor feeds to create persistent virtual replicas of physical tower assets. Tower operators in Germany and South Korea are deploying these systems for structural load simulation and preemptive maintenance scheduling. This convergence is compressing the feedback loop between field condition detection and engineering response.
OSHA tower climbing safety standards are mandating enhanced field service documentation modules that capture technician certification status and equipment inspection timestamps. Software vendors serving the United States market are retrofitting mobile applications with biometric verification and geofenced check-in protocols. Tower maintenance contractors are absorbing these compliance costs through renegotiated service agreements.
Subscription-based licensing is displacing perpetual software purchases as tower companies prioritize operational expenditure treatment for financial reporting. Managed service providers are bundling site management platforms with staffing and maintenance contracts. This shift is most pronounced in North American markets where REIT-structured tower companies face shareholder pressure for predictable cost structures.
Telecom Site Management Software Market Segmentation
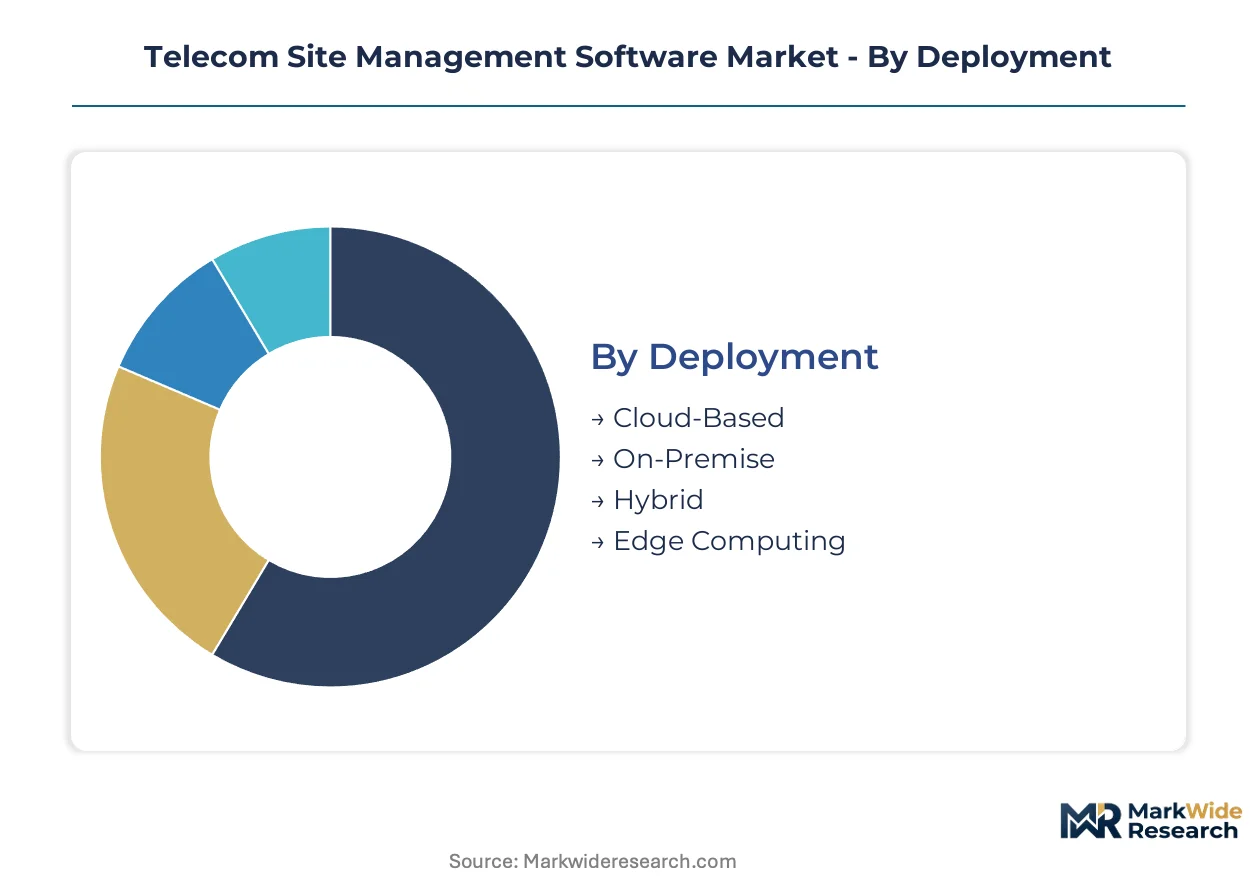
Telecom site management software segments reflect divergent integration depths across tower operator technology stacks. Deployment models range from standalone cloud platforms to deeply embedded edge systems, while solution types vary between modular point tools and unified orchestration suites.
Deployment:
Integration depth varies sharply: cloud and hybrid deployments operate as overlay systems atop existing infrastructure, while edge computing embeds directly into tower-mounted hardware.
- Cloud-Based:Elastic infrastructure scales across geographically dispersed portfolios without proportional capital investment. Tower companies in India prioritize this model to meet BharatNet rural connectivity deadlines without on-site server deployment.
- On-Premise:Legacy installations persist at established sites with stringent data sovereignty requirements. Operators in Germany maintain these systems for structural load simulation data governed by national cybersecurity frameworks.
- Hybrid:Split architectures process sensitive telemetry locally while pushing analytics to centralized clouds. This model dominates where TRAI infrastructure sharing guidelines mandate localized audit trails.
- Edge Computing:Millisecond-latency processing for real-time equipment intervention. South Korean operators deploy these systems for preemptive maintenance on dense urban small cell networks.
Cloud-Based leads volumes today; Edge Computing is gaining share fastest.
Solution Type:
Cost tier stratification separates premium orchestration modules from commodity monitoring functions, with energy management commanding the highest price points.
- Network Optimization:RF performance tuning and spectrum allocation algorithms. Demand concentrates among managed service providers in the United States where FCC 5G buildout deadlines drive procurement for site densification tracking.
- Asset Tracking:Geolocation and lifecycle management for distributed equipment. Tower companies expanding across India's underserved districts prioritize this function for distributed asset portfolio visibility.
- Fault Management:Automated alerting and ticket generation for equipment failures. This module retains higher margin pools in emerging infrastructure buildouts where reactive maintenance still dominates.
- Energy Management:Diesel generator fuel tracking and renewable hybrid integration. Remote cell towers in Sub-Saharan Africa and Southeast Asia drive demand for predictive battery cycling analytics.
Asset Tracking leads volumes today; Energy Management is climbing the fastest.
Use Case:
Application maturity separates established inventory functions from emerging compliance automation, with performance analytics representing the newest capability layer.
- Site Inventory Management:Centralized databases of physical infrastructure components. Network operators in mature markets treat this as table stakes, while India's tower densification projects treat it as a competitive differentiator.
- Maintenance Scheduling:Calendar-based and condition-triggered service dispatch. OSHA tower climbing safety standards in the United States mandate enhanced documentation modules with biometric verification protocols.
- Compliance Monitoring:Automated regulatory reporting for multi-jurisdiction portfolios. This use case expands fastest where FCC Part 15 equipment authorization rules intersect with emerging data localization mandates.
- Performance Analytics:Historical trending and predictive modeling for capacity planning. South Korean operators leverage these tools for 5G small cell overlay coordination in dense urban corridors.
Site Inventory Management leads volumes today; Compliance Monitoring is expanding most quickly.
End User:
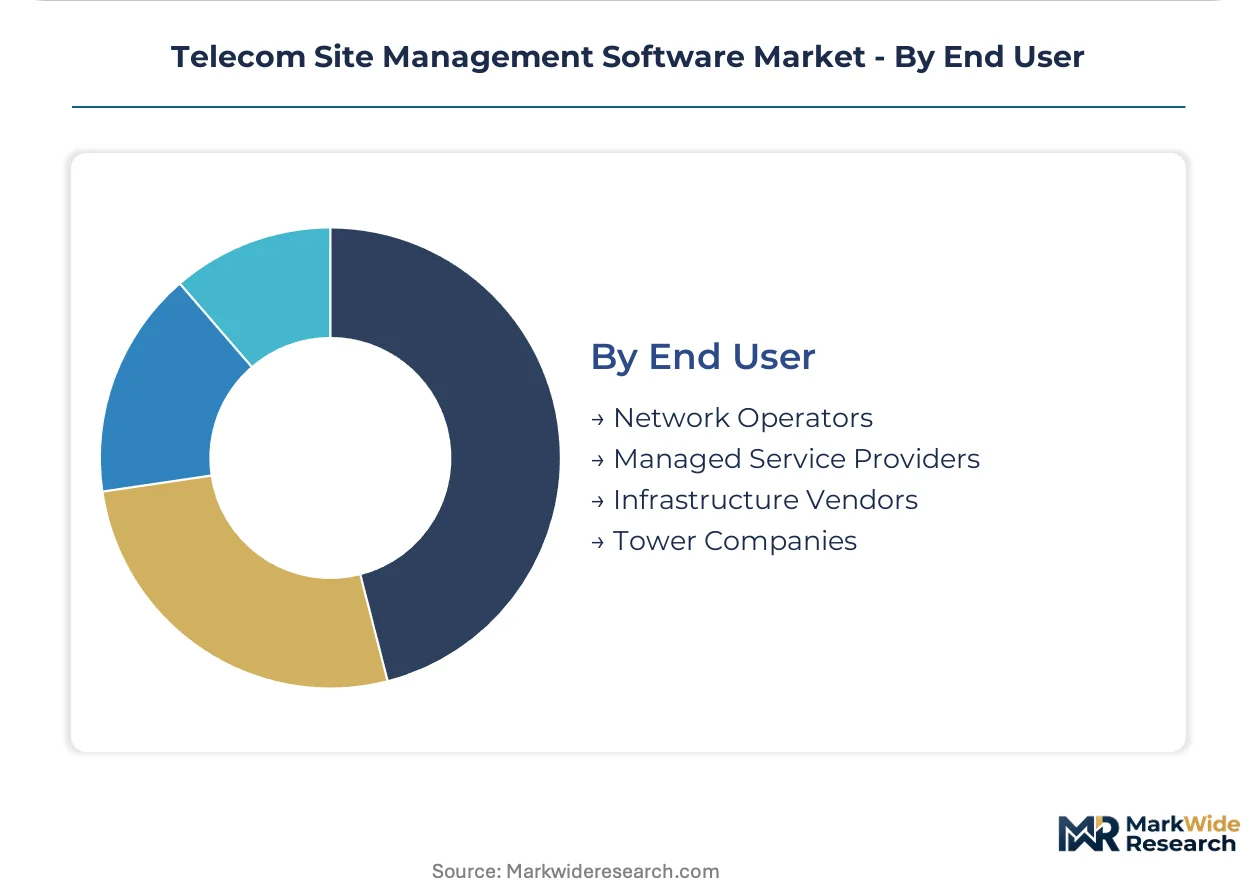
Customer type determines procurement complexity, with tower companies consolidating vendor relationships while managed service providers bundle platforms with staffing contracts.
- Network Operators:Multinational carriers requiring enterprise-grade orchestration across heterogeneous equipment portfolios. These buyers prioritize hybrid cloud architectures with NIST framework compliance certification.
- Managed Service Providers:Third-party contractors absorbing operational technology costs through renegotiated service agreements. North American REIT-structured tower companies favor this model for predictable operational expenditure treatment.
- Infrastructure Vendors:Original equipment manufacturers extending software capabilities to differentiate hardware offerings. These players face protocol fragmentation challenges when interfacing with multi-vendor tower environments.
- Tower Companies:Pure-play site owners consolidating software procurement to reduce integration overhead. India's independent tower operators represent the most concentrated demand pool for vendor competition.
Tower Companies lead volumes today; Managed Service Providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tower densification sprint contrasts with Germany's methodical infrastructure consolidation, yet both markets drive software procurement through divergent regulatory pathways. The United States anchors enterprise-grade adoption through FCC-mandated compliance deadlines, while emerging buildouts in Sub-Saharan Africa and Southeast Asia prioritize energy optimization modules for off-grid deployments.
United States
FCC Part 15 equipment authorization rules and 5G spectrum buildout deadlines are accelerating procurement for site densification tracking and compliance documentation. OSHA tower climbing safety standards mandate enhanced field service modules with biometric verification protocols. Tower operators in Texas and the Southeast are consolidating vendor relationships to reduce integration overhead across multi-tenant portfolios.
India
BharatNet rural connectivity targets and TRAI infrastructure sharing guidelines are intensifying vendor competition for tower management contracts in underserved districts. CEA telecom energy norms drive localization of compliance monitoring features for diesel-to-solar hybrid transitions. Independent tower operators in Maharashtra and Gujarat represent the most concentrated demand pools for cloud-based deployment models.
Germany
National cybersecurity frameworks and data sovereignty requirements sustain on-premise installations for structural load simulation data. The country's national telecom regulator enforces strict audit trail mandates that favor hybrid architectures with localized processing. Tower operators in Bavaria and North Rhine-Westphalia deploy digital twin modeling for preemptive maintenance on dense urban infrastructure.
South Korea
Millisecond-latency requirements for urban 5G densification are driving edge computing deployment on street furniture and building-mounted small cells. The national spectrum authority mandates real-time equipment intervention capabilities for critical infrastructure monitoring. Operators in Seoul and Busan leverage performance analytics for small cell overlay coordination in dense metropolitan corridors.
Brazil
Remote cell tower electrification challenges and renewable hybrid integration requirements are expanding demand for predictive battery cycling analytics. The national telecom regulator enforces infrastructure sharing guidelines that complicate multi-vendor interoperability. Tower operators in São Paulo and Minas Gerais prioritize energy management modules to optimize diesel generator runtime in off-grid locations.
Telecom Site Management Software Market Competitive Landscape
Top-tier vendors anchor enterprise orchestration suites, while specialized workflow providers occupy project-centric niches. The market exhibits tiered concentration with multinational technology conglomerates competing against vertical specialists in tower rollout cycles. Three archetypes dominate: hybrid cloud architects, project workflow specialists, and networking heritage extenders. Consolidation through strategic partnerships and API-driven platform expansion represent the dominant competitive vectors.
Within the hybrid cloud architecture tier, IBM and Hewlett Packard Enterprise exemplify enterprise-grade deployment anchors for multinational network operators. Sitetracker occupies a position among North American workflow specialists focused on tower rollout project management. Cisco Systems and Nokia represent networking heritage extenders competing on real-time telemetry integration and edge-aware platform development.
| Leading Market Players |
|---|
| Accruent |
| Sitetracker |
| Tarantula |
| Asentria |
| IBM |
| Cisco Systems |
| Nokia |
| Hewlett Packard Enterprise |
| Oracle |
| Others |
Pricing and Supply Chain Analysis
A sharp bifurcation between cloud-native orchestration suites and legacy on-premise installations splits both pricing power and supply chain configurations across the telecom site management software market. Premium vendors command subscription multiples against commodity monitoring tools while supply concentration in Indian cloud infrastructure and German edge hardware feeds divergent margin structures.
Pricing Analysis
Capacity additions in India's cloud infrastructure sector are reshaping price floors for SaaS-tiered deployments targeting BharatNet rural connectivity deadlines. Three-tier pricing structure across premium, standard, and economy levels separates NIST-compliant enterprise suites from TRAI-localized compliance modules and basic fault monitoring tools. Price differentiation hinges on certification grade for FCC Part 15 equipment authorization and customization level for multi-vendor interoperability. Cost compression in the economy tier intensifies because middleware development for legacy SCADA integration drains deployment margins. Managed service providers in North America exhibit least price sensitivity due to REIT-structured operational expenditure treatment, while independent tower operators in Maharashtra and Gujarat represent the most price-constrained buyer segment.
Supply Chain Analysis
Edge computing hardware supply rests on South Korean semiconductor foundries and German industrial automation specialists for millisecond-latency processing modules. Cloud infrastructure draws from Indian data center operators and U.S. hyperscaler platforms for elastic deployment architectures. Raw material dependencies span silicon wafers for edge processors, lithium-ion cells for remote tower battery systems, and specialized sensors for structural load monitoring. Single-source vulnerability concentrates in South Korean memory chip supply for real-time telemetry integration. Distribution runs through direct enterprise sales for multinational network operators and managed service provider bundling for REIT-structured tower companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement consolidation favors vendors with proven multi-jurisdiction compliance portfolios over point-solution specialists. Demand is shifting toward premium specifications as OSHA biometric verification mandates and FCC buildout deadlines raise the cost of inadequate field service documentation.
For Market Incumbents: Anticipate margin compression from API-driven platform expansion by networking heritage extenders competing on real-time telemetry integration. Defensive consolidation through strategic partnerships with Indian cloud infrastructure providers secures localization advantages under pending data sovereignty frameworks. Certification investment in NIST framework compliance and SOC 2 attestation creates switching costs against emerging workflow specialists.
For New Entrants and Emerging Players: Rural connectivity contractors under BharatNet deadlines represent the most penetrable buyer archetype currently underserved by incumbent enterprise suites. White-space targets include diesel-to-solar hybrid analytics for Sub-Saharan African off-grid deployments and small cell overlay coordination tools for South Korean urban densification corridors. A channel partnership with managed service providers bundling platforms with staffing contracts offers the lowest customer acquisition friction.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-vendor interoperability complexity exceeds in-house development capabilities of mid-tier tower operators. Long-term viability favors vendors with hybrid cloud architectures spanning edge computing and centralized analytics across the analysis window. Acquisition target archetype: workflow specialists with proven India market penetration and TRAI compliance localization. The signal to watch is FCC enforcement action on 5G spectrum buildout deadline extensions as a demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fault management and energy analytics for multi-tenant tower portfolios under single dashboards. |
| Geographic Expansion | Establishes in-country cloud infrastructure to satisfy India's data localization mandates and reduce sales friction. |
| Strategic Partnership | Aligns with managed service providers to bundle software with OSHA-compliant field staffing contracts. |
| Acquisition of Specialist Firm | Absorbs edge computing capabilities for South Korean millisecond-latency small cell management requirements. |
| Product Launch | Introduces AI-driven predictive maintenance modules trained on equipment telemetry to reduce site visits. |
Research Methodology
Direct dialogue with tower company procurement directors, managed service provider operations executives, network operator CTOs, and FCC regulatory compliance officers grounded qualitative findings in operational reality. Secondary validation drew from SEC filings of REIT-structured tower companies, TRAI infrastructure sharing guideline updates, OSHA tower climbing safety standard revisions, and hyperscaler capex disclosures for cloud infrastructure expansion. Bottom-up and top-down triangulation cross-checked vendor revenue estimates against tower portfolio growth data and software procurement cycle timing.
Bottom-up modeling aggregated individual site deployment counts and solution module pricing across cloud, hybrid, and edge computing architectures. Segmentation dimensions spanned deployment model, organization size by tower count, vertical integration depth, and regional regulatory cluster complexity. CAGRs were derived from installed base expansion rates and replacement cycle acceleration factors. Industry-specific forecast inputs included FCC 5G buildout deadline enforcement probability and BharatNet rural connectivity target revisions across the projection horizon.
Underlying measurement precision varies by segment; cloud-based deployment and asset tracking functions carry tighter precision than emerging edge computing and compliance monitoring categories. Forecasts reflect assumptions about regulatory deadline adherence and middleware development cost trajectories. Material deviation in FCC enforcement intensity or Indian data localization implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Home Service Market
Digital Solutions
India ICT Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Global Application Container Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Global Automatic Content Recognition (ACR) Market
Digital Solutions
Digital Signage Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Online Hyper-Local Services Market