
 Smart Connected Assets and Operations Market | 2026-2036
Smart Connected Assets and Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Connected Assets and Operations Market Outlook
Modular platform bundling is expanding as the dominant configuration pattern, with vendors combining edge hardware, analytics software, and managed services into unified subscription offerings rather than standalone components. Siemens AG leverages its automation heritage to anchor integrated factory solutions across European manufacturing hubs. IBM Corporation competes through Watson-based AI analytics layered atop hybrid cloud architectures for asset-intensive clients. Cisco Systems, Inc. specializes in secure industrial networking infrastructure that connects legacy operational technology to modern IT environments.
Smart Connected Assets and Operations denotes the integration of internet-enabled sensors, edge computing nodes, and AI-driven analytics platforms with physical industrial equipment to enable real-time monitoring, autonomous optimization, and predictive intervention across production and distribution systems. The architecture typically incorporates time-series data ingestion at sub-second latency, digital twin modeling, and API-based interoperability between enterprise resource planning and operational technology stacks. IoT Solutions and Edge Computing segments lead current revenue generation due to foundational hardware deployment cycles, while AI Analytics captures expanding margin pools as software-layer value intensifies. Cloud Platforms and Hybrid deployment models are gaining fastest traction among mid-market manufacturers seeking capital expenditure flexibility without sacrificing data sovereignty controls.
The EU AI Act imposes conformity assessment requirements on autonomous decision-making systems in industrial settings, while the NIS2 Directive mandates enhanced cybersecurity governance for critical infrastructure operators deploying connected assets. FDA scrutiny of software-as-a-medical-device functions in connected healthcare equipment and FCC spectrum allocation for industrial wireless protocols further shape product certification pathways and market access conditions. Stakeholders must monitor evolving liability frameworks around AI-generated operational decisions and align R&D roadmaps with emerging interoperability standards before competitive positioning solidifies around compliant architectures.
Market Dynamics
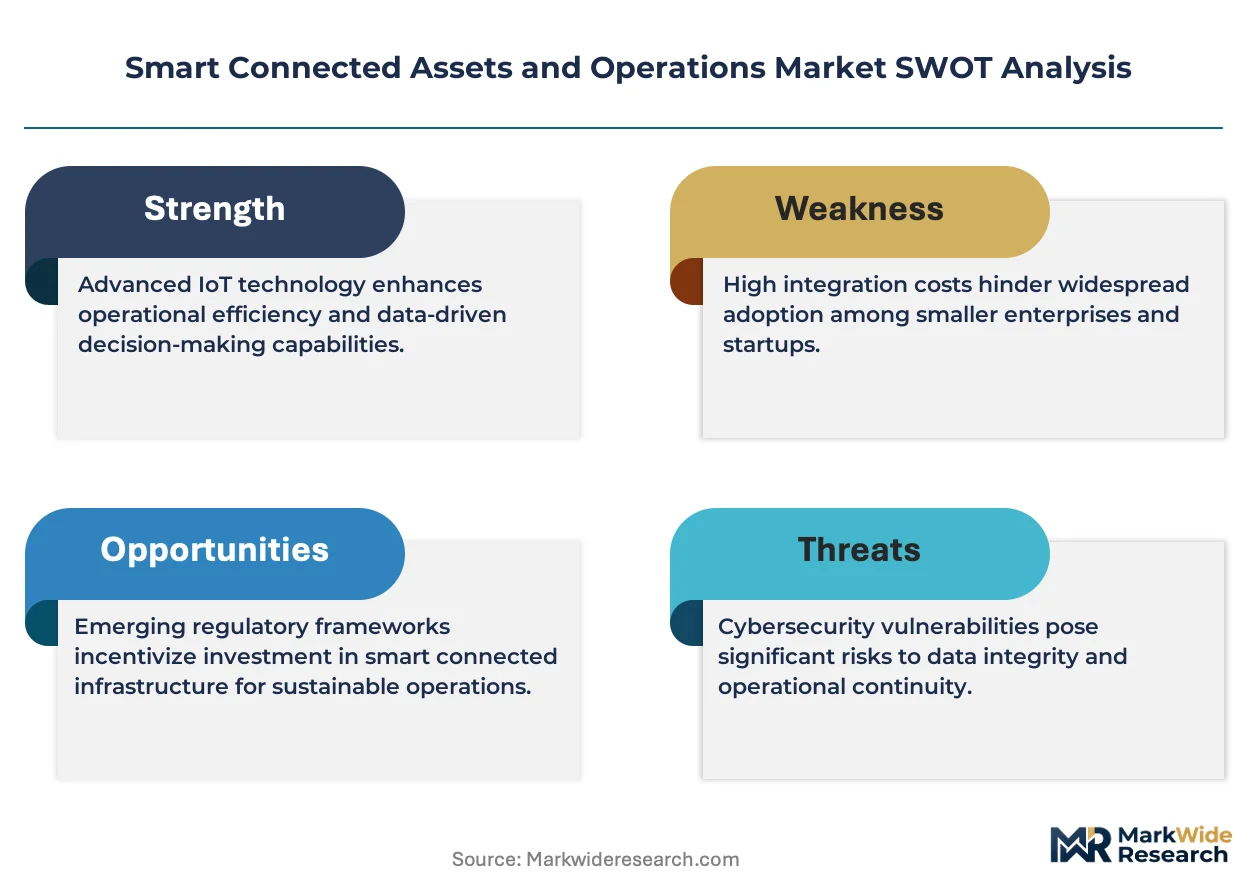
Modular platform bundling is compressing procurement cycles across manufacturing verticals as vendors consolidate edge hardware, analytics software, and managed services into unified subscription architectures rather than standalone component sales.
Growth Catalysts
- EU AI Act compliance mandates:Industrial operators deploying autonomous decision-making systems face conformity assessment requirements that accelerate replacement of legacy monitoring infrastructure with certified connected asset platforms.
- Predictive maintenance adoption in automotive manufacturing:Assembly line operators are integrating vibration sensors and thermal imaging into unified condition-monitoring networks to eliminate unplanned downtime.
- Edge computing deployment in German industrial clusters:Stuttgart and Munich manufacturing hubs are prioritizing sub-10-millisecond latency processing for real-time quality control applications.
Market Restraints
- Semiconductor supply concentration:Industrial-grade sensor microcontrollers and edge AI chips depend on foundry capacity concentrated in Taiwan and South Korea, creating procurement bottlenecks.
- Cybersecurity skill scarcity:NIS2 Directive mandates for critical infrastructure operators exceed available talent pools for OT/IT security architecture in European markets.
- Legacy protocol fragmentation:Proprietary industrial communication standards from decades of automation vendor lock-in impede seamless API-based interoperability.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and component assembly create localized supply chain alternatives for connected asset hardware.
- Digital twin convergence with generative AI:Physics-based simulation models are merging with large language interfaces to enable natural-language querying of asset performance scenarios.
- Outcome-based service contracting:Equipment vendors are pivoting from capital sales to availability-guarantee subscriptions in mining and energy extraction verticals.
Industry Challenges
- OT/IT integration complexity:Converging operational technology networks with enterprise IT security frameworks requires specialized systems architects scarce in industrial labor markets.
- Multi-jurisdiction certification timelines:FDA software-as-medical-device pathways for connected healthcare equipment and FCC industrial wireless approvals create sequential rather than parallel market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Connected Assets and Operations Market |
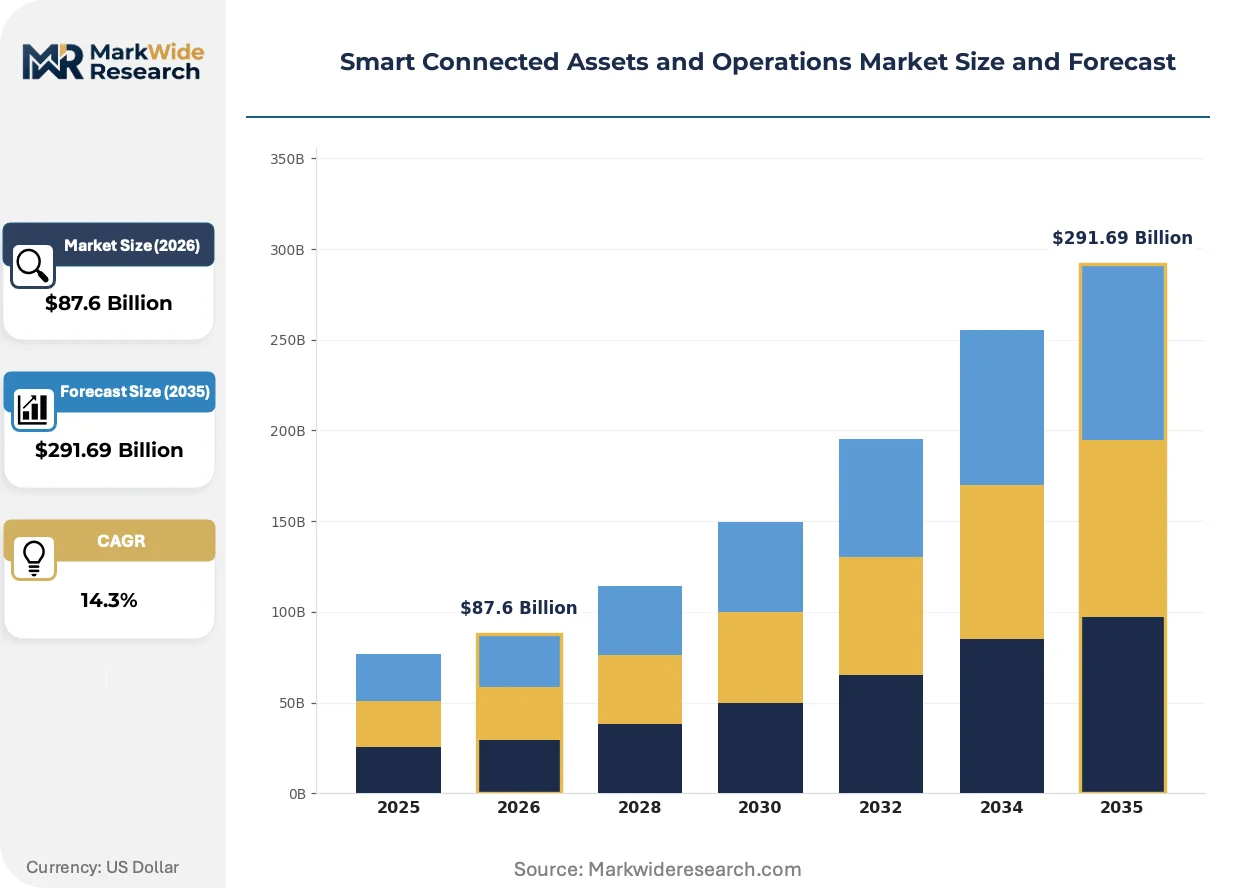
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $291.69 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Edge Computing, AI Analytics, Cloud Platforms End User: Manufacturing, Transportation, Utilities, Retail Application: Asset Management, Predictive Maintenance, Supply Chain Optimization, Energy Management Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud |
| Companies Covered | IBM Corporation, Intel Corporation, Cisco Systems, Inc., General Electric Company, Rockwell Automation, Siemens AG, Schneider Electric SE, PTC Inc., Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Connected Assets and Operations Market Strategic Shifts
Convergence between edge intelligence and cloud-native analytics is redefining architectural standards across asset-intensive industries, compressing the traditional separation between real-time control systems and strategic optimization layers.
Time-series databases optimized for industrial telemetry are converging with vector search architectures to enable semantic querying of historical asset performance. Chemical processing and power generation operators are piloting these hybrid data platforms for root-cause analysis. This convergence is compressing the analytics vendor landscape as specialized historians merge with general-purpose cloud data warehouses.
The EU AI Act's risk-based classification system imposes documentation and human-oversight requirements on high-risk industrial automation. Manufacturers deploying autonomous quality inspection or safety-critical control loops must maintain algorithmic audit trails. German automotive suppliers and French aerospace subcontractors are restructuring R&D roadmaps to embed explainability features before 2026 enforcement deadlines.
Buyer procurement patterns are fragmenting as mid-market manufacturers bypass traditional systems integrators for direct vendor relationships. Regional equipment distributors in the United States are losing share to factory-direct subscription models. This disintermediation is most pronounced among food and beverage processors with standardized production lines seeking faster deployment cycles.
Smart Connected Assets and Operations Market Segmentation
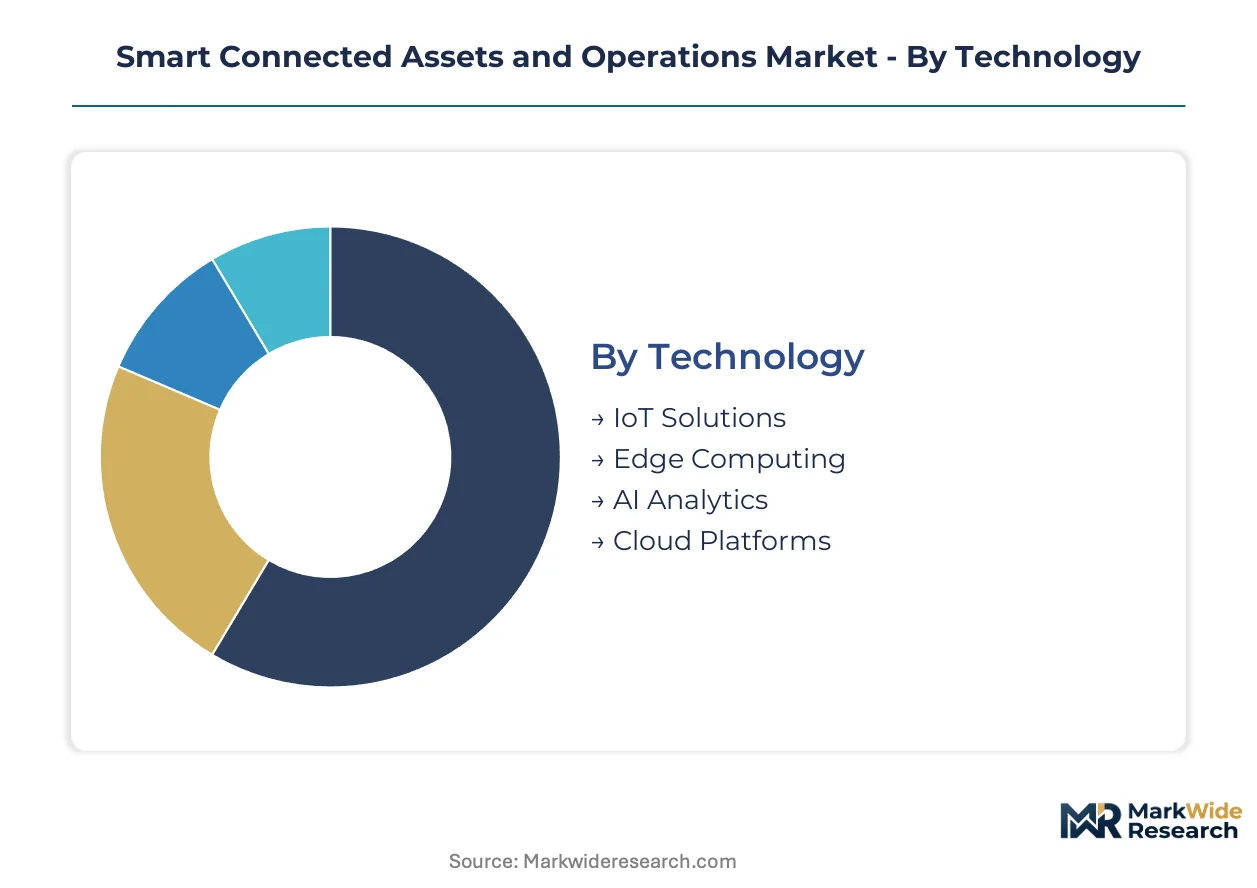
Smart Connected Assets and Operations architectures fragment across four distinct dimensions that determine integration complexity, procurement patterns, and margin capture. Technology choices anchor capital allocation decisions. End-user verticals dictate regulatory exposure and performance requirements. Application focus shapes software-layer monetization. Deployment models determine data sovereignty and operational control trade-offs.
Technology:
Integration depth varies sharply: IoT Solutions and Edge Computing function as standalone infrastructure layers, while AI Analytics and Cloud Platforms embed as software services atop hardware foundations.
- IoT Solutions:Sensor networks, connectivity modules, and device management platforms form the physical data ingestion layer. Manufacturing facilities in Germany and the United States are prioritizing industrial-grade sensor deployments to satisfy EU AI Act documentation requirements for autonomous systems.
- Edge Computing:Sub-10-millisecond latency processing nodes enable real-time control without cloud dependency. Stuttgart and Munich industrial clusters are deploying these systems for quality control applications where network interruptions risk production losses.
- AI Analytics:Machine learning models for anomaly detection and optimization recommendations.
- Cloud Platforms:Scalable compute and storage infrastructure for historical data warehousing.
IoT Solutions leads volumes today; AI Analytics is gaining share fastest.
End User:
Cost tier segmentation separates capital-intensive heavy industry from lighter-asset service sectors, with manufacturing and utilities commanding premium pricing for mission-critical reliability.
- Manufacturing:Automotive assembly lines, chemical processing plants, and discrete fabrication facilities deploy vibration sensors, thermal imaging, and digital twins. German automotive suppliers are restructuring R&D roadmaps to embed explainability features before EU AI Act enforcement deadlines.
- Utilities:Power generation, water treatment, and grid infrastructure operators. French and German energy utilities are deploying connected asset platforms to meet NIS2 Directive cybersecurity governance mandates for critical infrastructure.
- Transportation:Fleet management, logistics hubs, and multimodal freight networks.
- Retail:Supply chain visibility and inventory optimization for distribution networks.
Manufacturing dominates current procurement; Utilities is expanding most quickly.
Application:
Application maturity curves diverge: Asset Management and Predictive Maintenance operate as established operational programs, while Supply Chain Optimization and Energy Management embed as cross-functional initiatives.
- Predictive Maintenance:Condition-based intervention using vibration analysis, thermal imaging, and oil particulate monitoring. Automotive assembly line operators are eliminating unplanned downtime through unified condition-monitoring networks.
- Asset Management:Lifecycle tracking, performance benchmarking, and capital planning for physical equipment. Mining and energy extraction verticals are pivoting toward availability-guarantee subscriptions rather than capital sales.
- Supply Chain Optimization:End-to-end visibility and demand forecasting across distribution networks.
- Energy Management:Consumption monitoring, load balancing, and carbon accounting integration.
Asset Management captures the largest installed base; Predictive Maintenance shows the steepest expansion trajectory.
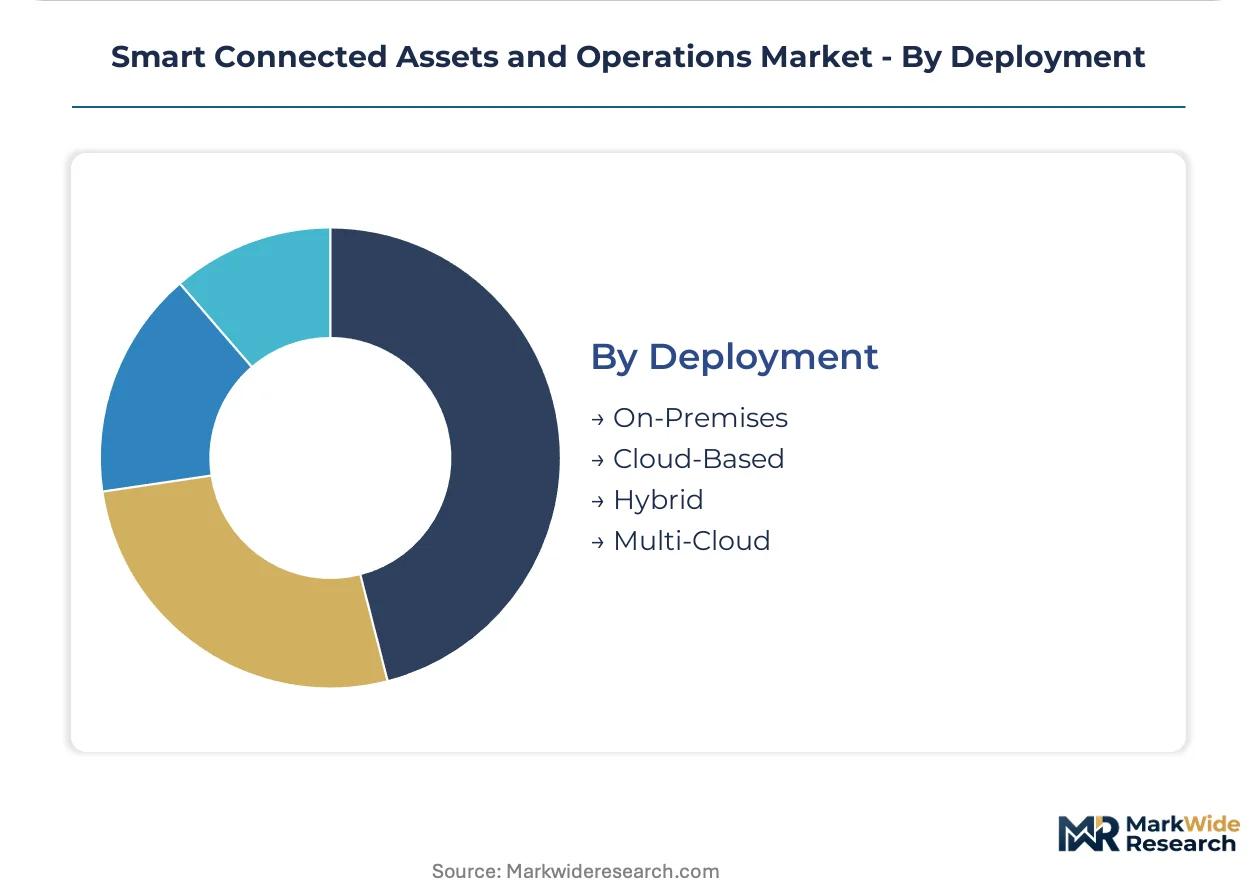
Deployment:
Customer type segmentation separates enterprise manufacturers with dedicated IT security teams from mid-market players seeking managed service alternatives.
- Hybrid:Split processing between on-premises edge nodes and cloud analytics for data sovereignty. Mid-market manufacturers are prioritizing this model to satisfy capital expenditure flexibility requirements without sacrificing operational control.
- Cloud-Based:Fully managed SaaS analytics with API connectivity to operational technology stacks.
- On-Premises:Air-gapped or privately hosted infrastructure for classified or safety-critical environments.
- Multi-Cloud:Distributed workloads across competing hyperscaler platforms for vendor risk mitigation.
Hybrid deployment leads adoption today; Cloud-Based models are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation first achieved commercial scale in Germany's Ruhr Valley during the 1970s, establishing the foundational architectures now replicated worldwide. Connected asset platforms today concentrate where manufacturing density intersects with regulatory pressure and digital infrastructure investment.
Germany
Automotive suppliers and machine tool builders drive platform procurement across Baden-Württemberg and Bavaria. The EU AI Act's conformity assessment deadlines for high-risk automation systems are compressing replacement cycles for legacy monitoring infrastructure. Stuttgart industrial clusters deploy sub-10-millisecond edge computing nodes for real-time quality control applications.
United States
Mid-market manufacturers in Michigan and Ohio bypass traditional systems integrators for factory-direct subscription models. FCC spectrum allocation for industrial wireless protocols shapes product certification pathways for connected asset vendors. Houston energy extraction operators pilot outcome-based availability-guarantee contracts rather than capital equipment sales.
China
MIIT's dual carbon goals accelerate energy management platform adoption across Yangtze River Delta manufacturing zones. GB standards for industrial IoT interoperability create domestic certification requirements distinct from IEC frameworks. Shenzhen electronics assemblers integrate vibration sensors and thermal imaging into unified condition-monitoring networks.
India
PLI scheme incentives for electronics manufacturing attract semiconductor component assembly for connected asset hardware. CEA mandates for grid infrastructure modernization drive utility procurement of cybersecurity-hardened monitoring platforms. Gujarat and Tamil Nadu industrial corridors prioritize capital expenditure flexibility through hybrid cloud-edge deployment models.
France
Aerospace subcontractors in Île-de-France restructure R&D roadmaps to embed algorithmic explainability features before EU AI Act enforcement. ANSM oversight of connected healthcare equipment creates sequential certification timelines alongside industrial automation pathways. Lyon chemical processing operators pilot time-series databases merged with vector search architectures for root-cause analysis.
Smart Connected Assets and Operations Market Competitive Environment
Premium-margin players sit above commodity-margin players across software-layer value capture, with AI analytics and managed services commanding pricing multiples over hardware components. The vendor base concentrates around integrated platform architectures rather than standalone component sales. Three archetypes dominate: automation heritage firms leveraging factory-floor relationships, cloud-native analytics providers, and secure networking specialists bridging operational technology to enterprise IT. Competitive moves center on modular platform bundling and direct subscription relationships displacing distributor intermediaries.
Within the integrated platform tier, Siemens AG and IBM Corporation occupy positions reflecting divergent strategic origins. The German engineering conglomerate exemplifies automation heritage extension into unified factory solutions. The US technology corporation represents cloud-native AI analytics layered atop hybrid architectures for asset-intensive clients. Cisco Systems, Inc. anchors the secure networking archetype, specializing in infrastructure that connects legacy operational technology to modern IT environments.
| Leading Market Players |
|---|
| IBM Corporation |
| Intel Corporation |
| Cisco Systems, Inc. |
| General Electric Company |
| Rockwell Automation |
| Siemens AG |
| Schneider Electric SE |
| PTC Inc. |
| Texas Instruments |
| Others |
Value Chain & Pricing Dynamics
Modular platform bundling is simultaneously compressing procurement costs and concentrating margin capture among integrated vendors who combine edge hardware, analytics software, and managed services into unified subscription architectures. This shift rewards vendors with captive supply chains while squeezing standalone component suppliers unable to match bundled price points.
Pricing Analysis
Subscription-based SaaS tiers dominate pricing architecture across manufacturing verticals, separating premium analytics bundles with AI-driven predictive capabilities from standard monitoring dashboards and economy-grade connectivity-only packages. Price differentiation rests on EU AI Act certification grade and customization depth for legacy protocol integration. Pricing pressure stems from mid-market manufacturers demanding capital expenditure flexibility through hybrid deployment models. Food and beverage processors exhibit highest price sensitivity, while German automotive suppliers prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing is reshaping sourcing patterns by incentivizing localized semiconductor component assembly and reducing dependence on concentrated East Asian foundry capacity. Industrial-grade sensor microcontrollers and edge AI chips draw from Taiwan, South Korea, and mainland China fabrication networks. Single-source vulnerability around Taiwan Strait logistics creates procurement bottlenecks for European and North American operators. Distribution runs through regional equipment distributors losing share to factory-direct subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-layer value capture as AI analytics commands pricing multiples over commoditized hardware components, with edge-to-cloud integration complexity justifying premium service tiers.
For Market Incumbents: Deepen vertical integration into edge AI chip design to reduce Taiwan foundry exposure and defend margin position against cloud-native analytics entrants. Prioritize EU AI Act conformity assessment pre-certification to accelerate replacement cycles for legacy infrastructure. Anchor factory-floor relationships through outcome-based availability-guarantee subscriptions in mining and energy extraction verticals. For New Entrants and Emerging Players: Begin with mid-market food and beverage processors seeking faster deployment cycles outside traditional systems integrator channels. Target hybrid cloud-edge deployment models where capital expenditure flexibility requirements outpace incumbent response capabilities. Pursue direct vendor relationships through standardized production line configurations. For Investors and Strategic Acquirers: Valuations sit cheapest among secure networking specialists bridging operational technology to enterprise IT environments, where capability scarcity exceeds software-layer analytics. Long-term viability favors vendors with embedded explainability features aligned to EU AI Act enforcement timelines. Watch for FDA software-as-medical-device pathway approvals as inflection indicators for healthcare equipment diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies edge hardware, analytics software, and managed services into subscription architectures displacing component sales. |
| EU AI Act Pre-Certification | Accelerates replacement cycles for legacy monitoring infrastructure ahead of conformity assessment deadlines. |
| Backward Integration into Edge AI Chips | Reduces Taiwan and South Korea foundry dependency while capturing margin from semiconductor supply concentration. |
| Outcome-Based Service Contracting | Pivots mining and energy extraction verticals from capital equipment sales to availability-guarantee subscriptions. |
| Hybrid Cloud-Edge Deployment | Satisfies mid-market manufacturer demand for capital expenditure flexibility without sacrificing data sovereignty controls. |
Study Parameters
Direct dialogue with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads grounded qualitative findings in operational technology deployment realities. Secondary validation drew from SEC 10-K filings, EU AI Act implementation guidance, NIS2 Directive compliance frameworks, and industrial automation trade association publications. Bottom-up and top-down triangulation reconciled vendor shipment data with end-user procurement surveys across manufacturing, utilities, and transportation verticals.
Bottom-up modeling aggregated segment-level technology adoption curves, deployment model preferences, and application-specific pricing tiers across IoT Solutions, Edge Computing, AI Analytics, and Cloud Platforms. Top-down constraints incorporated EU AI Act risk classifications, FCC spectrum allocation timelines, and MIIT dual carbon goal implementation. CAGRs derived from convergence between hardware replacement cycles and software-layer value intensification over the projection horizon.
Caveats apply where semiconductor supply concentration, NIS2 Directive cybersecurity skill scarcity, or multi-jurisdiction certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement consistency and interoperability standard adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Signature Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Beacons Management Software Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Legal Technology Market
Digital Solutions
Application Performance Management Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Cloud Service Assurance Market