
 Global Asset Tracking and Inventory Management Solutions Market | 2026-2036
Global Asset Tracking and Inventory Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asset Tracking and Inventory Management Solutions Market Foresight
REACH is recalibrating the cost-of-entry calculus for asset tracking hardware imported into European manufacturing operations. Zebra Technologies dominates ruggedized mobile computing terminals deployed on factory floors. Honeywell International anchors its position through in-house production of precision RFID inlays and readers. Microsoft Corporation leverages Azure IoT cloud infrastructure to compete in enterprise-scale deployment contracts.
Asset tracking and inventory management solutions encompass integrated hardware-software systems that capture, transmit, and process location and status data through RFID tags, barcode scanners, GPS modules, IoT sensors, BLE beacons, and NFC chips operating across frequencies from 125 kHz to 5.8 GHz. These systems synchronize physical asset positions with enterprise resource planning databases to eliminate inventory shrinkage, reduce search times, and automate compliance documentation across supply chains. RFID Tracking solutions command the largest installed base in heavy-asset industries where metallic environments demand specialized tag engineering. Cloud-Based deployment is displacing on-premises infrastructure among mid-market logistics providers seeking elastic compute capacity without capital expenditure. Warehouse Management use cases generate the deepest software margins through integration with automated storage and retrieval systems.
The EU AI Act, FDA 21 CFR Part 820 quality system regulations, and ISO 55000 asset management standards collectively shape product certification pathways and data governance obligations for solution vendors. FDA requirements for unique device identification in healthcare equipment are mandating serialized tracking at the item level across hospital networks. Stakeholders must monitor how regulatory fragmentation between the EU AI Act's risk classification framework and FDA's predicate device logic will determine which platform architectures achieve cross-border deployability without costly re-engineering.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for mid-market logistics operators while EU AI Act compliance costs recalibrate vendor R&D budgets toward explainable automation.
Growth Catalysts
- FDA 21 CFR Part 820:Serialized tracking mandates for medical devices are forcing hospital networks to upgrade from facility-level to item-level RFID systems, expanding addressable hardware volumes.
- BLE beacon convergence with 5G private networks:Automotive assembly plants in Germany's industrial corridor now demand sub-asset-level traceability for tooling and work-in-process inventory.
- India's PLI scheme for electronics manufacturing:Contract manufacturers building capacity under the incentive program require automated inventory systems to qualify for production-linked benefits.
Market Restraints
- RFID inlay supply concentration:Precision antenna manufacturing clusters in Southeast Asia create single-source vulnerability for specialized metallic-environment tags.
- REACH substance restrictions:Compliance costs for adhesive and substrate materials in European-bound hardware are elevating working capital requirements for component suppliers.
- Passive UHF range limitations:Signal attenuation in liquid-dense pharmaceutical cold chains forces redundant infrastructure spend that on-premises deployments cannot amortize.
Strategic Opportunities
- Brazil's ANVISA track-and-trace mandates:Pharmaceutical distribution networks under serialization deadlines present first-mover advantage for cloud-based verification platforms.
- Digital twin convergence with RTLS:Heavy-asset operators in oil and gas are unifying physical tracking data with simulation environments for predictive maintenance workflows.
- EU CSRD scope expansion:Mandatory supply chain emissions disclosure is creating demand for carbon-accounting-integrated inventory systems among Tier-1 automotive suppliers.
Industry Challenges
- Embedded systems firmware expertise:Vendors face acute shortages of engineers capable of integrating multi-frequency RFID readers with edge AI processors.
- ISO 55000 certification timelines:Asset-intensive utilities require 18-24 month validation cycles that delay platform revenue recognition and strain cash conversion.
- Legacy ERP synchronization:Brownfield manufacturing sites running decades-old inventory databases resist API-based data exchange without costly middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asset Tracking and Inventory Management Solutions Market |
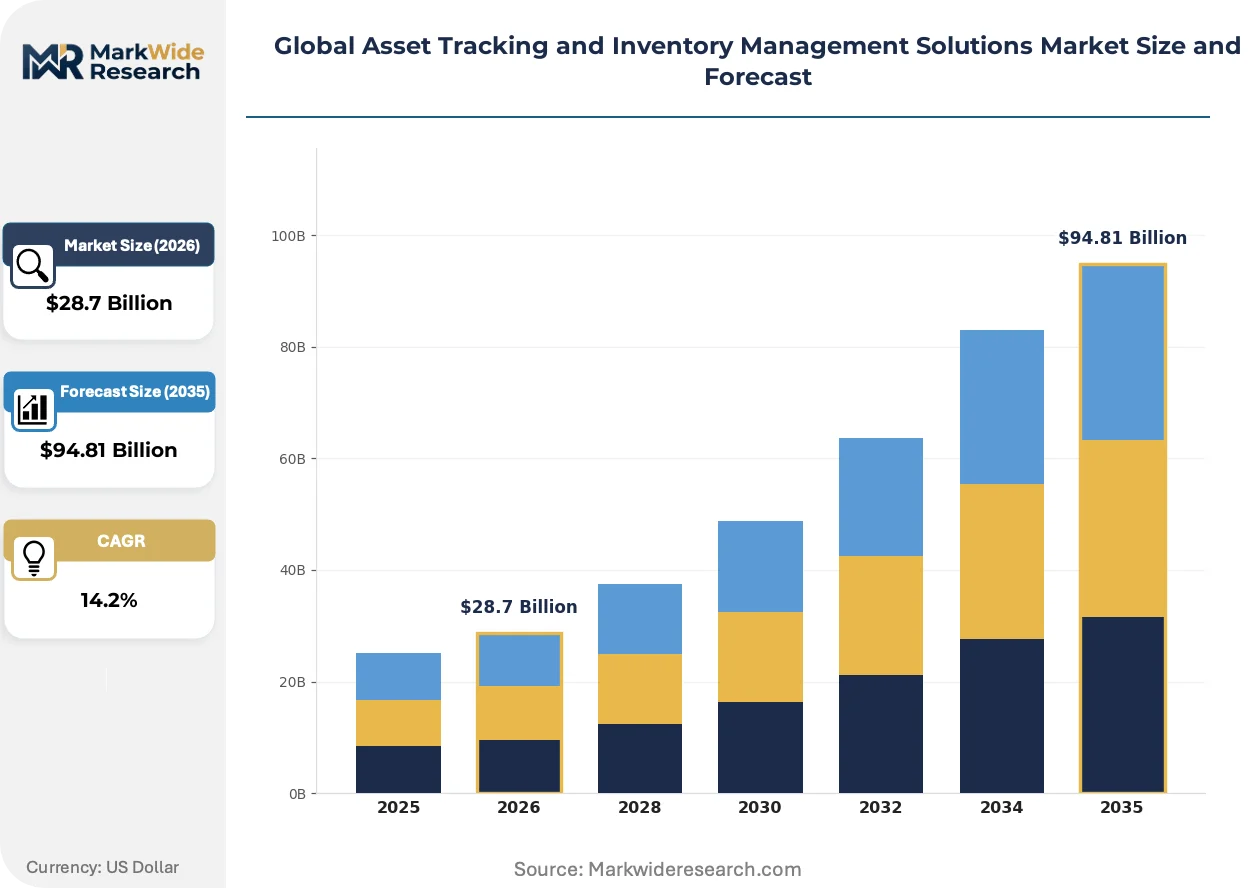
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
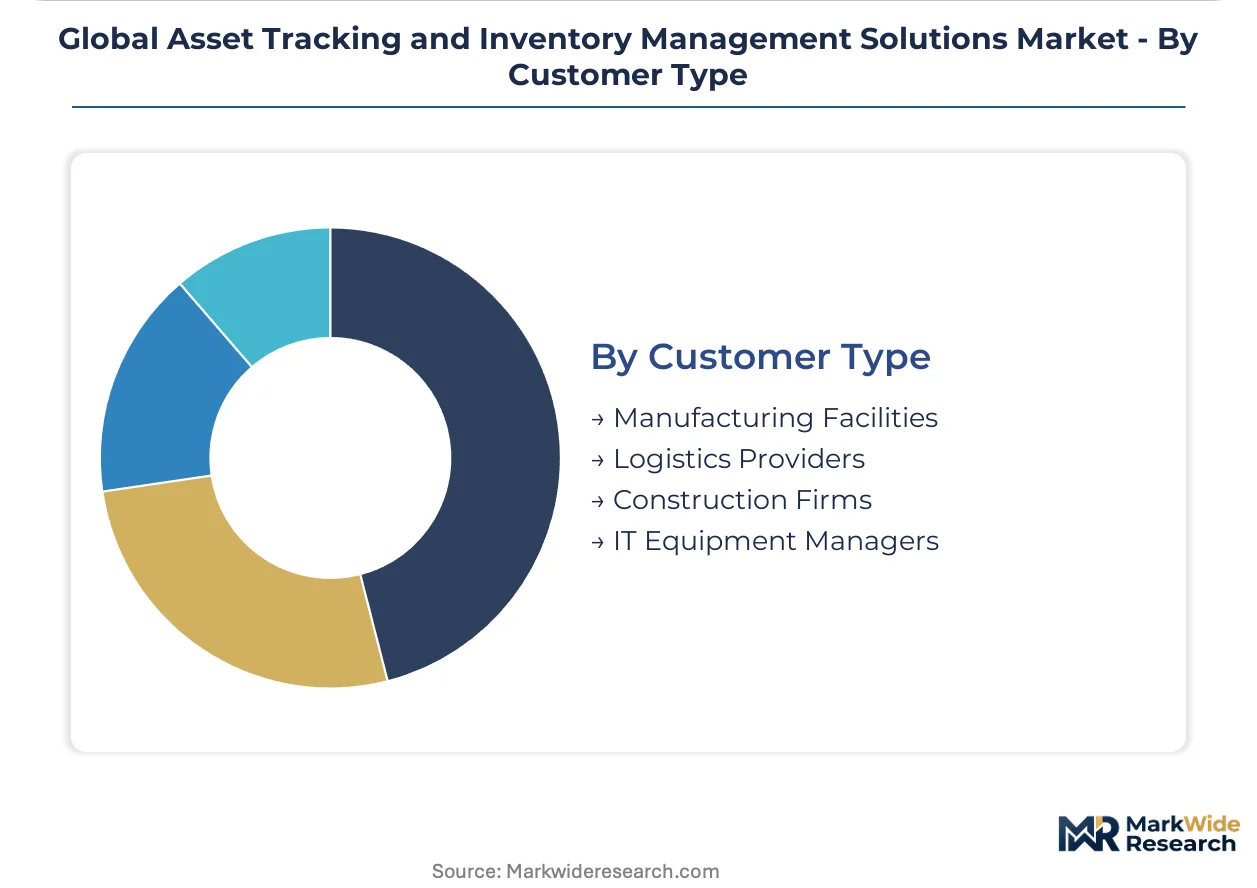
| Segmentation | Solution Type: RFID Tracking, Barcode Scanning, GPS Tracking, IoT Sensors, Bluetooth Low Energy, NFC Deployment Mode: Cloud-Based, On-Premises, Hybrid Configuration, Edge Computing Use Case: Warehouse Management, Fleet Monitoring, Tool Tracking, Inventory Optimization, Asset Lifecycle Customer Type: Manufacturing Facilities, Logistics Providers, Construction Firms, IT Equipment Managers |
| Companies Covered | Microsoft Corporation, ASAP Systems, Zebra Technologies Corporation, Asset Panda, GigaTrak, Honeywell International, Trimble, Cisco Systems, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asset Tracking and Inventory Management Solutions Market Shifts & Advancements
Multi-protocol edge devices are collapsing the hardware stack while regulatory disclosure obligations transform software from cost center to compliance infrastructure.
Ultra-wideband positioning chips operating at 6.5 GHz are unifying centimeter-level location accuracy with low-power consumption profiles. Pharmaceutical cold chain operators in the United States are deploying these modules at pilot scale ahead of FDA validation requirements. The technology is unifying previously separate temperature logging and spatial tracking into single-tag architectures, compressing unit economics for high-value biologics monitoring.
REACH authorization lists are expanding restricted substance categories for electronic components entering European manufacturing operations. ECHA's 2024 updates to SVHC thresholds are forcing RFID inlay producers to reformulate adhesives and antenna substrates. German automotive suppliers are responding by qualifying alternative material streams ahead of sunset dates, creating first-mover certification advantages for compliant vendors.
Subscription-based platform pricing is displacing perpetual license models among third-party logistics providers seeking operational expenditure treatment. Mid-market warehouse operators in the Netherlands are prioritizing vendors offering usage-based billing tied to scan volumes or tracked asset counts. This shift is most visible in e-commerce fulfillment networks where seasonal volume spikes demand elastic compute and storage capacity without capital commitment.
Global Asset Tracking and Inventory Management Solutions Market Segmentation
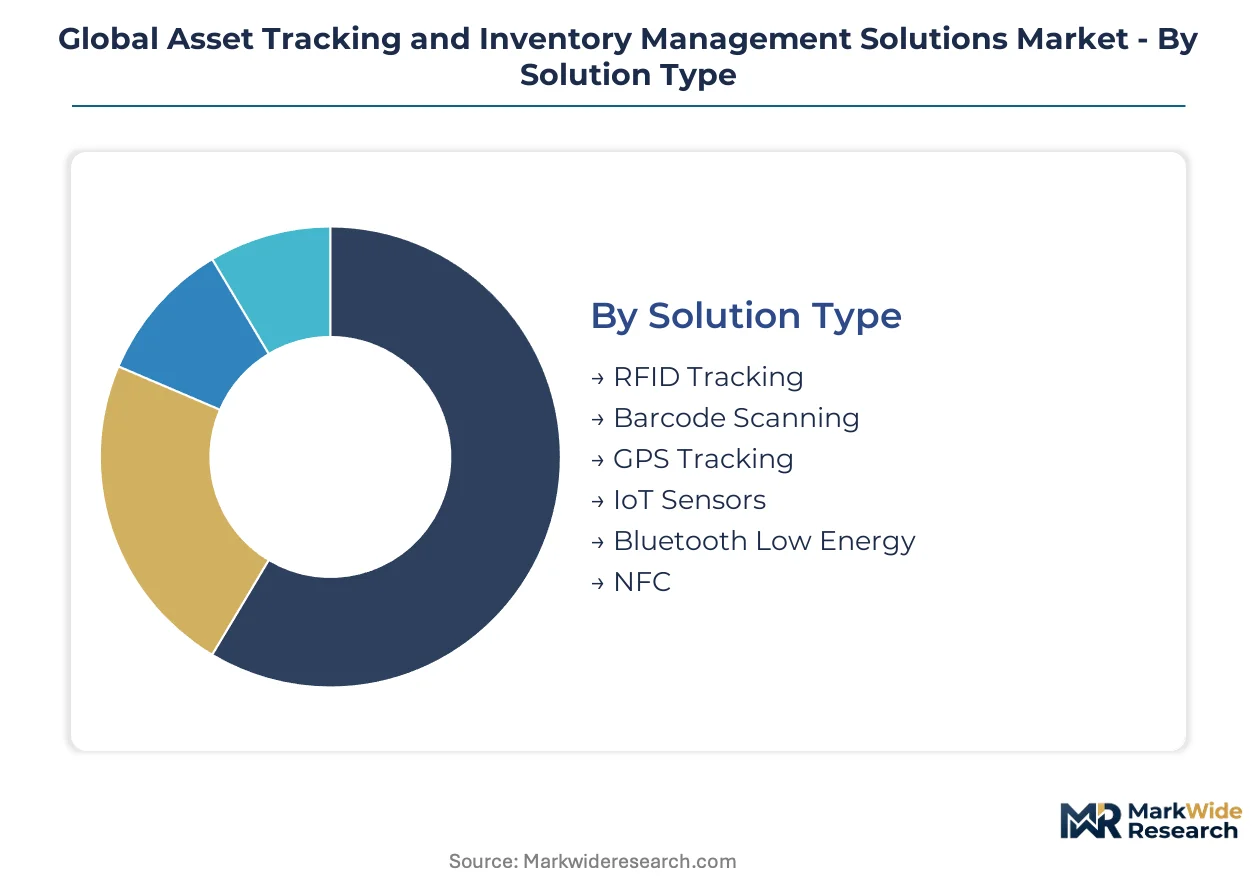
Asset tracking and inventory management solutions fragment across hardware protocols, infrastructure models, and operational contexts. Each segmentation axis carries distinct margin profiles and regulatory exposure that determine vendor positioning strategies.
Solution Type:
Standardization dominates at the radio-frequency layer while customization concentrates in tag engineering for metallic and liquid-dense environments.
- RFID Tracking:Passive UHF systems operating at 860-960 MHz anchor heavy-asset deployments in automotive and oil and gas sectors. German industrial corridors demand specialized inlay designs for tooling traceability on metal-rich assembly lines. REACH substance restrictions are elevating R&D costs for adhesive reformulation in European-bound hardware.
- Barcode Scanning:Linear and 2D imagers retain cost advantages in high-volume, short-range capture scenarios. Mid-market logistics providers in the Netherlands prioritize these terminals for warehouse management where line-of-sight constraints are manageable. Zebra Technologies dominates ruggedized mobile computing deployments on factory floors.
- GPS Tracking:Multi-constellation receivers enable meter-level positioning for fleet and container monitoring across extended geographic ranges.
- IoT Sensors:Multi-parameter environmental monitors unify location, temperature, and vibration telemetry for cold chain and predictive maintenance applications.
- Bluetooth Low Energy:BLE beacons operating at 2.4 GHz deliver sub-meter accuracy for indoor positioning with minimal power draw.
- NFC:13.56 MHz proximity interfaces enable tap-to-authenticate workflows for IT asset management and access control.
Leading the category by volume: RFID Tracking. Expanding most quickly: IoT Sensors.
Deployment Mode:
Capital intensity separates on-premises infrastructure from elastic cloud consumption patterns among mid-market operators.
- Cloud-Based:Subscription models displace perpetual licenses as third-party logistics providers seek operational expenditure treatment. Mid-market warehouse operators prioritize usage-based billing tied to scan volumes or tracked asset counts without capital commitment.
- On-Premises:Dedicated servers retain favor among defense contractors and critical infrastructure operators with data sovereignty requirements. Brownfield manufacturing sites running decades-old ERP systems resist API-based exchange without costly middleware layers.
- Hybrid Configuration:Edge-cloud splits process sensitive telemetry locally while aggregating analytics centrally.
- Edge Computing:Distributed processing nodes reduce latency for real-time location services in time-critical healthcare equipment tracking.
Cloud-Based deployments command the largest addressable base. Edge Computing exhibits the steepest expansion trajectory.
Use Case:
Software margin depth correlates with integration complexity against automated storage and material handling systems.
- Warehouse Management:Deep ERP and WMS integration generates recurring professional services revenue. Automated storage and retrieval system synchronization demands custom middleware development that extends implementation timelines.
- Fleet Monitoring:Telematics platforms combine GPS positioning with driver behavior analytics for compliance documentation. Brazil's ANVISA pharmaceutical distribution mandates create first-mover opportunities for verification-integrated platforms.
- Tool Tracking:Sub-asset-level traceability for calibration-critical equipment in aerospace and automotive tooling.
- Inventory Optimization:Demand-sensing algorithms reduce safety stock carrying costs for retail and e-commerce fulfillment networks.
- Asset Lifecycle:Condition-based maintenance scheduling extends useful life for heavy rotating equipment in utilities and oil and gas.
Warehouse Management leads by revenue concentration. Asset Lifecycle is gaining share fastest through digital twin convergence.
Customer Type:
Procurement sophistication ranges from centralized IT governance to distributed project-based purchasing across construction and field services.
- Manufacturing Facilities:Automotive and electronics contract manufacturers drive serialized tracking mandates. India's PLI scheme for electronics manufacturing requires automated inventory systems to qualify for production-linked incentives.
- Logistics Providers:Third-party and fourth-party operators prioritize multi-tenant platform architectures. Seasonal volume spikes in e-commerce fulfillment networks demand elastic compute without capital commitment.
- Construction Firms:Mobile equipment and material tracking across dispersed job sites with intermittent connectivity.
- IT Equipment Managers:Data center and enterprise device lifecycle management with financial compliance and audit trail requirements.
Manufacturing Facilities anchor demand by hardware volume. Logistics Providers represent the fastest-growing customer acquisition target.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's electronics manufacturing clusters under the PLI scheme are concentrating automated inventory demand among contract manufacturers seeking production-linked incentives. Special economic zones in Vietnam and Mexico are attracting automotive suppliers mandating sub-asset-level traceability.
United States
Hospital networks across the Midwest and Southeast are upgrading to item-level RFID systems under FDA 21 CFR Part 820 serialization mandates. The FDA's unique device identification requirements are forcing facility-level infrastructure replacement. Pharmaceutical cold chain operators in the Boston-Cambridge corridor are piloting ultra-wideband positioning chips ahead of validation deadlines.
Germany
Automotive suppliers in Baden-Württemberg and Bavaria now require sub-asset-level traceability for tooling and work-in-process inventory. REACH substance restrictions from ECHA are elevating compliance costs for RFID inlay adhesives entering European manufacturing operations. The Stuttgart industrial corridor is qualifying alternative material streams ahead of sunset dates.
China
Electronics contract manufacturers in the Yangtze River Delta are deploying automated inventory systems to meet export compliance requirements. MIIT standards for industrial internet platforms are shaping data governance obligations for solution vendors. Shenzhen-based logistics providers are prioritizing cloud-native architectures for elastic compute capacity.
Brazil
Pharmaceutical distribution networks under ANVISA track-and-trace mandates are creating first-mover opportunities for verification platforms. The national pharmaceutical regulator's serialization deadlines are compressing deployment cycles among mid-market operators. São Paulo state logistics hubs are migrating to subscription-based platform pricing for operational expenditure treatment.
India
Electronics manufacturing capacity building under the PLI scheme requires automated inventory systems to qualify for production-linked benefits. BIS certification pathways for industrial IoT devices are recalibrating vendor R&D budgets. Karnataka and Tamil Nadu contract manufacturers are driving serialized tracking hardware volumes.
Global Asset Tracking and Inventory Management Solutions Market Competitive Landscape
North American technology conglomerates anchor one tier; European industrial automation specialists hold differentiated positions in precision hardware. The vendor base organizes around three strategic archetypes: cloud infrastructure providers licensing enterprise-scale deployment contracts, ruggedized terminal manufacturers dominating factory floor deployments, and precision RFID engineering houses controlling inlay production. Competitive dynamics center on M&A activity consolidating middleware capabilities and strategic partnerships bridging legacy ERP synchronization gaps.
Among publicly traded technology providers, Microsoft Corporation and Oracle Corporation occupy positions anchoring cloud-native platform architectures. Zebra Technologies Corporation exemplifies the ruggedized mobile computing archetype deployed across manufacturing environments. These three entities represent distinct competitive vectors: enterprise software licensing, industrial hardware durability, and integrated hardware-software stack control.
| Leading Market Players |
|---|
| Microsoft Corporation |
| ASAP Systems |
| Zebra Technologies Corporation |
| Asset Panda |
| GigaTrak |
| Honeywell International |
| Trimble |
| Cisco Systems |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up hardware specialists have consolidated precision RFID inlay production across Southeast Asian manufacturing clusters, tightening supply discipline while subscription pricing models compress upfront capital barriers for mid-market logistics buyers in the Netherlands and Brazil.
Pricing Analysis
Short lead-time premiums separate urgent deployment contracts from standard procurement cycles in hospital network RFID upgrades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA-validated systems for pharmaceutical cold chains command substantial markups over uncertified warehouse management modules. Cost compression in passive UHF tags is intensifying because REACH-compliant adhesive reformulation elevates European-bound hardware production expenses. Third-party logistics providers exhibit acute price sensitivity due to seasonal volume volatility, while defense contractors with data sovereignty mandates demonstrate minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, China, and Vietnam anchor hub-and-spoke fulfillment patterns for ruggedized mobile computing terminals. Precision antenna manufacturing draws from copper substrate suppliers in Taiwan and specialized adhesive compounders in South Korea. Single-source vulnerability concentrates in metallic-environment tag engineering where German automotive qualification timelines create captive supplier relationships. Distribution runs through authorized industrial distributors serving factory automation channels rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework erects a compliance moat that favors incumbent vendors with existing explainable automation architectures, systematically excluding undercapitalized entrants from enterprise-scale healthcare and automotive deployment contracts.
For Market Incumbents: Anticipate margin erosion from cloud-native challengers by accelerating backward integration into precision RFID inlay production and securing REACH-compliant material streams ahead of ECHA sunset dates. Defensive consolidation of middleware capabilities will neutralize legacy ERP synchronization threats in brownfield manufacturing sites. For New Entrants and Emerging Players: The price-point gap between premium FDA-validated systems and economy-tier barcode scanning creates white-space opportunity in Brazil's ANVISA-mandated pharmaceutical distribution networks and India's PLI-driven electronics manufacturing clusters. Target mid-market warehouse operators with usage-based SaaS pricing tied to scan volumes. For Investors and Strategic Acquirers: Distressed-cycle entries favor firmware-integrated edge AI specialists in Germany's Stuttgart industrial corridor where ISO 55000 certification bottlenecks strain vendor cash conversion. Long-term viability hinges on digital twin convergence capabilities. Watch for FDA validation timeline acceleration as the signal indicating platform architecture consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA adhesive restrictions force RFID inlay producers to qualify alternative substrates ahead of European sunset deadlines. |
| Cloud-Native Platform Migration | Mid-market logistics providers in the Netherlands prioritize elastic compute capacity without capital expenditure commitment. |
| Ultra-Wideband Chip Integration | Boston-Cambridge pharmaceutical operators pilot 6.5 GHz modules to unify temperature logging with spatial tracking. |
| Digital Twin Convergence | Oil and gas heavy-asset operators unify physical RTLS data with simulation environments for predictive maintenance workflows. |
| BLE Beacon Private Network Deployment | German automotive suppliers demand sub-asset-level traceability for tooling across Baden-Württemberg assembly lines. |
Research Methodology
Independent corroboration across platform engineering directors, hospital biomedical equipment managers, automotive Tier 1 procurement leads, and third-party logistics CTOs underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR Part 820 guidance documents, ECHA REACH authorization lists, BIS industrial IoT certification pathways, and ANVISA pharmaceutical serialization mandates. Bottom-up hardware shipment analysis triangulates against top-down enterprise software licensing disclosures.
Comparable-period anchoring to historical RFID tag volume and cloud subscription bookings established baseline trajectory assumptions across the analysis window. Segmentation dimensions modeled include solution protocol, deployment architecture, use case integration complexity, and customer procurement sophistication. CAGRs were derived from installed base expansion rates and average revenue per unit trends in subscription versus perpetual license environments. Forecast inputs incorporate regulatory deadline acceleration scenarios and private 5G network deployment timelines.
Inputs from platform vendors and systems integrators were available through the study window; gaps in brownfield ERP system API documentation introduce uncertainty bands around middleware revenue recognition timing. Forecasts reflect documented assumptions regarding REACH compliance cost pass-through and FDA validation timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Legal Technology Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Microservices Architecture Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Condition Monitoring Software Market