
 Transport Management System Market | 2026-2036
Transport Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Management System Market Analysis
Cloud-native architecture is fragmenting legacy transport management stacks into modular API-first components. SAP SE leverages its embedded ERP footprint to anchor multimodal orchestration across European manufacturing networks. Oracle Corporation competes through autonomous logistics algorithms that reduce empty-mile incidence for North American fleet operators.
A transport management system constitutes a software platform that optimizes freight movement through real-time route algorithms, carrier selection protocols, and electronic data interchange with customs and warehouse systems. Its commercial purpose centers on minimizing landed cost per shipment while enforcing delivery-time compliance. Cloud-based deployment leads adoption as mid-market shippers abandon capital-intensive on-premises infrastructure; AI-enabled solutions capture expanding margin pools as predictive ETA and dynamic pricing modules displace rule-based dispatch logic. SaaS models now dominate new procurement cycles among retail and e-commerce end users seeking elastic capacity during peak seasons.
EU CSGD reporting requirements and the EU AI Act's risk-classification framework for automated routing decisions are reshaping vendor compliance roadmaps. The US DOT's electronic logging device mandates and FMCSA hours-of-service rules continue driving fleet telematics integration into core TMS workflows. India's DPIIT logistics efficiency directives and Germany's KBA commercial vehicle certification standards further fragment regulatory compliance across operational geographies. Stakeholders must evaluate whether their platform architecture can absorb jurisdiction-specific audit trails without fragmenting user experience.
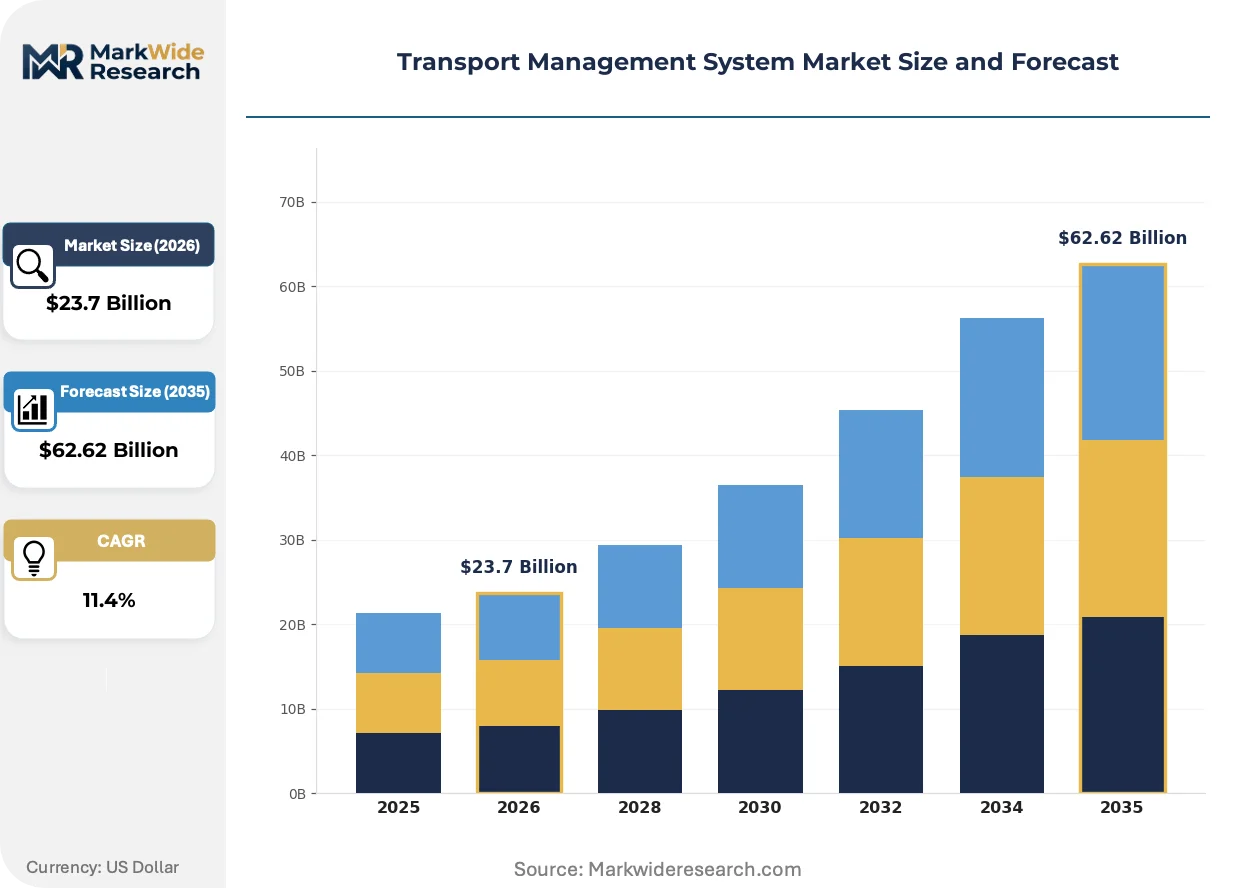
Market Dynamics
Cloud-first mandates from the EU AI Act and CSRD are fragmenting legacy transport management stacks, forcing mid-market shippers to abandon on-premises infrastructure for modular API-first architectures that embed compliance-by-design.
Growth Catalysts
- EU CSRD Reporting Mandates:Corporate sustainability disclosure requirements are accelerating procurement of carbon-tracking TMS modules among European manufacturing networks seeking audit-ready freight emissions data.
- Electronic Logging Device Integration:US DOT and FMCSA hours-of-service enforcement continues driving fleet telematics adoption into core TMS workflows for North American trucking operators.
- Freight Digitization in India:DPIIT logistics efficiency directives are concentrating platform investments among third-party logistics providers serving manufacturing corridors around Mumbai and Chennai.
Market Restraints
- Legacy System Entrenchment:Capital-intensive on-premises TMS installations in German automotive supply chains create switching friction that delays SaaS migration timelines.
- Regulatory Fragmentation:Jurisdiction-specific audit trail requirements from KBA certification standards in Germany, US DOT electronic logging mandates, and India's DPIIT directives force costly platform customization.
- API Interoperability Gaps:Proprietary data formats between competing TMS platforms limit seamless carrier selection protocol integration across multimodal freight networks.
Strategic Opportunities
- Predictive ETA Modules:AI-enabled dynamic routing algorithms represent white-space expansion for retail and e-commerce end users seeking elastic capacity during peak seasons.
- Customs-EDI Convergence:Integration of electronic data interchange with warehouse management systems creates new margin pools for platforms serving cross-border manufacturing networks.
- Empty-Mile Reduction Services:Autonomous logistics algorithms targeting backhaul optimization offer subscription revenue streams for fleet operators in North American long-haul corridors.
Industry Challenges
- Embedded ERP Integration Complexity:SAP-dominated European manufacturing networks require specialized implementation expertise to avoid multimodal orchestration workflow disruption.
- AI Risk Classification Compliance:EU AI Act's automated routing decision frameworks demand new internal audit functions that few mid-market TMS vendors have operationalized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Management System Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Route Planning, Freight Audit, Carrier Management, Shipment Tracking Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retail, Manufacturing, E-commerce, Logistics Technology: AI, IoT, Blockchain, Big Data |
| Companies Covered | Oracle Corporation, IBM Corporation, SAP SE, The Descartes Systems Group Inc., Manhattan Associates, MercuryGate International, Inc., JDA Software Group, Inc., Infor Inc., Trimble Transportation Enterprise Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Management System Market Emerging Trajectories
Real-time route algorithms are compressing dispatch cycles from batch-based planning to continuous optimization, reshaping how carriers and shorters negotiate capacity allocation across volatile freight markets.
Dynamic pricing engines is migrating from rule-based tariff systems to machine learning models that ingest spot market rates, fuel indices, and congestion data. Large retail shippers with seasonal volume spikes are adopting these modules fastest. The technology is compressing RFP cycles from annual to quarterly while fragmenting carrier contract structures into more granular lane-specific agreements.
REACH and EU AI Act compliance frameworks are mandating algorithmic transparency for automated routing decisions that affect driver hours and vehicle emissions. Industrial consequence includes mandatory documentation of training data provenance and model validation protocols. German freight networks serving automotive OEMs are most affected, responding by embedding compliance checkpoints directly into TMS workflow engines.
Shipper procurement patterns are compressing vendor evaluation cycles as cloud-native architectures reduce implementation risk. Retail and e-commerce buyers are displacing lengthy pilot programs with standardized API compatibility tests. This acceleration is most visible in United States cross-border freight corridors where seasonal demand volatility rewards rapid platform deployment.
Transport Management System Market Segmentation
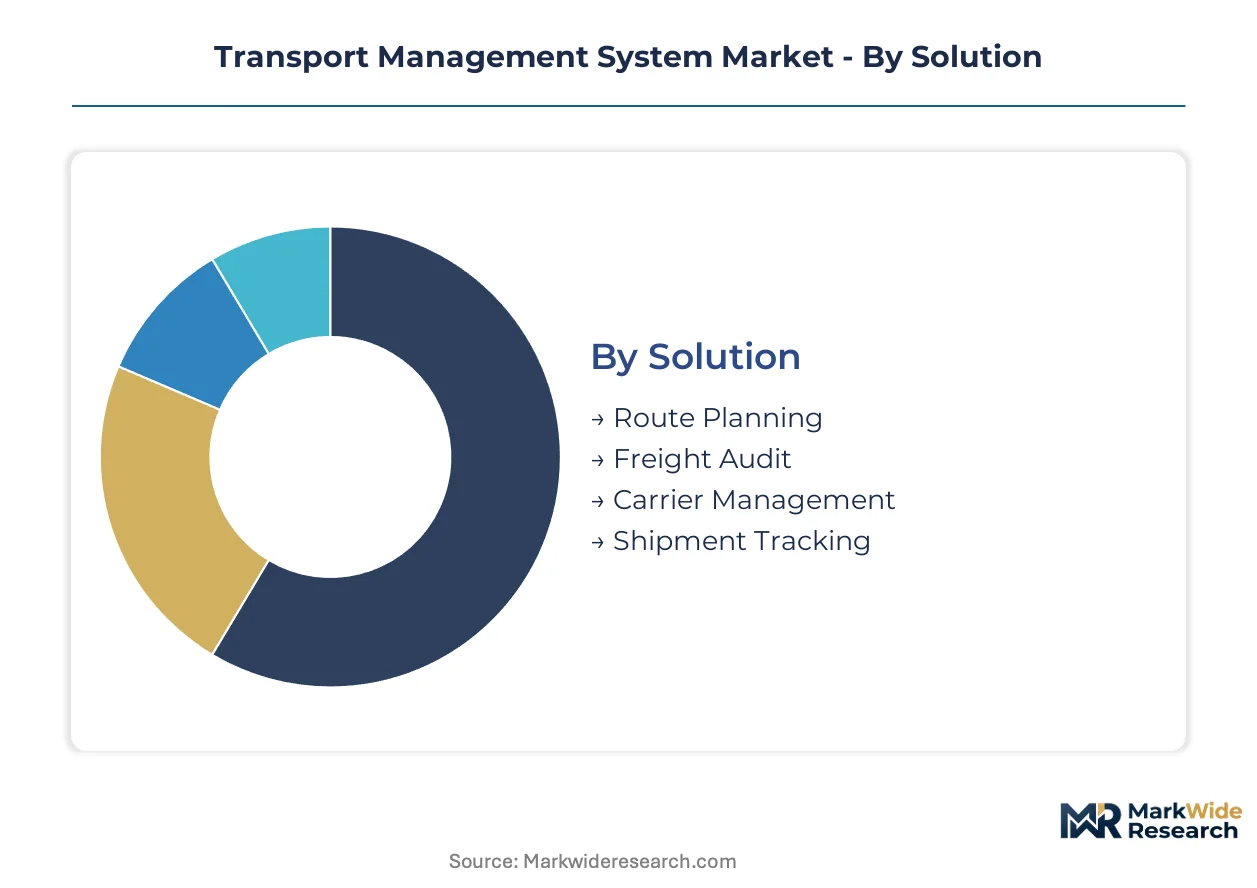
Transport management system procurement patterns diverge sharply across deployment models, end-use verticals, and technology stacks. Understanding these fault lines reveals where platform investments concentrate and which solution architectures capture expanding margin pools.
Solution:
Mature optimization modules dominate procurement budgets while emerging audit and compliance tools reshape vendor roadmaps.
- Route Planning:Core dispatch algorithms calculate multimodal paths using real-time congestion, fuel cost, and carrier capacity signals. German automotive supply chains and US cross-border freight corridors embed these engines directly into ERP workflows to compress planning cycles from batch to continuous optimization. Route Planning retains volume leadership; Carrier Management holds the steepest expansion curve.
- Carrier Management:Automated tendering and performance scorecarding platforms displace manual broker relationships. Retail shippers in India and e-commerce operators in the United States adopt these modules fastest to secure elastic capacity during peak seasons without long-term contract exposure.
- Freight Audit:Invoice validation engines match carrier bills against contracted rates and actual shipment events. Mid-market shippers deploy these tools to recover overcharge leakage in fragmented trucking markets.
- Shipment Tracking:Real-time visibility layers aggregate GPS, ELD, and warehouse milestone data into unified ETA predictions. These solutions concentrate among logistics providers serving just-in-time manufacturing networks.
Route Planning retains volume leadership; Carrier Management holds the steepest expansion curve.
Deployment:
Cost tier segmentation separates capital-intensive infrastructure commitments from elastic subscription models.
- Cloud-Based:Scalable compute architectures eliminate data center overhead while embedding automatic compliance updates for EU CSRD and US DOT mandates. European manufacturing networks and Indian third-party logistics providers lead migration away from owned infrastructure.
- SaaS:Per-shipment pricing models align vendor revenue with shipper volume volatility. Retail and e-commerce end users favor this structure to avoid fixed costs during seasonal demand troughs.
- On-Premises:Legacy installations persist in German automotive supply chains where ERP integration complexity and data residency requirements delay cloud migration timelines.
- Hybrid:Split architectures isolate sensitive planning data on local servers while routing execution workloads to cloud nodes. These configurations satisfy India's DPIIT directives and Germany's KBA audit trail standards without full infrastructure replacement.
Cloud-Based commands the largest installed base; SaaS demonstrates the most rapid customer acquisition velocity.
End User:
Application intensity varies by sector-specific volatility exposure and margin pressure.
- Retail:Seasonal volume spikes demand elastic capacity orchestration across fragmented carrier bases. These buyers prioritize dynamic pricing modules and rapid API deployment over deep customization.
- E-commerce:Same-day and next-day delivery promises require real-time inventory positioning and last-mile optimization. Platforms serving this vertical concentrate investment in predictive ETA algorithms.
- Manufacturing:Just-in-sequence production schedules mandate multimodal coordination with millisecond tolerance. German automotive OEMs and their tier suppliers anchor this segment with embedded ERP requirements.
- Logistics:Asset-light freight intermediaries seek backhaul optimization and empty-mile reduction to defend thin margins. North American long-haul corridors and Indian manufacturing clusters drive adoption here.
Manufacturing contributes the highest average contract value; E-commerce generates the fastest-growing new logo pipeline.
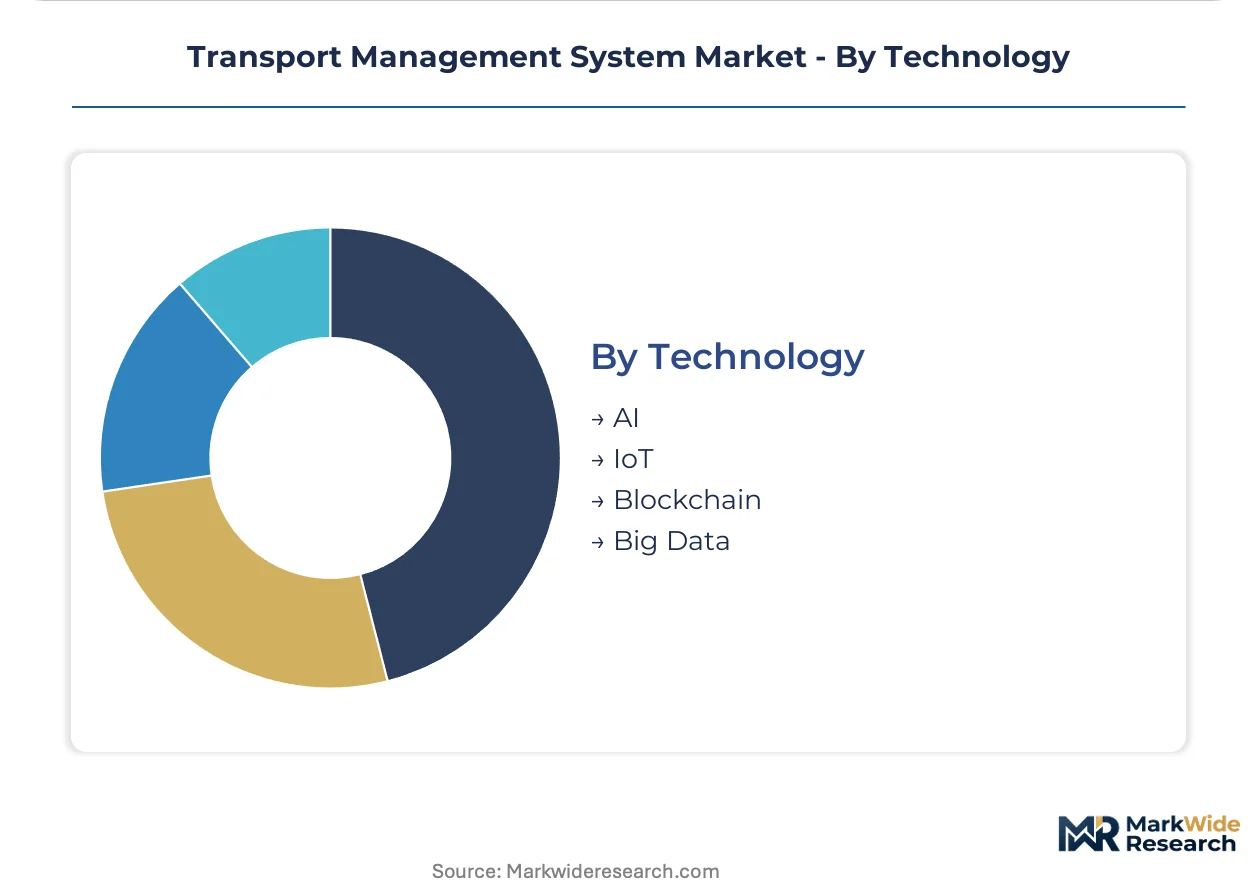
Technology:
Supply concentration among AI and IoT stack providers determines platform differentiation trajectories.
- AI:Machine learning models ingest spot market rates, weather patterns, and port congestion to generate dynamic routing decisions. EU AI Act risk-classification frameworks now mandate algorithmic transparency documentation for these systems.
- IoT:Sensor networks capture vehicle health, cargo condition, and driver behavior telemetry. US DOT electronic logging device mandates and FMCSA hours-of-service rules embed this layer into compliance workflows.
- Big Data:Historical freight pattern repositories enable predictive demand forecasting and lane-specific rate benchmarking. These capabilities concentrate among platforms with multi-year shipment archives.
- Blockchain:Distributed ledger applications address document authenticity and payment settlement in cross-border trade. Adoption remains exploratory due to interoperability gaps with legacy customs systems.
AI anchors current R&D expenditure; IoT delivers the most immediate compliance-driven procurement lift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Third-party logistics providers and retail shippers concentrate platform investments across manufacturing corridors and cross-border freight networks. Demand patterns diverge sharply between EU compliance-driven procurement and North American fleet telematics integration. Indian manufacturing clusters and German automotive supply chains anchor contrasting deployment models.
United States
Retail and e-commerce shippers drive dynamic pricing module adoption to manage seasonal volume volatility. US DOT electronic logging device mandates and FMCSA hours-of-service rules embed telematics into core TMS workflows. Cross-border freight corridors through Los Angeles-Long Beach and Chicago-Rockford concentrate multimodal orchestration investments.
Germany
Automotive OEMs and tier suppliers anchor embedded ERP requirements for just-in-sequence production schedules. KBA commercial vehicle certification standards and EU AI Act risk-classification frameworks mandate algorithmic transparency documentation. Manufacturing clusters in Stuttgart and Munich drive cloud migration delays due to data residency complexity.
India
Third-party logistics providers serving manufacturing corridors around Mumbai and Chennai concentrate platform investments. DPIIT logistics efficiency directives accelerate freight digitization mandates for mid-market shippers. The Delhi-Mumbai Industrial Corridor and Tamil Nadu automotive belt generate fastest-growing carrier management module procurement.
United Kingdom
Post-Brexit customs complexity drives electronic data interchange integration with warehouse management systems. CSRD reporting requirements accelerate carbon-tracking TMS module adoption among retail networks. The Midlands logistics hub and London distribution corridors concentrate SaaS procurement for elastic capacity management.
Japan
Precision manufacturing supply chains demand millisecond-tolerance multimodal coordination with embedded ERP systems. METI supply chain resilience directives promote domestic platform investment for critical component logistics. The Chubu-Nagoya automotive cluster and Kanto-Tokyo distribution networks anchor predictive ETA algorithm deployment.
Transport Management System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented vendor tiers. Enterprise software conglomerates anchor multimodal orchestration through embedded ERP footprints while pure-play logistics specialists capture elastic capacity segments. Strategic archetypes include compliance-embedded platform providers, API-first modular specialists, and fleet telematics integrators. Competitive moves concentrate on M&A for geographic expansion and strategic partnerships for customs-EDI convergence.
Among enterprise software providers, SAP SE and Oracle Corporation occupy positions as archetype anchors for ERP-embedded transport management. The Descartes Systems Group Inc. exemplifies the compliance-specialist tier. Manhattan Associates and MercuryGate International, Inc. sit within the logistics-native platform segment. These named entities represent structural positioning rather than specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| SAP SE |
| The Descartes Systems Group Inc. |
| Manhattan Associates |
| MercuryGate International, Inc. |
| JDA Software Group, Inc. |
| Infor Inc. |
| Trimble Transportation Enterprise Solutions, Inc. |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure providers in the United States and Ireland anchor upstream compute costs for TMS platforms, concentrating margin capture among vendors with captive data center capacity or long-term hyperscaler contracts. This concentration shapes downstream pricing power, as SaaS-native vendors pass through elastic compute costs while legacy on-premises installers absorb stranded infrastructure depreciation.
Pricing Analysis
Cost-plus contracts with fuel indexation dominate long-haul fleet management agreements, linking per-mile rates to DOE diesel indices and regional congestion surcharges. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive routing modules from basic dispatch tools and legacy on-premises licenses. Pricing pressure stems from mid-market shippers consolidating vendor relationships to reduce API integration overhead. Retail and e-commerce buyers exhibit highest price sensitivity due to seasonal volume troughs, while German automotive OEMs prioritize ERP compatibility over unit cost.
Supply Chain Analysis
Export-control restrictions on AI training hardware under US Commerce Department advanced computing rules limit GPU availability for European TMS vendors developing autonomous routing algorithms. Software development concentrates in the United States, Germany, and India, with implementation services drawing from specialized system integrator networks in each market. Cloud infrastructure, ELD telematics hardware, and customs data feeds constitute critical input dependencies. Single-source vulnerability runs through hyperscaler concentration for compute capacity. Distribution runs through direct enterprise sales teams serving manufacturing verticals and channel partners targeting mid-market logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as freight digitization mandates from India's DPIIT and EU CSRD compliance deadlines compress replacement timelines for legacy systems.
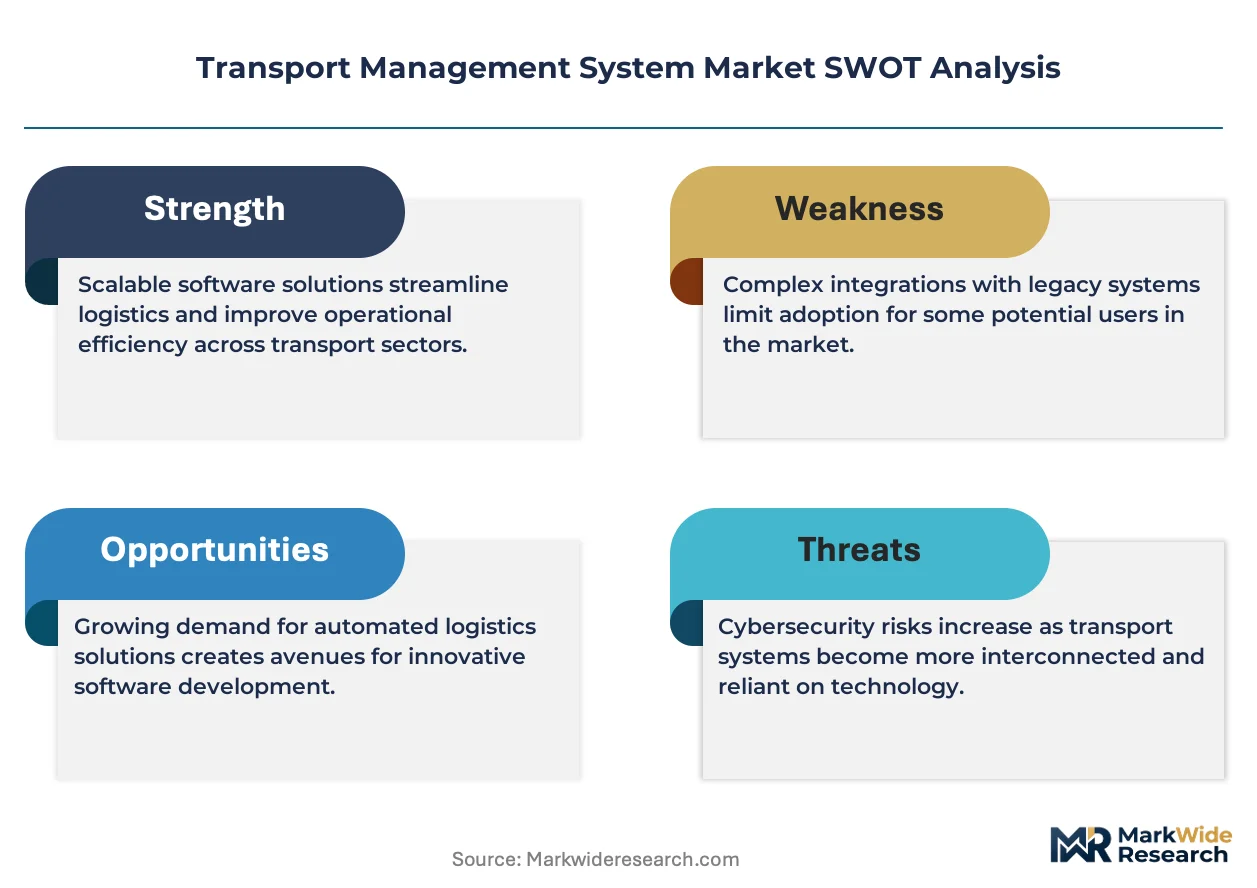
For Market Incumbents: Pre-empt SaaS-native challengers by embedding compliance-by-design modules for EU AI Act risk classification before mid-market vendors operationalize audit functions. Consolidate around customs-EDI convergence capabilities to capture cross-border manufacturing network spend. Vertical integration into ELD hardware partnerships defends against telematics-agnostic platform entrants. For New Entrants and Emerging Players: Build out API-first modular architectures targeting Indian third-party logistics providers in Mumbai and Chennai manufacturing corridors, where DPIIT directives accelerate procurement without entrenched ERP switching costs. White-space expansion concentrates in predictive ETA modules for retail peak-season elasticity. Go-to-market leverage rests on standardized compatibility testing displacing lengthy pilot programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed logistics-native platforms that have consolidated regional carrier networks but lack AI-enabled routing layers. Long-term viability hinges on compliance-embedded architecture absorbing jurisdiction-specific audit requirements without fragmenting user experience. Watch for inflection when EU AI Act enforcement triggers mandatory algorithmic transparency documentation among German automotive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded ERP connectivity with SAP SE and Oracle Corporation anchors multimodal orchestration workflows. |
| Strategic Partnership | Customs-EDI convergence with warehouse management systems captures cross-border manufacturing margin pools. |
| Product Launch | AI-enabled dynamic pricing modules compress RFP cycles from annual to quarterly for retail shippers. |
| Acquisition of Specialist Firm | Empty-mile reduction algorithms from fleet telematics integrators expand subscription revenue in North American corridors. |
| Geographic Expansion | Cloud-first deployment in Indian manufacturing clusters around Chennai leverages DPIIT digitization mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EU regulatory disclosure databases, and customs trade data covering software and logistics services. Interviews with TMS product managers, fleet operations directors at third-party logistics providers, IT procurement officers at retail networks, and compliance leads at automotive OEMs inform demand-side validation. Top-down market sizing triangulates against bottom-up vendor revenue aggregation across deployment models and end-use verticals.
Forecast inputs include cloud infrastructure capex disclosures, ELD mandate enforcement timelines from the US DOT, and EU AI Act implementation guidance from national regulators. Segmentation models capture solution type, deployment architecture, end-user vertical, and technology stack complexity across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves weighted by regulatory compliance deadlines and ERP replacement cycles. Freight digitization intensity indices and carrier consolidation rates inform corridor-specific growth assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed logistics platforms would shift outcomes. Material shifts in EU AI Act enforcement stringency or US DOT hours-of-service rule modifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Indonesia Enterprise Mobility Management Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Europe API Management Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Digital Signature Market
Digital Solutions
Automatic Identification and Data Capture Market