
 Canada ICT Market | 2026-2036
Canada ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Canada ICT Market Insights
Silicon photonics is rebalancing interconnection economics inside Canadian data centers, cutting energy per bit and extending rack density limits. Shopify leverages merchant-facing AI infrastructure to sustain platform stickiness across North American e-commerce. CGI anchors federal digital transformation contracts through decades of Ottawa presence. Telus competes on 5G network coverage in Western Canada, differentiating its enterprise IoT offerings against national rivals.
Information and communications technology encompasses hardware, software, and services enabling data creation, transmission, storage, and processing across enterprise and consumer environments, operating through standards including 100 Gbps+ optical transport and IPv6 addressing protocols. Cloud-based deployment leads enterprise migration as firms abandon capital-intensive on-premises infrastructure for operational expenditure models. Managed security services represent the fastest-growing service type as ransomware frequency elevates cybersecurity to board-level priority. AI technology commands concentrated R&D investment, though IoT integration in resource extraction sustains distinct Canadian demand patterns.
Health Canada and the Canadian Centre for Cyber Security shape product standards through medical device software validation and critical infrastructure protection frameworks, while Innovation, Science and Economic Development Canada directs spectrum allocation and broadband subsidy programs. The Personal Information Protection and Electronic Documents Act governs cross-border data flows, compelling cloud providers to maintain domestic processing capabilities. Stakeholders must monitor forthcoming artificial intelligence regulation under the proposed Artificial Intelligence and Data Act for compliance architecture decisions.
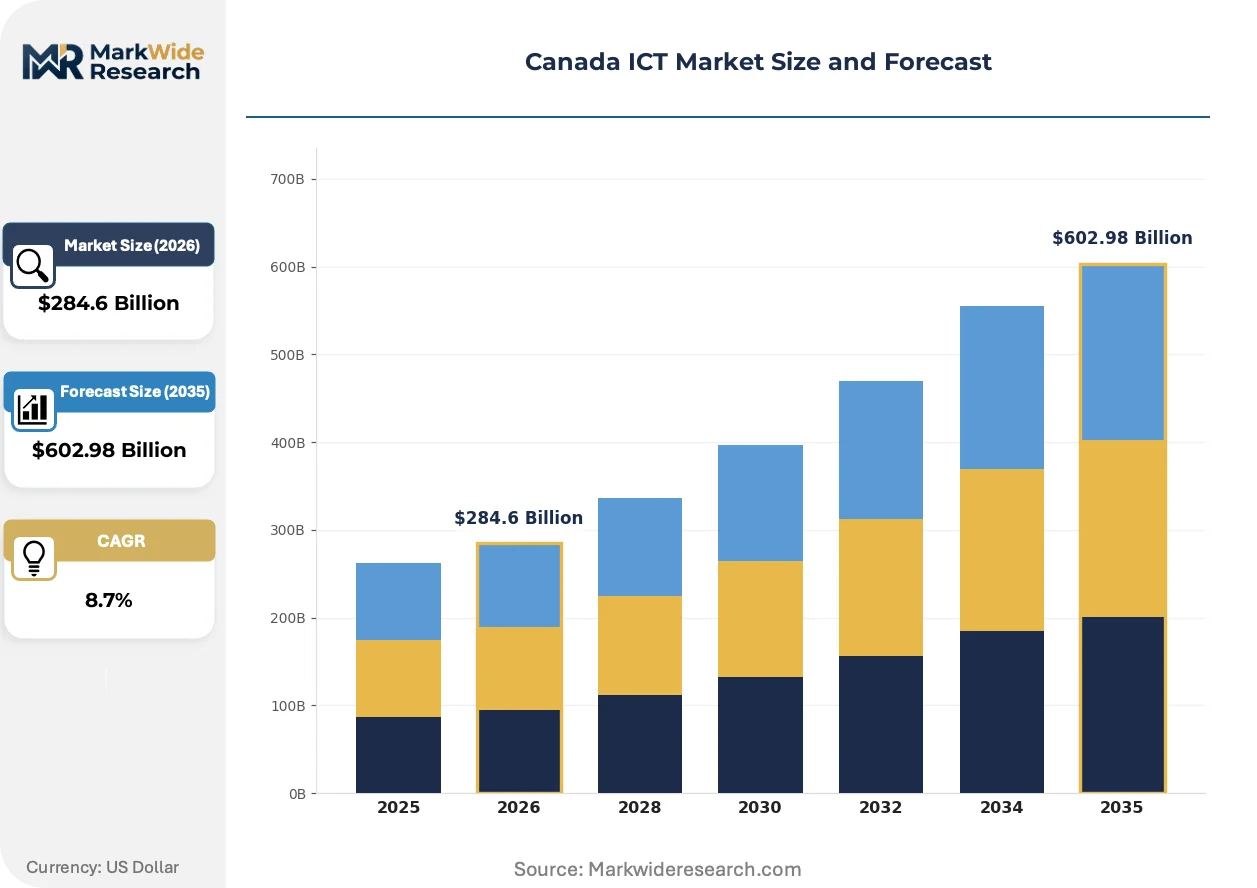
Market Dynamics
Federal cloud-first procurement mandates are compressing public sector modernization timelines while silicon photonics deployment inside Canadian data centers rebalances interconnection economics. Health Canada software validation requirements and proposed AI regulation under the Artificial Intelligence and Data Act are forcing compliance architecture investments across enterprise software stacks.
Growth Catalysts
- Health Canada medical device software validation:Diagnostic AI deployment in provincial healthcare systems is expanding compute infrastructure procurement requirements.
- Ontario financial services concentration:Toronto's banking sector anchors enterprise software demand for risk analytics and regulatory reporting platforms.
- Federal cloud-first procurement:Treasury Board directives are accelerating public sector migration from capital-intensive on-premises infrastructure to operational expenditure models.
Market Restraints
- Domestic cloud processing requirements:PIPEDA cross-border data flow restrictions compel providers to maintain Canadian data center footprints, elevating operational costs.
- Specialized photonics engineering talent:Silicon photonics design and packaging expertise concentrates in Ottawa and Vancouver corridors, creating hiring bottlenecks.
- Spectrum allocation delays:Innovation, Science and Economic Canada auction timelines constrain 5G network densification schedules in Western Canada.
Strategic Opportunities
- Alberta resource extraction IoT:Oil sands operators are deploying predictive maintenance sensors across remote extraction sites, creating managed connectivity demand.
- Quebec AI compute clusters:Provincial hydroelectric surplus is attracting hyperscale data center investments for machine learning training workloads.
- Atlantic broadband subsidy programs:Universal service fund deployments are extending fiber infrastructure to underserved rural municipalities.
Industry Challenges
- Artificial Intelligence and Data Act compliance architecture:Proposed federal AI regulation requires algorithmic impact assessment capabilities that most mid-market software vendors lack.
- Legacy healthcare system integration:Provincial electronic health record platforms resist API standardization, complicating diagnostic AI deployment.
- Photonics packaging yield rates:Silicon photonics module manufacturing defect rates elevate unit economics for domestic optical interconnect suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada ICT Market |
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $602.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Service Type: Consulting, Integration, Support, Managed Security End User: SMEs, Large Enterprises, Government, Educational Institutions Technology: AI, Blockchain, IoT, Big Data |
| Companies Covered | Shopify Inc., CGI Inc., Constellation Software Inc., Bell Canada, Telus Communications Inc., Rogers Communications Inc., OpenText Corporation, Celestica Inc., Amazon Web Services, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada ICT Market Trends and Innovations
Silicon photonics is compressing energy-per-bit economics inside hyperscale facilities while federal AI regulation forces algorithmic transparency investments. Procurement patterns across Ontario financial services are favoring consumption-based licensing over perpetual software ownership.
Silicon photonics co-packaged optics is electrifying rack-scale interconnect economics by collapsing electrical signaling distances inside data centers. Shopify and other Toronto-based hyperscalers are deploying 800G optical links at accelerated refresh cycles. This technology is electrifying density limits previously constrained by copper power dissipation, enabling 100kW+ rack configurations.
The proposed Artificial Intelligence and Data Act is mandating algorithmic impact assessments for high-risk AI systems before commercial deployment. Health Canada is aligning medical device software validation with these transparency requirements. Diagnostic imaging vendors serving Ontario and Quebec hospitals are restructuring quality management systems to accommodate pre-market documentation obligations.
Consumption-based enterprise software licensing is displacing perpetual ownership models across Toronto financial services procurement. Royal Bank of Canada and TD Bank are negotiating usage-metered contracts for risk analytics platforms. This shift is most visible in Ontario capital markets technology budgets, where operational expenditure treatment aligns with Basel liquidity reporting requirements.
Canada ICT Market Segmentation
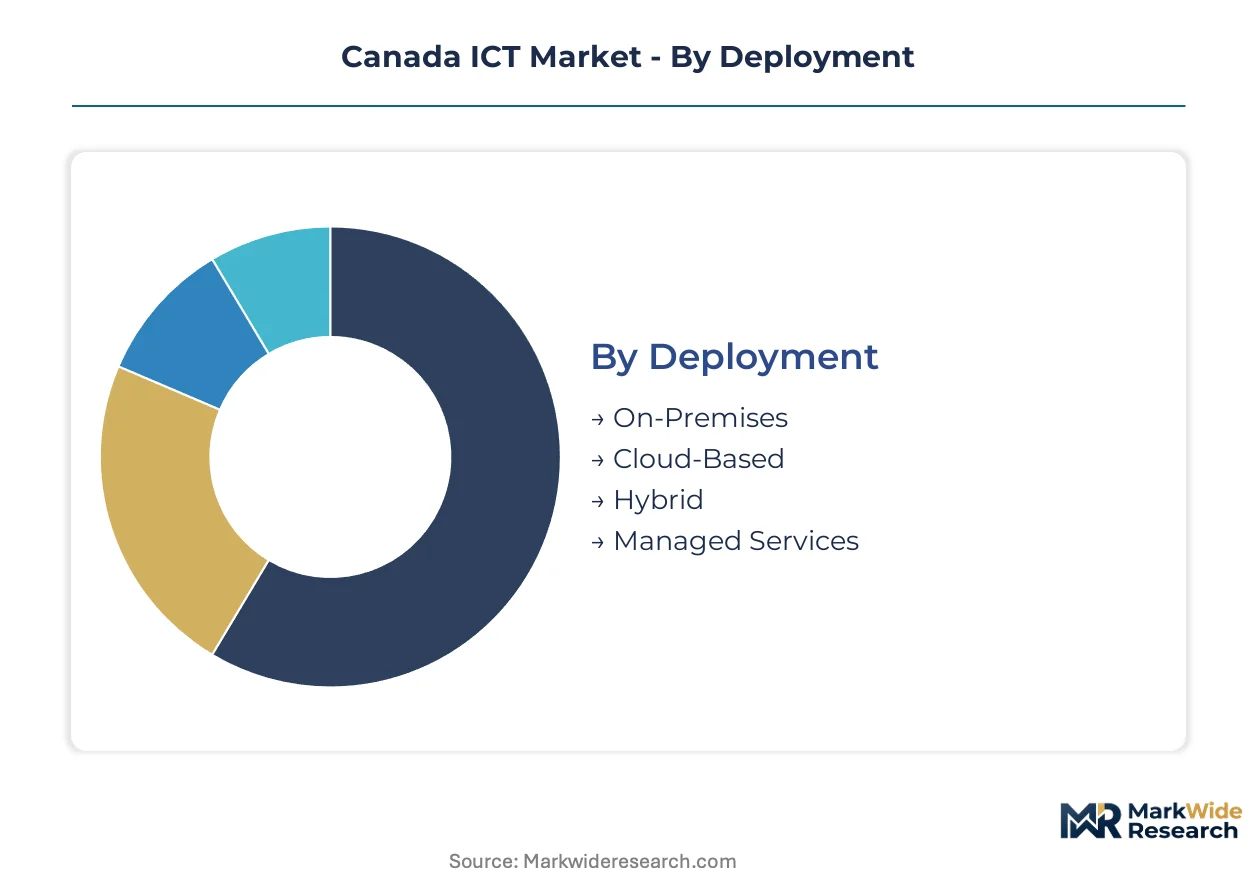
Deployment architecture determines procurement authority and capital allocation across Canadian ICT procurement. Service type selection reflects organizational cybersecurity maturity and internal technical capacity. Understanding how buyers navigate these dimensions clarifies vendor positioning and channel strategy.
Deployment:
Capital expenditure constraints versus operational flexibility governs infrastructure decisions across federal and provincial procurement.
- Cloud-Based:Treasury Board cloud-first mandates accelerate federal migration from owned infrastructure to consumption models. Ontario healthcare authorities and Quebec financial institutions lead enterprise adoption, driven by disaster recovery requirements and elastic compute scaling for seasonal workloads.
- Hybrid:Organizations maintain sensitive workloads on-premises while bursting to public cloud for variable demand. Alberta resource operators and Health Canada regulated entities favor this architecture to satisfy data residency requirements under PIPEDA while accessing advanced analytics services.
- On-Premises:Legacy core banking systems and classified government networks retain owned infrastructure for air-gapped security. Concentrated in Department of National Defence and established Toronto financial institutions with sunk capital investments.
- Managed Services:Third-party operational handoff appeals to mid-market firms lacking specialized IT talent. Atlantic Canada SMEs and municipal governments leverage managed service providers for 24/7 coverage without headcount expansion.
Cloud-based deployment leads on scale; managed services leads on momentum.
Service Type:
Internal capability gaps determine outsourcing depth, with cybersecurity talent scarcity elevating managed security above commoditized support contracts.
- Managed Security:Ransomware frequency and federal critical infrastructure protection frameworks compel 24/7 threat monitoring outsourcing. Royal Bank of Canada and Telus enterprise divisions anchor demand, with Health Canada validation requirements adding compliance complexity.
- Integration:Legacy system modernization across provincial healthcare and federal departments requires specialized middleware expertise. CGI and systems integrators dominate Ottawa-Gatineau corridors, connecting siloed databases to modern API architectures.
- Consulting:Strategic guidance on AI governance and cloud migration roadmaps. Toronto financial services procurement favors boutique firms for regulatory technology implementations.
- Support:Break-fix and maintenance contracts for established enterprise software estates. Stable demand from manufacturing and logistics sectors with conservative technology refresh cycles.
Integration commands the largest contract values; managed security exhibits the steepest expansion trajectory.
End User:
Budget scale and procurement complexity separate segments, with government buyers subject to strict vendor qualification and competitive bidding regimes.
- Government:Federal and provincial procurement operates through standing offers and supply arrangements with pre-qualified vendors. Shared Services Canada consolidates infrastructure buying power, while individual departments retain application discretion.
- Large Enterprises:Toronto-Dominion Bank, Shopify, and Suncor Energy anchor demand for custom development and advanced analytics. Direct vendor relationships and private cloud deployments characterize this segment.
- SMEs:Subscription-based SaaS consumption dominates, with sector-specific vertical solutions gaining traction. Vancouver technology startups and Prairie agricultural operations represent distinct demand profiles.
- Educational Institutions:Provincial funding cycles drive lumpy procurement, with research-intensive universities prioritizing high-performance computing and AI compute clusters.
Large enterprises lead on absolute spend; government leads on contract predictability.
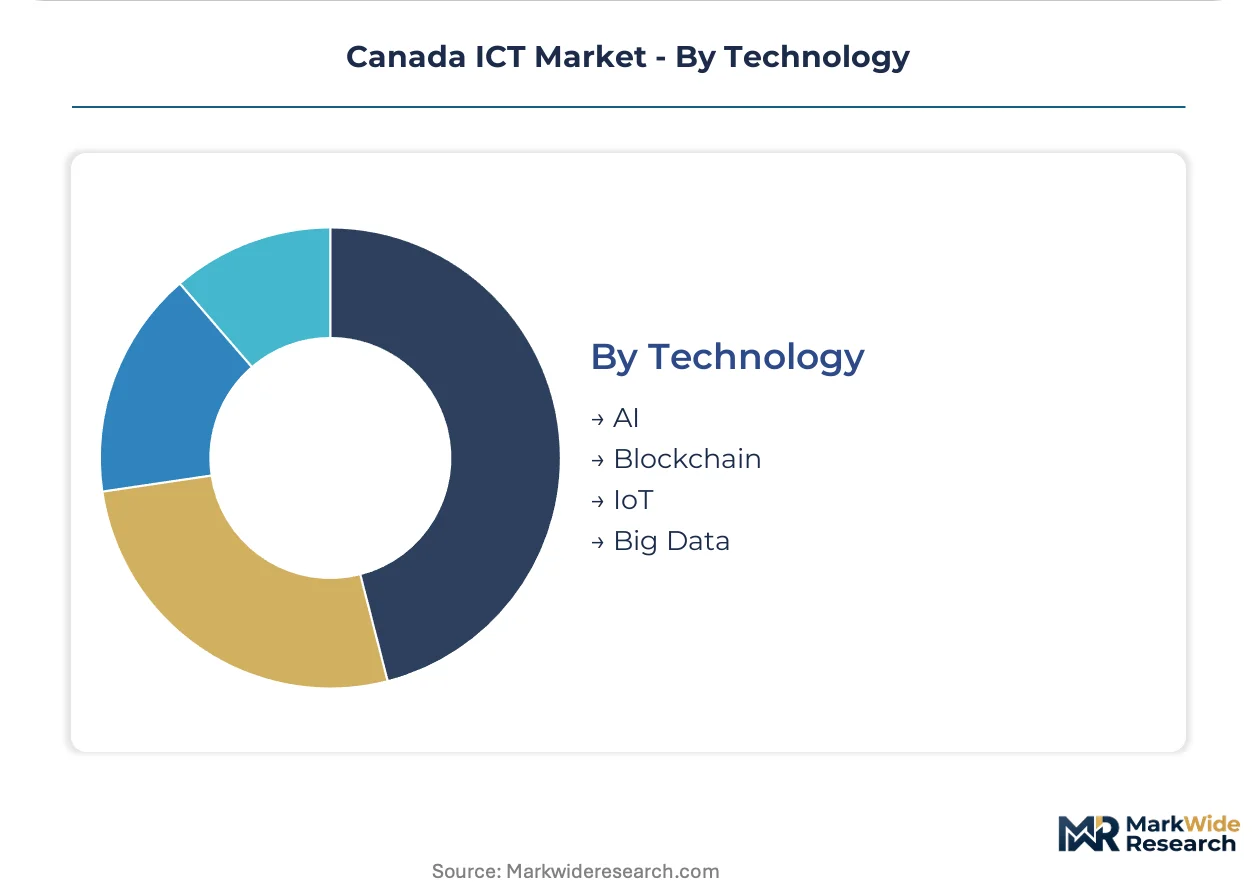
Technology:
Maturity curves and implementation complexity separate near-term deployable solutions from experimental architectures requiring specialized talent.
- AI:Diagnostic imaging deployment in Ontario and Quebec hospitals, plus merchant-facing recommendation engines at Shopify, anchor commercial demand. Proposed Artificial Intelligence and Data Act compliance architecture adds implementation overhead.
- IoT:Predictive maintenance sensors across Alberta oil sands and British Columbia forestry operations create ruggedized hardware demand. Telus 5G network coverage in Western Canada supports remote connectivity requirements.
- Big Data:Risk analytics platforms at Toronto financial institutions and fraud detection systems at payment processors. Regulatory reporting requirements under Basel frameworks sustain investment.
- Blockchain:Supply chain provenance pilots and digital identity experiments. Concentrated in consortia arrangements among financial services incumbents, with limited production deployment outside capital markets settlement trials.
AI dominates current investment flows; IoT gains share fastest in resource extraction verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Toronto-Waterloo corridor anchors national ICT demand through financial services concentration and hyperscale data center development.
Ontario
Toronto's banking sector and Kitchener-Waterloo technology cluster drive enterprise software procurement and AI infrastructure investment. Treasury Board cloud-first mandates accelerate federal migration through Ottawa-Gatineau procurement corridors. Shopify anchors merchant-facing platform development while provincial healthcare authorities expand diagnostic compute clusters.
Quebec
Montreal's AI research institutes and low-cost hydroelectric power attract hyperscale data center investments for machine learning training workloads. Innovation, Science and Economic Development Canada spectrum auctions enable 5G network densification priorities. Quebec City anchors provincial government digital transformation through shared services consolidation.
Alberta
Calgary's energy sector headquarters and oil sands extraction operations create ruggedized IoT hardware demand for predictive maintenance deployment. Provincial carbon reduction mandates accelerate industrial sensor network adoption. Edmonton anchors healthcare AI pilot programs through cross-provincial diagnostic imaging consortia.
British Columbia
Vancouver's technology startup ecosystem and Asia-Pacific trade gateway status sustain SaaS development and cloud infrastructure demand. Telus 5G network coverage in Western Canada supports enterprise IoT connectivity requirements. Victoria anchors provincial government cybersecurity procurement through critical infrastructure protection frameworks.
Atlantic Canada
Universal broadband subsidy programs extend fiber infrastructure to underserved rural municipalities across Nova Scotia and New Brunswick. Atlantic Canada SMEs leverage managed service providers for 24/7 coverage without headcount expansion. Halifax anchors regional cybersecurity operations centers through federal defense procurement proximity.
Canada ICT Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and telecommunications verticals, producing a tiered structure where hyperscale providers anchor platform layers while domestic specialists capture regulated sector contracts. Three archetypes dominate: vertically integrated telecommunications conglomerates, enterprise software platforms with sector-specific customization depth, and hyperscale cloud providers with compliance-adapted domestic footprints. Competitive moves concentrate on strategic partnerships for AI capability access and geographic expansion through provincial procurement channel development.
Within the domestic platform tier, Shopify Inc. and CGI Inc. exemplify divergent specialization models—merchant-facing commerce infrastructure versus government systems integration—while OpenText Corporation occupies a position in enterprise information management. Constellation Software Inc. represents the vertical software consolidator archetype through decentralized operating group structures. These Canadian-domiciled entities anchor mid-market and public sector procurement against American hyperscale entrants.
| Leading Market Players |
|---|
| Shopify Inc. |
| CGI Inc. |
| Constellation Software Inc. |
| Bell Canada |
| Telus Communications Inc. |
| Rogers Communications Inc. |
| OpenText Corporation |
| Celestica Inc. |
| Amazon Web Services, Inc. |
| Others |
Pricing and Supply Chain Analysis
Federal carbon reduction mandates gate qualified supply for data center infrastructure and premium-tier pricing access for energy-efficient compute deployments. Health Canada software validation requirements add compliance certification premiums to medical device platforms, compressing margins for vendors lacking domestic engineering presence.
Pricing Analysis
Input-cost pass-through from silicon photonics components and hydroelectric power tariffs shapes enterprise infrastructure pricing. Consumption-based SaaS licensing dominates Toronto financial services procurement, with price differentiation resting on Health Canada validation tier and disaster recovery SLA grade. Cost compression in mid-market managed security services is intensifying because talent scarcity elevates operational overhead. Atlantic Canada SMEs exhibit highest price sensitivity; federal departments show lowest due to standing offer procurement frameworks.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for advanced semiconductor fabrication and China for optical component assembly. Canadian ICT hardware draws from South Korea for memory modules and Japan for precision manufacturing equipment. Tariff exposure on networking gear imported through Vancouver port facilities elevates landed costs for Western Canada deployments. Distribution runs through Toronto-Gatineau corridors for federal procurement and Calgary-Edmonton channels for Alberta resource sector connectivity contracts.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quebec's hydroelectric surplus against Ontario's constrained grid capacity creates a geographic-arbitrage play for hyperscale data center operators seeking marginal compute cost advantages.
For Market Incumbents: Extend federal digital transformation contract coverage through Ottawa-Gatineau channel deepening against CGI's entrenched position. Invest in Health Canada validation certification to defend premium pricing on diagnostic AI platforms. Vertical integration into silicon photonics packaging addresses photonics engineering talent scarcity in Vancouver corridors. For New Entrants and Emerging Players: Atlantic Canada municipal governments represent an underserved buyer archetype with universal broadband subsidy tailwinds and limited incumbent MSP saturation. Target rural healthcare authorities in Nova Scotia and New Brunswick for managed security services penetration. Partner with existing fiber infrastructure deployers to accelerate channel access without capital-intensive network buildouts. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical software consolidators with Constellation Software-like decentralized operating models and sticky government maintenance revenue. Five-to-ten year viability favors targets with embedded PIPEDA compliance architecture and standing offer eligibility. Watch Treasury Board cloud-first procurement acceleration as inflection signal for public sector modernization spend velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Validation Investment | Unlocks diagnostic AI deployment in Ontario and Quebec hospital procurement channels. |
| Quebec Hyperscale Data Center Buildout | Leverages provincial hydroelectric surplus for machine learning training workload cost advantage. |
| Silicon Photonics Packaging Acquisition | Captures Ottawa and Vancouver engineering talent for domestic optical interconnect supply. |
| Federal Cloud Migration Partnership | Positions vendor for Shared Services Canada infrastructure consolidation contracts. |
| Atlantic MSP Channel Development | Extends 24/7 coverage to rural municipalities through managed service provider networks. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core of this study. Primary interviews with federal procurement officers, provincial health authority CTOs, hyperscale platform engineers, and managed service provider executives combined with secondary validation from Treasury Board contracting disclosures, Innovation Science and Economic Development Canada spectrum allocation records, Health Canada device licensing databases, and hyperscaler capital expenditure filings. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Historical trendline analysis of federal IT spending patterns and provincial healthcare digitization budgets established baseline growth trajectories. The forecast framework models deployment architecture, service type, end user scale tier, and technology maturity curve across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves for cloud migration and AI infrastructure investment. Industry-specific inputs include Treasury Board cloud-first mandate implementation velocity and silicon photonics refresh cycle acceleration at Toronto hyperscalers.
Underlying measurement precision varies by segment; federal procurement and large enterprise cloud spend carry tighter precision than SME SaaS adoption and emerging technology pilots. Forecasts reflect assumptions about regulatory timeline adherence and infrastructure investment continuity. Algorithmic transparency requirements under proposed Artificial Intelligence and Data Act legislation and spectrum auction schedule delays represent specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
Labor Management System in Retail Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Global Data Virtualization Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Workflow Content Automation (WCA) Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Global Work Order Management Systems Market