
 Digital Manufacturing Market | 2026-2036
Digital Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Manufacturing Market Intelligence
The gap between premium integrated platforms and commodity point solutions is realigning competitive dynamics across factory floors. Siemens AG leverages its hardware-software convergence to dominate high-complexity deployments. Rockwell Automation competes through specialized industrial control architectures. Honeywell International anchors its position in process-intensive verticals with embedded analytics.
Digital manufacturing encompasses the integration of computer-based systems with production operations, encompassing cyber-physical infrastructure, real-time data orchestration, and automated decision loops operating at sub-millisecond latency for synchronized machine coordination. Its primary purpose is to replace sequential, paper-driven production workflows with continuously optimized, self-correcting operational environments. Software Solutions commands the dominant margin pool as recurring license and cloud-subscription models displace perpetual sales. IoT infrastructure is expanding fastest at the network edge where sensor density requirements are climbing. Control Systems remains structurally mature with replacement cycles extending beyond typical technology refresh timelines.
The EU AI Act and FDA's software-as-medical-device framework are tightening validation requirements for autonomous quality-control algorithms, forcing vendors to re-architect compliance documentation. OSHA's machine-guarding standards are intersecting with collaborative robotics deployments, creating dual-certification burdens for automotive and electronics end users. Stakeholders must evaluate whether their technology stacks can absorb escalating regulatory documentation loads without fragmenting engineering resources.
Market Dynamics
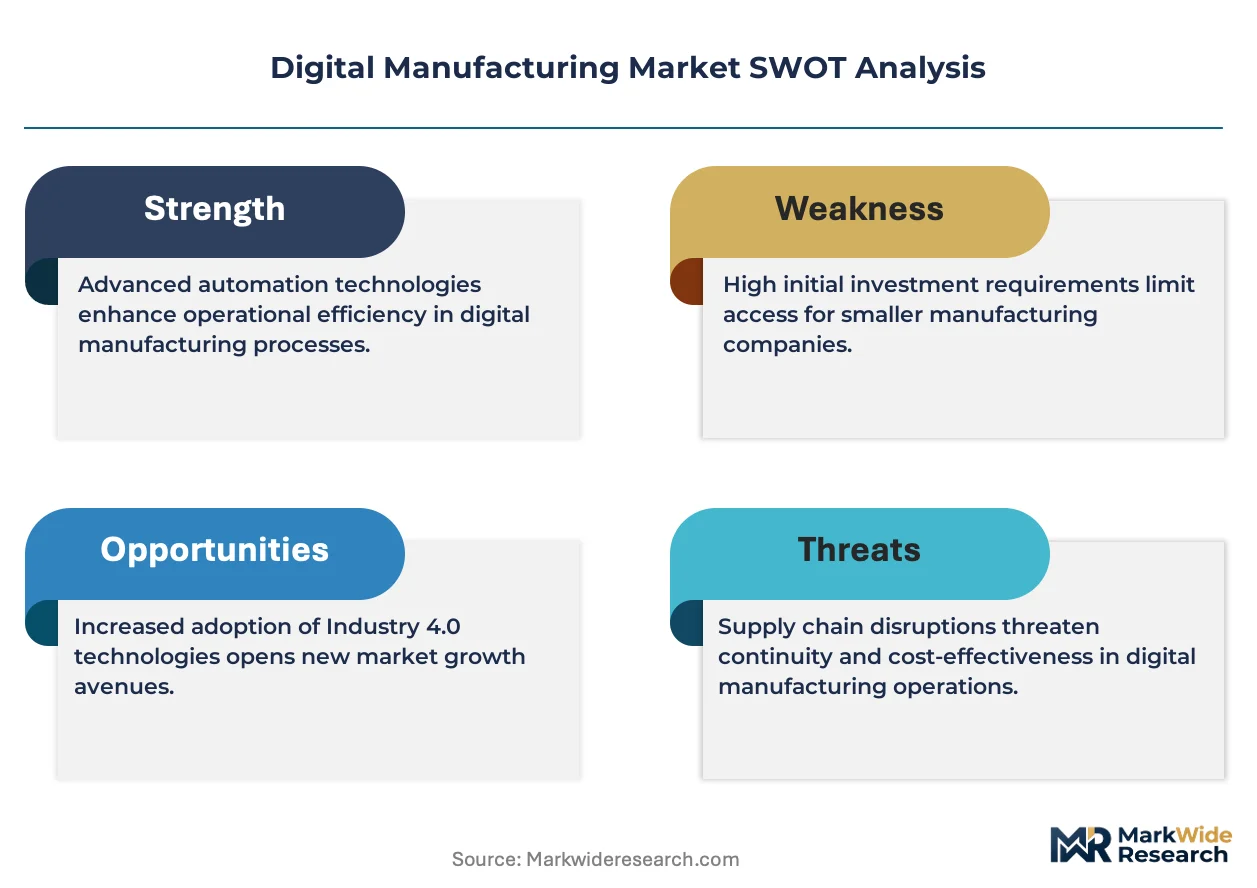
Convergence between operational technology and enterprise software stacks is compressing deployment timelines while fragmenting vendor ecosystems. The EU AI Act's risk-classification framework for autonomous systems is forcing re-architecture of quality-control algorithms before deployment.
Growth Catalysts
- Aerospace digital twin mandates:Engine manufacturers in Germany and France now require physics-based simulation for component certification, pulling demand for high-fidelity modeling platforms.
- EU AI Act compliance deadlines:High-risk autonomous production systems face mandatory conformity assessments, creating immediate upgrade cycles for legacy installations.
- Sub-millisecond latency requirements:Synchronized machine coordination in automotive assembly is driving edge compute infrastructure refresh across Stuttgart and Munich industrial corridors.
Market Restraints
- Semiconductor supply concentration:Industrial control system ASICs remain captive to Taiwan and South Korea foundry capacity, extending lead times beyond 40 weeks.
- Specialized talent scarcity:Cyber-physical systems engineering expertise concentrates in Germany's technical universities, creating recruitment bottlenecks for multinational deployments.
- Legacy protocol fragmentation:Proprietary fieldbus standards from the 1990s persist in installed bases, complicating interoperability with IP-based architectures.
Strategic Opportunities
- Process-intensive verticals:Chemical and pharmaceutical manufacturers in Ludwigshafen and Leverkusen seek embedded analytics for batch optimization, opening white space beyond discrete manufacturing.
- Cloud-native MES convergence:Manufacturing execution systems are migrating from on-premise servers to containerized deployments, enabling multi-site orchestration for mid-cap industrials.
- CSRD reporting mandates:The EU's Corporate Sustainability Reporting Directive requires granular production emissions data, creating demand for carbon-accounting modules integrated with shop-floor sensors.
Industry Challenges
- Dual-certification burdens:Collaborative robotics deployments in automotive assembly must satisfy both OSHA machine-guarding standards and CE marking requirements, extending validation timelines.
- Intergenerational system integration:Brownfield facilities operate paper-driven workflows alongside digital twins, forcing expensive middleware development for data harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Manufacturing Market |
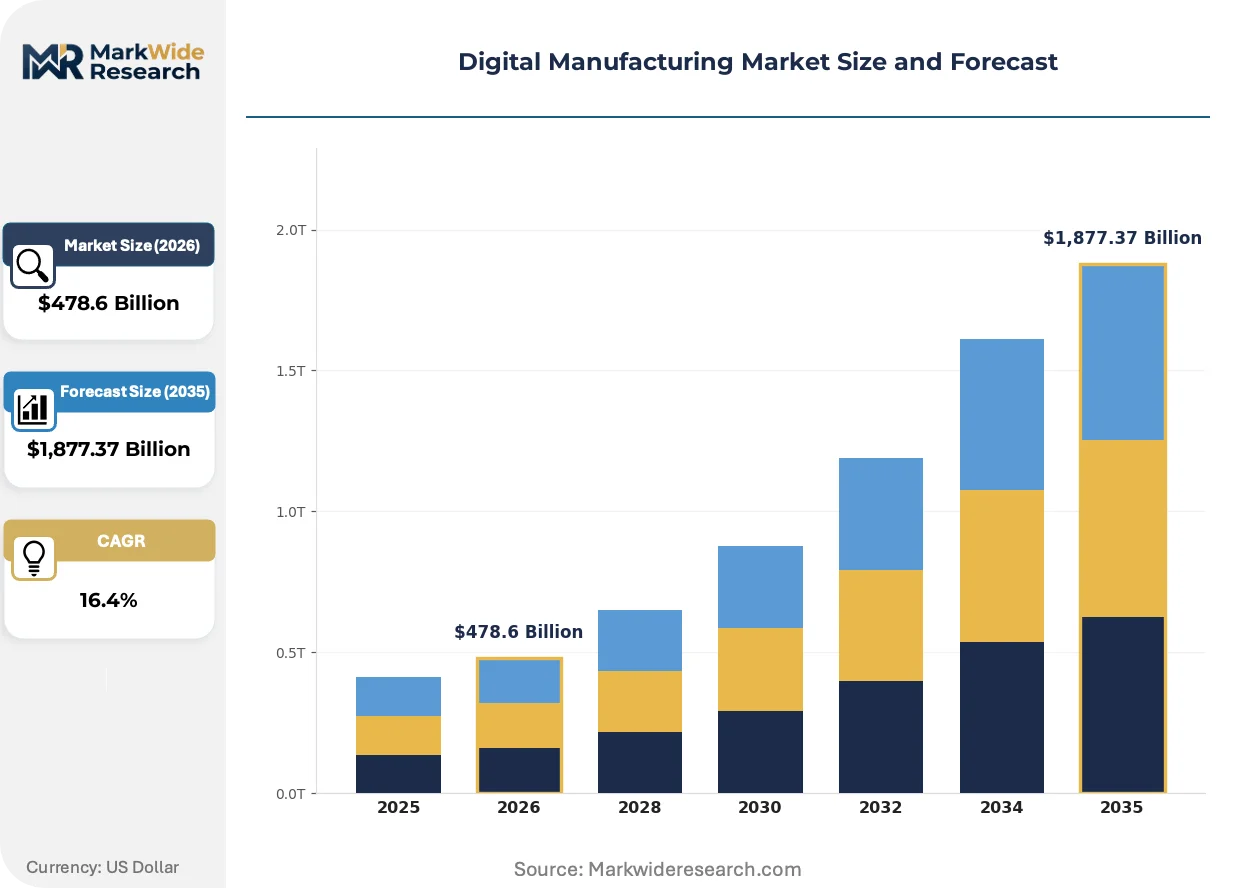
| Market Size in 2026 | $478.6 Billion |
| Market Size in 2035 | $1,877.37 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Robotics, 3D Printing Product Type: Automation Equipment, Software Solutions, Sensors, Control Systems End User: Aerospace, Automotive, Electronics, Pharmaceuticals Application: Supply Chain Optimization, Quality Control, Predictive Maintenance, Production Planning |
| Companies Covered | Siemens AG, Rockwell Automation, Honeywell International, Schneider Electric, ABB, IBM Corporation, Microsoft Corporation, SAP SE, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Manufacturing Market Strategic Shifts & Innovations
Real-time data orchestration is displacing batch-oriented manufacturing intelligence, while regulatory pressure on algorithmic transparency accelerates vendor consolidation around compliant platforms.
Digital thread architectures spanning design, production, and service are unifying previously siloed engineering workflows. Aerospace suppliers in Toulouse and Hamburg are deploying these across engine component lifecycles. The structural consequence is compressing iteration cycles from months to days while collapsing separate software licenses into integrated subscriptions.
The EU AI Act's risk-based classification for autonomous quality-control systems is tightening validation documentation requirements. High-risk applications now require technical files demonstrating human oversight capabilities. German automotive suppliers are responding by embedding explainability modules into inspection algorithms before the 2026 enforcement window.
Buyer procurement for manufacturing software is consolidating around outcome-based performance contracts rather than perpetual licenses. Mid-cap industrials in Bavaria now demand uptime guarantees and throughput improvements as contractual metrics. This shift is most visible among automotive tier-one suppliers renegotiating multi-year MES agreements.
Digital Manufacturing Market Segmentation
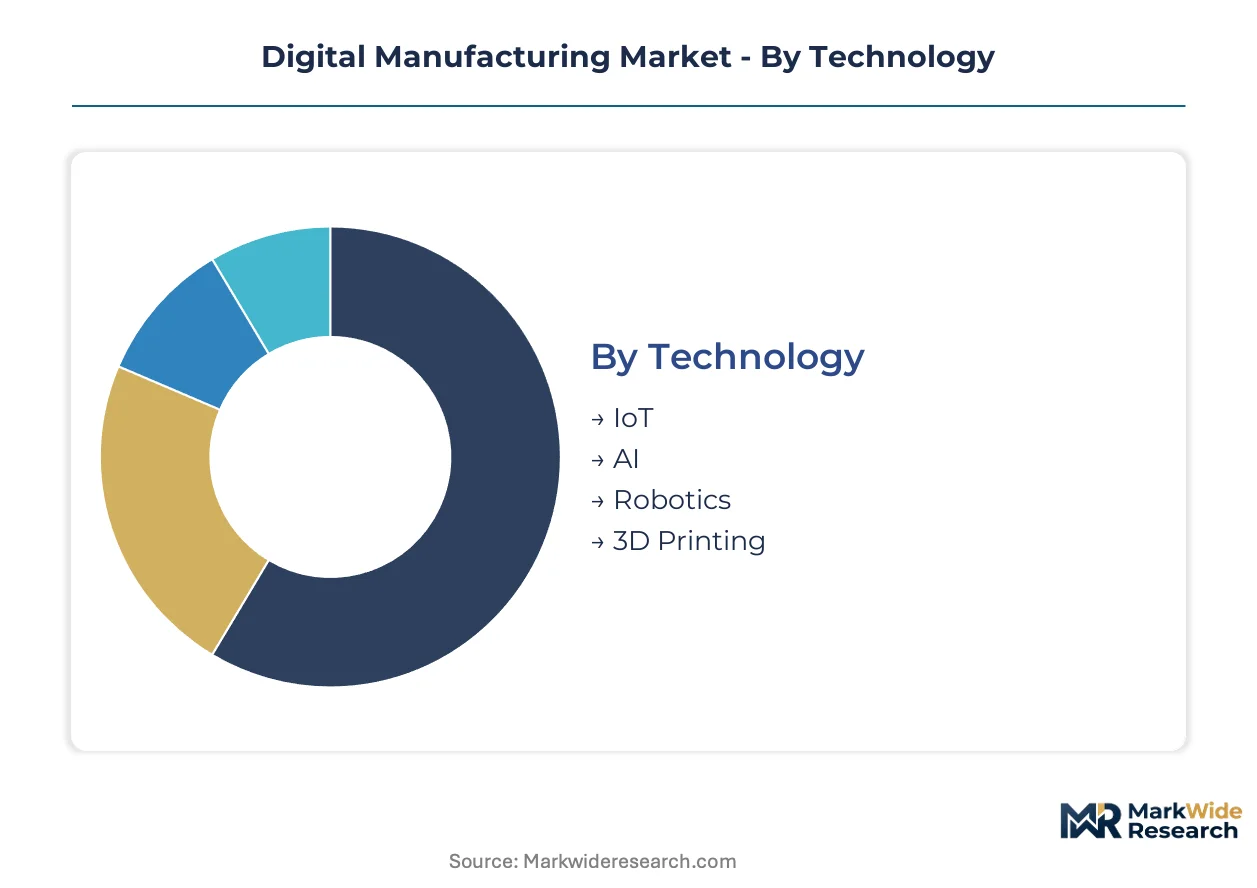
Segmentation reveals how digital manufacturing value pools concentrate across technology layers, with software recurring revenue diverging sharply from hardware replacement cycles. Understanding these fault lines exposes where margin accretion occurs versus where commodification pressures dominate.
Technology:
Customization intensity varies from plug-and-play sensor modules to bespoke AI model architectures requiring extensive retraining for each deployment environment.
- IoT:Network edge infrastructure combining industrial-grade sensors with low-latency connectivity protocols. Demand clusters around Stuttgart and Munich automotive corridors where sensor density requirements for synchronized machine coordination are climbing fastest.
- AI:Machine learning pipelines for quality inspection, demand forecasting, and autonomous process optimization. EU AI Act risk-classification mandates are forcing re-architecture of validation documentation before deployment in French and German aerospace supply chains.
- Robotics:Collaborative and autonomous systems for material handling, assembly, and inspection.
- 3D Printing:Additive manufacturing systems for prototyping and production-grade metal components.
Leading the category by volume: IoT. Expanding most quickly: AI.
Product Type:
Margin structures separate recurring cloud subscriptions from capital-intensive hardware with extended depreciation schedules.
- Automation Equipment:Robotic arms, conveyance systems, and programmable machinery executing physical production tasks. Automotive assembly lines in Bavaria drive replacement cycles as collaborative robotics deployments must satisfy dual-certification burdens under OSHA machine-guarding standards and CE marking requirements.
- Software Solutions:Manufacturing execution systems, digital twin platforms, and analytics suites operating on subscription models. Aerospace engine manufacturers in Germany and France now require physics-based simulation for component certification, pulling demand for high-fidelity modeling platforms.
- Sensors:Temperature, pressure, vibration, and vision systems capturing operational data.
- Control Systems:PLCs, SCADA, and distributed control architectures managing machine coordination.
Software Solutions commands dominant recurring revenue. Automation Equipment faces semiconductor supply concentration extending lead times beyond 40 weeks.
End User:
Regulatory stringency varies from FDA software-as-medical-device frameworks in pharmaceuticals to FAA certification requirements in aerospace.
- Aerospace:Airframe, engine, and component manufacturers deploying digital twins across design-to-service lifecycles. Toulouse and Hamburg suppliers are unifying siloed engineering workflows through digital thread architectures that compress iteration cycles from months to days.
- Automotive:OEM and tier-one suppliers synchronizing multi-site production through cloud-native MES. Mid-cap industrials in Bavaria now demand uptime guarantees and throughput improvements as contractual metrics in renegotiated agreements.
- Electronics:Semiconductor and consumer device manufacturers requiring sub-millisecond latency for precision assembly.
- Pharmaceuticals:Batch process manufacturers in Ludwigshafen and Leverkusen seeking embedded analytics for optimization.
Aerospace leads investment intensity per facility. Pharmaceuticals shows steepest regulatory-driven upgrade trajectory.
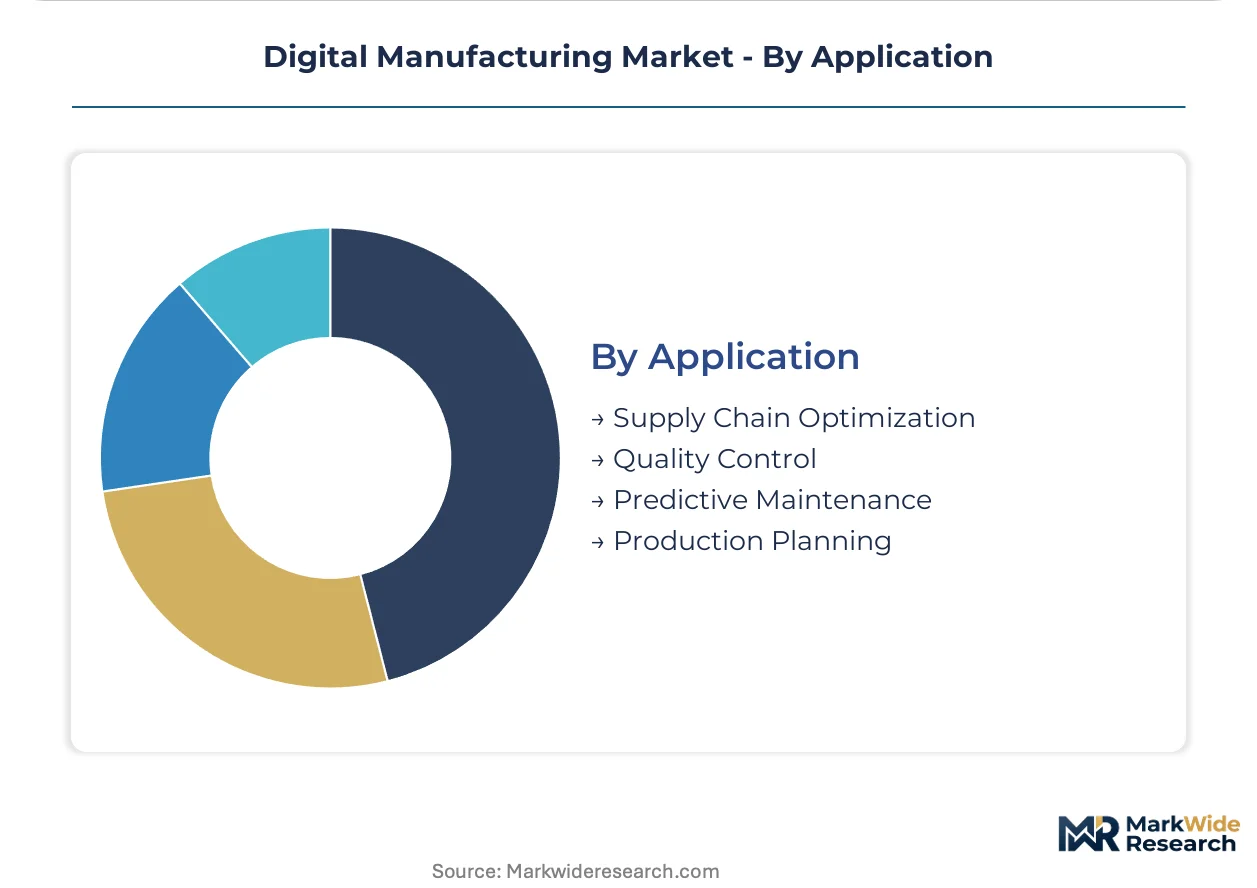
Application:
Value capture potential diverges between operational efficiency gains and compliance-mandated quality assurance systems.
- Supply Chain Optimization:Inventory positioning, logistics orchestration, and demand-responsive production scheduling. CSRD reporting mandates require granular production emissions data, creating demand for carbon-accounting modules integrated with shop-floor sensors.
- Quality Control:Automated inspection, defect detection, and conformance verification using computer vision. High-risk autonomous quality-control systems under EU AI Act now require technical files demonstrating human oversight capabilities.
- Predictive Maintenance:Condition monitoring and failure anticipation reducing unplanned downtime.
- Production Planning:Capacity allocation, sequencing, and resource optimization across multi-site operations.
Quality Control carries highest compliance documentation burden. Supply Chain Optimization is gaining share fastest as sustainability reporting requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Stuttgart anchor the most concentrated digital manufacturing demand corridor worldwide. German automotive suppliers in Bavaria are synchronizing multi-site production through cloud-native MES deployments. This industrial belt sets the benchmark for sub-millisecond latency requirements in synchronized machine coordination.
Germany
Physics-based simulation mandates from aerospace engine manufacturers in Munich and Hamburg pull demand for high-fidelity digital twin platforms. EU AI Act risk-classification deadlines force re-architecture of autonomous quality-control algorithms before 2026 enforcement. Stuttgart's automotive corridor concentrates sensor density requirements for edge compute infrastructure refresh.
France
Toulouse aerospace suppliers deploy digital thread architectures compressing iteration cycles from months to days. ANSM and CNIL oversight intersects with CE marking requirements for medical device manufacturers near Paris. The Île-de-France region anchors embedded analytics demand from pharmaceutical batch process operators.
United States
FDA's software-as-medical-device framework tightens validation requirements for autonomous quality-control systems in Boston and San Francisco medical technology clusters. OSHA machine-guarding standards create dual-certification burdens for collaborative robotics in Detroit automotive assembly. The Pacific Northwest concentrates cloud-native MES migration among mid-cap industrials.
China
MIIT industrial internet initiatives accelerate edge compute deployment in the Yangtze River Delta manufacturing belt. GB standards for cyber-physical systems intersect with dual carbon goals driving carbon-accounting module integration. Shenzhen electronics manufacturers demand sub-millisecond latency for precision semiconductor assembly.
Japan
METI's Society 5.0 roadmap funds digital twin adoption for precision machinery manufacturers in Nagoya's Chubu region. JIS standards for industrial automation create compliance documentation requirements for robotics deployments. Kansai's Osaka-Kobe corridor concentrates predictive maintenance solution demand from process-intensive chemical producers.
Digital Manufacturing Market Key Industry Players
Capital-heavy producers compete with asset-light designers across converged operational technology and enterprise software stacks. The vendor ecosystem fragments between premium integrated platforms commanding recurring subscription margins and commodity point solutions facing replacement cycle extension. Three archetypes dominate: hardware-software convergents anchoring high-complexity deployments, specialized industrial control architects, and embedded analytics providers targeting process-intensive verticals. Competitive moves concentrate on strategic partnerships compressing deployment timelines and portfolio diversification absorbing escalating regulatory documentation loads.
Within the hardware-software convergent tier, Siemens AG exemplifies the integrated platform archetype through its Munich-based industrial software and automation convergence. Rockwell Automation occupies a position among specialized control architecture providers competing through industrial internet expertise. Honeywell International anchors the embedded analytics specialist segment with process automation heritage. These three represent distinct competitive vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation |
| Honeywell International |
| Schneider Electric |
| ABB |
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
Industrial control system ASICs from Taiwan and South Korea foundries cascade through three pricing tiers before reaching automotive and aerospace end users in Germany and France. Foundry capacity constraints at the wafer level transmit cost pressure downstream, where premium integrated platforms command subscription multiples over commodity point solutions.
Pricing Analysis
Outcome-based performance contracts now anchor pricing for manufacturing execution systems, with mid-cap industrials in Bavaria demanding uptime guarantees and throughput improvements as contractual metrics. Price differentiation separates CE-marked autonomous quality-control systems requiring EU AI Act technical files from uncertified alternatives. Cost compression in the commodity sensor tier intensifies because of Chinese module oversupply. Small-scale pharmaceutical batch operators in Ludwigshafen exhibit highest price sensitivity, while aerospace engine manufacturers in Hamburg accept premium positioning for physics-based simulation platforms.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundries for industrial control system ASICs, where capacity allocation prioritizes consumer electronics over automotive and industrial orders. The supply chain draws from German precision machining for motion control hardware, Japanese servo motors, and Chinese sensor modules. Tariff exposure on semiconductor components compounds lead time uncertainty for European system integrators. Distribution runs through authorized distributor networks serving discrete manufacturing verticals, with direct OEM relationships dominating high-complexity deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity concentration props pricing power for vendors with secured wafer allocations, creating a supply-constrained market structure through the analysis window.
For Market Incumbents: Deploy hardware-software convergence as the primary defensive lever. Siemens AG exemplifies this through Munich-based industrial software and automation integration that locks in high-complexity deployments. Incumbents should anchor recurring subscription revenue by embedding EU AI Act compliance documentation into platform architectures before the enforcement window. Capacity addition in German industrial corridors around Stuttgart and Munich reinforces regional service density against emerging cloud-native entrants. For New Entrants and Emerging Players: Capture white space in process-intensive verticals beyond discrete manufacturing. Chemical and pharmaceutical batch optimization in Ludwigshafen and Leverkusen remains underpenetrated by embedded analytics specialists. Cloud-native MES migration among mid-cap industrials offers the most penetrable entry point. A go-to-market angle emphasizing containerized deployment speed without legacy protocol baggage resonates with Bavarian automotive tier-one suppliers renegotiating multi-year agreements. For Investors and Strategic Acquirers: EU AI Act conformity assessment deadlines for high-risk autonomous systems are the leading indicator that compliance-enabled platforms will command valuation premiums over point solutions. The five-to-ten-year viability window favors asset-light designers with recurring revenue models over capital-heavy producers exposed to semiconductor cycle volatility. Acquisition targets should display vertical-specific AI model architectures with embedded explainability modules. The signal to watch is aerospace supplier consolidation around digital thread architectures unifying design-to-service lifecycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies siloed engineering workflows for Toulouse and Hamburg aerospace suppliers under single subscription models. |
| Regulatory Compliance Investment | Builds EU AI Act technical documentation capabilities before mandatory conformity assessments for autonomous quality-control systems. |
| Edge Compute Infrastructure Refresh | Addresses sub-millisecond latency requirements for synchronized machine coordination across Stuttgart automotive corridors. |
| Carbon-Accounting Module Development | Integrates shop-floor sensor data to satisfy CSRD reporting mandates for granular production emissions tracking. |
| Strategic Partnership | Compresses deployment timelines by combining industrial control heritage with cloud-native software architectures. |
Research Approach
Independent corroboration across plant engineers at Bavarian automotive suppliers, procurement leads at French aerospace tier-ones, and regulatory affairs directors navigating EU AI Act implementation underwrites the qualitative findings in this study. Primary interviews with digital twin platform architects, OT-IT convergence specialists, and embedded analytics product managers combined with secondary validation from SEC filings of listed automation vendors, ECHA regulatory guidance documents, and EU official journal AI Act implementing acts. Bottom-up sensor shipment analysis and top-down industrial software revenue aggregation provided triangulation across the market size estimation.
Comparable historical periods spanning technology refresh cycles in manufacturing execution systems anchored the projection framework across the analysis window. The analytical approach modeled segmentation dimensions including deployment model (on-premise versus cloud-native), integration complexity (greenfield versus brownfield), vertical regulatory stringency (aerospace FDA versus automotive OSHA), and geographic adoption pattern (German industrial corridor concentration versus dispersed multi-site operations). CAGRs derived from installed base replacement timelines and regulatory-driven upgrade mandates incorporated semiconductor lead time volatility and specialized talent scarcity in cyber-physical systems engineering.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry capacity allocation shifts, EU AI Act enforcement stringency variations, and collaborative robotics dual-certification timeline extensions. The forecasts reflect documented assumptions regarding regulatory deadline adherence and supply chain normalization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Global Web Push Notification Software Market
Digital Solutions
Global Content Moderation Solutions Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Legaltech Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Web Content Management Market