
 Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market | 2026-2036
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market Size, Share, and Industry Trends Forecast 2026-2036
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market Analytics
North American enterprise software vendors is recalibrating capacity for cloud-native PLM architectures to serve CPG and retail workloads. Siemens leverages deep manufacturing integration to anchor aerospace-grade traceability tools into consumer supply chains. Dassault Systèmes sustains dominance in 3D design simulation through its ENOVIA platform, extending digital-twin concepts from industrial into fast-moving consumer goods development cycles. Centric Software specializes in formula-based product management for food and beverage clients, occupying a narrow but defensible position against broader ERP-integrated rivals.
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) denotes a software-enabled discipline governing ideation, formulation, specification, compliance documentation, and retirement of packaged goods from concept through commercialization. Core functional parameters include bill-of-materials accuracy to ingredient-level granularity, revision control for packaging artwork, and workflow orchestration across distributed supplier networks. Cloud-Based Solutions lead technology adoption as retailers prioritize elastic compute for seasonal SKU surges, while AI-Powered Tools represent the fastest-expanding capability segment by automating demand sensing and formulation optimization. Food & Beverage applications command the largest share of implementation spend due to allergen traceability mandates and recipe complexity, though Personal Care shows the steepest growth trajectory as clean-label and sustainability claims proliferate.
FDA Food Safety Modernization Act traceability rules, EU Green Deal packaging sustainability directives, and China's GB standards for prepackaged food labeling collectively elevate compliance automation from optional efficiency to market-access prerequisite. Retailers selling across these jurisdictions now embed regulatory validation gates directly into PLM workflow stages rather than treating compliance as a post-development checkpoint. Stakeholders must evaluate whether their current platforms can natively support multi-jurisdiction formula lockdowns and automated label generation without manual intervention across distributed R&D teams.
Market Dynamics
SKU proliferation across omnichannel retail networks is compressing product development cycles, forcing PLM vendors to embed real-time supplier collaboration tools directly into core workflows rather than offering them as modular add-ons.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal packaging sustainability directives are accelerating PLM investment as brands automate compliance documentation for recyclable material specifications and carbon footprint tracking across European markets.
- Cloud-native architectures:Elastic compute infrastructure enables retailers to scale PLM capacity during seasonal design surges without capital-heavy on-premise expansion, particularly for fast-fashion and holiday-centric CPG categories.
- Food & Beverage allergen traceability:FDA Food Safety Modernization Act traceability rules are embedding ingredient-level tracking into PLM systems as a non-negotiable market-access requirement for US-bound food manufacturers.
Market Restraints
- Legacy system integration costs:ERP-to-PLM data migration requires substantial professional services expenditure, with mid-market retailers facing 18-24 month implementation timelines that delay ROI realization.
- Cloud data sovereignty constraints:China's GB standards for prepackaged food labeling and data localization requirements create architectural complexity for multinational PLM deployments spanning mainland China operations.
- Specialized talent scarcity:Formula-based product management expertise combining regulatory knowledge with PLM configuration skills concentrates in established software hubs, inflating implementation partner rates.
Strategic Opportunities
- Personal Care clean-label expansion:Sustainability claims and ingredient transparency demands in cosmetics and skincare are driving PLM adoption in a historically underpenetrated vertical with complex formulation workflows.
- AI-powered demand sensing convergence:Machine learning forecasting tools integrated with PLM specification management enable automated recipe scaling based on regional demand signals, compressing reformulation cycles.
- India's FSSAI digitization:India's Food Safety and Standards Authority is mandating electronic compliance documentation for packaged goods, creating regulatory tailwinds for PLM penetration in a market with fragmented supplier networks.
Industry Challenges
- Packaging artwork revision control:Multi-language label variants and region-specific regulatory claims create version management complexity, with errors triggering costly product recalls or customs delays.
- Supplier network onboarding friction:Tier-2 and tier-3 packaging material suppliers in developing manufacturing clusters lack digital maturity, requiring manual data entry that undermines PLM automation benefits.
- Cross-functional workflow alignment:R&D, procurement, and regulatory teams operate with conflicting KPIs and approval hierarchies, generating specification change-order backlogs that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market |
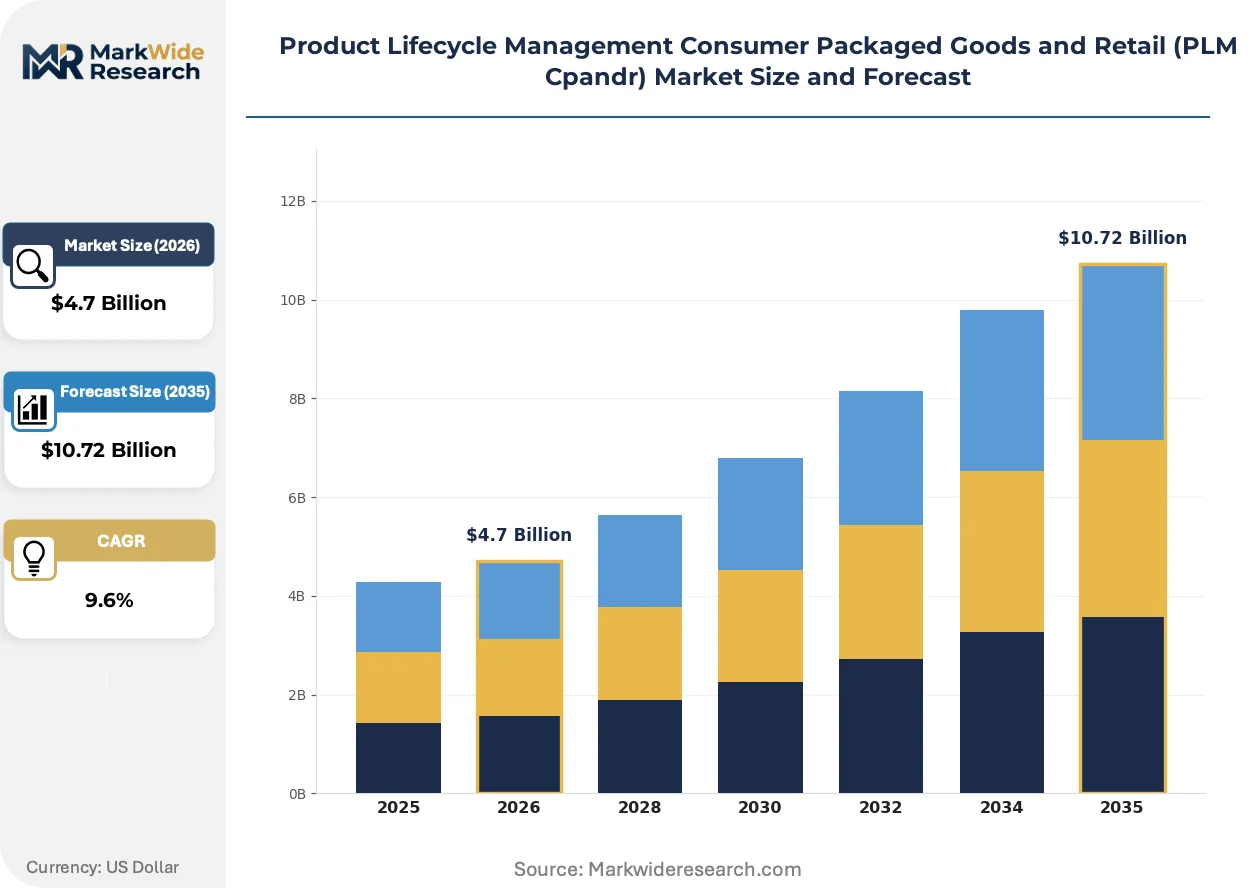
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.72 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Care, Food & Beverage, Household Products, Apparel Customer Type: B2B, Distributors, Online Retailers, Supermarkets Technology: Cloud-Based Solutions, On-Premises Software, Mobile Applications, AI-Powered Tools Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Siemens, Dassault Systèmes, PTC, SAP, Oracle, Autodesk, Aras, Centric Software, Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market Evolving Landscape
Generative AI and digital-twin simulation are converging with regulatory automation to reshape how consumer brands manage product specification, compliance validation, and supplier qualification workflows.
Digital-twin technology is unifying physical and virtual product development environments for packaging and formulation testing. Apparel and cosmetics brands are adopting 3D simulation tools at accelerating rates to reduce physical sample iterations. This convergence is unifying design, compliance, and sourcing decisions into single-threaded workflows that compress concept-to-shelf timelines.
REACH chemical substance restrictions and the EU AI Act are mandating algorithmic transparency for automated formulation recommendations. Industrial software vendors must now document training data provenance and decision audit trails for AI-powered PLM modules. Food and personal care segments operating in European markets are responding by embedding compliance validation gates earlier in development cycles.
Retailer consolidation is concentrating buying power among omnichannel platforms that demand standardized product data exchange formats. Mid-sized CPG brands are migrating from proprietary PLM instances to multi-tenant cloud architectures to meet trading partner interoperability requirements. This procurement model evolution is most visible in Germany and the United States, where Walmart and Amazon marketplace integration mandates are driving vendor platform standardization.
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market Segmentation
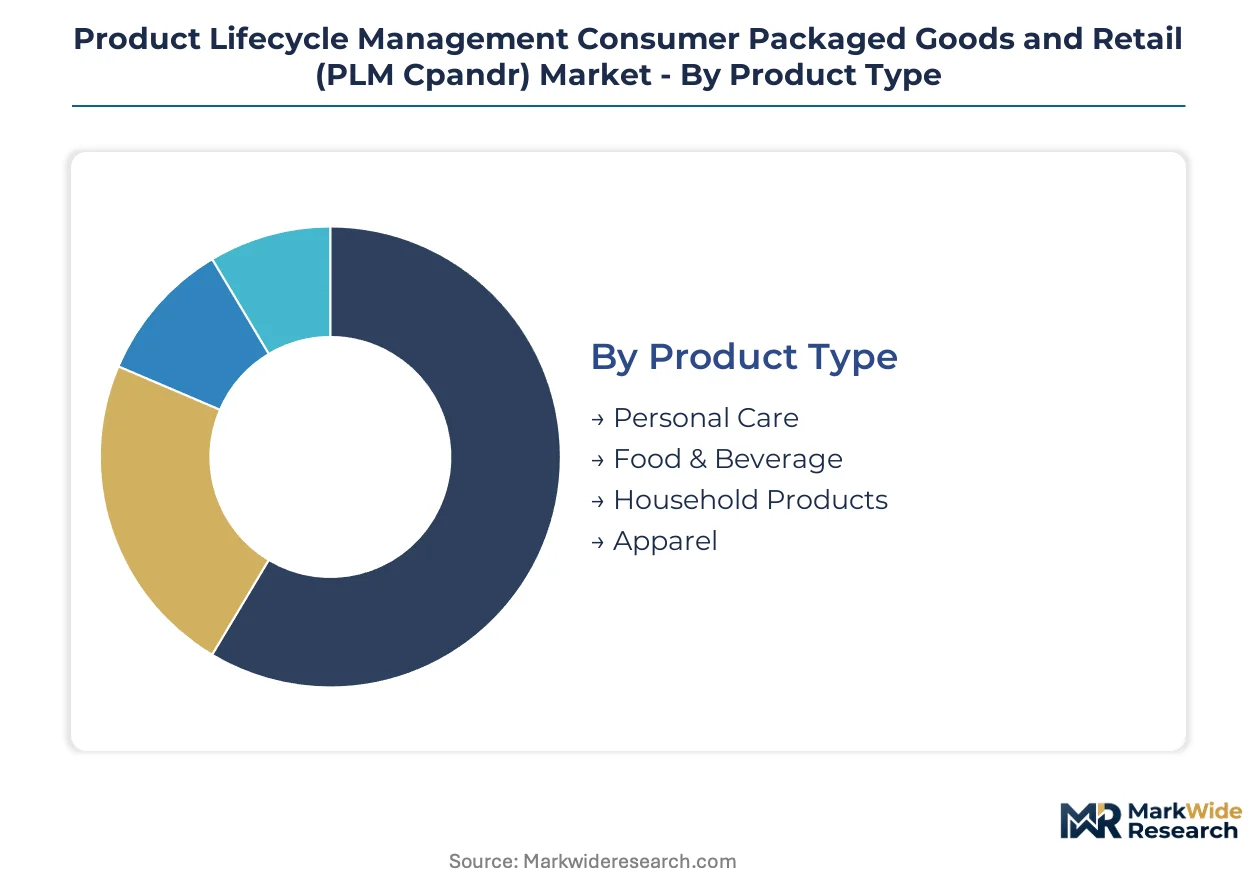
PLM Cpandr segmentation reveals how software deployment models and customer procurement patterns create distinct capability requirements across consumer goods verticals. Understanding these divides enables vendors to align R&D investment with where specification complexity and compliance automation demands concentrate most intensely.
Product Type:
Standalone PLM deployments dominate Food & Beverage and Personal Care where formula confidentiality and regulatory traceability mandate dedicated systems, while Apparel and Household Products more commonly embed PLM within broader ERP suites.
- Food & Beverage:Formula-based product management with ingredient-level granularity and allergen tracking sits at the core of PLM value propositions here. Demand concentrates in the United States and Germany where FDA Food Safety Modernization Act and EU Green Deal traceability rules enforce automated compliance documentation across distributed supplier networks.
- Personal Care:Clean-label ingredient transparency and sustainability claims drive specification complexity for cosmetics and skincare formulations. Growth is accelerating fastest in this vertical as brands reformulate to meet REACH chemical restrictions and EU AI Act algorithmic transparency mandates for automated recommendation engines.
- Household Products:Surface cleaners and home care items utilize PLM primarily for packaging artwork revision control and regional label variant management.
- Apparel:Fast-fashion brands leverage PLM to compress design-to-shelf timelines through 3D sample simulation and digital-twin workflows.
Volume placements concentrate in Food & Beverage; the faster expansion belongs to Personal Care.
Customer Type:
Procurement sophistication varies sharply across buyer categories, with B2B manufacturers demanding deep supplier network integration while retail channels prioritize standardized data exchange formats for marketplace compliance.
- B2B:Industrial ingredient suppliers and contract manufacturers require PLM systems with tier-2 and tier-3 supplier onboarding capabilities. These buyers dominate implementation spend in China where GB standards for prepackaged food labeling create complex multi-jurisdiction workflow requirements.
- Supermarkets:Omnichannel grocery chains are mandating standardized product data exchange formats from CPG partners. Walmart and Amazon integration requirements in the United States are pushing mid-sized brands toward multi-tenant cloud architectures.
- Online Retailers:Marketplace platforms prioritize real-time inventory synchronization and automated listing generation from PLM master data.
- Distributors:Wholesale intermediaries utilize lighter PLM implementations focused on regulatory documentation handoff rather than upstream formulation management.
Implementation scale peaks with B2B manufacturers; adoption velocity is climbing fastest among supermarkets.
Technology:
Deployment architecture decisions determine scalability economics, with cloud-native platforms enabling seasonal capacity surges while on-premises installations persist where data sovereignty constraints apply.
- Cloud-Based Solutions:Elastic compute infrastructure supports SKU proliferation surges without capital-heavy expansion. Retailers in Germany and the United States prioritize these architectures for fast-fashion and holiday-centric category management.
- AI-Powered Tools:Machine learning modules automate demand sensing and formulation optimization, compressing reformulation cycles. These capabilities are expanding most quickly as REACH and EU AI Act requirements mandate algorithmic transparency documentation.
- On-Premises Software:Data localization requirements in China sustain demand for mainland-hosted installations despite higher total cost of ownership.
- Mobile Applications:Field-based quality assurance and supplier audit workflows drive adoption of tablet-native PLM interfaces.
Deployment volume favors Cloud-Based Solutions; capability investment is shifting most aggressively toward AI-Powered Tools.
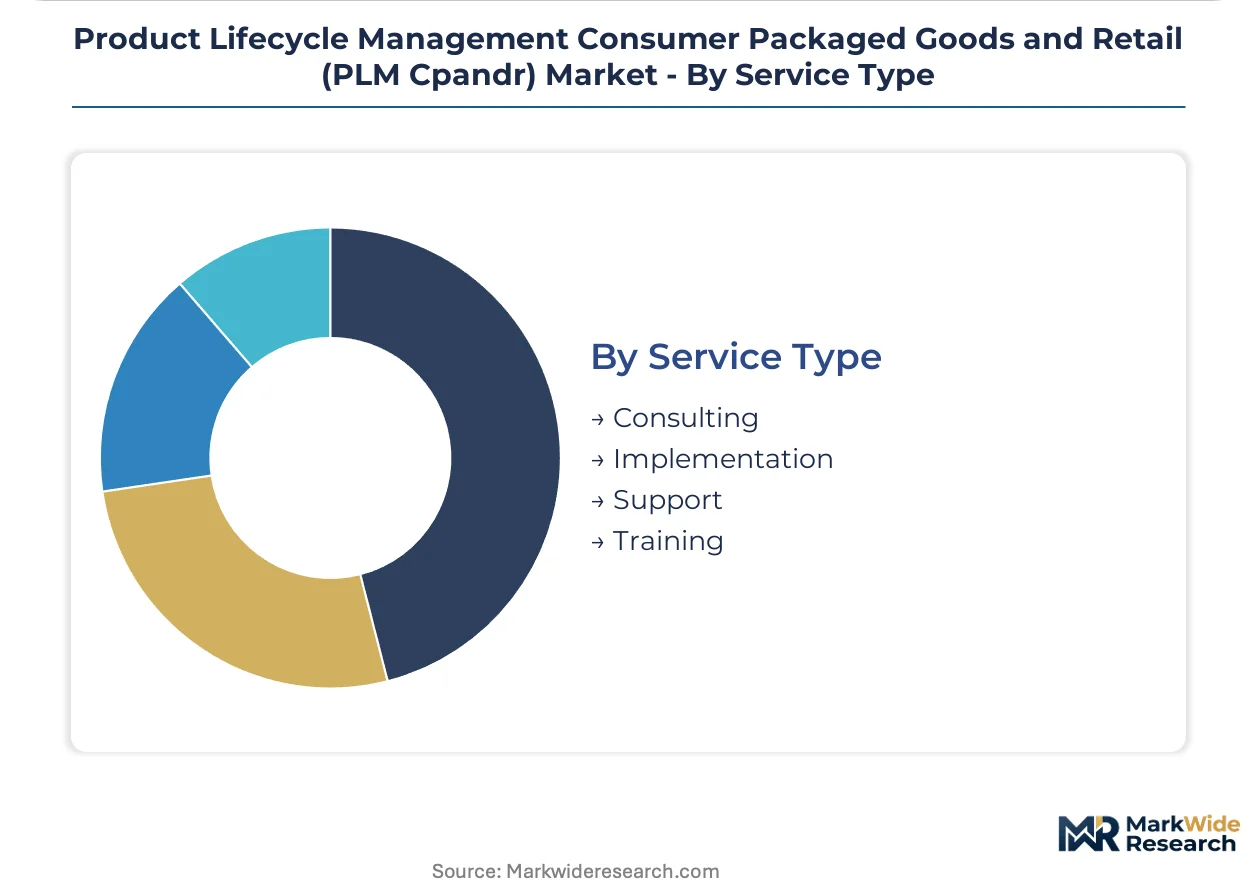
Service Type:
Professional services intensity correlates with legacy system complexity, where ERP-to-PLM data migration and regulatory workflow configuration dominate implementation economics.
- Implementation:System integration and data migration services account for the largest services spend as mid-market retailers face 18-24 month deployment timelines. Demand concentrates in the United States where fragmented legacy ERP estates require substantial professional services expenditure.
- Consulting:Regulatory workflow design and multi-jurisdiction compliance automation strategy command premium rates. Food & Beverage clients in Germany leverage these services to navigate EU Green Deal packaging sustainability directives.
- Support:Ongoing technical maintenance and release management sustain recurring revenue streams.
- Training:Formula-based product management expertise development addresses specialized talent scarcity in established software hubs.
Services revenue concentrates in Implementation; Consulting is gaining share fastest as regulatory complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development clusters in California, Bavaria, and Shanghai anchor PLM Cpandr innovation pipelines. Regulatory complexity across FDA, ECHA, and SAMR jurisdictions shapes where vendors prioritize cloud infrastructure investment.
United States
Fast-fashion brands and omnichannel retailers drive elastic cloud demand for seasonal SKU surges. FDA Food Safety Modernization Act traceability rules embed ingredient-level tracking as a market-access requirement. Silicon Valley and Boston software corridors host the dominant PLM architecture development centers.
Germany
Automotive-grade manufacturing discipline migrates into consumer supply chains through industrial software heritage. EU Green Deal packaging sustainability directives and REACH chemical restrictions mandate automated compliance documentation. Bavaria's industrial software ecosystem anchors aerospace-to-consumer PLM capability transfer.
China
GB standards for prepackaged food labeling and data localization requirements sustain demand for mainland-hosted installations. Tier-2 supplier network digitization lags in interior manufacturing clusters, creating implementation friction. Shanghai and Shenzhen house the primary cloud infrastructure development for Asia-Pacific retail workloads.
India
FSSAI digitization mandates for packaged goods create regulatory tailwinds in a market with fragmented supplier networks. Mid-market apparel brands accelerate PLM adoption to compress design-to-shelf timelines. Mumbai and Bangalore concentrate implementation partner expertise for formula-based product management.
United Kingdom
Post-Brexit regulatory divergence from EU standards forces dual-track compliance automation in PLM workflows. Clean-label cosmetics and personal care brands drive specification complexity for sustainability claims. London's enterprise software procurement hub influences vendor platform standardization across Commonwealth markets.
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and regulatory workflow depth. The vendor base stratifies into three tiers: diversified industrial software conglomerates, pure-play PLM specialists, and ERP-integrated platform providers. Siemens, Dassault Systèmes, and PTC anchor the industrial heritage tier. Autodesk and Aras occupy the cloud-native disruption tier. SAP and Oracle represent the ERP-embedded expansion tier. Competitive moves concentrate on M&A for AI capabilities and strategic partnerships for vertical-specific regulatory templates.
Among industrial-heritage conglomerates, Siemens leverages deep manufacturing integration to anchor traceability tools into consumer supply chains. Dassault Systèmes sustains dominance in 3D design simulation through its ENOVIA platform, extending digital-twin concepts into fast-moving consumer goods development cycles. Centric Software exemplifies the pure-play specialist archetype, occupying a narrow but defensible position in formula-based product management against broader ERP-integrated rivals.
| Leading Market Players |
|---|
| Siemens |
| Dassault Systèmes |
| PTC |
| SAP |
| Oracle |
| Autodesk |
| Aras |
| Centric Software |
| Infor |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging sustainability directives gate qualified supplier networks and premium-tier pricing access for PLM vendors serving European CPG brands. Compliance-certified implementation partners command 15-30% service premiums over uncertified rivals, while brands lacking automated carbon footprint documentation face procurement exclusion from major retail channels.
Pricing Analysis
Warranty and implementation support bundling separates enterprise-grade PLM subscriptions from entry-level SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with premium tiers incorporating dedicated regulatory template libraries and 24/7 compliance hotlines. Pricing pressure stems from cloud-native entrants unbundling professional services, compressing margins for traditional on-premise migration specialists. Mid-market retailers exhibit highest price sensitivity due to constrained IT budgets, while multinational CPGs prioritize total cost of ownership over upfront licensing.
Supply Chain Analysis
Direct-to-enterprise sales channels handle hyperscale buyer demand from Walmart and Amazon marketplace integrators, while value-added resellers serve mid-market apparel and personal care brands. Cloud infrastructure concentrates in the United States, Germany, and China, with regulatory data localization requirements sustaining mainland-hosted installations. AI/ML compute hardware and specialized regulatory content libraries constitute critical input dependencies. Single-source vulnerability in tier-2 supplier onboarding expertise creates implementation bottlenecks for Food & Beverage clients. Distribution runs through certified implementation partners with vertical-specific compliance credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over regulatory content libraries and AI training data emerges as the decisive upstream lever. Players securing exclusive partnerships with standards bodies and inspection agencies lock in differentiation that software features alone cannot replicate.
For Market Incumbents: To counter cloud-native entrants unbundling implementation services, Siemens and Dassault Systèmes should deepen backward integration into regulatory content generation, acquiring specialized compliance database providers. Incumbents must also secure exclusive data partnerships with FDA and ECHA to create switching costs that neutralize price competition from lightweight SaaS alternatives. For New Entrants and Emerging Players: The mid-market pricing gap between premium enterprise suites and basic cloud tools offers entry opportunity for AI-native PLM vendors targeting Personal Care clean-label workflows. India's fragmented supplier networks and FSSAI digitization mandates present the most penetrable geography for formula-management specialists. Go-to-market should prioritize channel partnerships with existing ERP resellers rather than direct enterprise sales. For Investors and Strategic Acquirers: Consolidation among tier-2 implementation partners is the leading indicator that margin compression is accelerating in professional services. Long-term viability favors vendors combining cloud-native architecture with captive regulatory content libraries. Acquisition targets should exhibit vertical-specific workflow depth in Food & Beverage or Personal Care rather than horizontal platform breadth.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Content Library Acquisition | Captive access to FDA and ECHA documentation templates locks in enterprise switching costs. |
| AI-Powered Formulation Module Launch | REACH compliance automation addresses EU AI Act transparency mandates for Personal Care clients. |
| Cloud-Native Architecture Migration | Elastic compute infrastructure captures seasonal SKU surge demand from fast-fashion retailers. |
| India Market Expansion Partnership | FSSAI digitization mandates create regulatory tailwinds in fragmented supplier networks. |
| Multi-Tenant Platform Standardization | Interoperability compliance with Walmart and Amazon procurement requirements secures mid-market share. |
Research Methodology
Multi-period observation of PLM deployment timelines, cloud migration patterns, and regulatory compliance automation rates anchored the trend analysis, supplemented by interviews with software product managers, implementation consultants, regulatory affairs directors at CPG brands, and category buyers at omnichannel retailers. Secondary validation drew from SEC 10-K filings, FDA FSMA guidance documents, EU Green Deal regulatory impact assessments, and hyperscaler cloud infrastructure expenditure disclosures. Bottom-up vendor revenue aggregation and top-down market sizing triangulated volume estimates.
Input-output matrices mapped deployment model adoption curves against customer segmentation dimensions including organization size, vertical industry, geographic regulatory cluster, and integration complexity tier. CAGRs were derived from regression analysis of historical implementation spend patterns extrapolated across the projection horizon. Industry-specific forecast inputs incorporated SKU proliferation indices and regulatory mandate implementation calendars without year-specific anchoring.
Inputs from vendor financial disclosures and regulatory agency guidance documents were available through the study window; gaps in private mid-market retailer spending data introduce uncertainty bands around adoption velocity estimates. Forecasts reflect base-case assumptions regarding cloud infrastructure cost curves and regulatory enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Revops Platform Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Cloud E-Signature Tools Market